
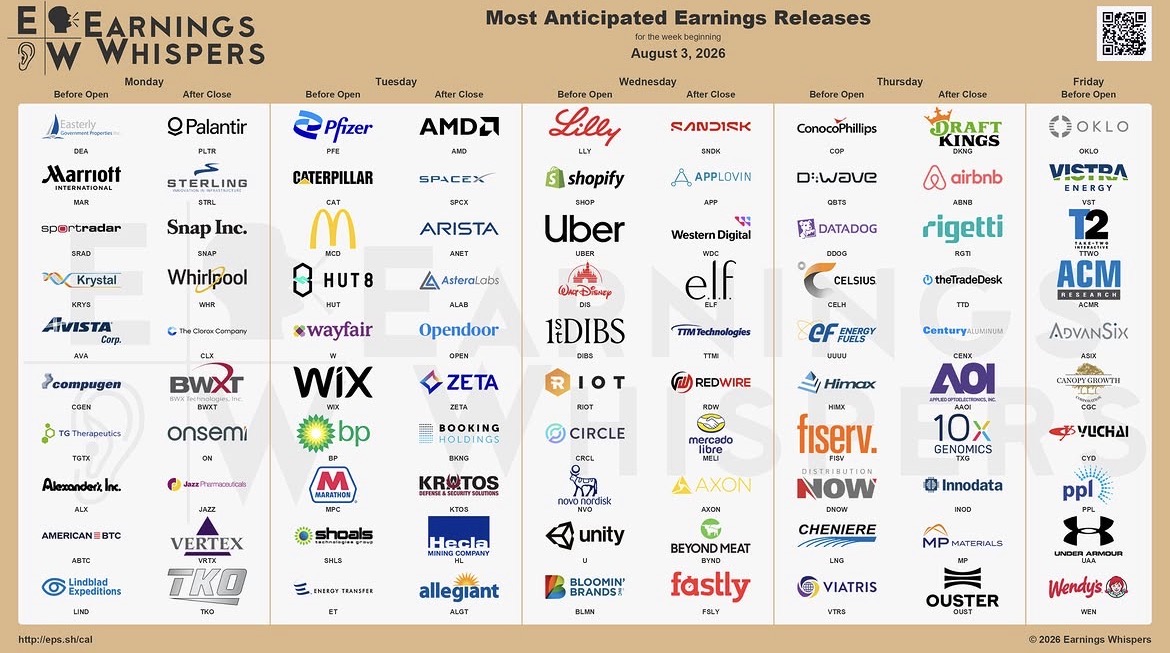
$MAR (+0,87%)
$KRYS (+1,42%)
$PLTR (+4,99%)
$STRL (+0,05%)
$SNAP (+2,93%)
$WHR (-5,64%)
$CLX (-2,07%)
$BWXT (-0,37%)
$ON (+0,84%)
$VRTX (+1,17%)
$PFIZER
$CAT (-0,57%)
$MCD (+0,58%)
$HUT (+0,95%)
$WIX (+0,15%)
$W (+5,78%)
$BP. (-0,69%)
$SHLS
$AMD (+2,16%)
$SPCX (+1,07%)
$ANET (+3,63%)
$ALAB (+0,39%)
$OPEN (-1,98%)
$ZETA (+1,94%)
$BKNG (-0,26%)
$KTOS (-2,41%)
$HL (-0,7%)
$LLY (-0,3%)
$SHOP (+1,47%)
$UBER (+0,45%)
$DIS (-0,43%)
$RIOT (+1,55%)
$CIRC
$NOVO B (-0,41%)
$U (-0,09%)
$SNDK (+6,06%)
$APP (+1,14%)
$WDC (+5,28%)
$ELF (+1,47%)
$MELI (+0,31%)
$AXON (-1,51%)
$TTMI (+4,72%)
$RDW (+0,26%)
$QBTS (-0,21%)
$DDOG (+6,6%)
$CLA (+0%)
$FI (+0,83%)
$LNG (-0,64%)
$UUUU (-3,08%)
$HIMX (+2,88%)
$ABNB (+1,28%)
$RGTI (-0,41%)
$TTD (-0,37%)
$AAOI (+2,11%)
$TXG (-0,02%)
$INOD (+2,23%)
$OUST
$MP (-1,96%)
$OKLO
$VST (-1,83%)
$TTWO (+0,25%)
$ACMR (+6,35%)
$WEED (-1,02%)
$UAA (+0,53%)
TTM Technologies
Price
Discussão sobre TTMI
Postos
4Let's move on to the next round!


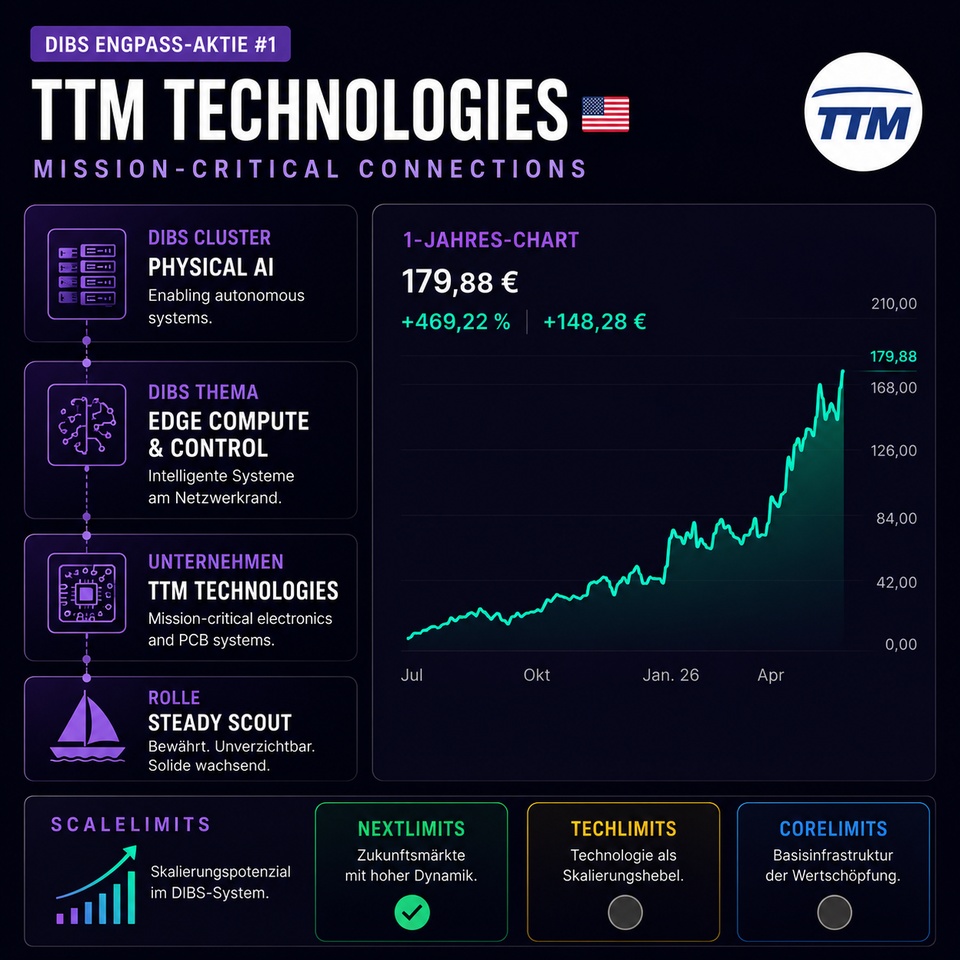
DIBS Bottleneck Stock #1: TTM Technologies 🇺🇸
Starting today, I’ll be regularly featuring companies from my investment universe that I find particularly interesting. All of the stocks mentioned are in my portfolio. Many of them are also part of my three wikifolios —NextLimits, TechLimits, and CoreLimits—in the ScaleLimits system (see the checkmarks in the chart). Of course, this applies only as of the time of publication of this post. Things can change.
I’m less concerned with short-term price targets or quarterly earnings. I’m primarily interested in which technological bottleneck a company is addressing and why I’ve added it to my portfolio. The overarching structure of my approach is illustrated by the DIBS Board (Dynamic Infrastructure Bottleneck Stack), which I regularly publish on getquin.
We’ll start today with TTM Technologies $TTMI (+4,72%). When people talk about AI infrastructure, the focus is usually on chips, GPUs, and data centers. Less often discussed is how these components are actually connected to one another.
This is where TTM Technologies comes in. The company develops and manufactures highly complex printed circuit board and interconnect systems for data centers, networking, aerospace, defense, and industrial applications.
A processor alone doesn’t provide any value. It’s only through printed circuit boards, backplanes, and interconnects that chips become servers, servers become systems, and systems become AI applications.
In the DIBS system, TTM is part of the Physical AI and the “Bottleneck” topic Edge Compute & Control . Role: Steady Scout ⛵
TTM does not build AI models and is rarely in the public spotlight. However, the company provides a building block without which modern electronic systems would not function.
For me, TTM is a good example of how interesting investment opportunities are often found not where the headlines are made, but where the technological infrastructure is being built.
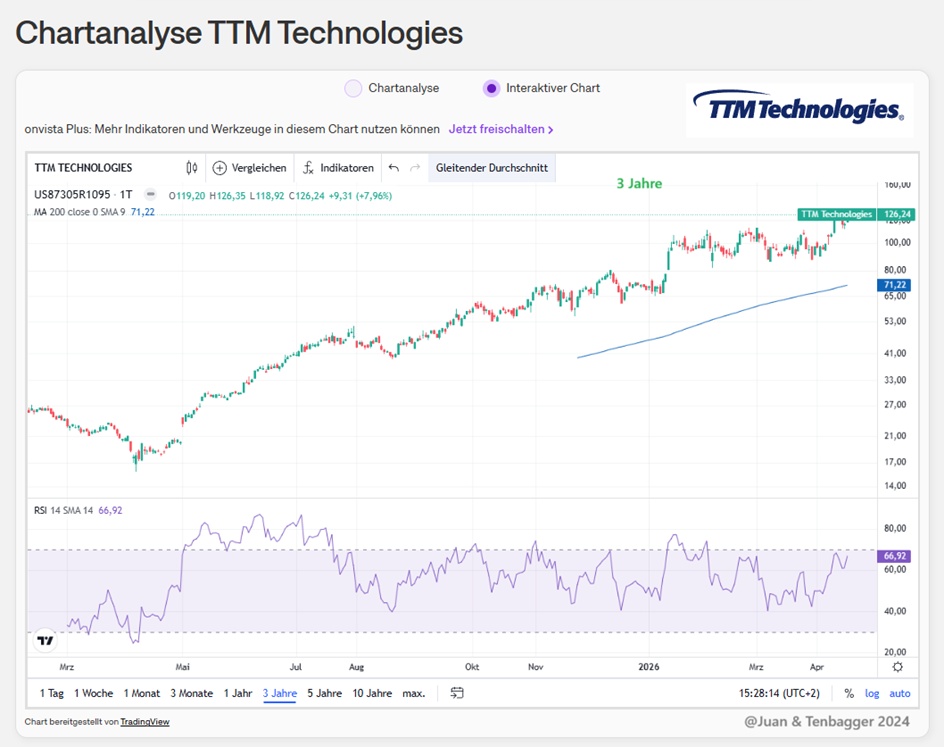
The sharp rise in the stock price over the past few months shows that the market is increasingly recognizing the importance of this sector. However, inclusion in this DIBS Bottleneck series is not determined by past stock performance, but rather by the company’s role within the respective bottleneck.

I'm looking forward to more 👍

Juan and Jack, the big battle .
Good morning my dears,
Some of you will probably have already seen my new series
🎥 "My intern Juan on a tenbagger search" know.
Here, Juan is looking for companies for you with great enthusiasm. Which might even have the potential to become a Tenbagger.
Here, dear Juan often dives deep into the engine room. Which involves a lot of work and enthusiasm. That's why I don't say anything about Juan.
" For me, Juan is the Elton of interns"
After all, I now prefer to watch Elton on TV than his mentor.
That's why Juan gets my full support when Jack or another prompt thinks he's doing a bad job. And looks for the fly in the ointment.
Yes, I know, that's what prompts are for.
But yesterday Juan has $TTMI (+4,72%) TTM, Juan found a great company in the industry that I would invest in myself.
Juan listened carefully to Jack, after all he's the one who looks for the pearls. And in the end Jack just sits in his nest.
And looks at what doesn't fit the company from his checklist.
- Growth in turnover and profit
- Debt
- CAPEX
- Margins
- FCF Yield
- Valuation
He and his colleagues seem to be particularly fond of FCF Yield. Just like the cat likes the mouse. Free cash flow is there to work with, not for the piggy bank.
For Jack, yesterday it was investing in concrete, and he dismissed the high-quality products for the semiconductor industry and aerospace as frills.
But Juan takes it with a sense of humor, it looks like a battle for him. And that's why he wants to make it as difficult as possible for Jack. Dear Jack, buckle up and take a close look at what's in Juan's goodie bag for you today.
As always, Juan would love lots of support from the community in the comments.
And presents you today Innoscripta $DE000A40QVM8 (+1,79%)
Innoscripta - Highly profitable software company with turnaround potential and a high dividend yield.
08.04.26
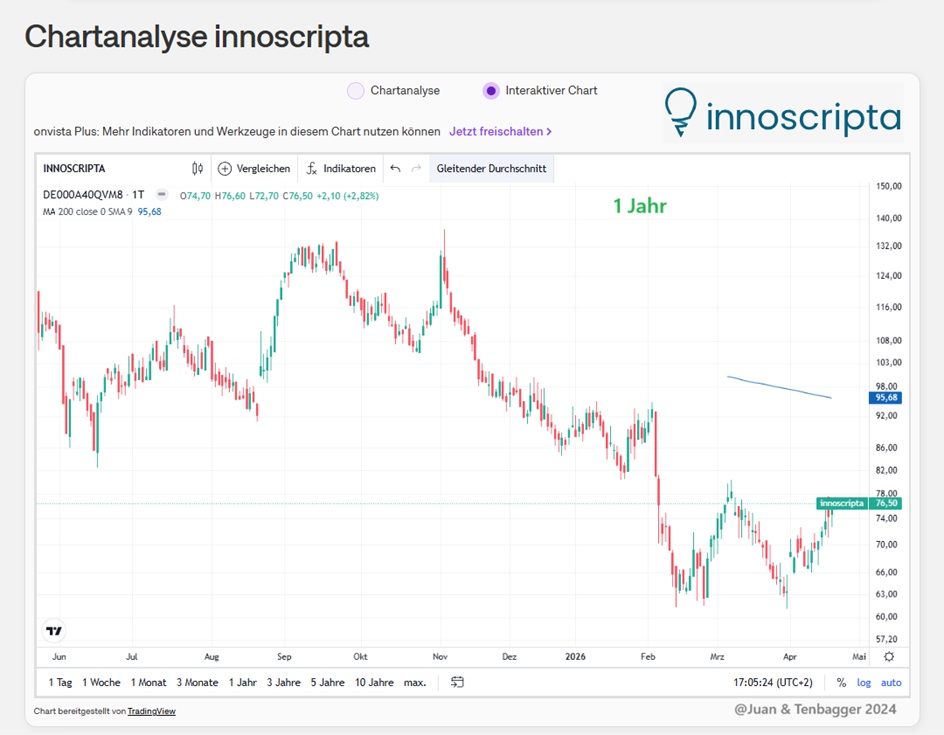
The Munich-based software company Innoscripta [WKN: A40QVM, ISIN: DE000A40QVM8] could become an exciting turnaround story according to Börse Online (issue 15/2026). After the IPO at EUR 120 in May 2025, the share price fell sharply. On the other hand, the company has grown strongly since then and generates extremely high margins. For courageous shareholders, this is a good opportunity for speculation.
Innoscripta operates a platform for recording and controlling expenditure on research and development. Customers who use this platform can receive tax refunds for research and development costs. The online platform enables the complete recording of data and documentation for the authorities. If successful, Innoscripta receives 20% of the tax refunds.
Even if the momentum in sales growth will slow down, the Group will continue to impress with a high profit margin
The platform has the potential to be a success story. Innoscripta has been able to multiply its turnover in recent years. In 2025 alone, sales growth of almost 60 % was achieved.
Innoscripta benefits from economies of scale and has been able to achieve a margin of 61% as a result. In the current financial year, turnover is expected to increase by more than 30 %. The operating result will be at least EUR 80 million.
The dividend policy is also exciting for investors. The current yield is 6.4%. Nevertheless, there are risks with regard to growth potential. On the one hand, competitors could try to build up their own solutions with AI. And churn in the portfolio should not be forgotten. First-time customers could claim expenses from the last four years. As a result, the participation in tax refunds will be correspondingly lower from next year. However, if Innoscripta can continue to achieve double-digit growth rates, the share price has the potential to double. Börse Online advises with a target price of 100 euros to buy (40 % potential).
Innoscripta SE: Insider purchase and extension of the tax research allowance in Germany
Von M. Herzberger - Updated on 21.01.26 10:20
Innoscripta SE (i.) is positioning itself as a specialized software provider that radically simplifies the often bureaucratic processes surrounding government research and development (R&D) funding. Instead of limiting itself to manual consulting services, the Group digitizes the entire value chain from the identification of eligible projects to legally compliant documentation and the submission of applications to the authorities.
Both CEO Michael Hohenester and Co-CEO Alexander Meyer took advantage of the share price fluctuations following the IPO in May 2025 via their investment companies to make massive purchases of their own shares. On the evening of January 20, a new insider purchase by CEO Michael Georg Hohenester via Hohenester Beteiligungs-UG (haftungsbeschränkt) was reported after the close of trading. Specifically, he bought shares in Innoscripta via XETRA on January 15 at an average price of EUR 84.88 per share, amounting to EUR 118,752.20.
A key growth driver is the expansion of the research tax allowance in Germany, which will take effect from January 2026. The new rules, which include a 20% flat rate for overhead costs and an increased assessment basis, will make the subsidy more attractive for companies and are likely to lead to a sharp rise in demand for Innoscripta software as an enabler of these funds. As Innoscripta's platform structure allows for high fixed cost degression effects, every additional euro of revenue should contribute disproportionately to profits. In addition, there is the potential for further internationalization and the development of the huge SME market, which has hardly been penetrated to date and is now increasingly coming into focus due to the simplified funding conditions.
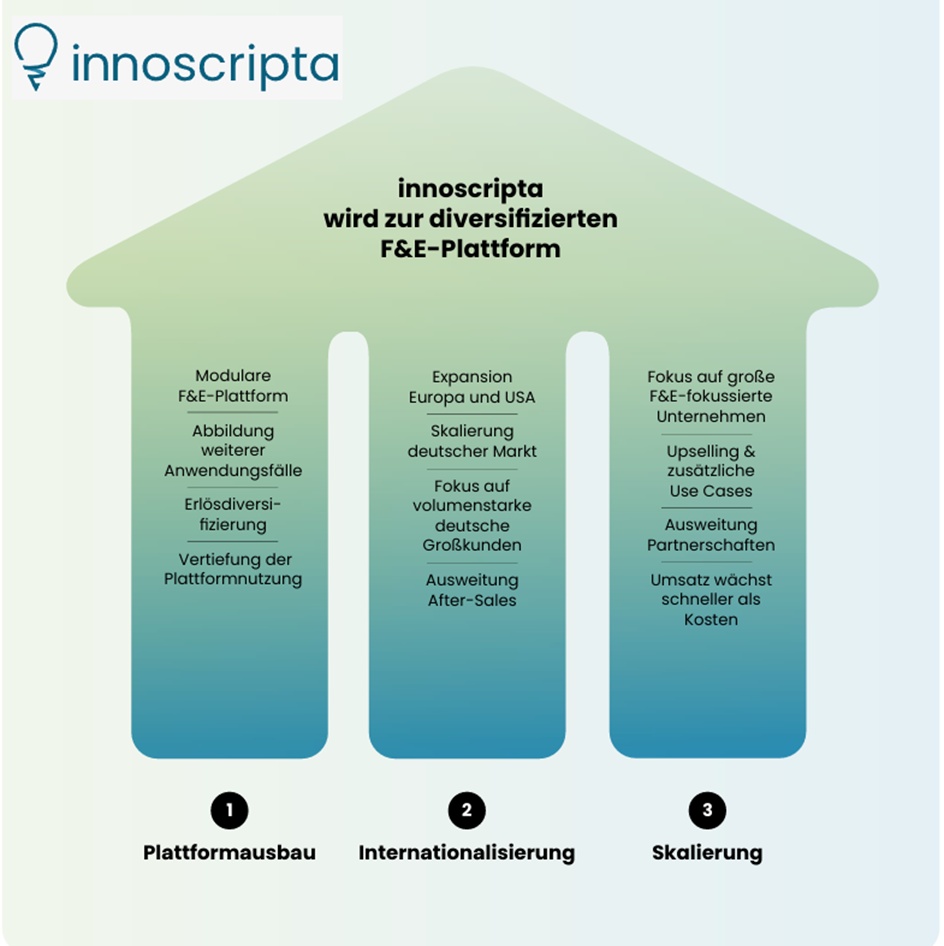
Three-pillar growth strategy
The tax incentives for research have broad political support
innoscripta has many years of experience and a high level of market penetration in this regulated environment. Accordingly, the business model is based on an established legal funding framework.
On course for growth:
In the coming years, innoscripta will develop from a primarily funding-driven platform into a diversified software platform that increases the efficiency, transparency and controllability of R&D activities as a whole. Fiscal research funding will remain an important, but not the only, component of the platform. In the long term, Clusterix is to be established internationally as a central system for R&D-related processes. The innoscripta growth strategy has three strong drivers: platform expansion, growth in core markets such as Germany and increasingly internationally, and scaling the business model.
1️⃣ Expansion of the platform
Clusterix is to develop even more strongly into a modular data and
process platform for R&D projects as a whole:
- Research allowance as the first, high-margin use case
with immediate, economic benefits for customers as an
easy entry
- Illustration of further use cases with the same architecture,
z. documentation and verification-intensive topics
such as transfer pricing or other R&D-related control and compliance
and compliance issues
- Increasing diversification of revenues with simultaneous
deepening the use of the platform
2️⃣ Growth in the core market + internationalization
innoscripta's growth in its home market of Germany remains attractive due to:
- continuous expansion of production volume in Germany and high margins
- increasing market penetration with major German corporations
- Expansion of after-sales opportunities with existing customers
In addition to the focus on Germany, European and international expansion is planned, including in
- Markets without a relevant language barrier e.g. Austria, Netherlands
- First locations opened in France and the USA at the start of 2026, with more to follow in the UK
- In other international markets in the medium term, as R&D tax incentives are established in almost all OECD countries
International activities are deliberately in a controlled development phase. The aim is to establish sustainable structures with clear cost control before further scaling steps are taken. innoscripta is pursuing a risk-conscious approach to expansion.
3️⃣ Scaling
In the coming years, Clusterix will be continuously developed and its efficiency increased. Revenue is set to grow significantly faster than costs thanks to the following measures:
- Focus on larger, R&D-strong companies,
- Expansion of existing customer relationships and additional use cases
- Strong partnerships to drive further expansion
The business model is characterized by high operational scalability. With increasing sales growth, fixed cost levers have a positive effect on earnings development. innoscripta assumes that the structurally high profitability can be secured sustainably even with further growth.
Sales efficiency will increase sustainably as the product, platform and use cases are clearly defined and geared towards recurring requirements.
NEWS
- innoscripta drives expansion in Europe: Market entry in France completed
15,04,2026
- innoscripta SE expands in the Rhine-Main growth region and strengthens its position as a leading R&D platform provider with a new office in Frankfurt
19,03,2026
- Why Exasol values innoscripta's consulting and software support
Exasol's Erfolgsgeschichte | innoscripta
- CEWE Group gains funding clarity and structured R&D processes with innoscripta
CEWE's Erfolgsgeschichte | innoscripta
- Leica Nussloch and innoscripta
Leica's Erfolgsgeschichte | innoscripta
- ZDF Studios structures complex funding processes for digital innovation
ZDF's Erfolgsgeschichte | innoscripta
- Verti Versicherungs AG achieves full approval of all submitted R&D funding applications
🧾 Brief summary of the key financial figures (Innoscripta 2025-2028)
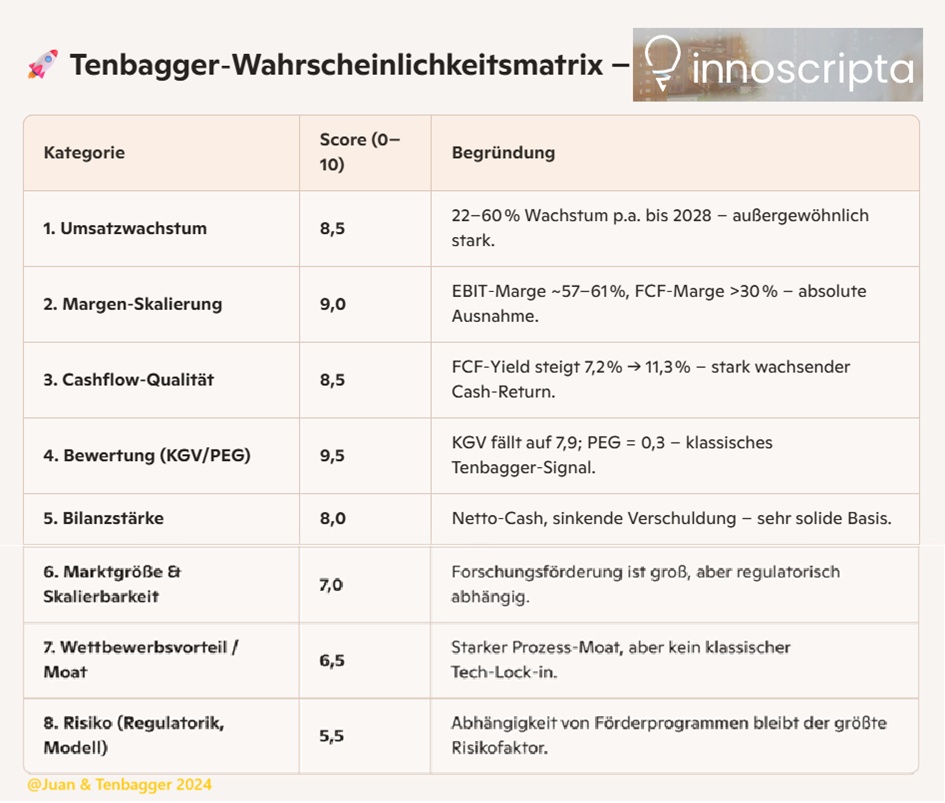
Innoscripta shows an extremely dynamic, almost atypically strong growth profile for a service company. Revenue increases over four years at 22-60 % per yearwhile EBIT and net income grow almost proportionally. This speaks for a scalable, high-margin business model.
The margins are exceptionally high:
- EBIT margin constant ~57-61 %
- EBITDA margin ~58-62 %
- FCF margin >30 % from 2026
Such values are otherwise more likely to be seen in software or IP-based business models.
Particularly strong:
- ROE > 90 % (2026) - an indication of extremely efficient use of capital
- Stable double-digit growth in free cash flow
- Net debt is negative and continues to decrease → Net cash position
Risks: Margins are so high that they could be difficult to maintain in the long term. In addition, the model is heavily dependent on regulatory framework conditions (research funding)
Overall assessment: Financially, Innoscripta looks like a a highly profitable, rapidly scaling quality company with excellent cash generation and very strong balance sheet. The key figures are clearly strong in terms of growth and returnsbut also unusually high - which creates opportunities and valuation risks at the same time.
Market value 744
Number of shares (in thousands) 10,000
Date of publication 20.02.2026
🧾 Summary of the key valuation figures (Innoscripta 2025-2028)
The valuation of Innoscripta appears strikingly favorable in relation to growth. From 2026, the P/E ratio falls from 13 → 10 → 7.9which is unusually low for a company with double-digit sales and earnings growth. At the same time, the P/B ratio falls from 10.5 → 6.08 → 4.96which indicates a rapidly increasing equity base and high profitability.
The PEG value of 0.3 in 2027 and 2028 signals a massive undervaluation relative to earnings growth - Values below 1 are considered attractive, 0.3 is extremely rare.
The FCF yield is rising sharply (7.2 % → 8.7 % → 11.3 %), which shows that the company is generating more and more free cash flow per market capitalization. This is a classic quality feature of mature, highly profitable business models.
The dividend per share is high and volatile (19.5 → 16.08 → 24.39), but the payout ratio remains within reasonable limits. The dividend yield ranges between 5-7% and is therefore above average and attractive.
Overall assessment: The valuation ratios paint the picture of a highly profitable growth companythat traded like a value stock in terms of valuation. The combination of falling multiples, rising FCF yield and extremely low PEG points to a structurally undervalued profile. structurally undervalued profile profile - assuming the forecasts materialize.
🚀 Does Innoscripta have tenbagger potential? - Juan's assessment
In a nutshell: Yes - the valuation ratios clearly speak for it. And more so than you would normally expect from a company of this size.
🔍 Why the valuation signals Tenbagger potential
1) Extremely low multiples despite strong growth
- P/E ratio falls from 13 → 10 → 7.92
- P/B ratio falls from 10.5 → 6.08 → 4.96
For a company with >30% growth, this is unusually favorable. Such multiples are more likely to be seen in stagnating companies - not in scaling machines.
2) PEG of 0.3 = classic tenbagger signal
PEG < 1 = attractive PEG < 0.5 = rare PEG = 0,3 = massive undervaluation relative to earnings growth
This is exactly the area in which former tenbaggers such as Nvidia, ASML, Palo Alto, Salesforce were in their early phases.
3) FCF yield rises sharply (7.2% → 8.7% → 11.3%)
A company with double-digit growth and at the same time delivers double-digit cash flow returns is an exceptional case.
This means: The market is not pricing in growth.
4) Dividend yield of 5-7 % despite growth
Growth companies normally pay no dividends. Innoscripta pays high dividends and still continues to grow strongly.
That is a sign of quality.
🧠 Juan's overall verdict
Yes, Innoscripta shows clear tenbagger potentialbecause:
- Valuation extremely low
- Growth high
- Margins exceptional
- Cash flow strong
- PEG ultra-low
- Balance sheet net cash
- Market apparently does not yet understand the model
BUT: The model is heavily dependent on research funding. If this remains stable, a tenbagger is realistic. If not, the potential drops significantly.
⭐ Overall score: 7.8 / 10
🎯 Realistic tenbagger probability: 25-35 %
This is high - comparable to early-stage companies that are scaling strongly but are not yet understood by the market.
🧠 Juan's conclusion
Yes, Innoscripta has real tenbagger potential. The figures speak for themselves: Undervalued, highly profitable, fast-growing, cash-flow rich.
The biggest variable is the regulation. If it remains stable, a tenbagger in 5-8 years is absolutely realistic.
(no investment recommendation, just Juan's assessment)
Performance
1 week +7.51 %
1 month +9.25 %
6 months -33.21 %
SHARE 72.15€ (22.04.2026 at 9:15 a.m.)
JACK, best regards your JUAN ( @Aktienhauptmeister )
+ 5

Juan on Tenbagger search, one more time
Hello my dears,
As announced yesterday, the series continues today.
After the last company presentation of Filtronic $FTC (-5,39%) the dear Prompt Jack ( @Aktienhauptmeister ) took another look at the company.
I realized that Juan still has some weaknesses, which Jack fortunately pointed out to us without embellishment.
Juan recognized the potential in the sector and also had SpaceX's IPO in mind. But in his euphoria, he neglected important criteria.
- He overlooked the fact that a great deal of SpaceX fantasy is already priced into the share price
That's why I explained to Juan once again in a personal one-on-one meeting. Despite the euphoria and Tenbagger fantasy, the valuation should not be neglected. After all, in the end this contributes to a large extent to achieving a Tenbagger at all.
Guys, and what can I tell you, motivated by the conversation, Juan set off on another search.
And he found a competitor of Filtronic in the USA.
Again, I look forward to a ruthless review from Jack ( @Aktienhauptmeister ), and from the community.
TTM Technologies $TTMI (+4,72%)
66% plus in the data center segment makes PCB specialist an indispensable AI profiteer!
13.04.2026
AI growth driver: massive demand for specialized PCBs for data centers ensures forecast segment growth of 66 Strong guidance for 2026: The company forecasts double-digit revenue growth driven by massive demand for AI infrastructure and modernization in the defense sector. Strong order backlog: A record backlog of USD 1.61 billion in the aerospace and defense sector offers long-term planning security.
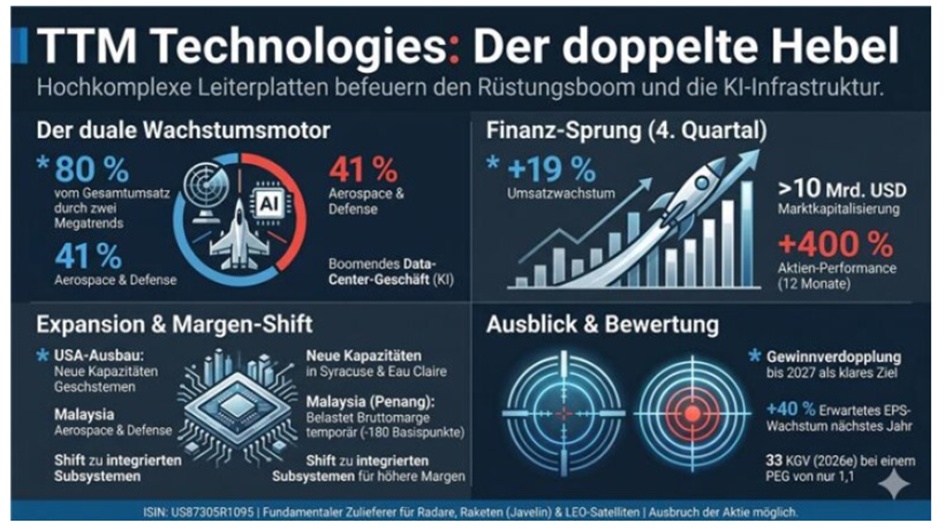
The double lever: How TTM Technologies is benefiting from the defense boom and AI craze.
15.04.2026
There's still room after the rally.
The market capitalization of TTM Technologies (TTMI) has now climbed to over USD 10 billion. The price-earnings-to-growth ratio (PEG) is 1.1, despite the 400% performance rally in the last twelve months.
Important components for radars, missile control systems and satellite communication
The company acts as the nervous system of modern defense and space systems. The company is not a manufacturer of tanks or missile hulls, but produces the highly complex printed circuit boards (PCBs), radio frequency (RF) assemblies and microwave subsystems that are essential for radars, missile guidance systems (e.g. Javelin) and satellite communications. The strategic role is also evolving: TTM is moving up the value chain by no longer just supplying the bare circuit board, but building complete, integrated sub and mission systems. This is lucrative, as complex assemblies achieve significantly higher margins than basic PCBs. In the space sector, TTM is benefiting from the development of radiation-hardened components that are needed for thousands of new LEO (Low Earth Orbit) satellites.
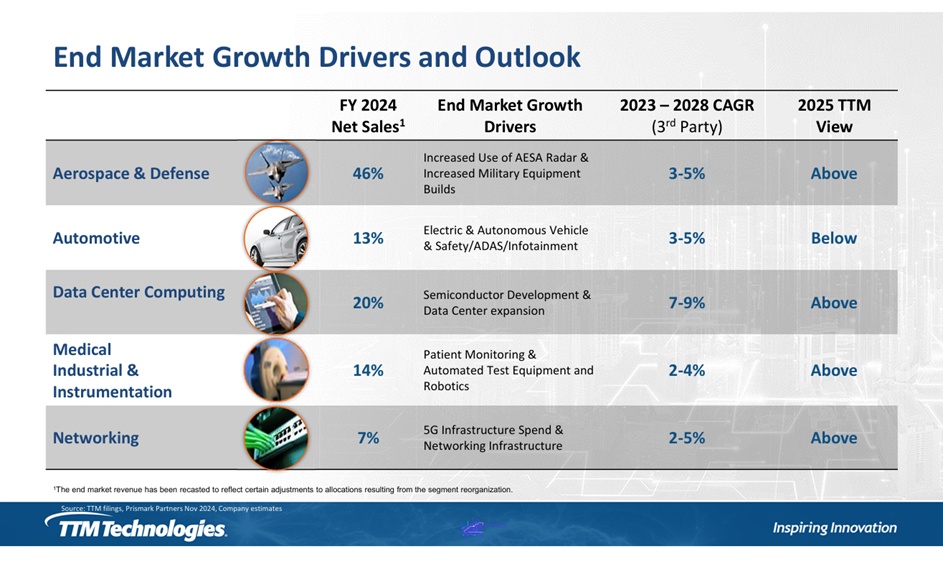
Aerospace & Defense accounts for around 40% of sales - Data Center business is also booming
41% of sales come from the Aerospace & Defense sector. At the same time, the data center business (AI) is booming. Together, these two drivers account for 80% of business. TTM is benefiting from the fact that military systems increasingly require AI capabilities ("Edge AI"), which is driving demand for extremely powerful PCBs in the defense sector. The new plant in Syracuse (New York), which is expected to generate revenue in the second half of 2026, and the huge plant acquired from TDK in Eau Claire (Wisconsin), will massively increase US production capacity for strategic customers.
Almost 20% sales growth
TTM delivered a strong 4th quarter and beat its own forecasts. Sales increased by 19%. The new plant in Penang (Malaysia) is not yet operating within the target corridor. It weighed on the gross margin in Q4 with 180 basis points, which was worse than the previously forecast 160 basis points. Management vows improvement, but this remains an operational construction site. The operating margin is improving and management issued very bullish medium-term growth targets (doubling profit by 2027). Bookings for surveillance radars, air defense systems (LTAMDS) and missile systems (MRAM, Javelin) were particularly highlighted. Management emphasized the growth in so-called "restricted programs" (secret military projects).
Conclusion
The ambitious targets (doubling profits by 2027) are attractive, but operational implementation is not a sure-fire success. The valuation with a P/E ratio26e of 33 is still ok, as EPS is expected to increase by another 40% in the coming year. The share could break out again and be picked up.
TTM Technologies, Inc. is a global manufacturer of technology solutions, including mission systems, radio frequency (RF) components and RF microwave/microelectronics assemblies, as well as quick-turn and technologically advanced printed circuit boards (PCBs). The company's segments include PCB and RF and Specialty Components (RF&S Components). The PCB segment consists of approximately 16 domestic system, subsystem and PCB factories, four PCB factories in China, one in Malaysia and one in Canada. The RF&S Components segment consists of one domestic plant for RF components and one plant for RF components in China. Both segments operate predominantly in the same industries, producing customized products for their customers and using similar distribution channels. The company offers a range of engineered systems, RF and microwave assemblies, HDI (High Density Interconnect) PCBs, rigid-flex PCBs, customized assemblies and system integration, IC substrates and others.
Number of employees: 18,200
TTM Technologies offers advanced technology products for a variety of innovative applications
- Aerospace & Defense
- Automotive
- Commercial Space
- Data Center Computing
- 5G / 6G
- Industry and instrumentation
- Medical Medicine
- Networks & Communication
INDUSTRY LEADER
- Top 10 of the world's leading PCB manufacturers
- 22 production sites worldwide
In the future
- Continued focus on markets with growth characteristics and favorable megatrends - Ongoing investment in differentiation:
- Advanced PCB technology for Generative AI
- Developed RF products for aerospace
- Manufacturing sites
- Sound financial management
- Plan in place to improve operating margins
- Strong focus on cash flow generation
- Capital allocation balances investment in the business with return of capital to shareholders
TTM Technologies, Inc. Investor Presentation - October 2025
Geographical distribution of sales
(USD 2025)
USA 1.55 billion
Other 1.1 bn
Taiwan 257 million
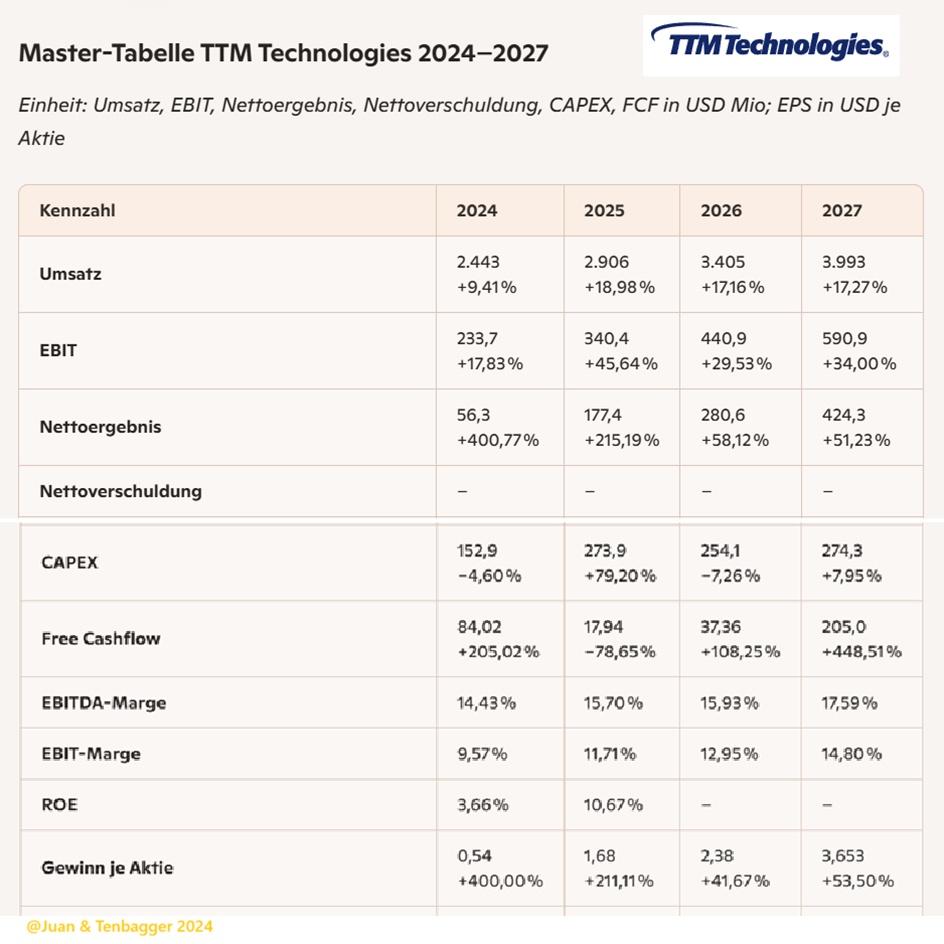
🔎 Brief analysis of the key financial figures (2024-2027)
1) Strong, accelerated growth Turnover grows from 2.44 billion → USD 3.99 billion (+17-19% p.a.). This is exceptionally dynamic for a PCB/RF manufacturer and reflects structural demand (aerospace, defense, high-speed computing).
2) Margins are rising continuously EBIT margin improves from 9,6 % → 14,8 %. EBITDA margin increases from 14,4 % → 17,6 %. → This speaks for economies of scale, pricing power and mix improvement.
3) Earnings explode Net profit grows from 56 million → USD 424 million. EPS increases from 0.54 → 3.653 USD. → Massive operating leverage.
4) Free cash flow volatile, but very strong in 2027 2025 weak (high CAPEX), but 2027 with 205m USD an FCF breakout. → CAPEX cycles determine short-term FCF fluctuations.
5) ROE jumps up From 3,66 % (2024) to 10,67 % (2025). → Return on investment increases significantly, no estimates from 2026.
🧭 Summary for you as an investor
TTM shows a classic structural growth profile: rising sales, rising margins, rising profits - and an FCF peak in 2027. The company is scaling cleanly, which in combination with defense exposure and high-speed electronics creates a robust, cycle-resistant growth picture results.
🧭 Ultra-short valuation conclusion
TTM is clearly a growth case, not a value case:
- P/E ratio highbut falling towards 2027 → Valuation eases.
- P/E 2027 = 0.6× → Strong ratio of growth to price.
- FCF yield 2027 = 1.56 % → still low, but trend rising strongly.
- No dividend → Complete focus on reinvestment & growth.
🚀 Tenbagger probability matrix - TTM Technologies (TTMI)
Based on the MarketScreener data from your active tab
📊 1st valuation basis (2024-2027)
- P/E RATIO: high, but falling → 46× → 34×
- PEG: 2027 at 0,6× → strong growth-to-price ratio
- FCF yield: 2025 weak, 2027 strongly increasing (1.56%)
- P/B RATIO: moderate (5-6×) → Valuation speaks for growth, not value.
📈 2. fundamental leverage (2024-2027)
- Turnover: 2.44 → USD 3.99 bn (+17-19% p.a.)
- EBIT margin: 9,6 % → 14,8 %
- EPS: 0.54 → 3.653 USD
- FCF: 2027 Breakout (USD 205 million) → Scaling + margin expansion + earnings leverage.
🛰️ 3. Strategic positioning
- Exposure to Aerospace, defense, high-speed computing
- PCB/RF high-end segment → structurally growing
- Strong order intake according to investor presentations → Cyclically robust + structurally growing.
🎯 Overall score: 6.9 / 10
→ Realistic tenbagger probability until 2032: 15-25 %
Why not higher?
- FCF yield still too low
- CAPEX cycles slow down in the short term
- Valuation already ambitious (growth premium)
Why still interesting?
- EPS leverage is extremely strong
- Margins increase every year
- Defense exposure provides stability
- PEG 2027 = 0.6× → Rare for a structural growth stock
Short conclusion for you
TTM is not a classic tenbagger moonshotbut a quality growth compounder with realistic 2-4× potential and a small but real chance to 10×, if:
- margins continue to rise
- FCF remains permanently high from 2027
- Defense/HPC cycles continue
Valuation does not expand too much
Performance
1 week +3.91 %
1 month +29.42 %
1 year +120.85 %
3 years +896.37 %
10 years +1,742.92 %
PRICE 108.23€ (21.04.2026 at 11:39)
+ 6

Títulos em alta
Principais criadores desta semana