
I don't think that's such a bad price for the first tranche.
Vertiv Holdg
Ação
Ação
Ticker: VRT
VRT
Price
Discussão sobre VRT
Postos
68
1Semana·
𝐕𝐞𝐫𝐭𝐢𝐯: 𝐐𝟑 𝐄𝐚𝐫𝐧𝐢𝐧𝐠𝐬 𝐚𝐧𝐝 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝐂𝐫𝐮𝐬𝐡 𝐄𝐬𝐭𝐢𝐦𝐚𝐭𝐞𝐬, 𝐎𝐫𝐠𝐚𝐧𝐢𝐜 𝐎𝐫𝐝𝐞𝐫𝐬 𝐒𝐮𝐫𝐠𝐞 𝐎𝐯𝐞𝐫 𝟏
⠀
📊 𝐑𝐞𝐬𝐮𝐥𝐭𝐬
• Adj. EPS: $2.21 (Est. $1.82) ✅, +78% YoY.
• Revenue: $4.313B (Est. $3.76B) ✅, +61% YoY.
• GAAP EPS: $1.95, +91% YoY.
• Organic Revenue Growth: +55% YoY.
• Adj. Operating Profit: $1.087B, +83% YoY.
• Adj. Operating Margin: 25.2%, +290 bps YoY.
• Operating Cash Flow: $794M, +64% YoY.
• Adj. Free Cash Flow: $652M, +50% YoY.
• Organic Orders Growth: >100% YoY.
• Liquidity: $6.2B, net cash position.
⠀
🎯 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
• Q4 2026 Revenue: $4.313B–$4.513B, midpoint $4.413B (Est. $4.31B) ✅.
• Q4 2026 Adj. EPS: $2.22–$2.28, midpoint $2.25 (Est. $2.21) ✅.
• Q4 Organic Revenue Growth: 49%–51%.
• Q4 Adj. Operating Margin: 25.3%–26.3%.
• FY2026 Revenue: $14.45B–$14.85B, midpoint $14.65B (Est. $14.00B) ✅, raised.
• FY2026 Adj. EPS: $7.10–$7.20, midpoint $7.15 (Est. $6.73) ✅, raised.
• FY2026 Organic Revenue Growth: 37%–39%.
• FY2026 Adj. Operating Profit: $3.475B–$3.555B.
• FY2026 Adj. Free Cash Flow: $2.6B–$2.8B.
⠀
📌 𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
• Q3 Adj. EPS beat consensus by ~21.4%, while revenue exceeded estimates by ~14.7%.
• Organic orders more than doubled YoY, reflecting accelerating global data center infrastructure demand.
• Americas revenue surged 75% YoY, APAC grew 50%, and EMEA increased 23%.
• Adjusted operating margin expanded 290 bps to 25.2%, driven by operating leverage and manufacturing productivity.
• FY2026 revenue guidance was raised by $650M, with the new midpoint ~4.6% above consensus.
• FY2026 adjusted EPS guidance midpoint stands ~6.2% above consensus.
• Vertiv continues expanding manufacturing capacity and investing in next-generation power and cooling infrastructure.
⠀
💬 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐂𝐨𝐦𝐦𝐞𝐧𝐭𝐚𝐫𝐲
“We are in the middle of the largest infrastructure buildout and it's accelerating.”
1414
5 Comentários
Keineui@Keineui
1Semana
•
77
•Ver todas as 3 restantes respostas

1Semana·
Money has to work...
$VST (-2,71%) 10x at 126.81
$VRT (-4,12%) 10x at 178.36
and see below
Let’s see how it goes. All three are new positions. Maybe the price will correct a bit further, in which case we’ll add to the position at a lower price; maybe it will rebound, in which case we’ll gradually buy more.
1515
2 Comentários1Semana
Vistra is currently trading in an exciting range. It should benefit significantly from the demand for energy in the long term. The share buybacks over the past few years have been incredible. Here’s hoping it continues this way👍
•
22
•
1Mês·
Agreement Reached on the Acquisition of King Environmental Services
My dear friends, I remain invested in Vertiv.
Vertiv announced on September 24, 2026 announced the acquisition of King Environmental Services Ltd. . The company specializes in fluid management, commissioning, and thermal and electrical load testing for high-density, liquid-cooled data centers. With this acquisition, Vertiv aims to expand its service capabilities for AI and high-density data centers in Europe, the Middle East, and Africa .
With this move, Vertiv is not only expanding its hardware business but also its recurring service and integration offerings related to liquid cooling. This strengthens its position in the AI infrastructure market but also entails integration and execution risks in the short term. The press release did not disclose the purchase price or provide a specific upward revision to the forecast.
The acquisition of King Environmental Services aligns directly with the structural trend toward higher computing densities and liquid cooling in AI data centers. The geographic synergy is particularly positive: Vertiv gains additional operational capabilities in Europe and can more effectively support customers throughout the entire lifecycle of their cooling infrastructure.
www.vertiv.comVertiv announces agreement to acquire King Environmental Services Ltd., expanding global fluid management services
1717
5 Comentários

1Mês
I'm staying invested, too. My job involves a lot of planning and operations related to data centers. Liquid cooling is becoming more and more common for systems exceeding 100 MW.
•
66
•
1Mês·
Your thoughts on the potential portfolio
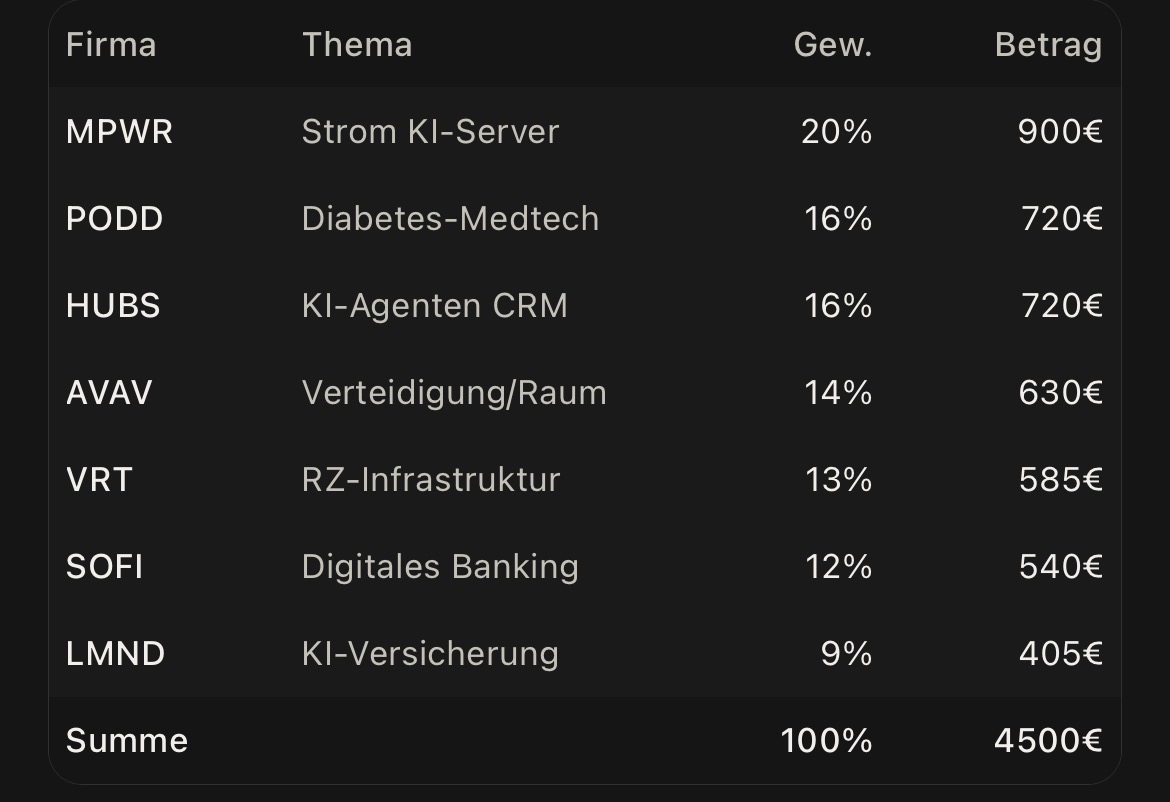
I’m 18, taking my high school graduation exams, have a long-term investment horizon, and am willing to take on a higher level of risk. With Claude’s help, I’ve put together a potential portfolio where I’d like to invest my money, since I’ve saved about 4,500€ through my job and other sources.
Component 1: The ETF Savings Plan as a Foundation
For some time now, I’ve been contributing €120 per month to a FTSE All World ETF and have already built up a base of €720 in it.
• Existing positions:
Microsoft (€515, +28%)
Amazon (€260, +30%) -> considering selling
Sofi Technologies (€245, -2.5%)
HubSpot (€188, -6.4%)
Lemonade (€170, -16%)
Building Block 2: The New Growth Portfolio (€4,500)
For my growth portfolio, I’m deliberately **not** investing €4,500 in other well-known mega-caps that haven’t yet been fully priced in by everyone:
I’m always open to suggestions for improvement and feedback😄
The ETF savings plan remains the actual foundation of my wealth-building strategy—everything else is a deliberately riskier supplement on top of that, not the other way around.
55
11 Comentários
Forget about individual stocks and just add QQQ to your portfolio. What nobody is talking about here is that in those US tax-deferred accounts everyone loves to track, rebalancing doesn’t trigger any taxes. Here, every move you make cuts into your returns. The main point of QQQ is that you can weed out the losers and buy more of the winners without incurring taxes.
•
1111
•
1Mês·
Risky, Niche… and Weirdly Convincing
I recently discovered $TMGT (-1,01%) and I’m actually pretty excited about it :) I just opened a position
It gives exposure to some of the more interesting corners of tech: AI, cybersecurity, robotics, space, quantum, data centers, semiconductors and more, basically a basket of sectors that are excited but probably will overcomplicate your portfolio if you try to expose yourself to each.
What really caught my attention are the holdings: $NBIS (-5,19%)
$MRVL (-4,27%)
$AMD (-4,39%)
$MU (-3,89%)
$PANW (-2,31%)
$CRWD (-2,96%)
$S (-1,89%)
$EQIX (-0,48%)
$DLR (+0,2%)
$IREN (-4,41%)
$VRT (-4,12%)
$IONQ (-3,43%) and many other smaller/niche companies with a lot of potential and barelly or really small existed in other ETFs and the big names doesn't dominate it. Also it has China and tiny bit small caps.
It also helped me finally get rid of my individual stock positions. A lot of the companies I was looking at for extra upside simply weren’t in my Nasdaq 100 or World Momentum ETFs, but many of them are here.
So instead of trying to guess which one will outperform, I can own the whole basket.
For me it’s a small aggressive satellite position, not a core ETF.
One small correction for Getquin: the TER is 0.50%, not what is currently shown here.
The fund is still pretty small, so hopefully more people discover it.
There is also $ITEP (-0,05%) but i like the exposure of $TMGT (-1,01%) better also it doesn't perform good when you conpare to $TMGT.
It has also more global thematic brother $WMGT (-0,61%) which is performing really good since the inception.
What do you guys think about $TMGT (-1,01%)
? Would you add something like this alongside Nasdaq/Momentum, or is it too thematic for you?
$TMGT (-1,01%)
$XNAS (-1,29%)
$EQQQ (-1,28%)
$CSNDX (-1,32%)
$XDEM (-1,48%)
$IS3R (-1,29%)
$SMH (-2,94%)
$INTL (-1,34%)
$WAGI (-3,85%)
$ITEP (-0,05%)
$SEMI (-3,96%)
$XAIX (-0,84%)
$AINF (-1,17%)
$EXXT (-1,3%)
$EQAC (-1,29%)
$QNTM (-1,3%)
$WQTM (-1,45%)
$QOMP (-0,11%)
$CHPX
$JEDI (-0,87%)

2Mês·
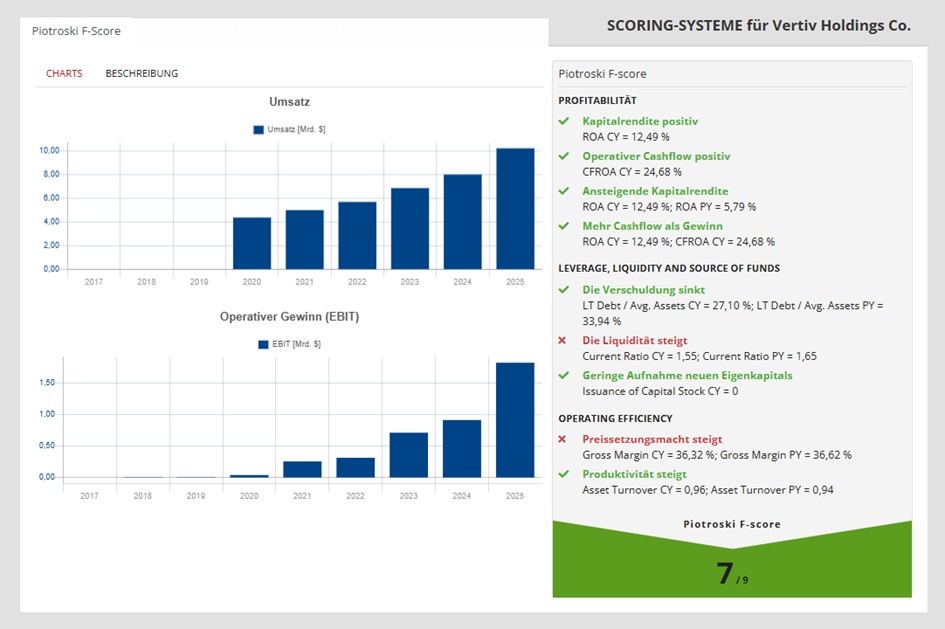
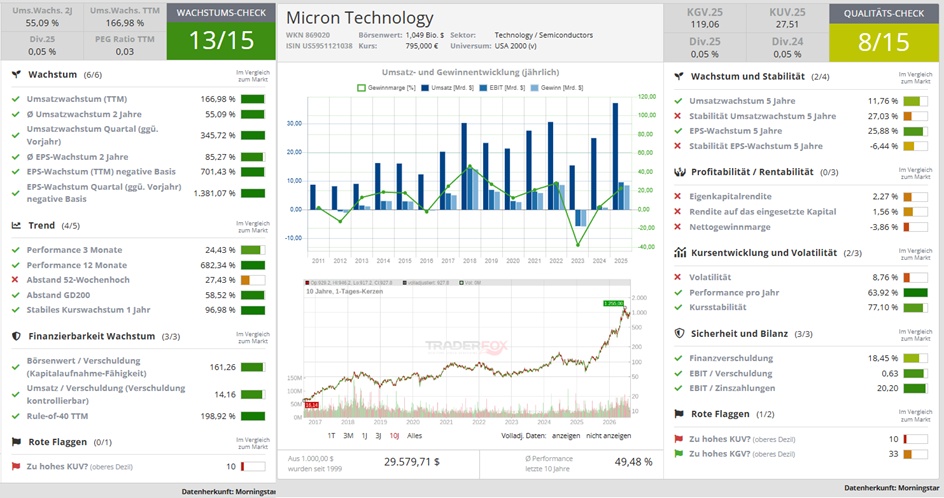
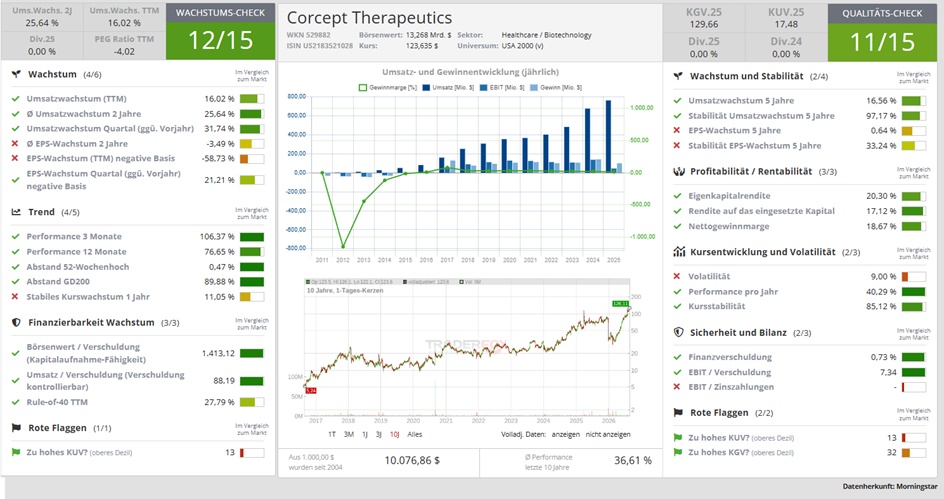
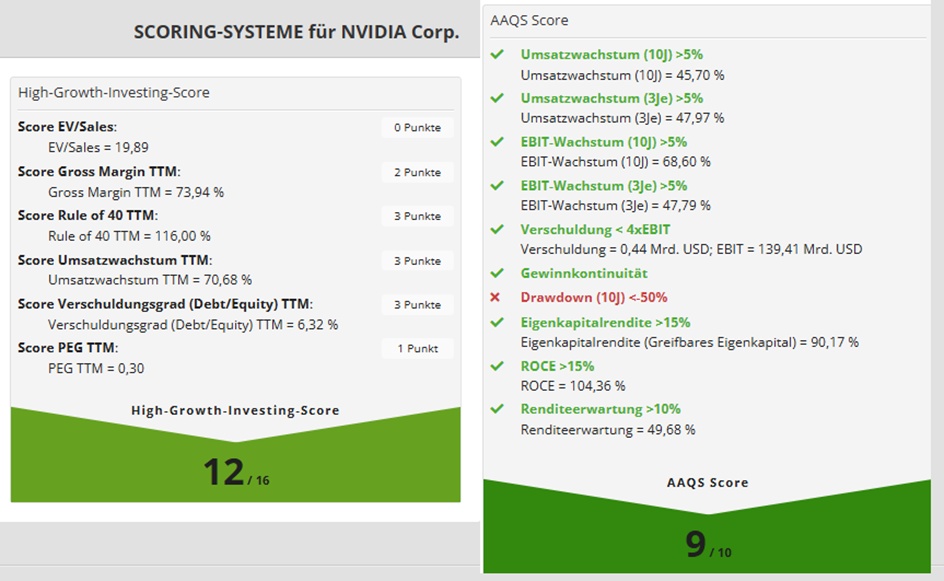
TÜV Inspection 2026, Part 1
Hello, everyone,
Every now and then, I send my portfolio in for a checkup.
I wanted to share today’s review with you.
I’m mainly focusing on the core—that is, the larger positions.
Of course, my main concern here is quality and growth are important to me.
The Traderfox Stock Terminal with its scoring system works well for this “TÜV” check. (no advertising)
If the valuation is too high, as a long-term investor I certainly won’t hit the sell button right away.
Feel free to let me know in the comments:
Whether you’re interested in this review at all and what you think of it.
How do you check your portfolio?
Which company do you like, or what would you like to learn more about?
Micron $MU (-3,89%)
GFT Technologies $GFT (+6,27%)
Nvidia $NVDA (-2,02%)
Corcept $CORT (-2,51%)
Vertiv $VRT (-4,12%)
Alphabet $GOOGL (-0,48%)
+ 6
3535
61 Comentários
It's alarming that, aside from $GFT, I also have all of your core stocks in my portfolio—either as stocks, derivatives, or both. That means either you're taking too many risks, or I'm playing it too safe. :-)
•
77
•3Mês·
The tough life of a trader!
I can understand very well that this isn’t for everyone, because heaven and hell are often very close together.
Example: As I posted here, I entered a leveraged derivative yesterday at noon at $VRT (-4,12%) at €1.60, as I posted here.
The stop-loss at €1.00 was triggered (about -40%), and the sell-off continued. Then, shortly before the market closed, I re-entered the same security at €0.59. The current price is €1.37, which is a gain of over 120% and more than makes up for the losses from the first trade.
Of course, this doesn’t always work out this way, and it was highly risky. So it’s better not to try this yourself—especially if you’re new to derivatives.
3131
11 Comentários
Congratulations on the trade, but at the end of the day, that was pure casino luck and not risk management. It should be seen as a warning rather than a model to follow.
•
66
•3Mês·
Snagged it before the market opened!
I just bought some shares in the U.S. right before the market opened, and the sell-off prices were at $LMND (-1,33%) and $VRT (-4,12%) to add to my position. At $VRT (-4,12%) it’s already paid off so far, up 5% in an hour.
1818
24 Comentários
Brave! …If I had to choose—if I had to choose at all—I would have gone with $VRT. Fingers crossed…
•
22
•
3Mês·
Vertiv: EPS Exceeds Estimates — Revenue Below Expectations
Here's the hot stuff from Vertiv Holdings $VRT (-4,12%) Q2 2026 Earnings Release, hot off the press.
🚀 Top-Line Performance & Hyper-Growth
Vertiv $VRT (-4,12%) surpassed the $3.27 billion . This represents extremely strong growth of +24.0% year-over-year (or +18.0% organic growth). The company has thus clearly outperformed Wall Street’s expectations, which stood at around 3.18 billion USD. Fueling this acceleration is the unrelenting global demand for AI cooling and high-performance power supply systems.
🔮 Balance Sheet Sensation & Cash Explosion
The fact that the engine is not only running but scaling extremely profitably is demonstrated by the operating cash metrics and the strength of the balance sheet:
The free cash flow (FCF) exploded in Q2 to $925 million —a breathtaking increase of +234% compared to the same quarter last year.
Financials at record levels: Vertiv officially reached the milestone of a net cash position (cash now exceeds financial liabilities). This effectively eliminates interest rate risk.
❄️ AI Infrastructure & Liquid Cooling
While traditional hardware manufacturers struggle with cyclical demand, Vertiv is fully benefiting from the construction of the next generation of data centers:
Liquid Cooling Dominance: Demand for liquid cooling and specialized thermal management systems for high-density chips (such as the latest NVIDIA architectures) is at an all-time high.
Pricing Power: The adjusted EBIT margin climbed by +410 basis points to a rock-solid 22.6%, underscoring the enormous pricing power in critical AI infrastructure.
Adjusted earnings per share (Adj. EPS) soared by +60% to $1.52 (analyst estimate: $1.38).
📈 Full-Year Outlook Raised
Based on excellent operational performance in the first half of the year, management is once again raising its forecast for FY2026:
Revenue guidance: Raised to $13.80 to $14.20 billion (previously $13.75B).
EPS guidance: Raised to $6.65 to $6.75 per share (on average, a massive increase of nearly +60% compared to FY2025).
⚡ 💡 Jack’s take
No sign of AI fatigue in the infrastructure sector. Vertiv proves that power and cooling remain the ultimate bottleneck for AI data centers. Whoever supplies the hardware—without which no supercomputer can run—has enormous pricing power. An operating cash jump of over 200%, paired with a spotless net cash balance sheet, is absolutely top-notch.

Títulos em alta
Principais criadores desta semana
Dados tempo real da LSX · Dados financeiros e EOD da FactSet