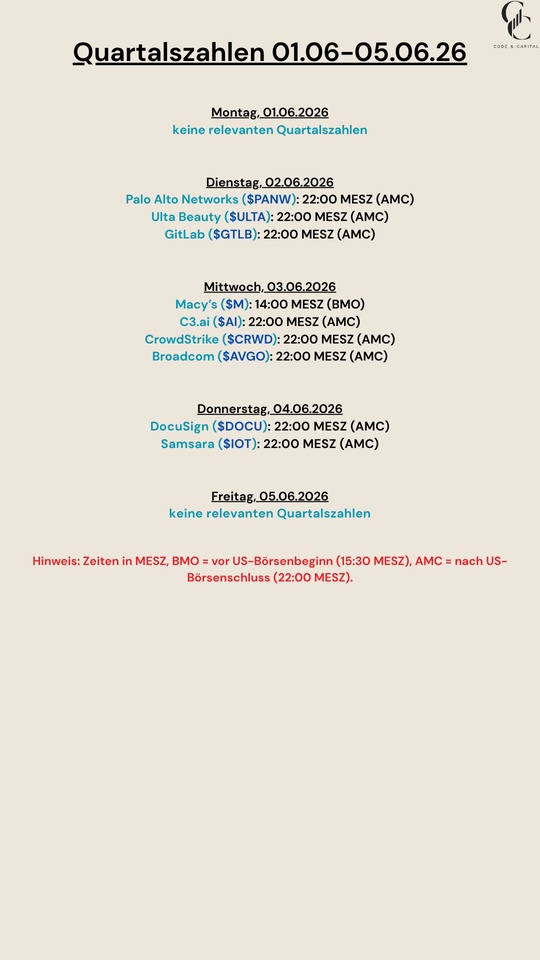
$PANW (-1,61%)
⠀
The headline: Wall Street remains overwhelmingly bullish after a broad beat-and-raise quarter, with AI increasingly translating into measurable security spending.
⠀
Average PT: $404
Implied upside from $357: ~13%
⠀
Updated analyst views:
• Jefferies: Buy, $450 unchanged (+26%)
• Truist: Buy, $435 unchanged (+22%)
• Scotiabank: Sector Outperform, $430 from $320 (+20%)
• Baird: Outperform, $420 unchanged (+18%)
• Citizens: Market Outperform, $415 unchanged (+16%)
• Evercore ISI: Outperform, $415 unchanged (+16%)
• Stifel: Buy, $415 unchanged (+16%)
• Citi: Buy, $410 from $400 (+15%)
• TD Cowen: Buy, $400 unchanged (+12%)
• Bernstein: Outperform, $253 unchanged (-29%)
⠀
What analysts liked:
• Q4 revenue reached $3.41B vs. $3.35B expected, up 34% YoY
• Adj. EPS of $1.02 topped the $0.98 consensus
• NGS ARR surged 63% to $9.1B, with nearly $1B of net new ARR added in Q4
• RPO grew 34% to $21.2B
• FY27 revenue guidance midpoint of ~$14.15B topped the ~$13.83B consensus
• FY27 NGS ARR and RPO guidance also came in above Street expectations
⠀
The AI angle: Growth is broadening across Prisma AIRS, XSIAM, Network Security and other AI-driven products. XSIAM ARR reached ~$700M, while Prisma AIRS reached roughly $120M.
⠀
Why the stock is soft:
• Gross margins are under pressure from higher cloud hosting and hardware costs
• CyberArk, Chronosphere and the newly announced Console acquisition add near-term integration and expense uncertainty
• Q1 revenue guidance implies a sequential decline from Q4
• NGS ARR was strong, but the beat fell slightly short of elevated buy-side expectations
• After a massive rally, valuation leaves less room for anything short of accelerating growth
⠀
Bottom line: Palo Alto delivered a fundamentally strong quarter with better-than-expected FY27 guidance and clear AI-driven demand. The debate is now about valuation and margins, not demand. Investors want proof that accelerating platform growth can translate into equally strong profitability as acquisition costs rise.