Micron Tech
Price
Discussão sobre MU
Postos
240



Podcast Episode 167: "Buy High. Sell Low."
Subscribe to the podcast so you don’t miss the year-end rally.
00:00:00 Crime Pays
00:07:17 JPMorgan Money Market Fund, 5% interest p.a.
00:10:54 SpaceX
00:18:00 Market Environment
00:34:00 Micron
00:50:30 Nike
01:00:00 Brazil ETF, Nu Holdings
01:27:45 Novo Nordisk
01:56:00 McDonald’s
Spotify
https://open.spotify.com/episode/6CMFiN9KKsX5EWIct1dgnJ?si=BXqto32nSeSrdUJg6qEoUw
YouTube
https://openyoutu.be/3TehNLK2NZg
Apple Podcasts
$NVO (+2,34%)
$MU (+1,5%)
$NU (-1,27%)
$MCD (+1,19%)
$SPCX (-2,4%)

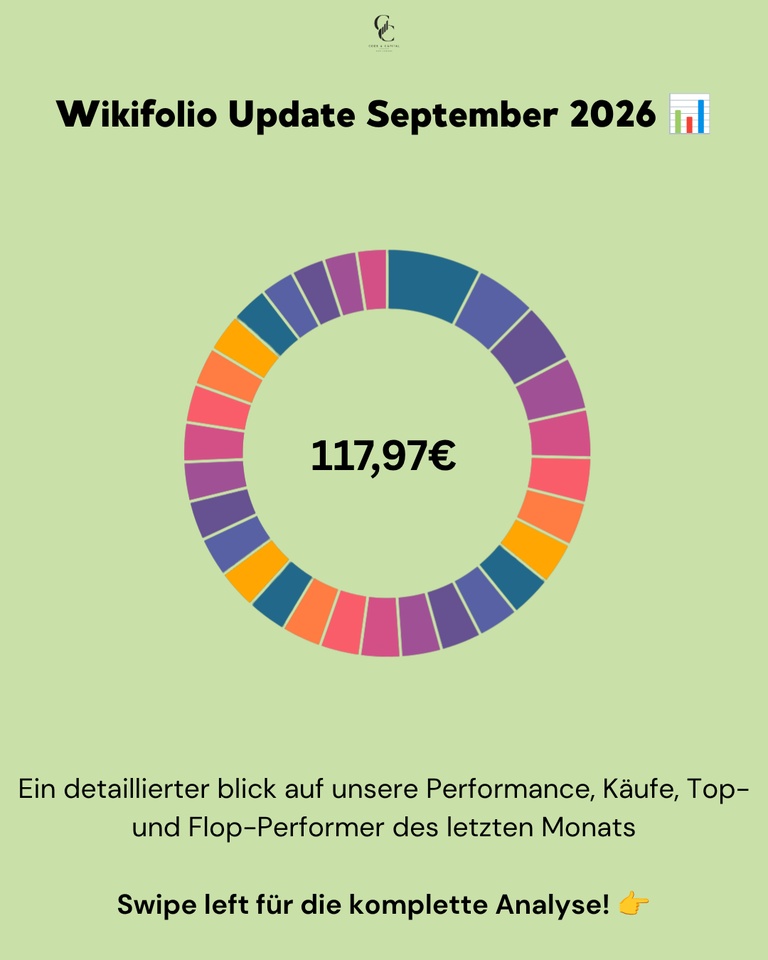
📊 Wikifolio Update September 2026: up 1.03%, tech stocks up, mining stocks down, and 18 of 30 positions swapped on October 1
In August, gold mines were the market's top performers. In September, they were the most expensive. Fresnillo
$FRES (+0,87%) down 15 percent, Micron
$MU (+1,5%) up 17. At the end of the month, the Wikifolio was up 1.03 percent, and one day later, I swapped out 18 of 30 positions.
September was all about interest rates and oil. Brent rose above $100 in the second week and, following a Saudi pipeline outage, briefly hit $110. U.S. inflation stood at 3.4 percent in August. On September 16, the Fed raised the benchmark interest rate by a quarter point to 3.75 to 4.00 percent, for the first time since July 2023. The 10-year U.S. yield subsequently climbed to 5.19 percent, a level last seen in 2007. This hardly bothered tech stocks. The Nasdaq hit a record high on September 21, and AMD has been worth one trillion dollars ever since. The situation was different in Europe. German inflation jumped to 3.3 percent, and the DAX lost about four percent over the month.
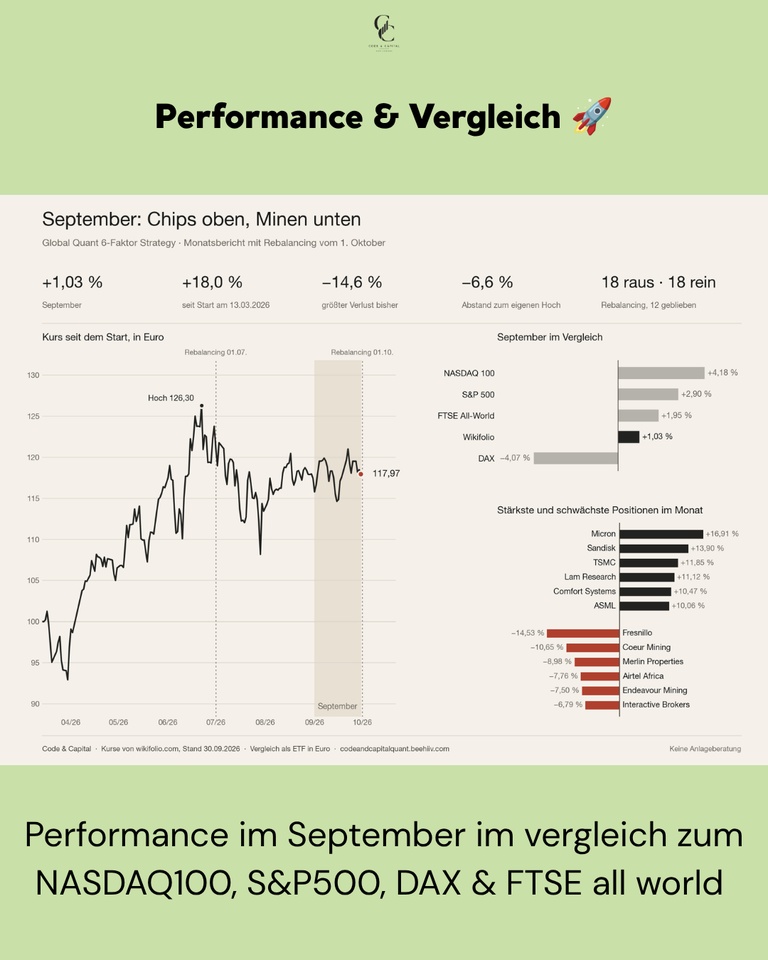
📊 Monthly performance: +1.03%
📊 Price as of September 30: €117.97
📊 Largest loss since inception: −14.6%
📊 Max performance: +18% (since March 13, 26)
Next rebalancing: Early January 2027
Performance & Comparison 🚀
The U.S. indices posted clear gains when calculated in euros, with the Nasdaq leading the way. The Wikifolio did not keep pace. It lagged behind the Nasdaq, S&P 500, and FTSE All-World, and outperformed only the DAX.
Performance Comparison (September 1–30, 2026, end of day):
Global Quant 6-Factor: +1.03%
NASDAQ 100: +4.18%
S&P 500: +2.90%
FTSE All-World: +1.95%
DAX: −4.07%
You can see what caused this in the two lists below. Tech stocks delivered, while mining stocks and a few individual stocks ate up a good chunk of those gains.
Purchases & Sales 💶
None in September itself. The model trades only on four dates per year, and the third was on October 1. What happened then is detailed in its own section below.
Top Movers in September 🟢
The month belonged to semiconductors and memory stocks. Midway through the month, Intel’s CEO said the company could currently only meet about half of the demand for processors. After that, the entire industry picked up steam. Micron
$MU (+1,5%) topped the list with +16.91%, followed by SanDisk
$SNDK (-1,61%) at +13.90% and TSMC
$2330 at +11.85%. Lam Research
$LRCX (-3,49%) rose +11.12%, ASML
$ASML (-0,26%) +10.06%. In between is Comfort Systems $FIX (-4,17%) , a stock that has nothing to do with chips, up 10.47%. In August, Comfort Systems was still among the losers.
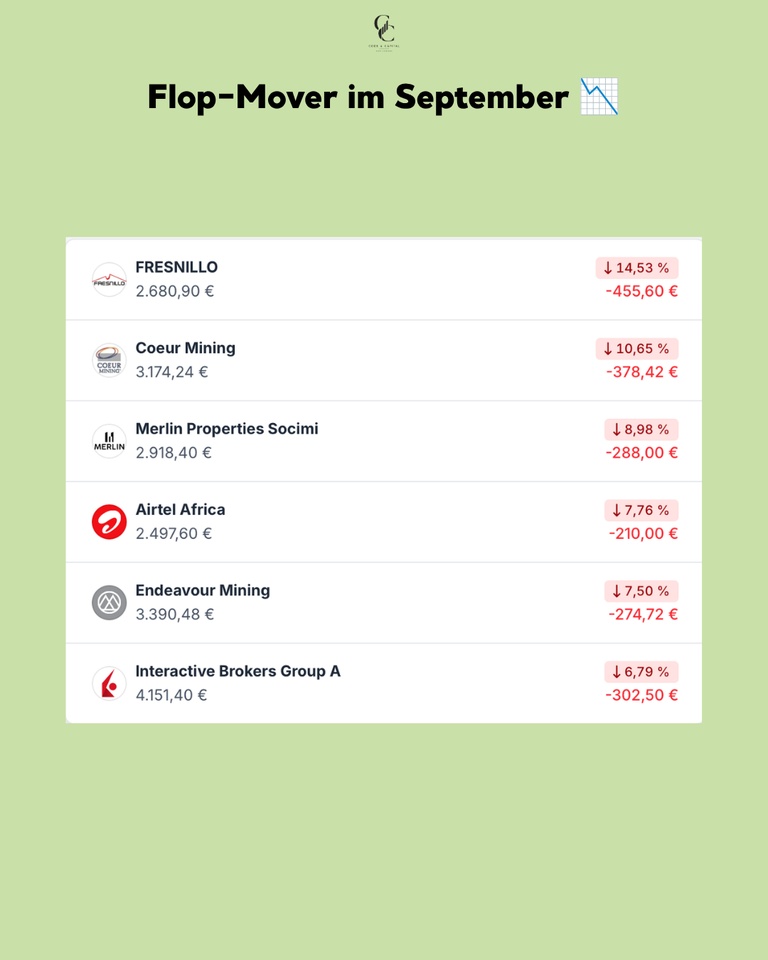
September’s Big Losers 🔴
Gold and silver declined in September, with silver falling much more sharply. Rising yields and a stronger dollar weighed on prices. Mining stocks followed suit. Fresnillo
$FRES (+0,87%) lost −14.53%, Coeur Mining
$CDE (+1,94%) −10.65%, and Endeavour Mining $EDV (+4,71%) -7.50%. In August, all three were still on the other list with gains of over 25 percent. Merlin Properties fell −8.98%, Airtel Africa
$AAF (+2,33%) down 7.76%, and Interactive Brokers
$IBKR (+0,62%) fell by 6.79%.
Rebalancing on October 1 🔄
On October 1, the third rebalancing since the start took place. I swapped out 18 of 30 positions—more than ever before. In July, it was nine.
All nine banks are out: Bankinter
$BKT (-0,11%) , CaixaBank
$CABK (-0,04%) , BBVA
$BBVA (+0%) , UniCredit
$UCG (-1,09%) , BPER
$BPE (-0,43%) , Monte dei Paschi $BMPS (+0,09%) , Banca Mediolanum
$BMED (+0,24%) , Swedbank$SWED A (-1,49%) and HSBC
$HSBA (-0,84%) . In addition, Interactive Brokers $IBKR (+0,62%) , Antofagasta $ANTO (-2,52%) , Coeur Mining
$CDE (+1,94%) , AppLovin
$APP (+5,92%) , Airtel Africa
$AAF (+2,33%) , Merlin Properties and Solaria
$SLR (+0,55%) . Investor AB
$INVE B (-0,05%) and Pershing Square
$PSH (-1,11%) are also no longer in the portfolio. So four of the six underperformers listed above are no longer in the portfolio.
Six stocks from the healthcare sector were added: Eli Lilly
$LLY (+2,64%) , Bristol-Myers
Squibb
$BMY (+1,66%) , Vertex $VRTX , Incyte
$INCY (+0,95%) , Illumina
$ILMN (-1,97%) and WuXi AppTec
$603259 . Five are from the semiconductor and storage sectors: Seagate
$STX (-4,72%) , Marvell
$MRVL (-2,04%) , Applied
Materials
$AMAT (-4,16%), Teradyne
$TER (-5,02%) and KLA
$KLAC (-3,88%) . The rest is split among Fortinet
$FTNT (-1,72%) , CF Industries
$CF (-0,3%) , Marathon Petroleum
$MPC (-2,7%) , APA
$APA (-1,2%) , Pop Mart $9992 (-2,97%) , Hong Kong Exchanges
$388 (-0,44%) and Lion Finance
$BGEO (-2,62%) .
Twelve remain: SanDisk, Micron, Western Digital, Nvidia, Lam Research, TSMC, ASML, Alphabet, Comfort Systems, Fresnillo, Endeavour and Newmont. All six of September’s top movers are included.
Two names stand out. Applied Materials and KLA I sold on July 1, up 92 and a gain of 90 percent. Now both are back in my portfolio. The model doesn’t remember what it has sold in the past. It only looks at where a stock stands in the ranking today.
Conclusion 💡
The portfolio looks different after October 1 than it did before. In September, about 41 percent was still in financial stocks; now there are two positions out of 30. Instead, 12 out of 30 are in semiconductors and memory, and six are in the healthcare sector. There’s no sector limit; the model sorts by score, not by industry. Trading won’t resume until early January.
How was your September? And did you hold onto your stocks after the pullback, or did you sell them? 👇
➡️ Every month, you’ll find the complete Wikifolio update here, along with research in between.
📈 Wikifolio $DE000LS9V052 (-0,77%)
+ 1


😄 “After earnings is before earnings” Portfolio 2036
Hello, everyone,
For a long-term portfolio, I would therefore not just look at the figures that have just been released, but directly at the next earnings season:
🔄 Portfolio 2036 – Earnings Cycle
1. What results were just released?
Revenue · EBIT · Net Income · Cash Flow · Margins · Order Intake
⬇️
2. What is management saying about the future?
Guidance · Demand · Capacity · New Products · Customers · Investments
⬇️
3. What are the leading indicators?
Orders · Book-to-bill ratio · Capacity expansion · New factories · Customer contracts · Licensing deals · Industry trends
⬇️
4. What’s next?
📅 Next quarterly report
📈 Possible change in guidance
🏭 New capacity
🤖 New applications
💾 New technologies
Earnings aren’t just a look in the rearview mirror. They’re leading indicators of whether today’s wave of investment is actually funding the technologies of tomorrow.
And that’s exactly why, in my next earnings analysis, not only highlight the numbers, but will be looking especially for new signals of the future that aren’t yet apparent in the traditional quarter-over-quarter comparison.
And for the 2030 project, I’ll also be working with my good friend @Dividendenopi
I’ve taken a look at taken a close look in detail. For the Portfolio 2036 , it contains several statements that make the Micron thesis much stronger than simply “AI needs memory.”
The most important point for me is: Micron no longer views the current memory boom as short-term HBM hype, but rather as a structural shift in computing architectures and memory demand.
🧠 Why Micron remains an attractive investment for the 2036 Portfolio
1. Memory requirements per unit of AI computing power continue to rise
For me, that’s the most important message.
Micron cites three specific drivers:
- larger AI models
longer context windows
a higher number of concurrently executed requests (concurrency)
All three increase the memory and storage capacity required per AI workload.
https://s25.q4cdn.com/621799436/files/doc_financials/2026/q4/Q4-26-Earnings-Deck.pdf
This means:
Not just more GPUs → more memory.
But also more powerful AI → a disproportionately larger amount of memory.
And that’s exactly why the memory story is so interesting for Depot 2036.
🚀 2. HBM is still in the early stages of development
Micron expects that HBM bit shipments will grow faster than conventional DRAM by 2028.
Even more importantly:
Micron has already contractually secured a large portion of its HBM capacity for 2027at significantly higher prices than last year.
And Micron is working with Nvidia on a custom HBM4E solution, which is set to be used in the next generation of GPUs and the NVLink Fusion platform.
This creates an interesting chain:
Nvidia GPU
↓
HBM4 / HBM4E
↓
Micron / SK Hynix
↓
Advantest tests increasingly complex chips
This is exactly the kind of interconnected ecosystem I’m modeling with the Depot 2036.
🔥 3. Perhaps the most important statement in the entire presentation
Micron essentially says:
Even with additional planned DRAM cleanroom capacity, there is currently no clear indication of when supply and demand will return to balance.
And according to Micron, this applies to 2027 and 2028.
This is exceptionally important.
Because normally, the memory cycle works like this:
Demand rises → Prices rise → Manufacturers invest → Overcapacity → Prices fall.
But Micron is now saying:
Demand rises → Manufacturers invest → yet supply is still expected to remain tight.
Why?
Because new DRAM fabs don’t just spring up within a year.
Micron cites the following examples:
- ID1: Wafer production Mid-2027
- ID2: Late 2028
- New DRAM factory in Japan: Late 2028
- New NAND factory in Singapore: Second half of 2028
- New York: first wafer production not until in 2030.
This creates a multi-year capacity lead.
💰 4. Even more interesting: Micron is already receiving funding for future demand
To me, this is one of the strongest arguments in favor of the 2036 portfolio.
Micron now has:
26 Strategic Customer Agreements
According to Micron’s current estimates, these contracts are expected to account for account for more than 35% of revenue by 2030 .
And:
75% of this expected revenue already has defined pricing structures.
Even more remarkable:
The customers’ financial commitments have now reached $32 billion —primarily in the form of cash deposits.
This is something entirely different from:
“We believe that demand may remain high.”
Customers are effectively saying:
“We want to secure long-term storage capacity and are willing to deposit money to do so.”
This reduces some of the traditional cyclicality of the memory market.
📈 5. Micron expects another record year in 2027
And this is where it gets particularly interesting.
Micron expects:
FY2027 = another record year
and even:
sequential revenue growth in every quarter of fiscal year 2027.
Current expectations for Q1 FY2027 are:
Micron Q1 FY27
Forecast
Revenue
$61.5 billion ±$1.5 billion
Gross Margin
approx. 86.25%
EPS
$38.15 ±$1
This is remarkable because Micron is just coming off a quarter with $54.2 billion in revenue .
Q4 → Q1:
$54.2 → $61.5 billion
and Micron expects further sequential revenue growth in fiscal year 2027.
💡 6. The memory boom is now bigger than just HBM
This is very important for my long-term thesis.
Micron’s Q4 revenue:
DRAM
$39.8 billion
NAND
$14.1 billion
And NAND, in particular, is finding a new area of application thanks to AI:
KV Cache
AI models generate massive amounts of contextual data. Micron sees this as driving additional demand for fast SSDs.
Data center SSD revenue in Q4 was already just under $10 billion —more than ten times the figure for the same quarter last year.
This is important:
AI → HBM
but at the same time:
AI → Server DRAM
AI → SSD
AI → Storage
AI → Network
AI → Power supply
AI → Cooling
This will broaden the storage boom.
🤖 7. And now Depot 2036 comes into play
In its presentation, Micron explicitly mentions future applications such as:
- Data centers
- PC
- Mobile
- Automotive
- Aerospace
- Defense
- Humanoid Robotics
- Industrial
- Consumer
I find this particularly exciting for my Depot 2036 portfolio structure.
Because if humanoid robots do indeed experience strong growth, they will need:
Sensors → Computing Power → Storage → Communication → Edge AI
This could create another major market for memory sales alongside data centers.
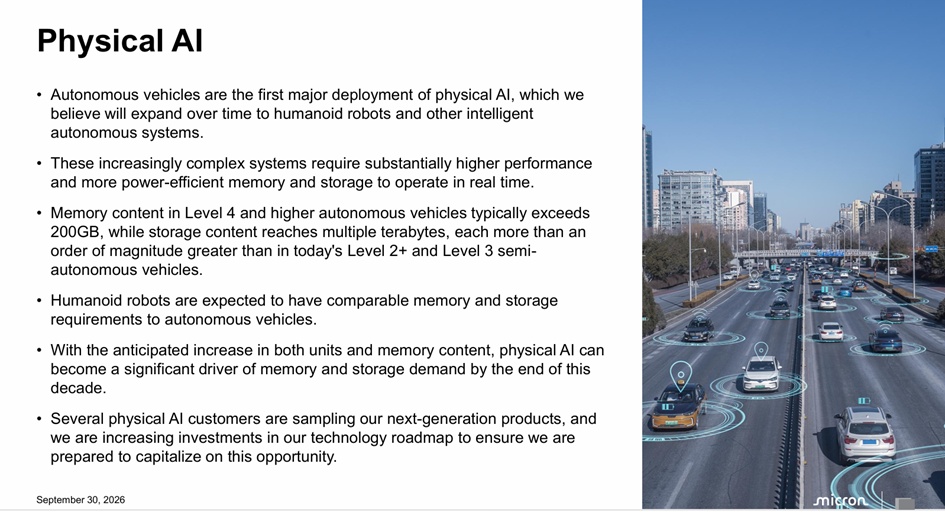
Physical AI
• Autonomous vehicles represent the first major deployment of physical AI, which we believe will expand over time to include humanoid robots and other intelligent autonomous systems.
• These increasingly complex systems require significantly higher performance and more memory-efficient storage to operate in real time.
• The memory capacity in Level 4 and higher autonomous vehicles typically exceeds 200 GB, while storage capacity reaches several terabytes—each more than an order of magnitude higher than in today’s semi-autonomous Level 2+ and 3 vehicles.
• Humanoid robots are expected to have storage and memory capacity requirements comparable to those of autonomous vehicles.
• With the expected increase in both the number of units and storage capacity, physical AI could become a major driver of storage and memory demand by the end of this decade.
• Several customers in the physical AI space are currently testing our next-generation products, and we are increasing our investment in our technology roadmap to ensure we are ready to capitalize on this opportunity.
🏭 8. Why the boom won’t simply end due to oversupply
This is the key difference from the traditional memory cycle.
Micron must invest heavily.
In FY2026 alone:
$27.4 billion in Capex
and Q1 FY2027 alone is already around $11.5 billion already budgeted.
Micron is even increasing its investments beyond previous plans because additional cleanroom capacity is needed.
But:
Capacity ≠ immediately available chips.
A new fab takes years to build.
That’s why the current cycle could last longer than previous memory booms.
🧩 My “Portfolio 2036” roadmap for Micron
Here’s how I’d view Micron at this point:
2026–2028
HBM + DRAM shortage
↓
2027–2030
AI infrastructure + HBM4/HBM4E + server memory
↓
2028–2032
Inference / KV Cache / AI Storage
↓
2030+
Physical AI / Humanoid Robots / Edge AI
↓
Long-term
Memory will become an even more strategic component of computing architecture
This goes far beyond the conventional wisdom:
“Micron will benefit from the next memory cycle.”
⚠️ But this is also where some risk lies
I will not conclude from this that:
“The memory boom can never end.”
That would be going too far.
Memory remains a cyclical industry. New capacity will eventually come onto the market. Technological changes can also alter the amount of memory required per computing operation.
And after a rise of 256% in FY26 revenue to $133.2 billion and a FY26 gross margin of 81.1%, expectations for Micron are now very high.
That’s why, for the 2036 portfolio, I’ll focus less on Micron’s current earnings and more on these metrics:
🔎 My 6 Micron Leading Indicators
Leading Indicator
What I would monitor
Significance for 2036
1. AI/Data Center
HBM, Server DRAM, AI SSDs, KV Cache
🔴 Key driver
2. New memory architectures
HBM4/HBM4E, LPDDR6, DDR6, new SSDs
🔴 Cycle Extenders
3. Physical AI / Robotics
Humanoids, Edge AI, Autonomous Systems
🔴 Potential New Mega-Market
4. Automotive
L2+/L3/L4, ADAS, autonomous driving
🟠 Structural growth driver
5. Aerospace / Defense / Industrial
Autonomous systems, sensor technology, edge computing
🟠 Diversification
6. Consumer / PC / Mobile
AI PCs, AI smartphones, on-device AI
🟡 Additional storage requirements
The key difference
In the future, I will address two questions separately :
A. How does the memory cycle work?
and
B. How fast is the structural memory content per device/system increasing?
Because exactly B is what could fundamentally change the next cycle.
🤖 Example: Humanoids
In my view, this is one of the most exciting leading indicators for the 2036 portfolio.
Micron explicitly states:
Humanoid robots require about 10 times as much memory as an average L2+ vehicle.
And Micron expects this to result in a demand cycle lasting several decades, which is set to begin in the second half of this decade.
This is on a completely different scale than:
“We’ll sell a little more DRAM this year.”
If humanoids do indeed become widespread in the millions, it will create a new memory sales market, which is still relatively small today.
And that is exactly the kind of development I’m looking at with the Depot 2036 .
🚗 The automotive sector is similarly interesting
Micron is already citing a more than five times higher memory/storage capacity compared to an average vehicle.
According to Micron, the share of L2+ and higher systems is expected to rise from over 20% this year to more than 40% by 2030 .
This means:
more autonomy → more sensors → more computing power → more memory → more storage
And after that, we may see:
L3 → L4 → L5
This means the amount of memory per vehicle could continue to rise.
🧠 Even more interesting: AI is changing the memory hierarchy
To me, this is even more important than individual end markets.
Micron now supplies SSDs for KV cache applications . At the same time, the demand for memory for AI inference and longer context windows is rising.
This leads to:
HBM
↓
DDR/LPDDR
↓
SSD / Storage
↓
KV Cache
↓
Edge Memory
In other words:
AI doesn’t just need “more memory.”
It changes the entire memory architecture.
In the long run, this could even be more valuable for Micron than today’s HBM boom.
🔥 That’s why I’m going to rephrase the Micron leading indicators a bit differently
Not just:
“Will the memory boom continue?”
but rather:
“Will memory content per computing unit, vehicle, robot, and AI system continue to rise?”
For me, that’s the key question for the Depot 2036 strategy.
For example, if:
- an AI server needs X GB of HBM in 2026,
- significantly more in 2028,
- in 2030 it requires additional storage and KV cache,
- an autonomous vehicle requires more and more memory,
- a humanoid requires many times more than a car,
- and edge AI equips additional devices with local computing power,
then the entire memory market can grow, even if individual traditional end markets stagnate.
🏗️ And this makes Micron more attractive for the 2036 portfolio
That’s why I now phrase the Micron thesis as follows:
Micron isn’t just a bet on the next memory cycle. It’s a bet that every new generation of smart machines will require more and more powerful memory.
That’s a much stronger long-term argument.
And that’s exactly why I’ll be 30 Micron , I’ll be adding a new section to every quarterly review:
“Micron Technology Leading Indicators”
featuring:
HBM4/HBM4E → AI Storage/KV Cache → AI PC → AI Mobile → Automotive/ADAS → Humanoids → Industrial/Edge AI → Aerospace/Defense
This will allow me to see early on whether Micron is actually evolving from a cyclical memory manufacturer into a structural infrastructure company riding the wave of physical and artificial intelligence.
I’ll be tracking this for the Portfolio 2036 .
🎯 And that’s why I’ll view my 30 Micron shares in Portfolio 2036 this way
Not merely as a memory stock.
But rather as:
a “pick-and-shovel” company for the increasing memory intensity of AI.
And that’s exactly why I’ve combined these positions:
Nvidia → Computing Power
Micron + SK Hynix + Kioxia → Memory & Storage
Advantest → Testing increasingly complex chips
Lumentum + Fujikura + Celestica → Optical/Network Infrastructure
Vicor → Power supply for AI systems
Vertiv → Data center/cooling/power infrastructure
For me, this has become one of the most interesting cross-connections within the 2036 portfolio.
And the new Micron presentation provides pretty strong evidence of this: Micron itself expects the structural supply shortage to last at least until 2028 and already has long-term customer contracts through 2030/31.
My friends,
Thank you for your attention.
I’m really looking forward to your comments.


Waiting Big Time Laps | Nikkei | S&P 500 | HSI
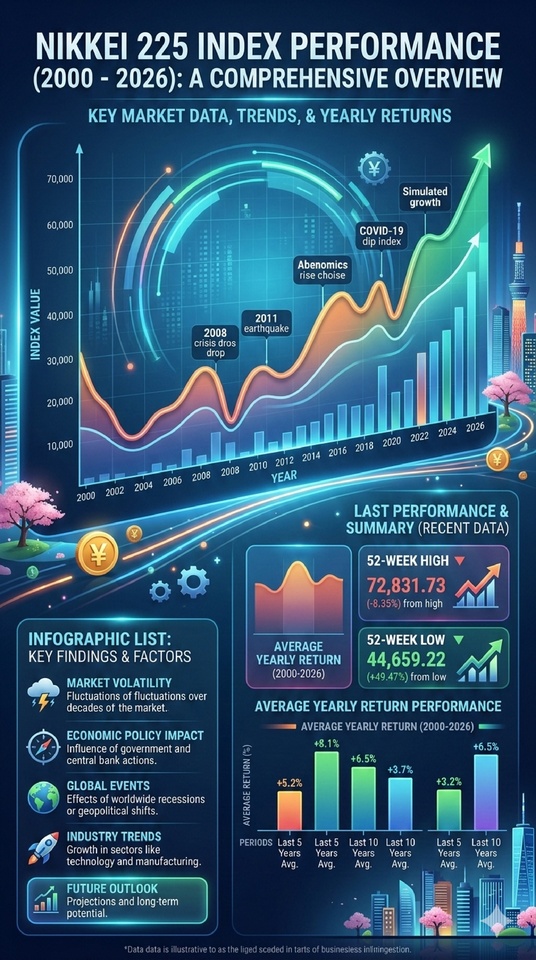
Japan Nikkei 225 index performance with in :
• 52-Week High 72,831.73 (-8.35%)
• 52-Week Low 44,659.22 (+49.47%)
■ Nikkei 225 Index ($NKY)
66,753.72 +1,272.45 (+1.94%) 09/30/26 [SPECIAL]
for Wed, Sep 30th, 2026
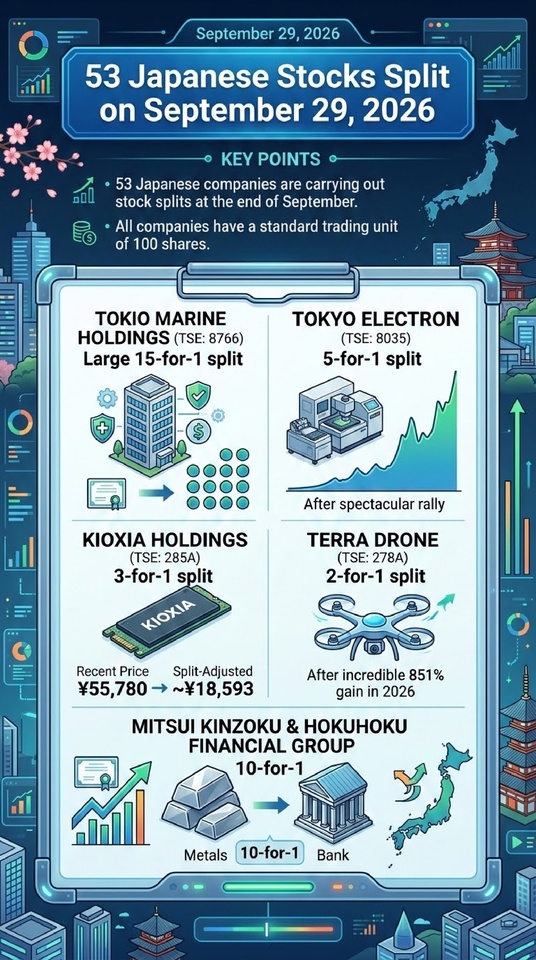
■ Split Stock on September 2026
- 53 Japanese companies are carrying out stock splits at the end of September.
■ Traditional event in frame cycle get performance every years with gap point level position and sink hole in momentum. US S&P 500 market Index | HSI | Japan Nikkei 225 Index. Which on first makes sink drop performance in Q4 season this years.
■ Economic Global Issue with Geopolitical get tension and friction from new story and momentum in market trend. There is still hot and makes point from issue internal on market strategy and frame works must be get balance in standpoint for every years with wave cycle market get average quarter return performance.
• 2025 and 2026 they have its from split stock and this is about "when and how" with market cap and market trends still works on trade meanwhile impact and effect from High Season in high level position. ✅️💫
$285A (-2,78%) , $SNDK (-1,61%) , $SMSD (-2,25%) , $HY9H (-3,9%) , $MU (+1,5%) , $ASML (-0,26%)

Micron Falls 0.9% to $1,055 After Earnings Report: Another Strong "Beat-and-Raise" Is Offset by Short-Term Margin Pressure and Higher Investments
⠀
The key takeaway: Wall Street remains clearly bullish on Micron. Analysts expect the AI-driven shortage of memory chips to persist through 2028, potentially keeping prices, margins, and earnings structurally high.
⠀
Average price target: $1,573
Potential from the current price of $1,055: ~49%
⠀
Current analyst ratings:
• Melius: Buy, $2,200 (unchanged) (+109%)
• Cantor Fitzgerald: Overweight, $2,000 (unchanged) (+90%)
• Susquehanna: Positive, $2,000 (unchanged) (+90%)
• Rosenblatt: Buy, $1,900 (up from $1,500) (+80%)
• KeyBanc: Overweight, $1,750 (unchanged) (+66%)
• Needham: Buy, $1,650 (unchanged) (+56%)
• Deutsche Bank: Buy, $1,550 (unchanged, +47%)
• Baird: Outperform, $1,520 (unchanged, +44%)
• Raymond James: Outperform, $1,500 (unchanged, +42%)
• RBC: Outperform, $1,500 (unchanged, +42%)
• Stifel: Buy, $1,500 (unchanged, +42%)
• Wells Fargo: Overweight, $1,400 (unchanged, +33%)
• Wedbush: Outperform, $1,400 (unchanged) (+33%)
• Mizuho: Outperform, $1,400 (up from $1,300) (+33%)
• Citi: Buy, $1,300 (unchanged) (+23%)
• BMO: Outperform, $1,300, unchanged (+23%)
• Goldman Sachs: Neutral, $1,250, unchanged (+18%)
• Morgan Stanley: Overweight, $1,200, unchanged (+14%)
⠀
What analysts liked:
• Q4 revenue of $54.2 billion, about 6% above consensus
• Adjusted EPS of $33.42 vs. about $31.2 expected
• Q1 revenue guidance of $61.5 billion, about 7% above Street estimates
• Q1 EPS guidance of $38.15, also well above consensus
• DRAM prices rose in the high double-digit percentage range quarter-over-quarter; NAND prices rose by about 30%
• More than 75% of production for 2027 is already committed
• Micron now has 26 long-term supply contracts, up from 16 in the previous quarter
⠀
Key takeaway: Management expects the supply-demand balance for DRAM and NAND to tighten even further in 2027 and 2028. As a result, an increasing number of analysts see a structurally stronger memory cycle than in previous boom-and-bust phases.
⠀
Why the stock isn’t rising anyway:
• The Q1 gross margin is expected to decline initially to around 86.3%
• Higher bonus payments, start-up costs for new factories, and rising investments are weighing on the stock in the short term
• FY27 capex could rise to around $55 billion or more
• Expectations were already extremely high following the massive rally
⠀
The next catalyst: Micron expects gross margins to rise again after Q1. At the same time, HBM prices are expected to be significantly higher in 2027. Starting December 9, more substantial share buybacks should also become possible once the restrictions under the CHIPS Act expire.
⠀
Conclusion: The results confirm the core Micron thesis. AI continues to drive shortages in DRAM, HBM, and NAND; long-term customer contracts increase visibility; and pricing remains exceptionally strong. The muted stock price reaction is primarily due to short-term margin pressure and very high expectations, not a slowdown in the memory cycle.

A Million with Satellit - MSCI World Momentum Champions - September 2026 Monthly Report
🚀 Month 9 since the start has also gone really well again. 🚀
So far this year, things really only went downhill from mid-June to the end of July, but over the last two months, the upward trend has continued. And yes, the 30k mark has been broken once again 😍
According to the algorithm, I was on track with Lumentum ($LITE (-2,65%) ), Kioxia ($285A (-2,78%) ), Micron ($MU (+1,5%) ), Hewlett Packard Enterprise ($HPE (-7,41%)), Recruit Holdings ($6098) (+2,43%) and Dell ($DELL (-6,89%) ). In addition, outside the algorithm, we are invested in SanDisk ($SNDK (-1,61%) ).
The starting value was around 26,300 euros. Due to capital gains tax on the sale of Western Digital ($WDC (-2,94%) ), 650 euros were lost; however, a capital inflow of 720 euros largely offset the tax.
All in all, September delivered a gain of almost exactly +15% for the satellite portfolio.
+4,000 euros in capital gains 🚀
Who was involved and how it went:
- Lumentum +11% 🚀
- Kioxia +16% 🚀
- SanDisk +16% 🚀
- Micron +15% 🚀
- Dell +21% 🚀🚀
- HPE +25% 🚀🚀
- Recruit +1% 🐌
The overall result was driven equally strongly by all of them. Only Recruit Holdings was unable to keep pace with the strength of the others.
YTD, the momentum performance now stands at a strong +110% TTWROR. 🤯😍
The analyses will now show whether there will be any changes for October. At least, that’s what I’m expecting. The analyses are underway...
Only 33 more to go until a million 🥹
Edit: Recruit Holdings is no longer in the portfolio for October. After a long wait, we now officially welcome SanDisk to the MSCI World Index—and thus directly into the portfolio (I’d already held it for a while as a precaution)—and Marvell has also made it back into the lineup. Here’s to a great October, which we’d love to see bring us the 3x.xxx,xx € mark!

IPO get spot market |Energy & Semiconductor
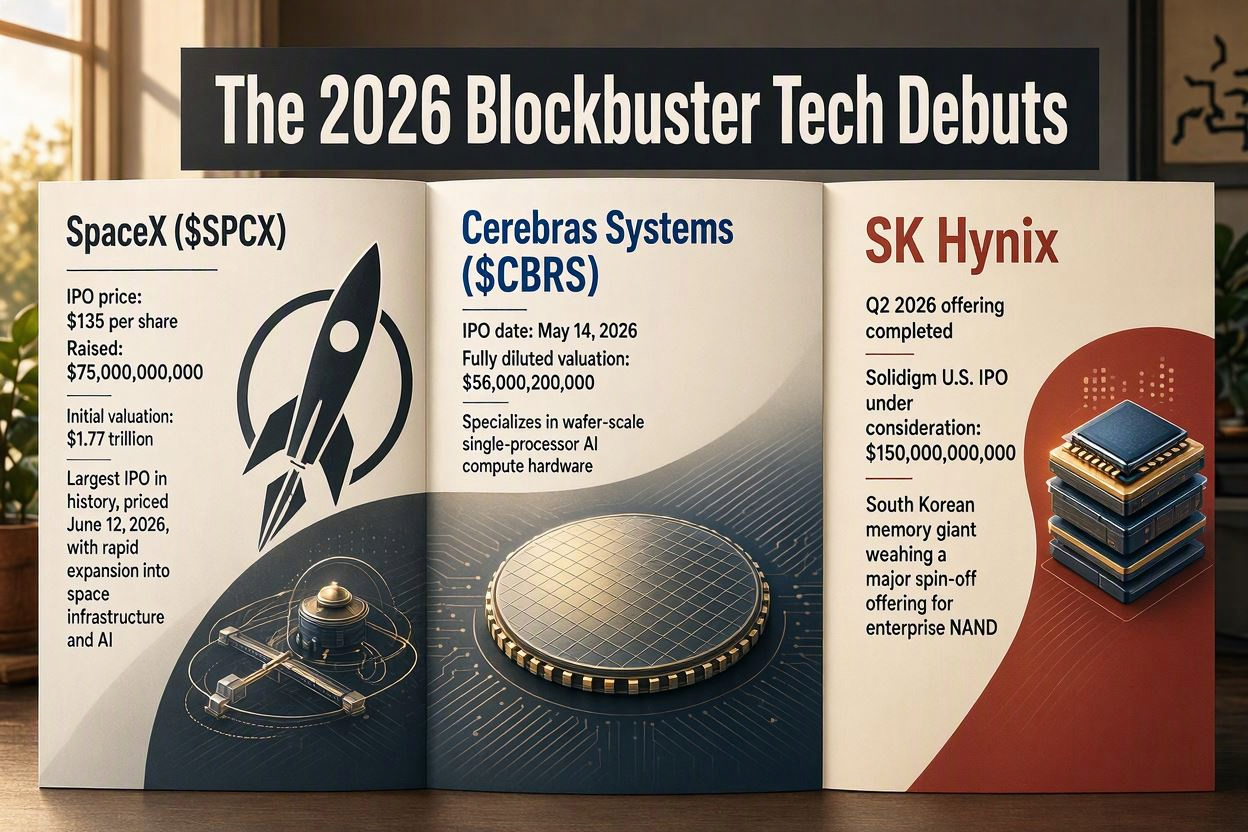
■ $SKHYX (-1,39%) , $CBRS , $SPCX (-2,4%)
• From IPO in stock market 2026 after oil makes peak top position on market cycle in traditional event every 4 years, they makes spot point to get momentum.
• Best prices to start in get market position with 90 day and starting to find market cap still have on trade market from option and ETF. ✅️⌛️
• Keep on stay to hold and get in 12 month performance with cycle time frame next years.
• Agenda Split Stock from $SNDK (-1,61%) , $LITE (-2,65%) , $STX (-4,72%) , $ASML (-0,26%) , $MU (+1,5%)
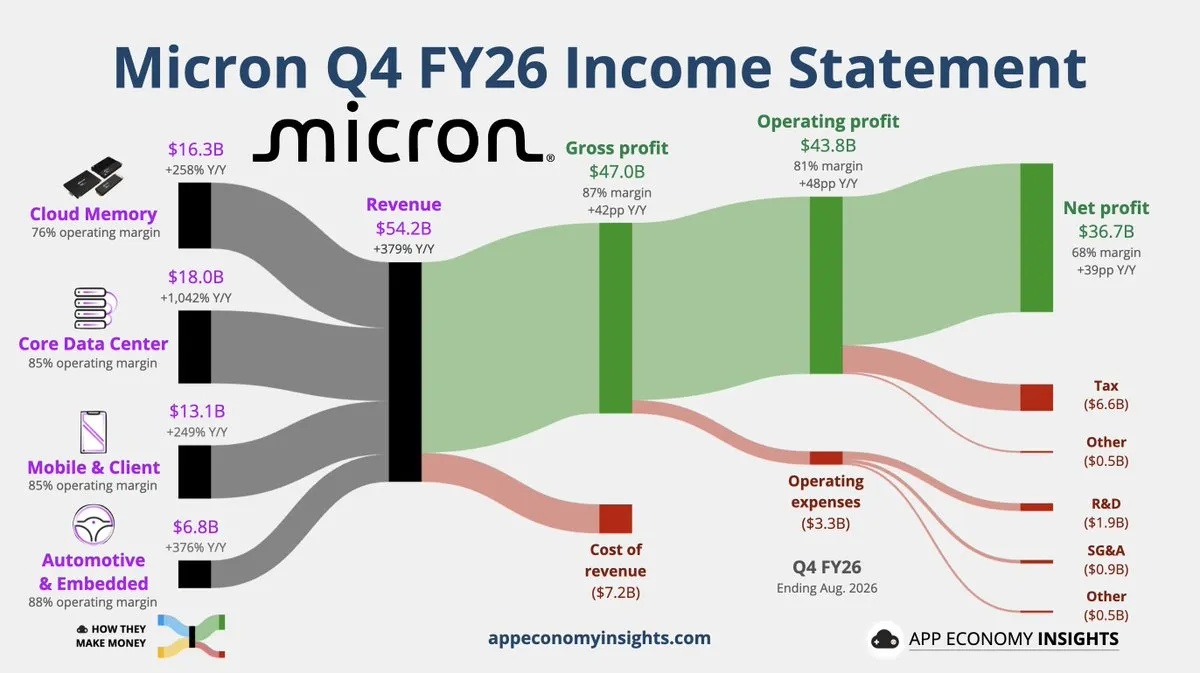

𝐌𝐢𝐜𝐫𝐨𝐧: 𝐑𝐞𝐜𝐨𝐫𝐝 𝐐𝟒 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝐚𝐧𝐝 𝐄𝐏𝐒 𝐁𝐞𝐚𝐭 𝐚𝐬 𝐀𝐈 𝐃𝐞𝐦𝐚𝐧𝐝 𝐃𝐫𝐢𝐯𝐞𝐬 𝐌𝐚𝐬𝐬𝐢𝐯𝐞 𝐆𝐫𝐨𝐰𝐭𝐡
⠀
📊 𝐑𝐞𝐬𝐮𝐥𝐭𝐬
• Adj. EPS: $33.42 (Est. $31.82) ✅
• Revenue: $54.23B (Est. $51.51B) ✅, +379% YoY.
• Adj. Gross Margin: 87.0%, vs. 45.7% a year ago.
• Adj. Operating Income: $44.64B, with an 82.3% margin.
• Operating Cash Flow: $43.97B.
• Adj. Free Cash Flow: $33.20B.
⠀
🎯 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
• Q1 FY2027 Revenue: $60.0B–$63.0B (Est. $57.93B) ✅
• Q1 FY2027 Adj. EPS: $37.15–$39.15 (Est. $35.92) ✅
• Q1 FY2027 Adj. Gross Margin: ~86.25%.
• Q1 FY2027 Adj. Operating Expenses: ~$2.06B.
⠀
📌 𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
• Q4 revenue beat consensus by ~5.3%, while Adj. EPS topped estimates by ~5.0%.
• FY2026 revenue reached a record $133.19B (Est. $130.34B), while Adj. EPS reached $75.52 (Est. $73.88).
• Q1 guidance is well above consensus on both revenue and Adj. EPS, with even the low ends of both ranges exceeding estimates.
• Core Data Center revenue reached $18.0B, while Cloud Memory revenue hit $16.3B amid surging AI-driven memory demand.
• FY2026 Adj. free cash flow reached $62.31B, while Micron ended the year with $73.48B in cash, marketable investments and restricted cash.
⠀
💬 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐂𝐨𝐦𝐦𝐞𝐧𝐭𝐚𝐫𝐲
“Micron delivered record fiscal 2026 results, and we expect an even stronger fiscal 2027.”
Títulos em alta
Principais criadores desta semana