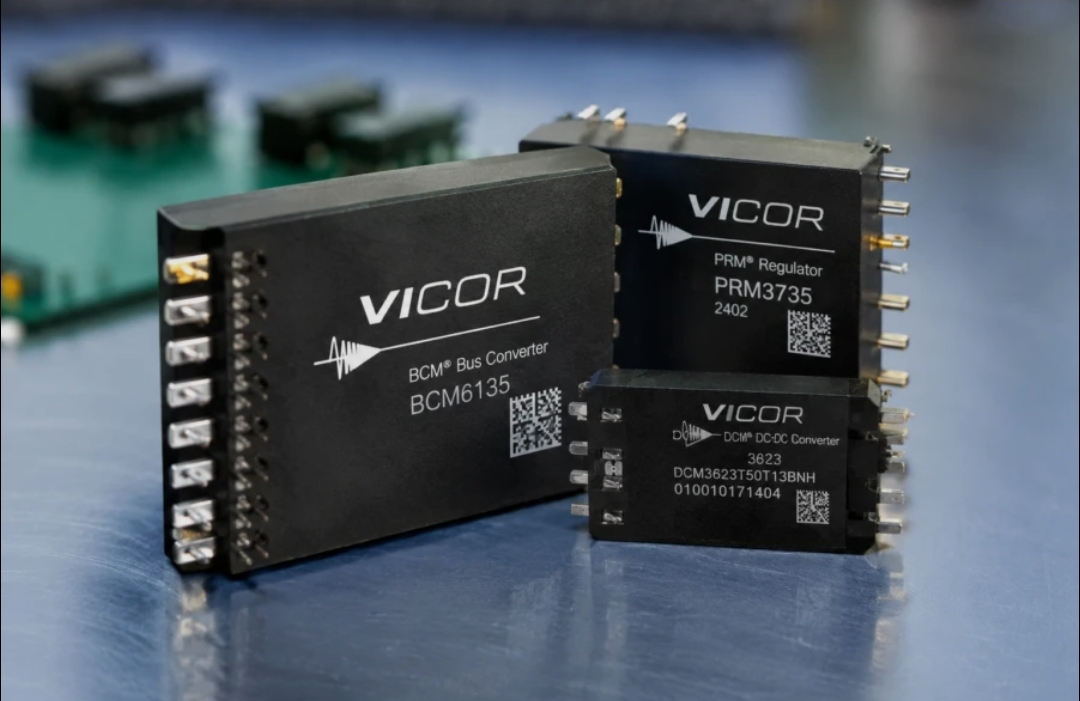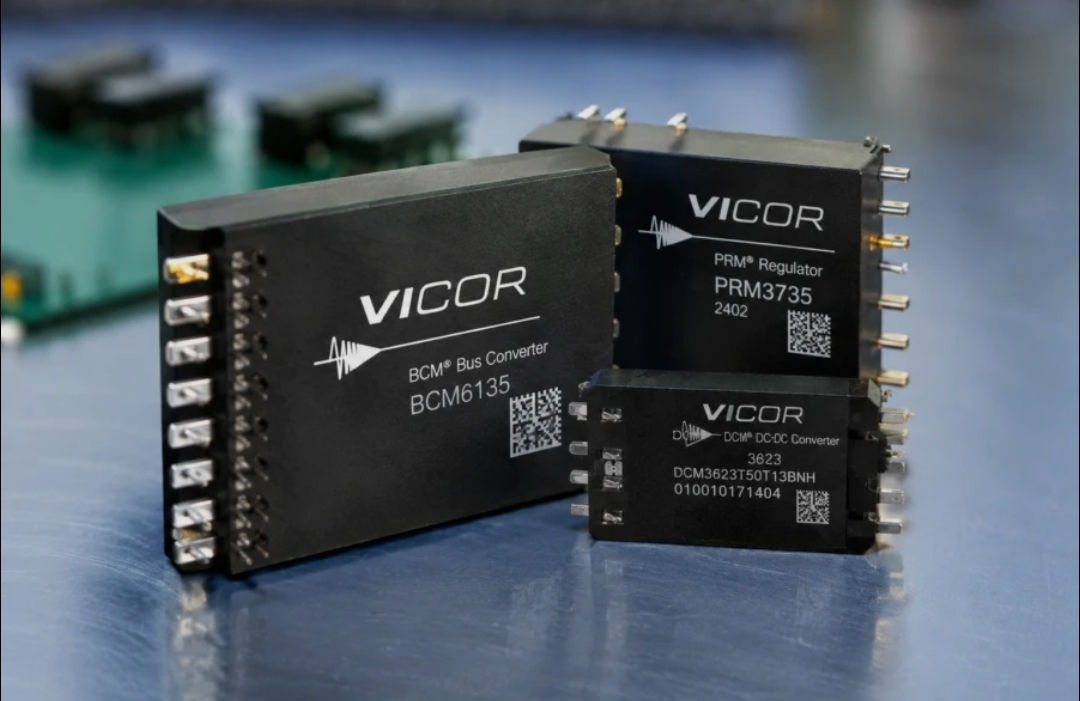

The manufacturer of modular power supply components $VICR (-15,78%) is posting impressive numbers.
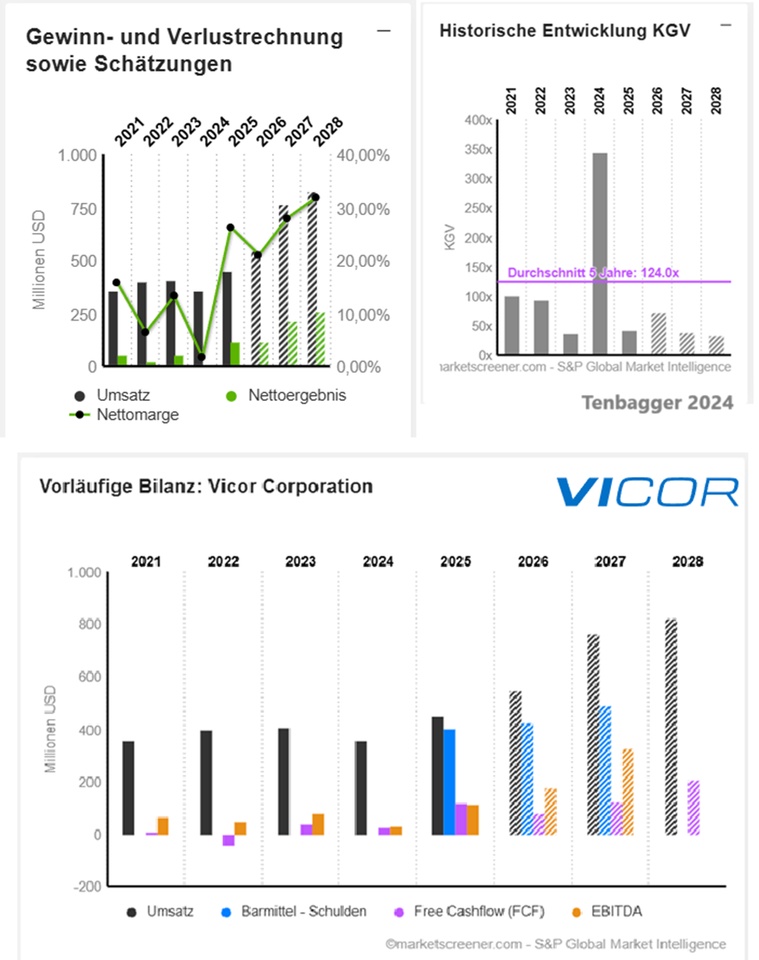
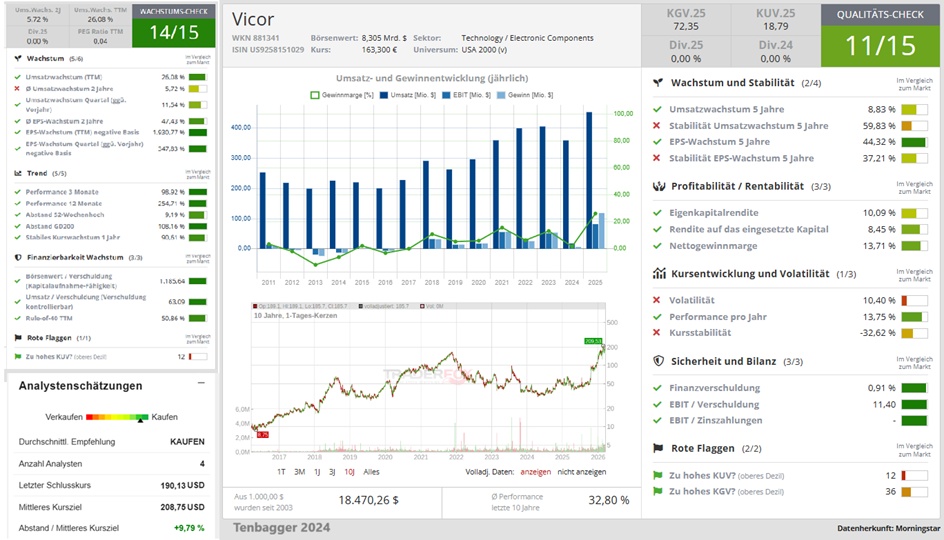
Adjusted earnings per share came in at $1.33, exceeding the market consensus of $1.29.
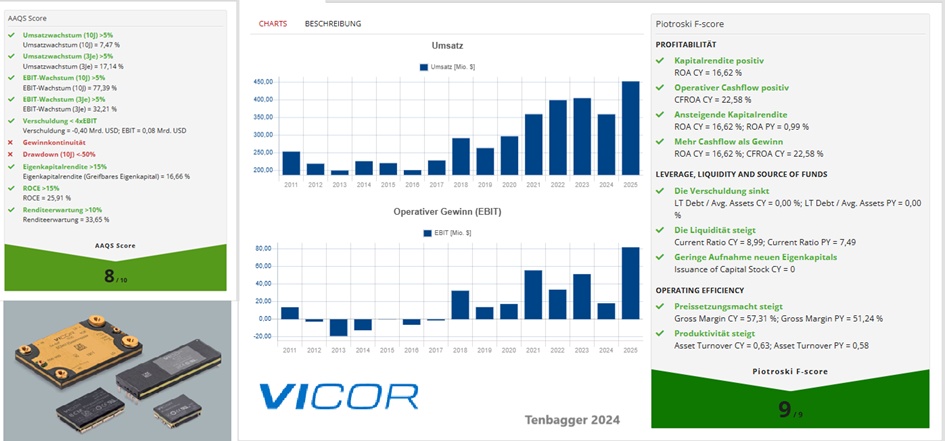
Revenue rose 78.5% year-over-year, from $110.4 million to $197.1 million, exceeding Wall Street’s forecast of $183.7 million.
Profitability was also impressive across the board:
The gross margin improved from 57.5% in the same period last year to 68.3%, while net income more than doubled to $63.3 million from $28.3 million in the third quarter of 2025.
Particularly noteworthy for growth-oriented investors: The order backlog climbed 166% year-over-year to $406 million.
This figure underscores the strong demand from customers in the AI infrastructure and high-performance computing sectors, which are driving Vicor’s licensing revenue in the Vertical Power Delivery segment.
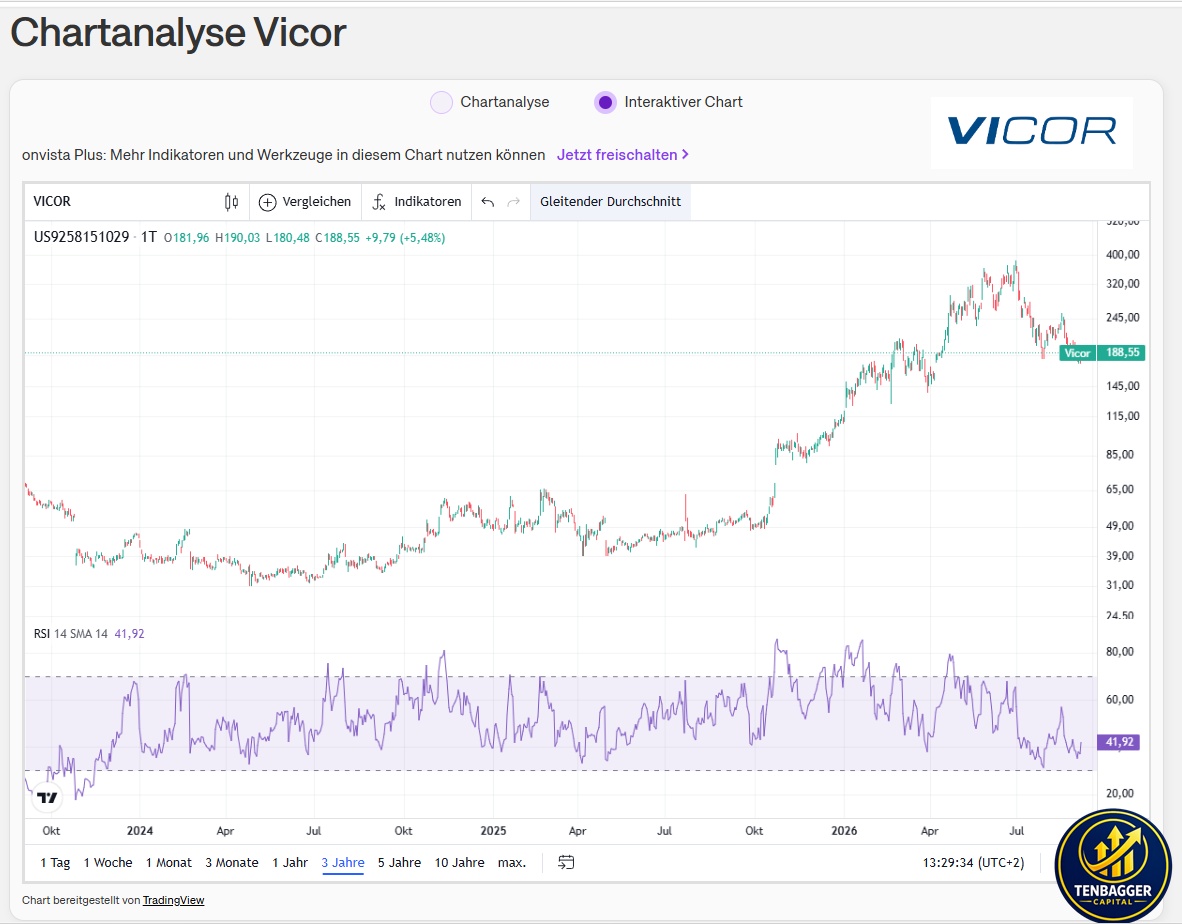
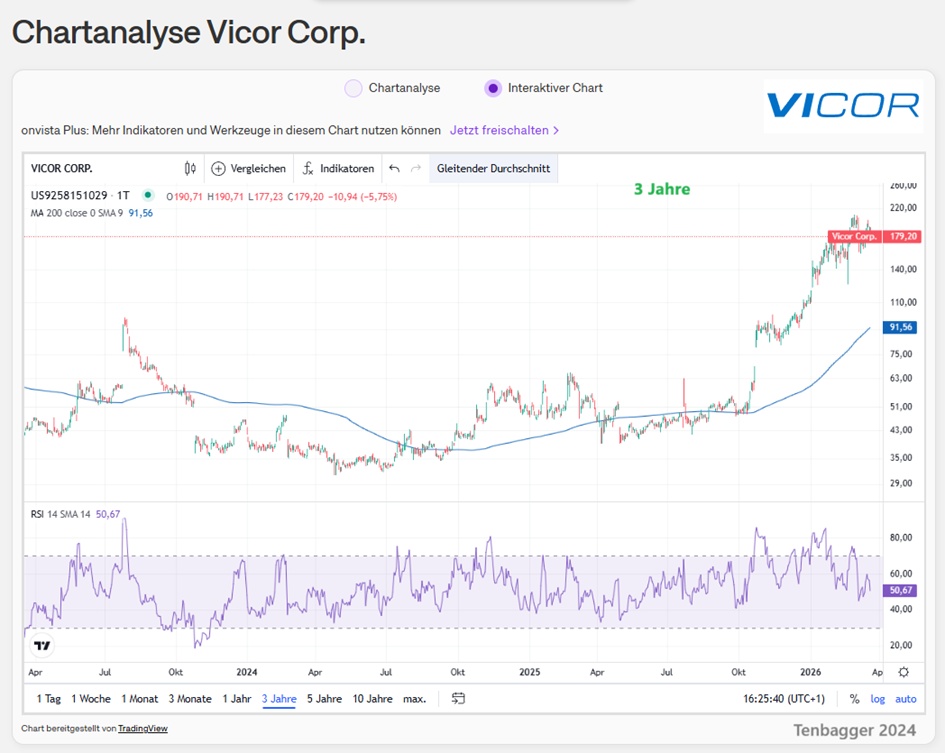
Overall, Vicor delivered an outstanding quarterly report that exceeded even the high expectations set by aggressive upward revisions. Coupled with a dynamically growing, license-based business model and a record order backlog, this gave investors solid reasons to drive the stock price significantly higher despite a subdued market environment for technology stocks.
The company reported third-quarter licensing revenue (link) of $66.61 million, up from $21.73 million in the prior year ** Reported a net income of $63.3 million
for the third quarter, or $1.33 per share, compared to $49.8 million, or $1.04 per share, in the prior year ** The order backlog rose 166 percent to $406 million in the third quarter, indicating strong demand ** All five brokerages rate the stock “Buy” or higher