

Hello, everyone,
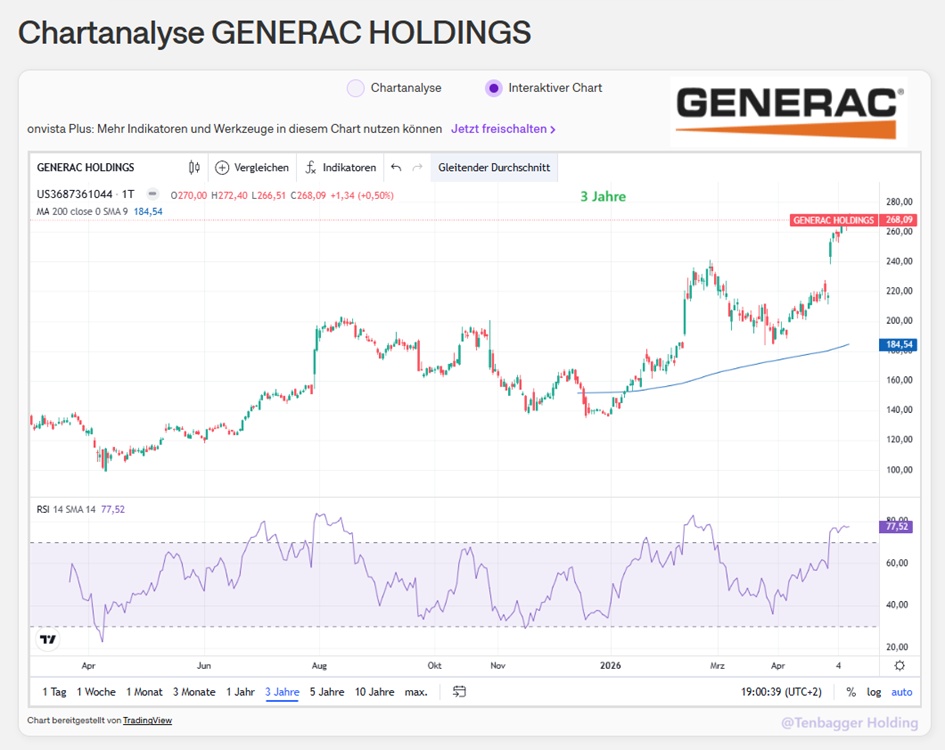
Today I took my first step with Generac $GNRC (+1,33%) .
I think I’ve already shared my reasons for doing this here a few times.
Otherwise, feel free to ask questions in the comments.

Postos
14Hello, everyone,
Today I took my first step with Generac $GNRC (+1,33%) .
I think I’ve already shared my reasons for doing this here a few times.
Otherwise, feel free to ask questions in the comments.

Hi, everyone! ☕🍁
When the weather outside gets gloomy and we cozy up in the sunroom with a freshly brewed cup of coffee, that’s when our analysis computers really start to heat up.
As many of you know, I’m working with the lovely @Tenbagger-Capital and our @Dividendenopi put our heads together regularly.
Together with other resourceful sleuths here in the community, we’ve made it our mission to uncover new trends and sectors early on.
Why do we active folks go to all this trouble and spend nights poring over annual reports?
It’s simple: We want to feed this forum with real, well-researched facts, rather than just throwing the latest hype buzzwords at you.
Anyone can shout “AI” or “electricity demand” these days—but who really benefits in the end without their portfolio going up in flames?
That’s exactly why we’ve taken a ruthless look at the current boom sector surrounding energy, electrification, and data centers.
We’ve put five companies—all of which, at first glance, look like the perfect future winners—through our rigorous analysis.
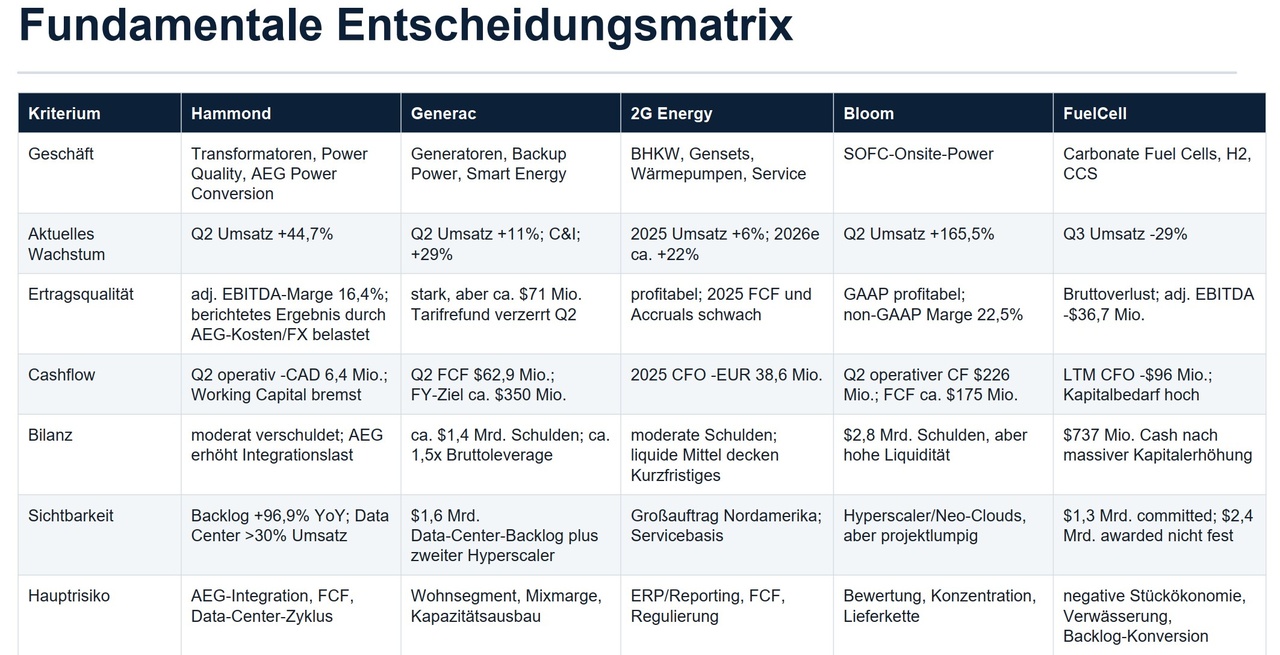
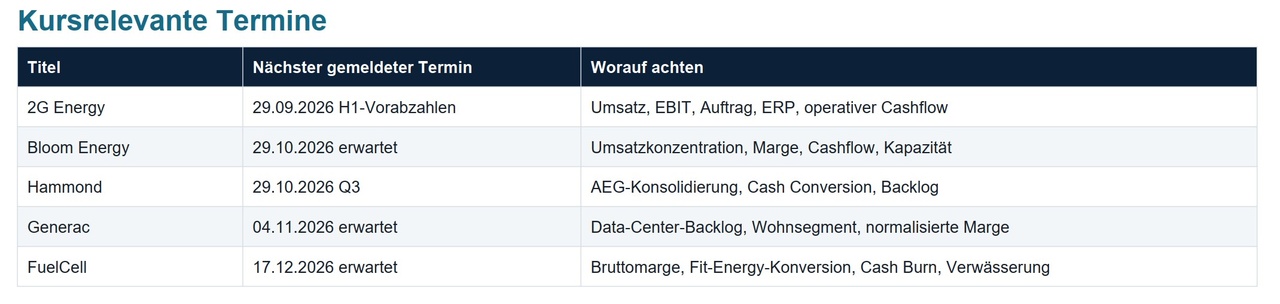
Here’s our showdown of the energy winners—and the result, which shows that revenue growth is by no means everything:
In the end, the ranking turned out as follows:
1. Hammond Power Solutions $HPS.A (-2,26%)
Hammond delivered the most compelling combination overall. Particularly strong were its high revenue growth, its order backlog that nearly doubled, and its positioning in transformers, power quality, and data centers. At the same time, the company is already profitable and backed by solid results to a much greater extent than some of the more speculative candidates.
However, Hammond is not without its question marks. Operating cash flow has been weak recently, the integration of AEG still needs to run smoothly, and the now-high proportion of the data center business also increases cyclicality. Nevertheless, Hammond was the strongest candidate overall.
2. Generac $GNRC (+1,33%)
Generac follows closely behind. Particularly positive factors include the rapidly growing commercial and industrial segment, the data center backlog of approximately $1.6 billion, and several hyperscaler contracts.
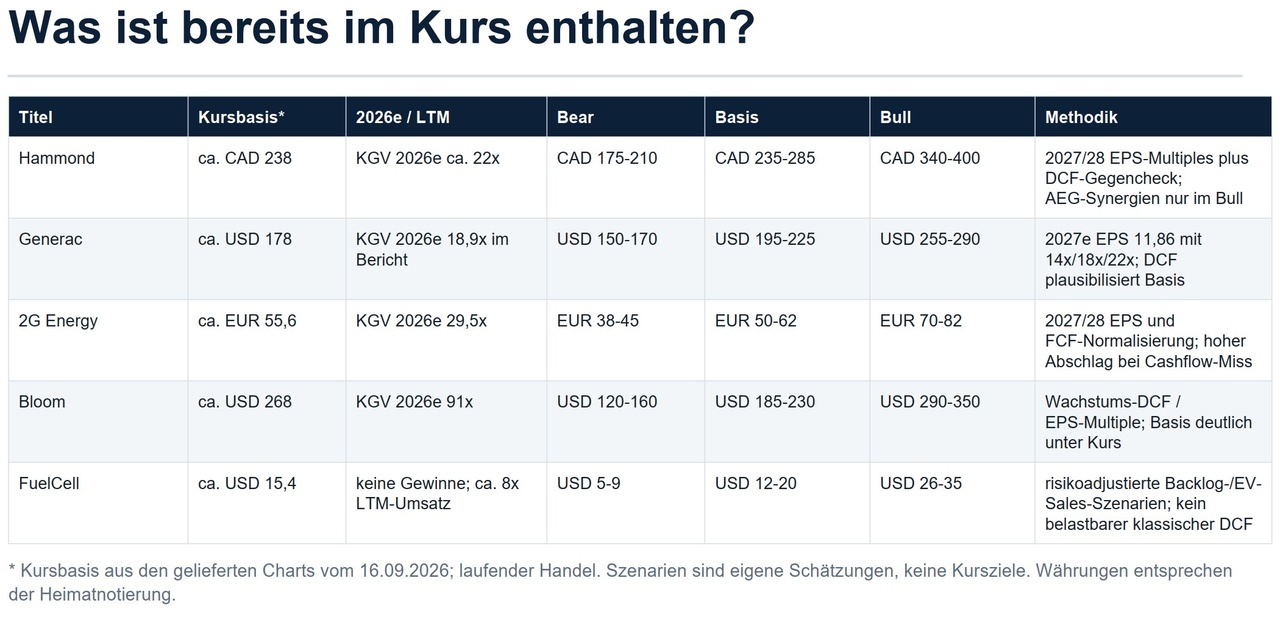
The key advantage over some other candidates is its valuation. Despite improved growth prospects, Generac is valued significantly more reasonably.
However, one had to look more closely at the most recent quarterly figures: Part of the sharp jump in earnings came from a one-time tariff refund. On a normalized basis, the margin looks somewhat less spectacular. Nevertheless, Generac remains a very interesting candidate due to its valuation, order backlog, and multiple revenue streams.
3. 2G Energy $2GB (+0,91%)
2G Energy comes in third place. Its business model, centered on decentralized energy supply, gensets, combined heat and power (CHP) plants, service, and, increasingly, heat pumps, is fundamentally attractive. Added to this is a major North American data center contract that could drive significant growth in the coming years.
The main reason for its third-place ranking is cash flow. In 2025, operating cash flow was significantly negative, even though the company was profitable. Furthermore, the ERP transition and delayed reporting are currently complicating the valuation. Therefore, 2G remains an interesting prospect but must first confirm the expected jump in earnings and cash flow.
4. Bloom Energy $BE (+2,26%)
Bloom is likely the most spectacular company of the five from an operational standpoint. Revenue growth recently exceeded 160%; at the same time, the company achieved quarterly revenue of more than $1 billion for the first time, along with positive operating income and strong operating cash flow.
The problem isn’t the business itself, but the valuation. With an expected price-to-earnings ratio of around 91 and a stock that has risen several hundred percent within a year, a great deal of success is already priced in. Added to this are project concentration, supply chain risks, and high expectations for further scaling.
Bloom is therefore fascinating from a technological and operational standpoint, but it has a significantly smaller margin of safety compared to the first three candidates.
5. FuelCell Energy $FCEL (-2,81%)
FuelCell Energy is clearly bringing up the rear.
The technology is interesting, and the company has relevant partners in Siemens and ExxonMobil. The pipeline and reported backlog also look impressive at first glance.
The problem, however, lies in profitability. Production continues to operate at a loss, capital expenditure is high, and a significant portion of the additional backlog is not yet binding. Added to this is significant dilution resulting from capital increases.
FuelCell must therefore first prove that technological demand can indeed give rise to a sustainably profitable business model.
Our Conclusion from the Comparison
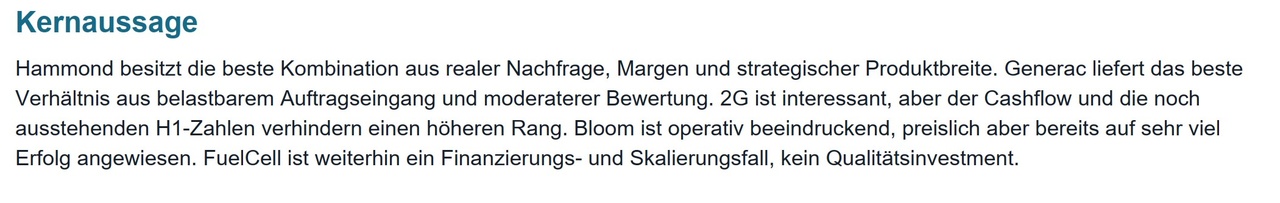
At first glance, all five companies appear to be set to benefit from rising electricity demand, electrification, and the data center boom. However, the comparison shows quite clearly just how different their quality and risk profiles actually are.
Hammond Power Solutions comes out on top in terms of the overall package of growth, profitability, order quality, and long-term electrification demand.
Generac is particularly impressive in terms of the balance between valuation and future order potential and trails only slightly behind.
2G Energy has an interesting industrial growth story, but still needs to prove that the expected growth spurt will translate directly into cash flow.
Bloom Energy currently has the most impressive operational momentum, but at the same time is also the candidate for which the market is already anticipating the most future success.
And as for FuelCell Energy , the story isn’t quite there yet. What’s missing here, above all, are positive unit economics, robust profitability, and lower capital requirements.
So, our final ranking is:
1. Hammond Power Solutions
2. Generac
3. 2G Energy
4. Bloom Energy
5. FuelCell Energy
What I found particularly interesting was that the company with the highest revenue growth rate doesn’t automatically rank first. Once valuation, cash flow, balance sheet, and execution risk are factored in, the picture shifts—in some cases, quite significantly. That’s exactly why the direct comparison of the five companies was quite revealing.
Good morning, everyone,
It’s just amazing how well collaboration between users can work.
Even though there are unfortunately sometimes only a few comments on my presentations, behind the scenes, the exchange with key users is getting better and better.
Yesterday with Generac $GNRC (+1,33%) you could clearly see that we had already analyzed exciting stocks ahead of a breakout.
With my last stock pick, Hammond $HPS.A (-2,26%) it could be the same story,
(not an investment recommendation, just my personal opinion)
But the stock I’d like to introduce to you today was also discussed and analyzed among us beforehand. And sure enough, yesterday brought the good news we’d been waiting for.
Thanks to my friend @Raketentoni reminded me once again of this IPO stock, which I’d initially put on my watchlist because the IPO price was too high—and which I’d naturally lost sight of here.
Since the news triggered a great surge yesterday, I naturally brought @Dividendenopi jumped on board. I appreciate his expertise and foresight more and more.
And so it has been—and continues to be—a wonderful collaboration between the three of us.
“The Crazy Trio”
We look forward to plenty of comments on $INIO (-0,17%) Innio
👉 The INNIO IPO took place in early June 2026, with the official pricing on June 4, 2026.
INNIO Stock: Major Order for U.S. Data Centers and Rating Upgrade Drive Share Price Surge
⚡ INNIO Stock –
🔋 Major order
💼 Rating upgrade
📈 Market Environment
💡 Conclusion
INNIO is positioning itself as a a leading provider of decentralized energy solutions for AI infrastructure. The report points to sustainable growth potential and improved creditworthiness — a clear boost to investor confidence.
Innio NV is a Germany-based provider of decentralized energy solutions that supplies electricity. The company develops, manufactures, and maintains power systems under the Jenbacher and Waukesha brands. It supplies electricity for applications such as data centers, microgrids, grid stabilization, industrial power supply, and gas compression.
Number of employees: 5,467
As of December 31, 2025, INNIO has a global presence in approximately 100 countries, supported by a resilient, high-margin services business that generates long-term, recurring revenue throughout the entire equipment lifecycle. As demand for electricity accelerates—driven by AI, electrification, and grid constraints—INNIO enables scalable, behind-the-meter power generation with high efficiency, rapid startup capability, strong transient performance, and fuel flexibility, including hydrogen-compatible solutions.
INNIO plans a $300 million expansion of its Wisconsin facility, creating 500 jobs
⚙️ INNIO Expands Wisconsin Facility
🔋 Goals of the expansion
🏭 Location and Employment
🌍 Company Profile
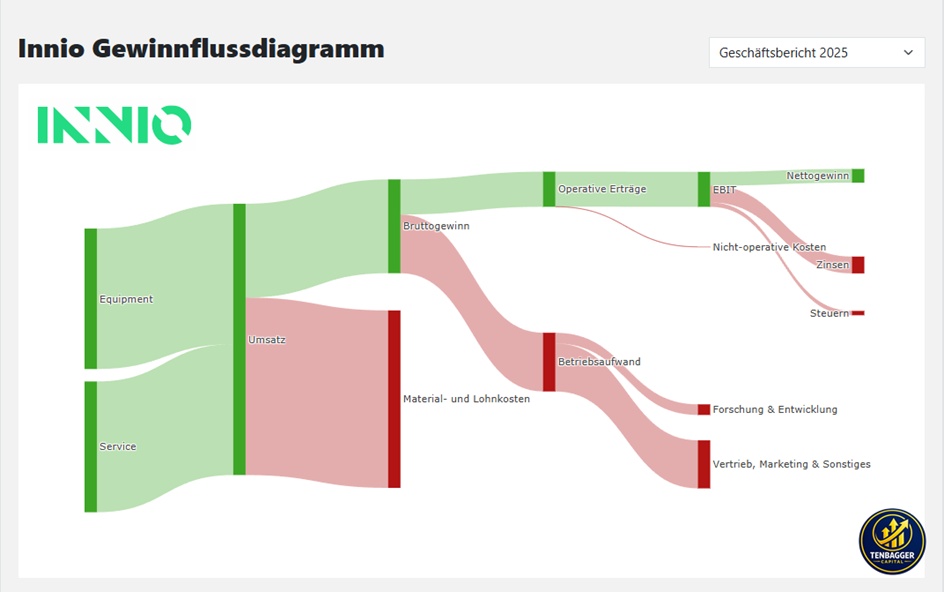
INNIO’s First Annual Report: A Test of the Growth Story in the Data Center Market
⭐ INNIO – First Annual Report Following the IPO (Q2 2026)
Date: July 27, 2026 Source: Investing.com
📌 Key Takeaway
INNIO releases its first quarterly report as a publicly traded company . The report is seen as testto see whether the major growth story in the data center market is viable.
📈 Expected Results (Q2 2026)
🔋 Strategic positioning
INNIO is benefiting greatly from:
📦 Order Book & Backlog
🏭 Capacity expansion
INNIO Q2 2026 Earnings Presentation
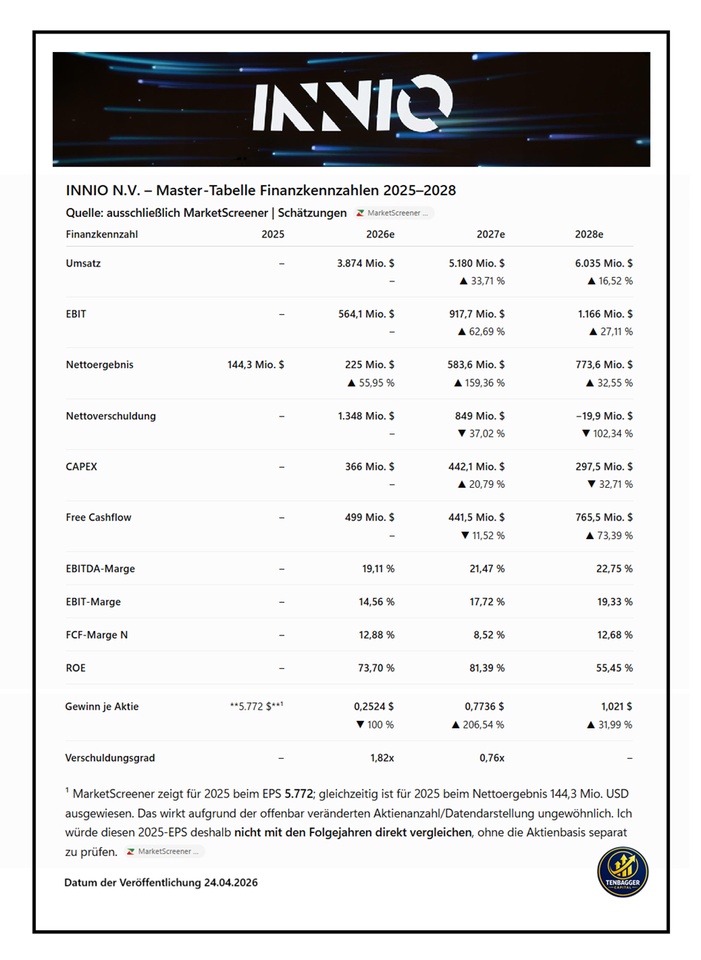
🔎 Development at a Glance
Revenue:
From 2026e to 2028e, revenue is expected to rise from $3.874 billion to $6.035 billion. This represents very dynamic growth, with the growth rate slowing from 33.71% to 16.52% .
Profitability:
The margin trend is particularly striking. The EBIT margin rises from 14.56% (2026) to 19.33% (2028), while the EBITDA margin rises from 19.11% to 22.75% .
Profit:
Net income is expected to rise from $225 million in 2026 to $773.6 million in 2028 . The biggest jump is expected in 2027, with +159.36% .
Debt:
According to the forecast, net debt will decline from $1.348 billion in 2026 to $849 million in 2027 and will even reach −$19.9 million —which would mean that INNIO would, on paper, achieve a net cash position.
Free Cash Flow:
In 2027, there will initially be a decline from $499 million to $441.5 million, before a significant jump to $765.5 million is projected for 2028. At the same time, CAPEX will fall to $297.5 million.
In short: MarketScreener’s estimates paint a scenario for INNIO through 2028 featuring strong revenue growth + significantly rising margins + rapidly growing profits + substantial debt reduction. The key points to watch here are, in particular, the realization of the high profit growth assumptions and the expected jump in FCF for 2028.
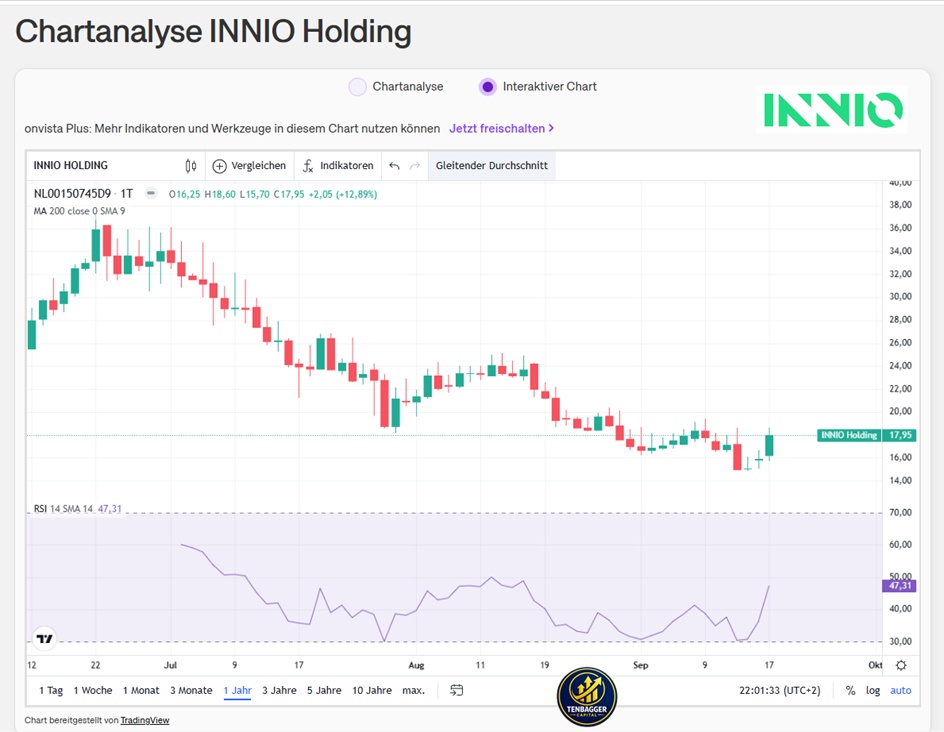
🔎 Performance
September 18, 2026, 8:55:05 a.m. •
Lang & Schwarz (EUR)
17.90 EUR
+ 2

Good morning, everyone,
It’s just amazing how well collaboration between users can work.
Even though there are unfortunately sometimes only a few comments on my presentations, behind the scenes, the exchange with key users is getting better and better.
Yesterday with Generac $GNRC (+1,33%) you could clearly see that we had already analyzed exciting stocks ahead of a breakout.
With my last stock pick, Hammond $HPS.A (-2,26%) it could be the same story,
(not an investment recommendation, just my personal opinion)
But the stock I’d like to introduce to you today was also discussed and analyzed among us beforehand. And sure enough, yesterday brought the good news we’d been waiting for.
Thanks to my friend @Raketentoni reminded me once again of this IPO stock, which I’d initially put on my watchlist because the IPO price was too high—and which I’d naturally lost sight of here.
Since the news triggered a great surge yesterday, I naturally brought @Dividendenopi jumped on board. I appreciate his expertise and foresight more and more.
And so it has been—and continues to be—a wonderful collaboration between the three of us.
“The Crazy Trio”
We look forward to plenty of comments on $INIO (-0,17%) Innio
👉 The INNIO IPO took place in early June 2026, with the official pricing on June 4, 2026.
INNIO Stock: Major Order for U.S. Data Centers and Rating Upgrade Drive Share Price Surge
⚡ INNIO Stock –
🔋 Major order
💼 Rating upgrade
📈 Market Environment
💡 Conclusion
INNIO is positioning itself as a a leading provider of decentralized energy solutions for AI infrastructure. The report points to sustainable growth potential and improved creditworthiness — a clear boost to investor confidence.
Innio NV is a Germany-based provider of decentralized energy solutions that supplies electricity. The company develops, manufactures, and maintains power systems under the Jenbacher and Waukesha brands. It supplies electricity for applications such as data centers, microgrids, grid stabilization, industrial power supply, and gas compression.
Number of employees: 5,467
As of December 31, 2025, INNIO has a global presence in approximately 100 countries, supported by a resilient, high-margin services business that generates long-term, recurring revenue throughout the entire equipment lifecycle. As demand for electricity accelerates—driven by AI, electrification, and grid constraints—INNIO enables scalable, behind-the-meter power generation with high efficiency, rapid startup capability, strong transient performance, and fuel flexibility, including hydrogen-compatible solutions.
INNIO plans a $300 million expansion of its Wisconsin facility, creating 500 jobs
⚙️ INNIO Expands Wisconsin Facility
🔋 Goals of the expansion
🏭 Location and Employment
🌍 Company Profile
INNIO’s First Annual Report: A Test of the Growth Story in the Data Center Market
⭐ INNIO – First Annual Report Following the IPO (Q2 2026)
Date: July 27, 2026 Source: Investing.com
📌 Key Takeaway
INNIO releases its first quarterly report as a publicly traded company . The report is seen as testto see whether the major growth story in the data center market is viable.
📈 Expected Results (Q2 2026)
🔋 Strategic positioning
INNIO is benefiting greatly from:
📦 Order Book & Backlog
🏭 Capacity expansion
INNIO Q2 2026 Earnings Presentation
🔎 Development at a Glance
Revenue:
From 2026e to 2028e, revenue is expected to rise from $3.874 billion to $6.035 billion. This represents very dynamic growth, with the growth rate slowing from 33.71% to 16.52% .
Profitability:
The margin trend is particularly striking. The EBIT margin rises from 14.56% (2026) to 19.33% (2028), while the EBITDA margin rises from 19.11% to 22.75% .
Profit:
Net income is expected to rise from $225 million in 2026 to $773.6 million in 2028 . The biggest jump is expected in 2027, with +159.36% .
Debt:
According to the forecast, net debt will decline from $1.348 billion in 2026 to $849 million in 2027 and will even reach −$19.9 million —which would mean that INNIO would, on paper, achieve a net cash position.
Free Cash Flow:
In 2027, there will initially be a decline from $499 million to $441.5 million, before a significant jump to $765.5 million is projected for 2028. At the same time, CAPEX will fall to $297.5 million.
In short: MarketScreener’s estimates paint a scenario for INNIO through 2028 featuring strong revenue growth + significantly rising margins + rapidly growing profits + substantial debt reduction. The key points to watch here are, in particular, the realization of the high profit growth assumptions and the expected jump in FCF for 2028.
🔎 Performance
September 18, 2026, 8:55:05 a.m. •
Lang & Schwarz (EUR)
17.90 EUR
+ 2

Hello, everyone,
Yesterday, our dear @Raketentoni a comparison of energy stocks.
Among others, the top pick of the day $GNRC (+1,33%) Generac.
But the stock we’d like to introduce to you today was also included. This stock might surprise you just as much as Generac.
@Raketentoni will be collaborating with me and will present his agents’ analysis to you once again in a repost.
Thank you very much in advance for this.
As always, we look forward to hearing your opinions in the comments.
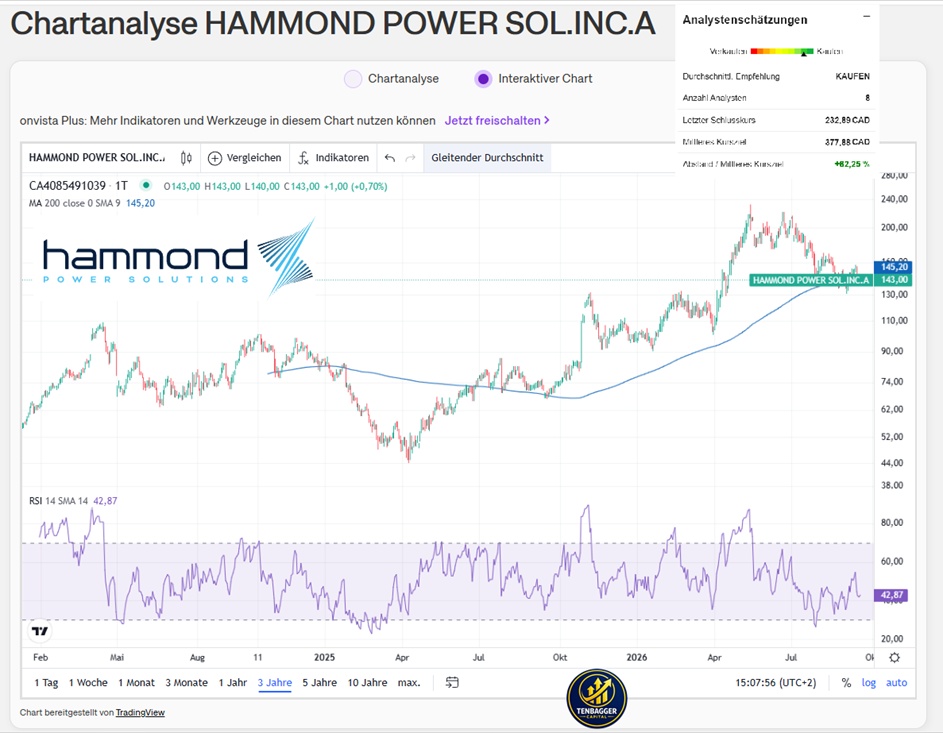
Hammond Power Solutions Inc. is a manufacturer of dry-type transformers in North America. It was founded in Ontario in 1917. The company develops and manufactures a range of standard and custom transformers, which are exported worldwide as electrical equipment and systems. Its product categories include control and automation products, low-voltage distribution products, medium-voltage distribution products, power quality products, as well as filters and specialty products. Control and automation products include control transformers, isolation transformers for drives, and chokes. The company serves robust industries such as oil and gas, mining, steel, waste and water treatment, commercial construction, data centers, and wind power generation. In addition, it offers “Integrated Electrical Solutions” (IES), a business unit focused on providing more comprehensive system-level solutions. The company has manufacturing facilities in Canada, the United States, Mexico, and India, and distributes its products worldwide.
Number of employees: 2,121
The acquisition of AEG Power Solutions by Hammond Power Solutions (HPS) is strategically very interesting from an investor’s perspective:
Product expansion:
AEG brings strong power electronics expertise (UPS, PCS, industrial power conversion). This allows HPS to expand its portfolio beyond traditional transformers.
Positive—strengthens technological depth
End-market diversification:
Access to sectors such as offshore wind, hydrogen, nuclear, data & IT, and rail.
Very positive – future markets
Geographic expansion:
HPS has traditionally had a strong presence in North America (≈ 96% of revenue). AEG opens up Europe, MEA, and APAC.
Transformative – true globalization
Aftermarket & Services:
AEG has an installed base with a high proportion of service revenue (≈ 41% of revenue). This increases recurring revenue.
Stability booster
Financial Impact:
The transaction (≈ CAD 365 million, all-cash) is expected to be EPS-accretive starting in Year 1; leverage is 2.7×, but strong FCF allows for rapid deleveraging.
Financially Sound
Integration:
Management retention, cultural preservation, phased integration.
Disciplined—low integration risk
💡 Investor Takeaway
🔋 Conclusion
The acquisition is strategically excellent and should catapult HPS into the league of global power-quality leaders in the medium term. For you as an investor: a clear step toward a “compounder story” with a growing service base and exposure to megatrends such as the energy transition and electrification.
Hammond Power Solutions Inc. schließt die Übernahme von AEG Power Solutions ab
Veröffentlichungsdatum: 29. Juni 2026
Allgemeine NachrichtenInvestor Relations
Geographic Revenue Breakdown:
2025 (CAD)
United States & Mexico 632 million
Canada 234 million
India 32.35 million
HPS-AEG-INVESTOR-PRESENTATION.pdf
Q2 2026
Finanzergebnisse des zweiten Quartals 2026
Veröffentlichungsdatum: 30. Juli 2026
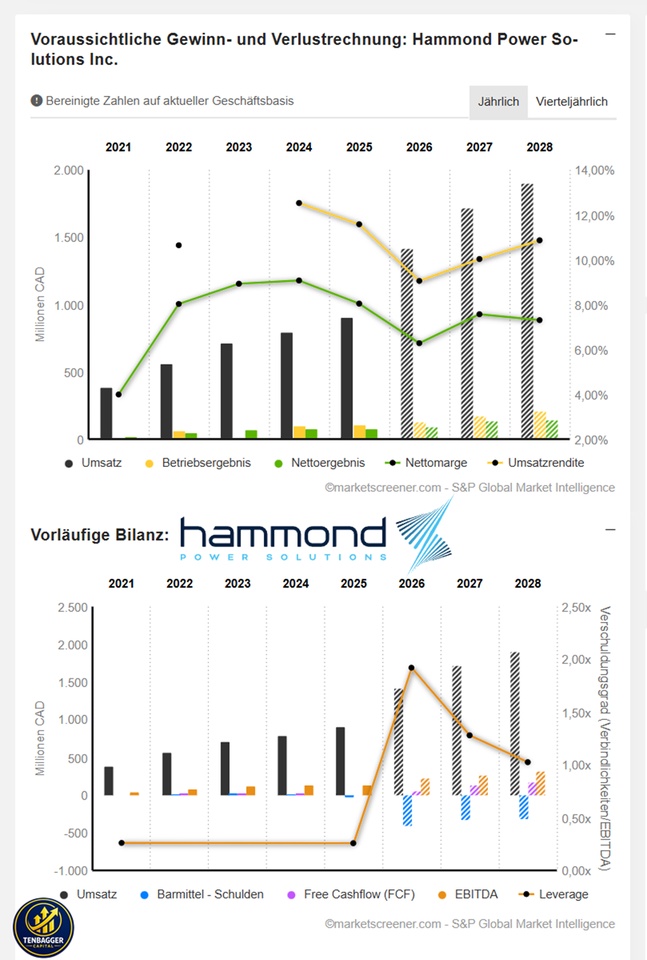
🔎 Performance at a Glance
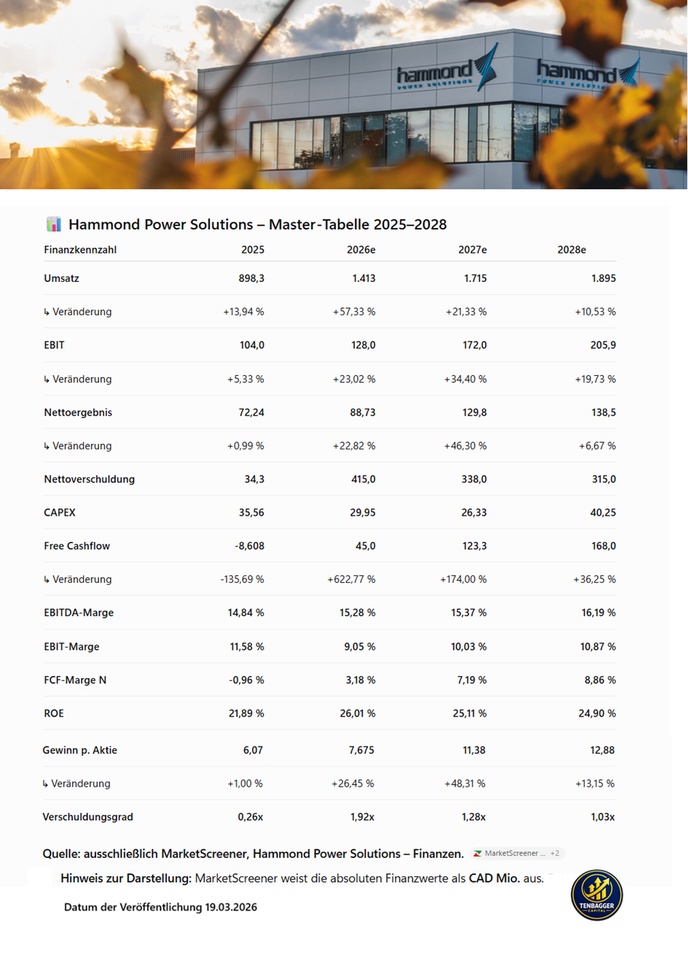
Particularly striking, therefore, is the combination of strong revenue and earnings growth and a very robust increase in free cash flow starting in 2026e.
🔎 Performance at a Glance
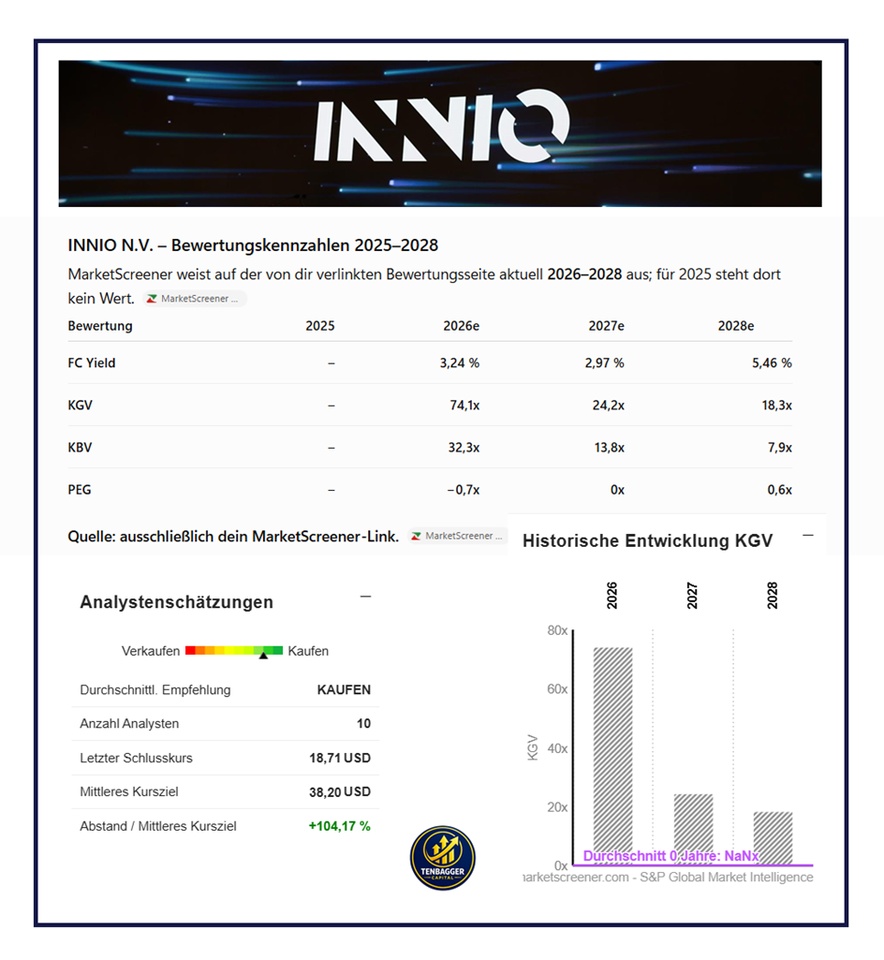
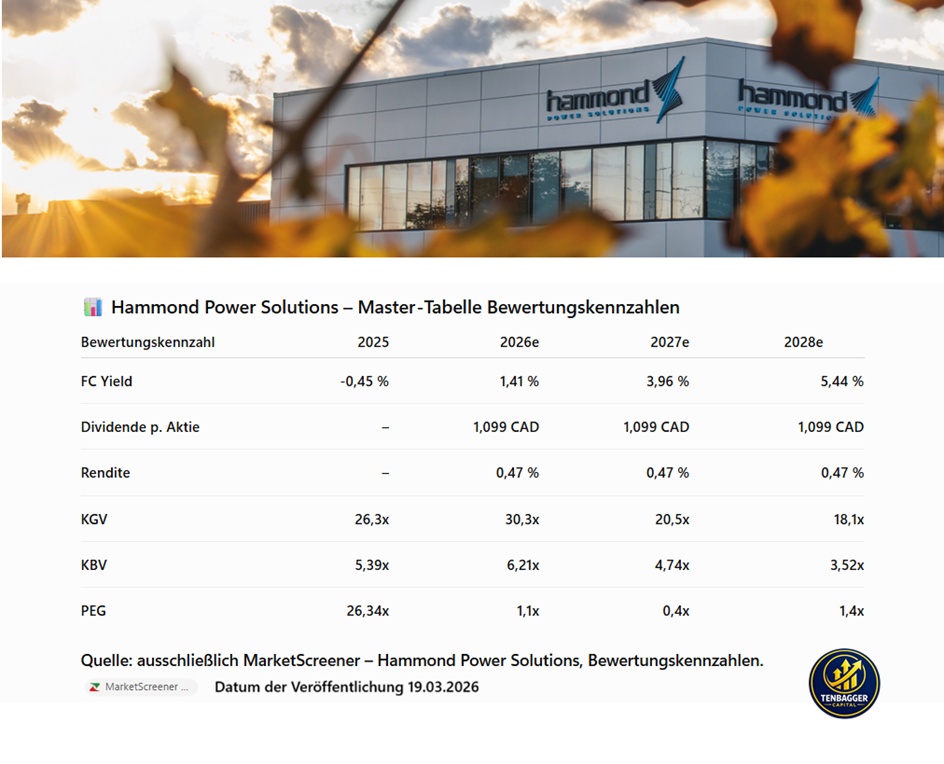
What is particularly interesting here is the sharply declining valuation multiples coupled with significantly rising FCF yields through 2028e.
Performance:
Year-to-date +48.55%
1 year +103.64%
5 years +2,000.27%
10 years +3,435.97%
September 17, 2026, 2:46:35 PM •
Lang & Schwarz (EUR)
143.00 EUR
+ 1

Hello, everyone,
My dear @Dividendenopi just brought to my attention a deal involving one of our companies in the project.
Of course, we remain invested here.
When selecting companies for the project, we both placed great emphasis on their fundamental prospects.
Even if the wait can be trying at times. Every stock with strong fundamentals has its time.
And patience pays off!
Generac, a manufacturer of emergency power generators and energy solutions, has Amazon a long-term supply contract worth up to $8 billion for emergency power generators in data centers. For the power technology manufacturer, the order is one of the largest in the company’s history and underscores its role as a supplier of physical infrastructure for hyperscale data centers. As part of the deal, Amazon will also receive a Optionsschein in Generac stock.
Generac-Aktie +33 Prozent nach Milliardendeal mit Amazon - Signalwirkung für Anleger

Hello my dears,
As announced yesterday, I will be introducing you to a few companies on the subject of electricity, energy and everything associated with it over the next few days. 🔌
I think the importance of these companies in the future, due to the growing demand for electricity and energy, should be clear to everyone by now.
There have already been some great posts about this in the past. Among others from our dear @EpsEra . (best wishes, and I hope you are well)
We are happy to discuss the topic and today's company in the comments.
Your opinion is important to me!
As Juan is still in Brazil, I will introduce Generac to you today. Nevertheless, as usual, here is the Juan's conclusion.
Generac dominates the market for emergency power systems with a US market share of over 70 %. Adjusted earnings per share of USD 1.80 were reported on April 29, exceeding the previous year's figure by 43 %. Sales increased by 12% year-on-year to USD 1.06 billion. As a result, management raised the outlook for revenue growth in 2026. The company not only supplies generators, but is increasingly integrating solar storage and energy management software. In view of outdated power grids and frequent blackouts, private crisis preparedness is becoming increasingly important.
Generac [GNRC | WKN A0YGR4 | ISIN US3687361044] is a leading provider of emergency power generators and backup power systems. The product range is aimed at private households, commercial enterprises, industrial plants and huge data centers. The core task of all these systems is to ensure a reliable and uninterruptible power supply precisely when the public power grid is overloaded or breaks down completely due to extreme weather events.
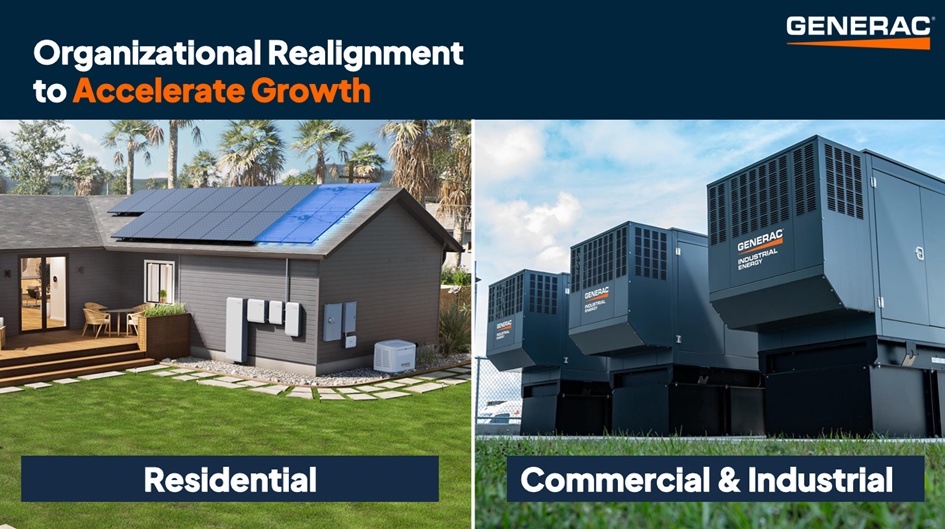
While the company has become known to investors in recent years as the US market leader for private emergency power solutions for private homes, Generac is currently undergoing a significant strategic change. Under CEO Aaron P. Jagdfeld, the company is transforming itself from a pure hardware manufacturer to an integral player in the decentralized energy transition.
The management's overarching vision is to build a decentralized energy grid that seamlessly networks conventional generators, modern battery storage systems and smart energy management systems. The company currently has a market capitalization of USD 13 billion.
The biggest drivers for Generac's core business are the accumulation of extreme weather events and the ageing of the US power grid. Last year alone, power outages in the USA amounted to over 1.5 billion hours. Added to this are rising energy costs. Generac not only wants to provide backup systems for more independence from the ailing power grids, but also enable a transparent and efficient supply via intelligent energy management. Every major power outage is free advertising and drives demand.
The market penetration of emergency power generators in the USA currently stands at 6.75%. In its latest investor presentation, Generac points out that every further 1% increase in the penetration rate corresponds to an additional market volume of around USD 4.5 billion.
The company is also increasingly benefiting from the gigantic appetite for energy in artificial intelligence. AI data centers are absolutely dependent on absolute reliability. As a result, the commercial and industrial (C&I) business is becoming a major growth driver for Generac. In the 4th quarter, the figures for which were published on February 10, the company recorded a 9% increase in revenue in the C&I segment to USD 358 million. Over the year as a whole, global C&I product sales even grew by 10 %.
There is currently already around 35 gigawatts of diesel backup capacity in the USA, installed at locations such as huge retail chains ("big box stores"), industrial plants and, above all, data centers - this is comparable to the output of 35 nuclear power plants. Although demand from the telecommunications sector has recently been rather weak due to a lack of extreme power outages, the high energy consumption of AI data centers easily makes up for this.
Generac was founded in 1959.
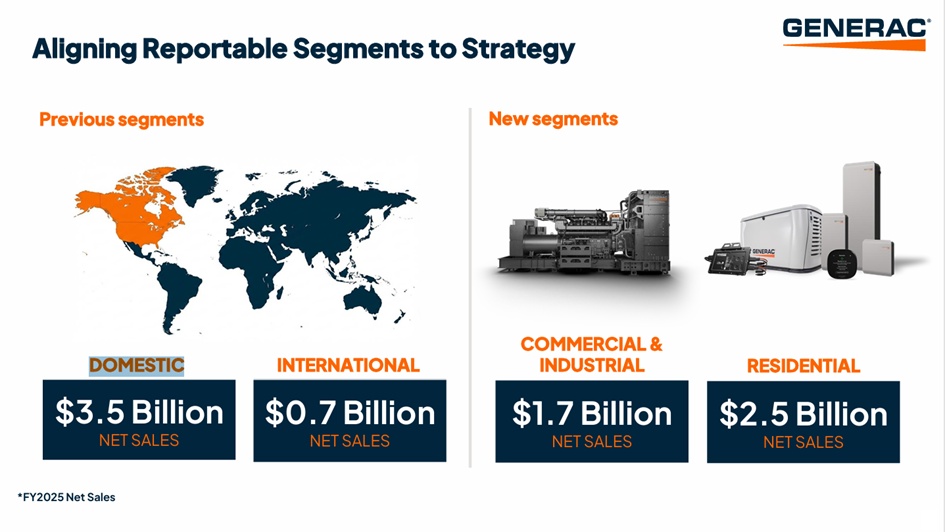
Net sales break down by product family as follows:
- Equipment for the private sector (53.9%): Emergency, portable and motorized generators powered by natural gas, propane or fuel, switchgear, etc.;
- Industrial and commercial equipment (34.6%): stationary, containerized, industrial and emergency generators powered by natural gas, propane, fuel, etc., advanced energy control systems and software platforms, switchgear, modular power systems, etc..;
- Other (11.5%).
The United States accounts for 82.5% of net sales.
f6f3ba99-5438-4678-9e6c-e983231864e4
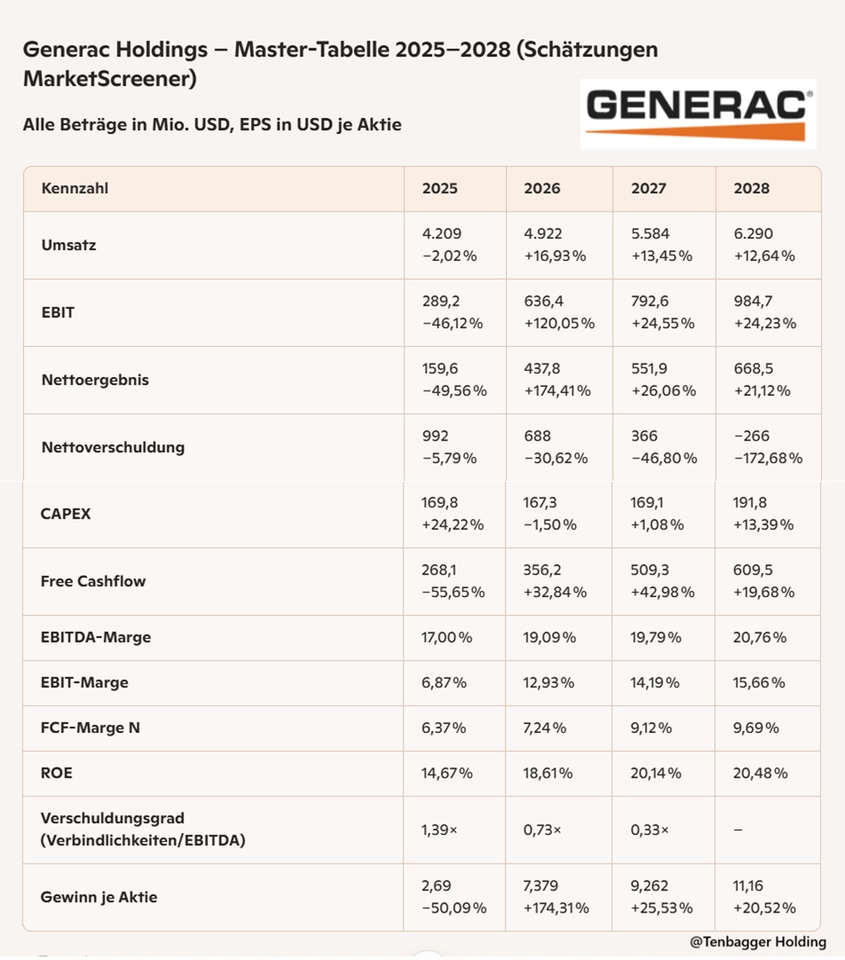
Juan summary of key financial figures (Generac 2025-2028)
Okay, here's the crisp Juan summary - just the way you like it:
Generac really ramps up again from 2026. 2025 is clearly a transition year with pressure on sales, EBIT and profit - but from 2026, profitability picks up massively. The EBIT margin practically doubles, free cash flow increases by double digits every year and net debt is consistently reduced, even to net cash by 2028. net cash turns into net cash.
Quality trend: Margins up, ROE up, debt down - exactly the kind of turnaround momentum that is often underestimated later. EPS jump: Earnings per share explode from 2026, which should ease the valuation significantly.
In a nutshell: 2025 is the trough - 2026-2028 are the steep slopes to the top. Generac becomes a cash machine setup again.
Market value 15,703
Number of shares (in thousands) 58,869
Date of publication 11,02,2026
Juan's conclusion on the valuation ratios (Generac 2025-2028)
"Generac looks like a comeback case in slow motion: The P/E ratio is falling noticeably year after year, while the FCF yield is slowly but steadily increasing. PEG turns healthy from 2027 - this is the first real quality signal. Dividend remains zero, so everything must come from growth and margins. Overall: Valuation side is clearly improving, but the market wants to see evidence first."
Performance
1 week +5.71 %
1 month +39.59 %
6 months +71.78 %
1 year +129.86 %
3 years +133.62 %
Please wait for a correction here!
PRICE: €228.85 08.05.2026 at 22:00
+ 3
Hi there, community! 🚀
As part of our latest search for undiscovered gems in the broader AI and energy ecosystem—because, as we all know, without massive energy storage systems (BESS), nothing will work in the extremely energy-hungry AI data centers of the future—we stumbled upon a pretty hot lead.
We first learned about the company through a recent press release on Investing, which covered a massive $200 million deal (a letter of intent). The link and more details are coming up later in the text.
And there was something else: We had promised our dear @Multibagger here in the group that we’d keep our eyes open for a speculative high-risk/high-reward candidate that really packs a punch and fits his type perfectly. Dear Multibagger, we really hope we’ve hit your sweet spot and that this stock delivers exactly the dose of thrills you’re looking for! 😉
While the solid cash cows on one side of our portfolio are quietly churning out their dividends, today I’ve brought something hot for the speculative side of things. A stock that hardly anyone has on their radar yet:
NeoVolta Inc. (NASDAQ: NEOV) $NEOV (-1,03%)
This isn’t a safe bet—it’s a full-blown gamble on the boom in battery storage systems and massive U.S. subsidies.
1. What the Company Does
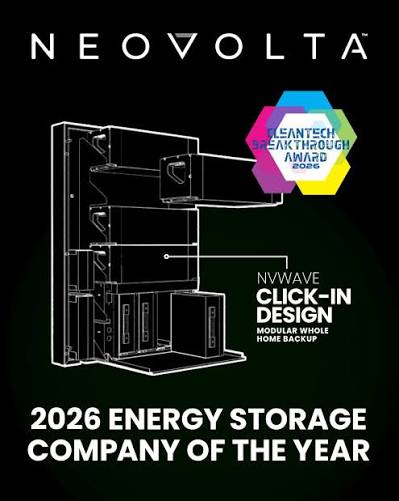
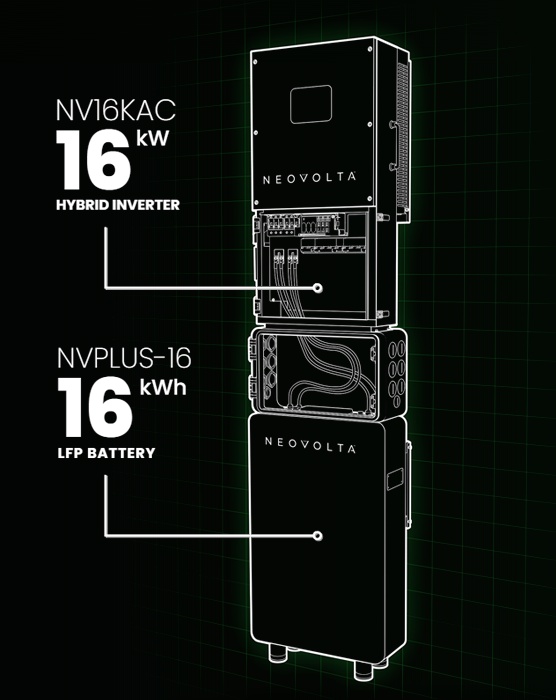
NeoVolta builds scalable battery energy storage systems (BESS) for residential and commercial use, and in the future, at the power-plant scale as well. The company is currently undergoing a massive transformation: it’s evolving from a provider of home storage solutions into a vertically integrated energy platform. At the very heart of this is a new factory in Pendergrass, Georgia, 80% of which is owned by the company.
2. Current Key Figures & Facts
3. Core Quality Formula (Revenue Growth + Margin)
Our target score for solid investments is > 25.
4. Cash Flow Quality Formula
5. Dividend Filter (Income-Core)
A very quick check: 0%. NeoVolta doesn’t pay out a single cent; it’s a pure growth stock.
6. Exclusion Rule Check
Actually, our ironclad rule applies here without exception: Operating margin consistently < 5%, company with no clear path to immediate profitability.
Why are we looking at this stock anyway? Because this is a deliberately isolated gamble for the highly speculative portion of the portfolio, where the focus right now is solely on future orders and the company’s narrative.
7. Future and Industry Outlook
This is where the real potential lies: NeoVolta has received the coveted “FEOC compliance opinion” for its Georgia plant. This qualifies it as one of the few U.S. providers eligible for massive tax credits (IRS Sections 45X and 48E).
There is already a letter of intent for $200 million. If they scale production from 2 GWh to 8 GWh, we’re talking about a theoretical revenue capacity of around $400 million.
8. Competition
The market is a veritable shark tank. $NEOV (-1,03%) It faces direct competition from giant, well-capitalized players such as $TSLA (+4,83%) and $GNRC (+1,33%) , which have long-established, global distribution channels.
9. Analyst Forecasts
Analysts are going completely crazy: Needham recently initiated coverage of NeoVolta with a price target of $8.00, Lake Street is even calling for $11.00.
The analysts’ bullish scenario anticipates a jump in revenue from ~$14 million (FY26) to a staggering ~$657 million in FY28.
10. Chart Analysis of the Last Few Months
The chart is a shambles over a 1-year period: a plunge of a whopping -51.6%. The 52-week low was $1.36, and the high was $7.13.
However, the short-term trend over the past few weeks shows extreme price swings (high volatility with a negative beta of -0.57) due to positive news about the factory in Georgia.
11. Bargain Hunter List (Entry Zones)
The price is currently fluctuating between $2.12 and $2.30. There is no fundamental bargain threshold for this speculative trade.
Anyone entering this trade must operate with a strictly limited stake and must absolutely set a strict stop-loss at approximately 15–20% below the purchase price to avoid total losses in the event of bad news.
12. Long-Term Viability
Everything hinges on the factory’s “Site Acceptance Testing” by the end of August 2026 and the subsequent production ramp-up in the third quarter.
The company must convert the non-binding letters of intent into binding purchase agreements. If it fails to do so, it risks running out of money.
13. Potential Alternatives
Those who aren’t interested in micro-cap risk and dilution should turn to industry giants such as Tesla or Generac.
While these don’t offer the potential for a 300% price target in just a few months, they aren’t burning through cash at that rate in their operations.
14. Profit Margin Report
Currently unavailable. Although the gross margin climbed to approximately 36% in Q3 (adjusted), the bottom line for Q3 was a steep net loss of -3.0 million USD (EPS of -0.08 USD, which missed expectations by a wide margin).
According to analysts, profits are not expected to materialize until FY28 (with an estimated EPS of +$0.70 at that time).
15. RaketenToni’s Conclusion & Risk Disclosure
NeoVolta is an asymmetric bet on the expansion of U.S. infrastructure and the FEOC tax credits. The company raised an additional $25 million in May through a new share issuance (dilution!), giving it some breathing room in the short term.
Caution: This is not solid buy-and-hold investment for our Cibus faction!
$NEOV (-1,03%) It’s a bet for the bold among us.
If the deals get signed, this stock will skyrocket.
If the factory stumbles, the lights go out. Strict position sizing and stop-loss orders are mandatory!
Greetings from Denmark
Yours, Raketentoni
and, of course, everyone else :)

Hello my dears,
As announced yesterday, I will be introducing you to a few companies on the subject of electricity, energy and everything associated with it over the next few days. 🔌
I think the importance of these companies in the future, due to the growing demand for electricity and energy, should be clear to everyone by now.
There have already been some great posts about this in the past. Among others from our dear @EpsEra . (best wishes, and I hope you are well)
We are happy to discuss the topic and today's company in the comments.
Your opinion is important to me!
As Juan is still in Brazil, I will introduce Generac to you today. Nevertheless, as usual, here is the Juan's conclusion.
Generac dominates the market for emergency power systems with a US market share of over 70 %. Adjusted earnings per share of USD 1.80 were reported on April 29, exceeding the previous year's figure by 43 %. Sales increased by 12% year-on-year to USD 1.06 billion. As a result, management raised the outlook for revenue growth in 2026. The company not only supplies generators, but is increasingly integrating solar storage and energy management software. In view of outdated power grids and frequent blackouts, private crisis preparedness is becoming increasingly important.
Generac [GNRC | WKN A0YGR4 | ISIN US3687361044] is a leading provider of emergency power generators and backup power systems. The product range is aimed at private households, commercial enterprises, industrial plants and huge data centers. The core task of all these systems is to ensure a reliable and uninterruptible power supply precisely when the public power grid is overloaded or breaks down completely due to extreme weather events.
While the company has become known to investors in recent years as the US market leader for private emergency power solutions for private homes, Generac is currently undergoing a significant strategic change. Under CEO Aaron P. Jagdfeld, the company is transforming itself from a pure hardware manufacturer to an integral player in the decentralized energy transition.
The management's overarching vision is to build a decentralized energy grid that seamlessly networks conventional generators, modern battery storage systems and smart energy management systems. The company currently has a market capitalization of USD 13 billion.
The biggest drivers for Generac's core business are the accumulation of extreme weather events and the ageing of the US power grid. Last year alone, power outages in the USA amounted to over 1.5 billion hours. Added to this are rising energy costs. Generac not only wants to provide backup systems for more independence from the ailing power grids, but also enable a transparent and efficient supply via intelligent energy management. Every major power outage is free advertising and drives demand.
The market penetration of emergency power generators in the USA currently stands at 6.75%. In its latest investor presentation, Generac points out that every further 1% increase in the penetration rate corresponds to an additional market volume of around USD 4.5 billion.
The company is also increasingly benefiting from the gigantic appetite for energy in artificial intelligence. AI data centers are absolutely dependent on absolute reliability. As a result, the commercial and industrial (C&I) business is becoming a major growth driver for Generac. In the 4th quarter, the figures for which were published on February 10, the company recorded a 9% increase in revenue in the C&I segment to USD 358 million. Over the year as a whole, global C&I product sales even grew by 10 %.
There is currently already around 35 gigawatts of diesel backup capacity in the USA, installed at locations such as huge retail chains ("big box stores"), industrial plants and, above all, data centers - this is comparable to the output of 35 nuclear power plants. Although demand from the telecommunications sector has recently been rather weak due to a lack of extreme power outages, the high energy consumption of AI data centers easily makes up for this.
Generac was founded in 1959.
Net sales break down by product family as follows:
- Equipment for the private sector (53.9%): Emergency, portable and motorized generators powered by natural gas, propane or fuel, switchgear, etc.;
- Industrial and commercial equipment (34.6%): stationary, containerized, industrial and emergency generators powered by natural gas, propane, fuel, etc., advanced energy control systems and software platforms, switchgear, modular power systems, etc..;
- Other (11.5%).
The United States accounts for 82.5% of net sales.
f6f3ba99-5438-4678-9e6c-e983231864e4
Juan summary of key financial figures (Generac 2025-2028)
Okay, here's the crisp Juan summary - just the way you like it:
Generac really ramps up again from 2026. 2025 is clearly a transition year with pressure on sales, EBIT and profit - but from 2026, profitability picks up massively. The EBIT margin practically doubles, free cash flow increases by double digits every year and net debt is consistently reduced, even to net cash by 2028. net cash turns into net cash.
Quality trend: Margins up, ROE up, debt down - exactly the kind of turnaround momentum that is often underestimated later. EPS jump: Earnings per share explode from 2026, which should ease the valuation significantly.
In a nutshell: 2025 is the trough - 2026-2028 are the steep slopes to the top. Generac becomes a cash machine setup again.
Market value 15,703
Number of shares (in thousands) 58,869
Date of publication 11,02,2026
Juan's conclusion on the valuation ratios (Generac 2025-2028)
"Generac looks like a comeback case in slow motion: The P/E ratio is falling noticeably year after year, while the FCF yield is slowly but steadily increasing. PEG turns healthy from 2027 - this is the first real quality signal. Dividend remains zero, so everything must come from growth and margins. Overall: Valuation side is clearly improving, but the market wants to see evidence first."
Performance
1 week +5.71 %
1 month +39.59 %
6 months +71.78 %
1 year +129.86 %
3 years +133.62 %
Please wait for a correction here!
PRICE: €228.85 08.05.2026 at 22:00
+ 3
So far I have 4 top stocks in my portfolio. Will it stay that way after 15:30?
They are all energy stocks
$BE (+2,26%) but already did well yesterday after the close. Are therefore up 17% compared to yesterday's close
$NVDA (+1,58%)
$IREN (+2,85%)
$JLL (+0%)
$GOOGL (+1,37%)
$AMZN (+5,14%)
$META (-0,51%)
$JLL (+0%) says the cycle will continue until 2030. 3Trillion! $, that's 3.000.000.000.000!!!! Will be invested. Pre-letting is currently >70%. Occupancy at 97%!
Obstacles are delivery difficulties in construction and power. Good news for blade manufacturers, e.g. of UPS, cooling etc. ($VRT (+0,1%)
$JCI (+1,91%)
$CARR (+0,92%)
$SU (-2,07%)
$ETN (+0,79%)
$GNRC (+1,33%)
$CSCO (+0,11%)
$ANET (+3,74%)
$COMM (+1,4%)) and companies like $IREN (+2,85%) who have already secured power.
Gas will also continue to be important.
More than half of this will take place in the USA and Europe will fall behind.
Which blade manufacturers are you focusing on? Where do you see the greatest potential?
I myself am with $NVDA (+1,58%)
$VRT (+0,1%) and $IREN (+2,85%) invested.

🔹 Revenue: $1.11B (Est. $1.19B) 🔴
🔹 EPS: $1.83 (Est. $2.20) 🔴
FY25 Outlook
🔹 Net Sales Growth: ~flat YoY (Prior: +2% to +5%) 🔴
🔹 Net Income Margin (pre-NCI): ~6.0% (Prior: 7.5%–8.5%) 🔴
🔹 Adjusted EBITDA Margin: ~17.0% (Prior: 18.0%–19.0%) 🔴
🔹 FCF Conversion (from adj. NI): ~80% (Prior: 90%–100%) 🔴
Principais criadores desta semana


