
$MAR (-1,2%)
$KRYS (-0,51%)
$PLTR (-2,49%)
$STRL (-10,19%)
$SNAP (-2,16%)
$WHR (+7,77%)
$CLX (+4,7%)
$BWXT (-5,49%)
$ON (-6,56%)
$VRTX (+4,26%)
$PFIZER
$CAT (-4,9%)
$MCD (+2,72%)
$HUT (-11,09%)
$WIX (+4,56%)
$W (+0,45%)
$BP. (+0,29%)
$SHLS
$AMD (-8,32%)
$SPCX (-8,41%)
$ANET (-7,81%)
$ALAB (-11,39%)
$OPEN (+4,62%)
$ZETA (-2,71%)
$BKNG (+2,15%)
$KTOS (-2,08%)
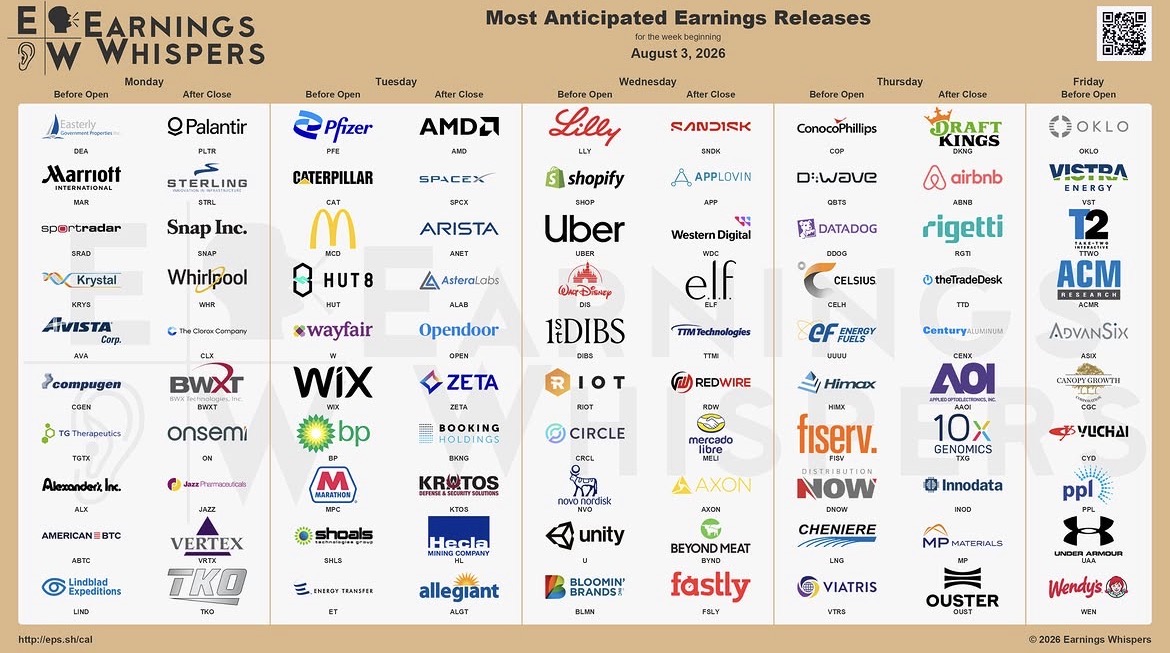
$HL (-6,95%)
$LLY (+2,96%)
$SHOP (-5,19%)
$UBER (+1,83%)
$DIS (+1,16%)
$RIOT (-9,13%)
$CIRC
$NOVO B (+0,86%)
$U (-2,69%)
$SNDK (-10,61%)
$APP (-1,73%)
$WDC (-13,87%)
$ELF (+0,74%)
$MELI (-1,66%)
$AXON (+3,78%)
$TTMI (-29,19%)
$RDW (-5,24%)
$QBTS (-4,53%)
$DDOG (-6,13%)
$CLA (+0%)
$FI (+5,07%)
$LNG (+1,15%)
$UUUU (-6,79%)
$HIMX (-6,81%)
$ABNB (+1,47%)
$RGTI (-5,6%)
$TTD (+3,75%)
$AAOI (-13,31%)
$TXG (-7,59%)
$INOD (-2,56%)
$OUST
$MP (-3,12%)
$OKLO
$VST (-10,1%)
$TTWO (+0,46%)
$ACMR (-10,11%)
$WEED (+1,67%)
$UAA (+5,66%)
Hecla Mining
Price
Discussão sobre HL
Postos
13Let's move on to the next round!


I have one more!
With a derivative on $HL (-6,95%) This was more of a speculation on good figures yesterday, but even after the price drop it is still an interesting value for all those who bet on silver. You can also see from the results that in the last quarter the price at which the silver mined was sold was around 65$, which is well below the current price. Not to mention the highs. I therefore see major further profit increases here, especially as debt has been greatly reduced and the company is almost debt-free.
Interesting for commodity investors
Good figures from $HL (-6,95%) I bought a small derivative today before the figures.
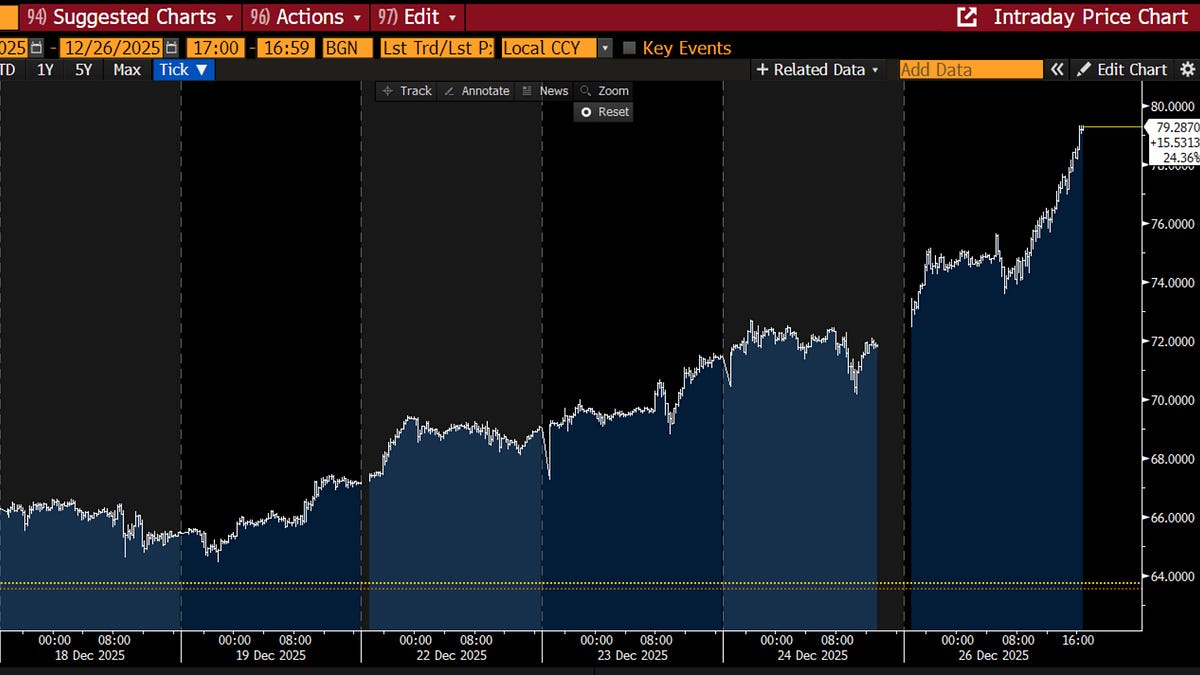
Investing.com -- Hecla Mining Company (NYSE:HL) reported fourth-quarter results that beat analysts' expectations thanks to higher precious metals prices and increased production. Shares rose 1.7% in after-hours trading following the announcement.
The silver and gold producer reported adjusted earnings of $0.20 per share for the quarter, beating analysts' consensus of $0.16. Revenue rose to $448.1 million, well above the $372.5 million forecast by analysts and 83% higher than the same quarter last year.
The strong business performance was boosted by the sharp rise in the price of silver. Hecla reported an average realized silver price of $69.28 per ounce for the fourth quarter, more than double that of the same period last year ($30.19 per ounce). The company produced 3.8 million ounces of silver in the reporting period.
"2025 was a transformative year for Hecla with strong operational and financial results across a number of key metrics," said Rob Krcmarov, President and Chief Executive Officer. "Our balance sheet has improved significantly and we are now well positioned to invest in value-creating initiatives focused on our world-class project pipeline."
For the full year 2025, Hecla reported record revenue of over $1.4 billion, an increase of 53% year-on-year. Net income also reached a record $321 million, or $0.49 per share. The company generated operating cash flow of $563 million and free cash flow of $310 million.
Hecla's net debt fell by more than 93% year-on-year to just $34 million. The net leverage ratio improved from 1.6x in the previous year to 0.1x.
The company recently announced the sale of its Casa Berardi gold mine for up to $593 million. According to management, this move positions Hecla as "North America's premier silver company". The transaction is expected to close in the first quarter of 2026.
For 2026, Hecla forecasts consolidated silver production of 15.1-16.5 million ounces and gold production of 65,000-72,000 ounces. This includes 14,000-17,000 ounces from the Casa Berardi mine in the first quarter.
A little quieter next week
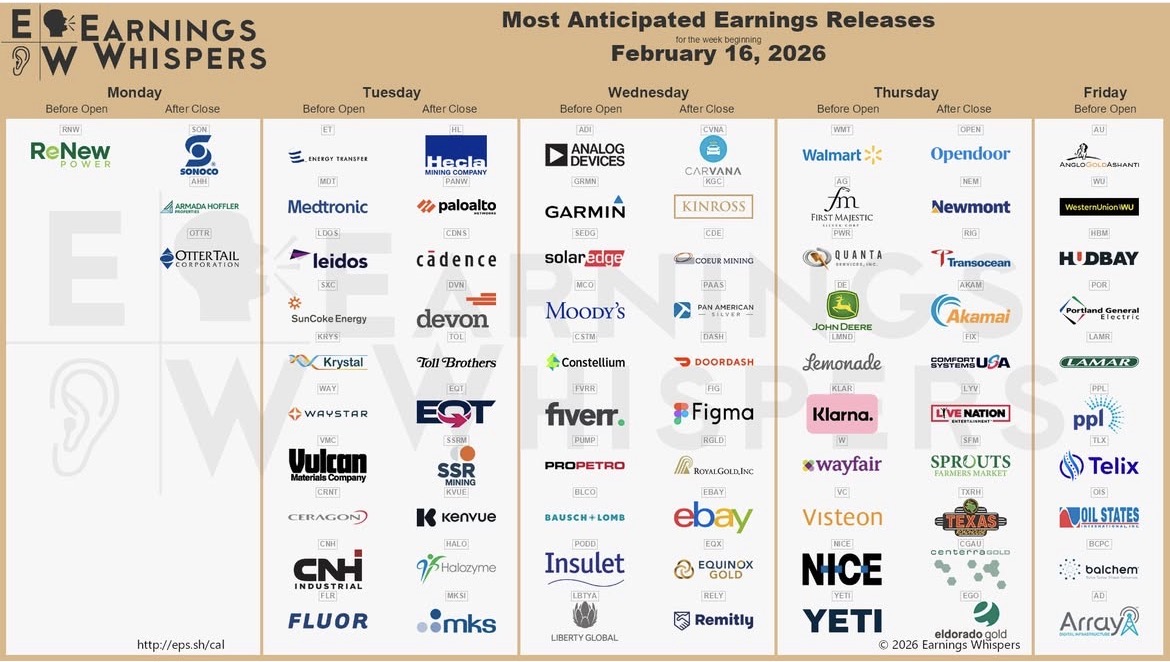
$SON (-1,22%)
$MDT (+3,89%)
$LDOS (+4,41%)
$PANW (+1,75%)
$CDNS (-5,62%)
$KRYS (-0,51%)
$HL (-6,95%)
$TOL (+5,36%)
$KVUE (+3,78%)
$DEVON
$ADI (-5,55%)
$GRMN (+1,6%)
$SEDG (-0,68%)
$MCO (+0,81%)
$FVRR (+1,14%)
$PODD (+4,55%)
$CVNA (-0,89%)
$DASH (+0,97%)
$FIGX
$EBAY (-0,56%)
$RELY
$WMT (+3,17%)
$PWR (-8,96%)
$DE (+1,04%)
$LMND (+0,67%)
$KLAR (+1,37%)
$W (+0,45%)
$NICE
$YETI (+2,89%)
$OPEN (+4,62%)
$NEM (-1,7%)
$AKAM (+0,32%)
$SFM (+5,26%)
$TXRH (+3,1%)
$BCPC (+1,51%)
$BKNG (+2,15%)


Where do you see more potential?
$HL (-6,95%) or $SVM (-7,8%) ???


Why Copper isn’t an Immediate Kill Switch for Silver
The most common pushback against the bullish silver thesis is: “Don’t worry, solar will just switch from silver to copper.” How plausible is that?
Alexander Campbell (ex Head of Commodities at Bridgewater) frames it this way:
🔻Demand destruction threshold
• He puts the “break-even / where demand destruction even begins” around $134/oz (not a price target, but the level where the squeeze starts to bite).
⏳ The bottleneck is time (not money)
• Rough math: ~300 factories worldwide, ~1.5 years to convert each to copper plating, and ~60 factories/year parallel capacity --> ~4 years minimum to reach 50% copper adoption.
💸 Even if economics scream “do it”…
• Around $125/oz, payback drops below 1 year, but “deciding tomorrow” still doesn’t compress the industrial timeline (physics/operations > incentives)
🛠️ Not plug-and-play
• Switching to copper isn’t a simple input swap; it requires process/design changes, manufacturing workflow changes, and retraining/qualification.
🔁 The mix effect (PERC → TOPCon → HJT)
• While copper is discussed, the tech mix shift can increase silver intensity on average (he cites ~13.5 mg/W in 2025 vs ~15.2 mg/W in 2030).
✅ Bottom line
Copper may be the long-term “end state”, but it’s unlikely to be an immediate kill switch. Silver can move faster than the PV supply chain can retool.
https://www.campbellramble.ai/p/10-silver-days-of-christmas
$SSLN (-5,63%)
$SILG (-6,3%)
$PHAG (-5,67%)
$XAD6 (-5,68%)
$SIVR (-5,45%)
$SLV (-5,43%)
$SIL (-5,86%)
$SILJ
$PAAS (-5,81%)
$AG
$EDR (-7,31%)
$SVM (-7,8%)
$MAG
$HL (-6,95%)
$SAMG
$AYA (-10%)
🚫NO SILVER LEFT🚫
Rising industrial demand, rigid supply and a market in continuous deficit since 2020.
⚡ The photovoltaic boom isn’t slowing down: total silver demand is expected to reach between 48,000 and 54,000 tonnes per year, with the solar sector alone accounting for up to 40% of global consumption.
⚒️ On the supply side, 72% of silver is produced as a byproduct, and any new primary mine takes nearly a decade to come online. Supply elasticity is almost zero.
Even after factoring in more recycling and lower silver intensity per solar cell, the model shows that by 2030, supply would cover at best 70% of demand — leaving a gap that someone will have to fill… or that prices will eventually correct for.
https://www.sciencedirect.com/science/article/abs/pii/S0921344925004392
$SSLN (-5,63%)
$SILG (-6,3%)
$PHAG (-5,67%)
$XAD6 (-5,68%)
$SIVR (-5,45%)
$SLV (-5,43%)
$SIL (-5,86%)
$SILJ
$PAAS (-5,81%)
$AG
$EDR (-7,31%)
$SVM (-7,8%)
$MAG
$HL (-6,95%)
$SAMG
$AYA (-10%)


You seem to look into mining companies. What makes minimg companies better that a direct investment in silver?


$HL
Once again taking profits at $HL (-6,95%) After 5 years with a percentage increase of approx. 130%, the percentages given by getquin are unfortunately not correct. But I'm still letting 230 shares run but wanted to invest in other things like $NOVO B (+0,86%) with Novo the dividend yield of approx. 4% was the main reason and $HIMS (-1,38%) otherwise I am unfortunately overweighted with the mining shares. I still have 80 shares in $EDV (-5,23%) which I like to let run longer because of the good dividend of approx. 2.5% on my invested capital, which makes them even more interesting for me. But I only bought these in 2022.
Winnings windfall
Had to take profits today from $HL (-6,95%) this position has grown to over 20% and has almost doubled in 2 months now I have taken about 40% of the position


Títulos em alta
Principais criadores desta semana