
$MAR (-0,73%)
$KRYS (-2,33%)
$PLTR (+0,29%)
$STRL (-1,72%)
$SNAP (+0,35%)
$WHR (-0,27%)
$CLX (-2,12%)
$BWXT (-0,73%)
$ON (-0,05%)
$VRTX (-1,61%)
$PFIZER
$CAT (-1,71%)
$MCD (-1,4%)
$HUT (-1,58%)
$WIX (-1,5%)
$W (+0,72%)
$BP. (+3,17%)
$SHLS
$AMD (+2,82%)
$SPCX (+0,8%)
$ANET (+2,27%)
$ALAB (+2,18%)
$OPEN (-1,08%)
$ZETA (+2,19%)
$BKNG (-2,42%)
$KTOS (+0,4%)
$HL (-1,07%)
$LLY (-1,81%)
$SHOP (+0,89%)
$UBER (-1,34%)
$DIS (-0,06%)
$RIOT (-1,06%)
$CIRC
$NOVO B (-0,9%)
$U (+3,43%)
$SNDK (+4,57%)
$APP (+0,3%)
$WDC (+7,94%)
$ELF (+0,64%)
$MELI (-0,52%)
$AXON (+1,04%)
$TTMI (+7,41%)
$RDW (+0,97%)
$QBTS (-0,87%)
$DDOG (+5,22%)
$CLA (+0%)
$FI (-2,16%)
$LNG (+4,03%)
$UUUU (-2,42%)
$HIMX (+2,27%)
$ABNB (-0,92%)
$RGTI (+0,45%)
$TTD (-0,43%)
$AAOI (+4,06%)
$TXG (+1,31%)
$INOD (+0,85%)
$OUST
$MP (+0,37%)
$OKLO
$VST (+0,27%)
$TTWO (-0,86%)
$ACMR (+4,28%)
$WEED (-2,46%)
$UAA (-3,59%)
Wayfair
Price
Discussão sobre W
Postos
9Let's move on to the next round!
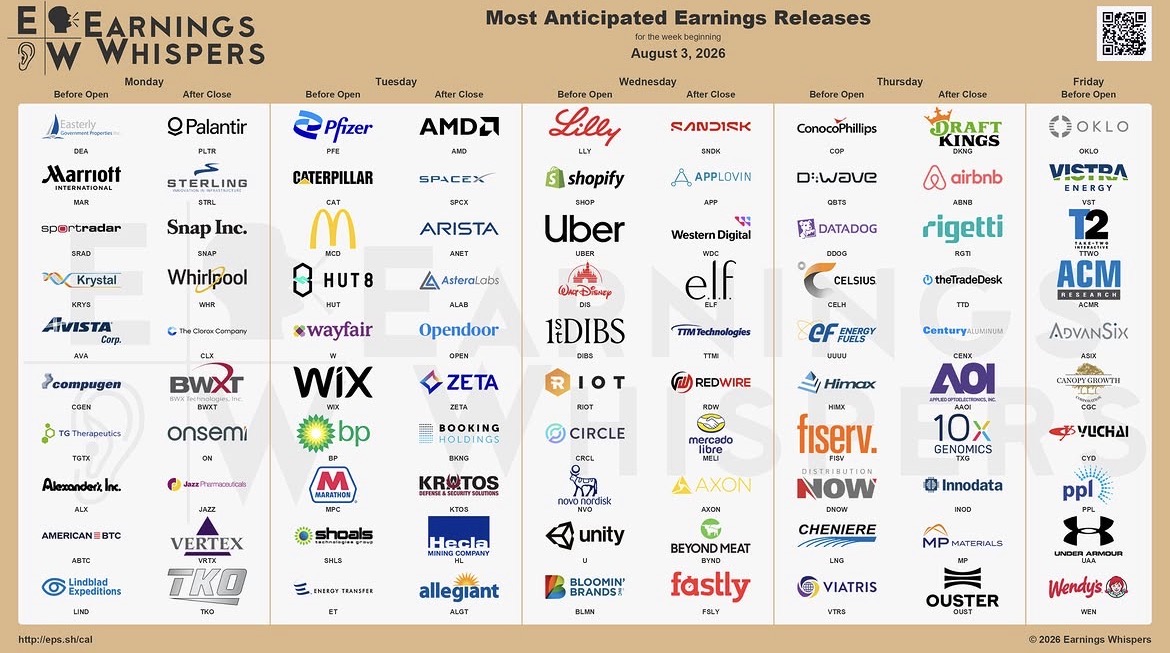


A little quieter next week
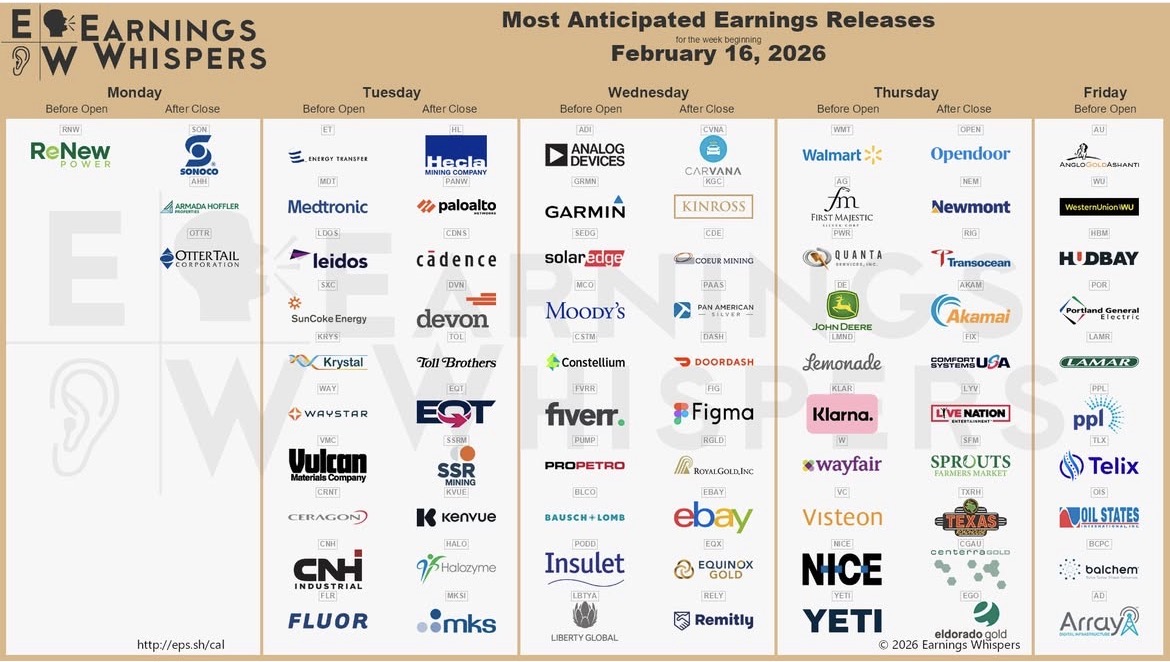
$SON (+0,08%)
$MDT (-0,19%)
$LDOS (+0,58%)
$PANW (+6,89%)
$CDNS (+3,53%)
$KRYS (-2,33%)
$HL (-1,07%)
$TOL (-0,28%)
$KVUE (-1,31%)
$DEVON
$ADI (+1,94%)
$GRMN (+0,82%)
$SEDG (+1,02%)
$MCO (-1,71%)
$FVRR (+1,03%)
$PODD (-0,11%)
$CVNA (-1,6%)
$DASH (-1,3%)
$FIGX
$EBAY (-0,18%)
$RELY
$WMT (-0,46%)
$PWR (+0,54%)
$DE (+0,44%)
$LMND (-0,31%)
$KLAR (-2,79%)
$W (+0,72%)
$NICE
$YETI (-2,04%)
$OPEN (-1,08%)
$NEM (-3,99%)
$AKAM (+3,07%)
$SFM (-3,67%)
$TXRH (-3,55%)
$BCPC (+1,2%)
$BKNG (-2,42%)


Wayfair Q2'25 Earnings Highlights
🔹 Revenue: $3.27B (Est. $3.12B) 🟢; UP +5.0% YoY
🔹 Adj. EPS: $0.87 (Est. $0.33) 🟢
🔹 Gross Profit: $984M; Gross Margin: 30.1%
🔹 Adj. EBITDA: $205M; EBITDA Margin: 6.3%
🔹 Net Income: $15M (vs. -$42M YoY)
🔹 Operating Income: $17M (vs. -$35M YoY)
🔹 Free Cash Flow: $230M (vs. $183M YoY)
🔹 Operating Cash Flow: $273M
Customer & Order Metrics
🔹 Active Customers: 21.0M; DOWN -4.5% YoY
🔹 LTM Revenue per Customer: $572; UP +5.9% YoY
🔹 Orders Delivered: 10.0M (flat YoY)
🔹 Avg. Order Value: $328 (vs. $313 YoY)
🔹 Orders per Customer: 1.86 (vs. 1.85 YoY)
🔹 Repeat Order Share: 80.7% (vs. 81.7% YoY)
🔹 Mobile Order Share: 62.9% (vs. 63.7% YoY)
CEO Commentary
🔸 “Q2 was a resounding success—sales growth, margin expansion, and market share gains. Our 6% adj. EBITDA margin reflects the leverage in our model and marks the best profitability we’ve seen since 2021.”
🔸 “This quarter shows years of thoughtful investment paying off, and we’re excited for what lies ahead in 2025 and beyond.”

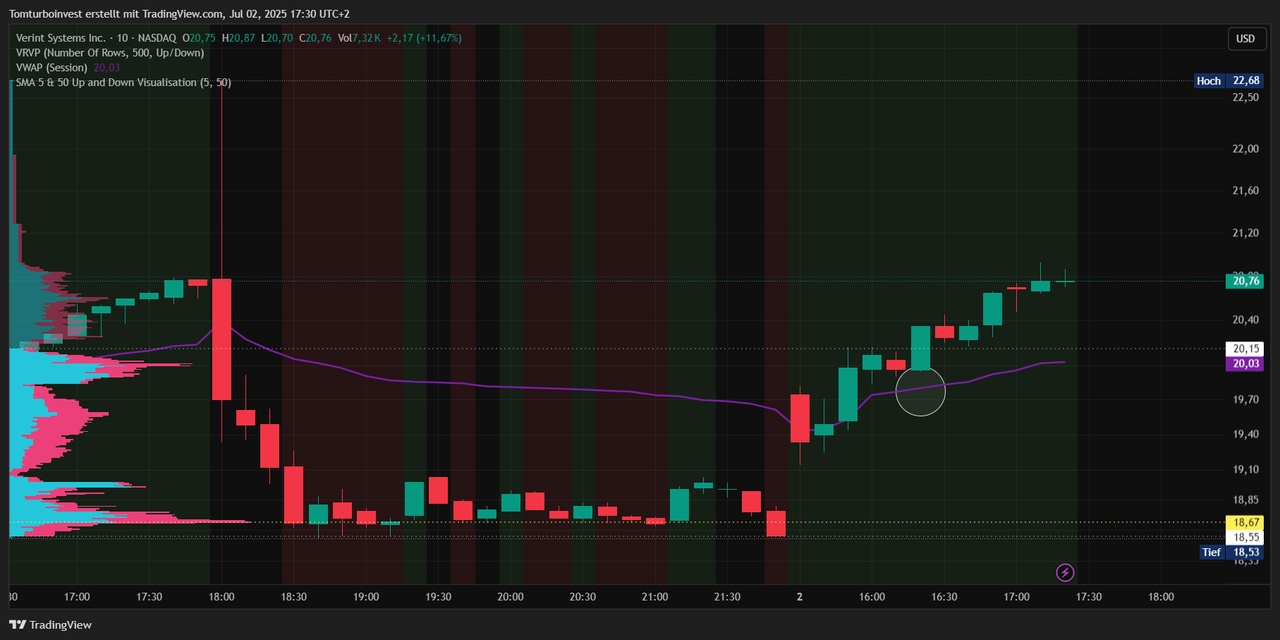
TradingSetup of today
⚠Only for those interested in trading - otherwise keep scrolling 😅
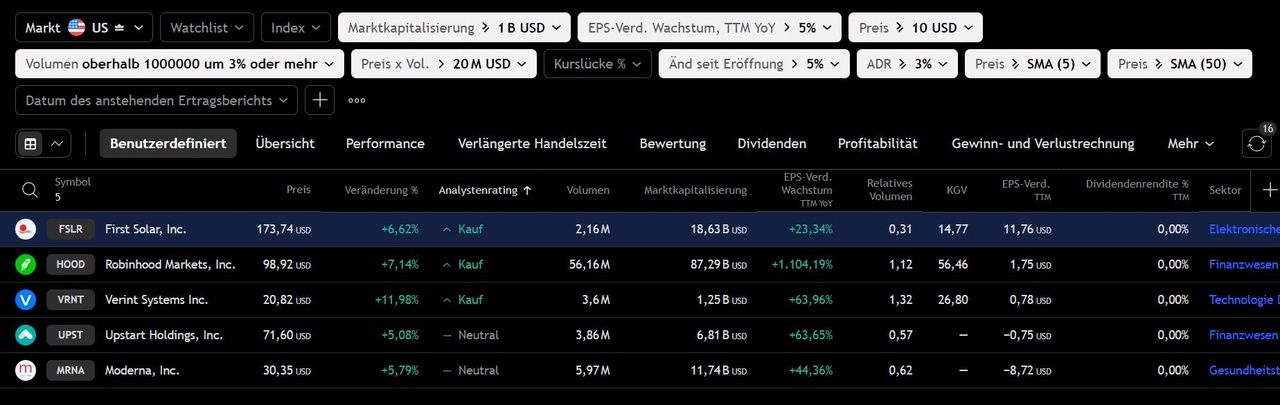
@MCKrummel-Divi-Holding Since I'm sitting at the computer after your comment, here are a few examples -> this is what the screener "spit out"
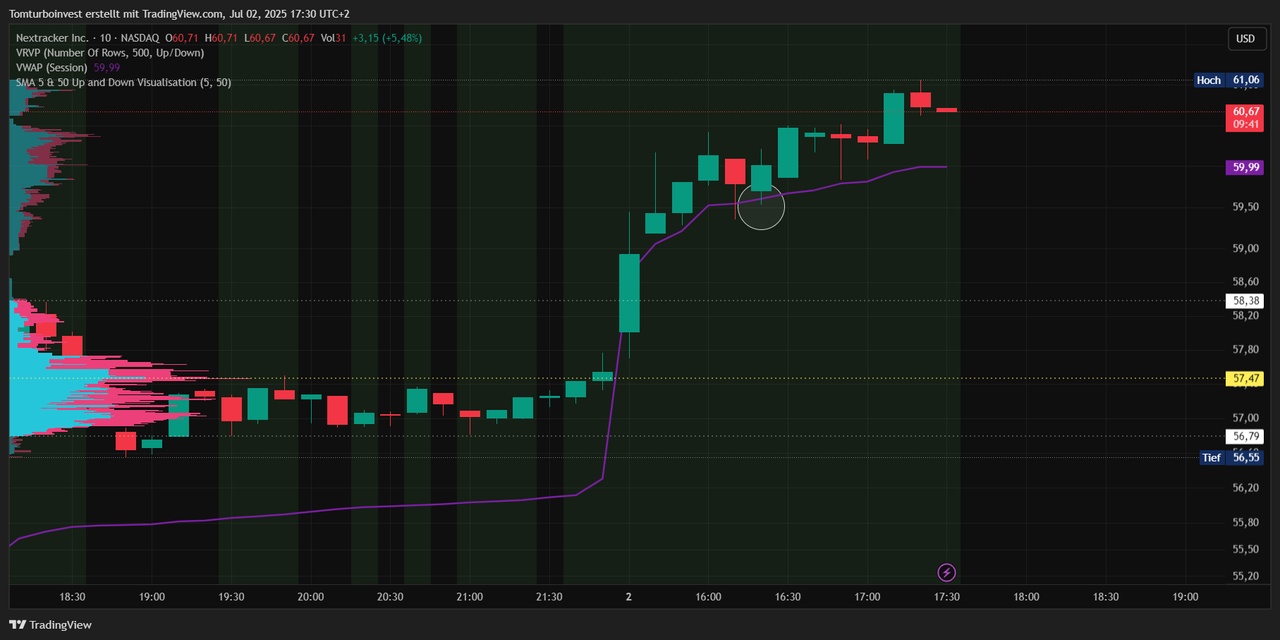
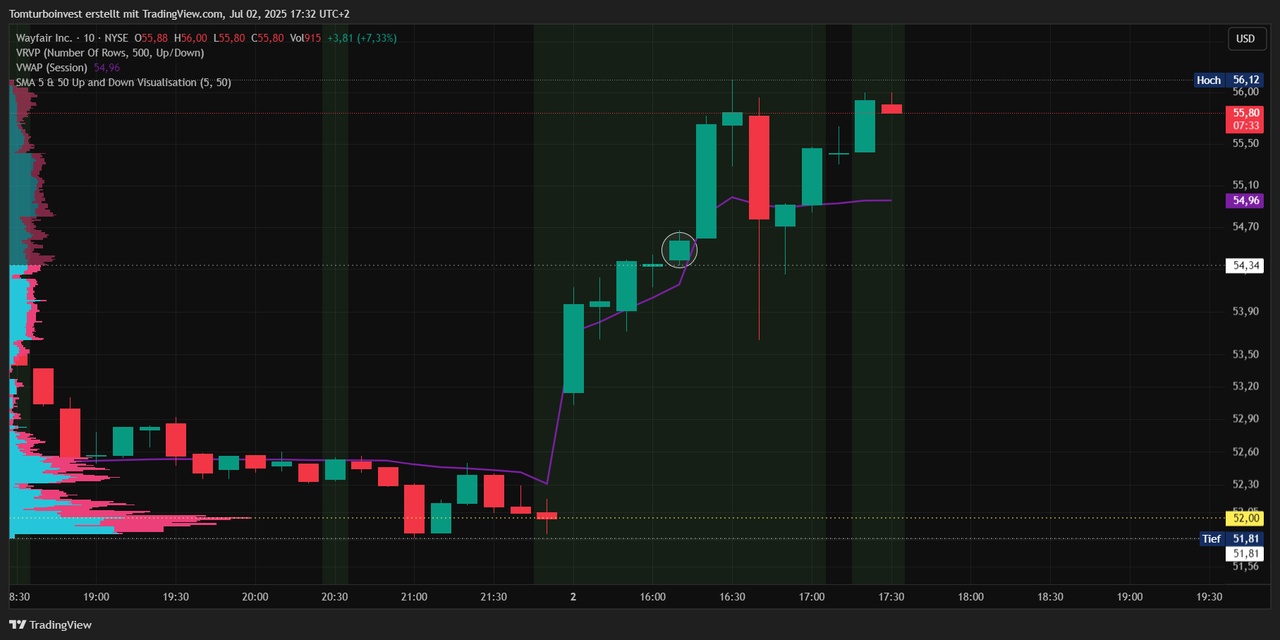
@Epi the recently discussed setup, I always look at the same pattern. Well secured on the downside
@Dividenden_Monteur something for you?😎
PS: I have added the link to the chart pictures everywhere, so you can still follow the chart live until the close of trading if you are interested 👈
$MRNA (+1,54%)
https://www.tradingview.com/x/vzNaFp6T/
$HOOD (+0,02%) wait here how it develops on the VWAP https://www.tradingview.com/x/l4g6iRhL/
$VRNT
https://www.tradingview.com/x/usbMLEAZ/
$NXT
https://www.tradingview.com/x/hzo2u5SA/
$FSLR (+0,79%)
https://www.tradingview.com/x/JWZVSjVl/
$W (+0,72%)
https://www.tradingview.com/x/rCO7KhVs/
@Multibagger my tubular cracker $STZ (+0%) maybe something will happen, from the -8% we are already at only -3% - I'll give this swing trade a little more time 🤕
+ 3


Wayfair - A turnaround candidate or will the pressure in the furniture market remain high?
Wayfair ($W) (+0,72%) was a clear winner in e-commerce during the pandemic, but experienced a drastic crash afterwards. Now that the market has stabilized, investors are asking themselves: Is Wayfair ripe for a comeback or will the company remain under pressure?
Overview: What does Wayfair do?
Wayfair is one of the world's largest online retailers for furniture and home accessories. The company operates an asset-light model, which means that it does not produce its own furniture, but brokers products via a broad network of manufacturers and suppliers.
✅ Wayfair.com: Main platform for online furniture retail in the USA, Canada and Europe.
✅ Wayfair Professional: B2B platform for companies and interior designers.
✅ Perigold, AllModern, Birch Lane and Joss & Main: Other brands covering different design styles.
Wayfair relies heavily on data analysis and AIto understand buying behavior and optimize the supply chain.
Competition: Who are the competitors?
🔸 Amazon ($AMZN) (-0,41%) & Walmart ($WMT) (-0,46%) - Huge competition in online retail, which also offer furniture.
🔸 IKEA - The stationary furniture giant that is constantly expanding its online presence.
🔸 Home Depot ($HD) (-2,37%) & Lowe's ($LOW) (-2,48%) - Important competitors in the Home & Living segment.
🔸 Etsy ($ETSY) (-0,12%) & smaller specialty retailers - Competition from individual furniture and decoration suppliers.
Wayfair has the advantage of being a pure online specialist specialist for furniture, but has to hold its own against financially strong rivals.
Opportunities: Why could Wayfair make a comeback?
✅ Efficiency gains: Wayfair has worked hard on its cost structure and reduced staff in recent quarters.
✅ Stabilization of demand: After the extreme boom in 2020-2021 and the decline in 2022-2023, the market could now normalize.
✅ Improved consumer climate: Falling inflation and potential interest rate cuts could boost purchasing power.
✅ Improved margins: The company has recently achieved higher gross margins, which indicates better cost control.
✅ Expansion of B2B business: Wayfair Professional continues to grow and could be a stable revenue generator in the long term.
Risks: What could continue to weigh on Wayfair? ⚠️
⚠️ High competitive pressure: Amazon, IKEA and Walmart are strong opponents with better supply chains.
⚠️ Dependence on macro factors: High interest rates and weak consumer sentiment could delay the recovery.
⚠️ Profitability remains fragile: Wayfair has made losses in the past and needs to show it can sustain profits.
⚠️ Logistics and storage costs: Despite efficiency gains, shipping bulky furniture remains a challenge.
⚠️ Customer loyalty: Unlike Apple or Tesla, customers have little loyalty to Wayfair - many simply compare prices with the competition.
Conclusion: turnaround opportunity or value trap?
Wayfair could be one of the most exciting turnaround candidates in 2025. The company has worked hard on its cost structure and could benefit from a recovery in consumer sentiment. However, competition remains intense and it is not yet certain whether Wayfair will become sustainably profitable.
What do you think? Does Wayfair have the potential for a strong recovery or will the share remain a shaky candidate? 🚀

In my opinion, they were selling cheap Chinese trash at overpriced prices. Just like Kare etc. do in my opinion.
Whether they still do it that way - I don't know. In any case, I would never buy the stock because I didn't like their business practices back then.

Boeing and 6 More Contrarian Stocks for 2025
Boeing $BA (-0,76%)
Merck $MRK (-1,58%)
Nike $NKE (-0,52%)
Ulta Beauty $ULTA (-1,4%)
Roku $ROKU (-0,43%)
Wayfair $W (+0,72%)
Peloton $PTON (-0,72%)
$W (+0,72%) | Wayfair Q3'24 Earnings Highlights:
🔹 Revenue: $2.88B (Est. $2.88B) 🟡; DOWN -2% YoY
🔹 Adjusted EPS: $0.22 (Est. $0.13) 🟢
🔹 Net Loss: $74M; Improved from $163M YoY
🔹 Gross Profit: $873M (30.3% margin)
🔹 Adjusted EBITDA: $119M; UP from $100M YoY
Key Metrics:
🔹 Active Customers: 21.7M; DOWN -2.7% YoY
🔹 Average Order Value: $310; UP from $297 YoY
🔹 Repeat Orders: 79.9% of total orders
🔹 Orders Delivered: 9.3M; DOWN -6.1% YoY
CEO Commentary:
🔸 "Focused on profitability and customer loyalty to build long-term value amidst a challenging environment."

An overview of the dismissals (last 3 months), via Twitter.
- Twitch: 35%
- Hasbro: 20%
- Spotify ($SPOT (-0,58%) ): 17%
- Levi's: 15%
- Zerox ($ZEROX ): 15%
- Qualtrics ($XM ): 14%
- Wayfair ($W (+0,72%) ): 13%
- Duolingo: 10%
- Washington Post: 10%
- eBay ($EBAY (-0,18%) ): 9%
- Business Insider: 8%
- Charles Schwab ($SCHW (-1,14%) ): 6%
- Macy's ($M (+1,46%) ): 4%
- Blackrock ($BLK ): 3%
- Citigroup ($C (-1,01%) ): 20,000
- UPS ($UPS (-1,11%) ): 12,000
- Pixar: 1,300
- Salesforce ($CRM (-1,17%) ): 700
- American Airlines: 650
- PayPal ($PYPL (+0,43%) ): 2,500


Quarterly figures on 03.11.2022...
Feel free to leave a follow, because...⤵️
...at 5,000 followers there will be together with getquin, a small thank you for the community. But this post could already be created tomorrow. I look forward to it! On to today's quarterly numbers. In this post that I post every morning, I had announced what was happening today:
https://app.getquin.com/activity/ydggsOLkpb?lang=de&utm_source=sharing
$SBUX (-0,12%)
Starbucks:
Beat analyst estimates of $0.73 in the fourth quarter with earnings per share of $0.81. Revenue of $8.4 billion beat expectations of $8.33 billion.
$PYPL (+0,43%)
PayPal:
Beats analyst estimates of $0.96 in the third quarter with earnings per share of $1.08. Revenue of $6.85 billion beats expectations of $6.82 billion.
$DBX (+0,16%)
Dropbox:
Beat analyst estimates of $0.38 in the third quarter with earnings per share of $0.43. Revenue of $591 million exceeded expectations of $586.15 million.
$DASH (-1,3%)
DoorDash:
Missed analyst estimates of -$0.55 in the third quarter with earnings per share of -$0.77. Revenue of $1.7 billion exceeded expectations of $1.62 billion.
$GPRO (+0,55%)
GoPro:
Beat analyst estimates of $0.17 in the third quarter with earnings per share of $0.19. Revenue of $305 million exceeded expectations of $298.85 million.
$MSI (+0,29%)
Motorola Solutions:
Beats third-quarter analyst estimates of $2.88 with earnings per share of $3.00. Revenue of $2.37 billion beats expectations of $2.31 billion.
$HOT (+0,2%)
Hochtief:
Reached sales of 7.18 billion euros in the third quarter, up from 5.32 billion a year earlier, and earned 115 million euros on the bottom line, up from 99.8 million a year earlier. Order intake on a comparable basis was 6.5 billion (prior year 7.5 billion).
$K
Kellogg Co:
Surpassed analysts' estimates of $0.97 in the third quarter with earnings per share of $1.01. Sales of $3.95 billion exceeded expectations of $3.77 billion.
$RCL (-2,85%)
Royal Caribbean Cruises Ltd:
Beat analyst estimates of $0.19 in the third quarter with earnings per share of $0.26. Revenue of $3 billion exceeded expectations of $2.99 billion.
$UAA (-3,59%)
Under Armour Inc:
Second-quarter earnings per share of $0.20 beat analyst estimates of $0.10. Revenue of $1.57 billion exceeded expectations of $1.42 billion.
$W (+0,72%)
Wayfair Inc:
Missed analyst estimates of -$2.05 in the third quarter with earnings per share of -$2.11. Revenue of $2.8 billion below expectations of $2.82 billion.
$PTON (-0,72%)
Peloton Interactive Inc:
Missed analyst estimates of -$0.64 with first-quarter earnings per share of -$1.20. Revenue of $616.5 million below expectations of $637.07 million.
$DDOG (+5,22%)
Datadog Inc:
Third-quarter earnings per share of $0.23 beat analyst estimates of $0.16. Revenue of $437 million exceeded expectations of $415.07 million.
$MRNA (+1,54%)
Moderna Inc:
Missed analyst estimates of $4.81 in the third quarter with earnings per share of $2.53. Revenue of $3.36 billion below expectations of $4.63 billion.
$CROX (-0,46%)
Crocs Inc:
Missed analyst estimates of $2.62 in the third quarter with earnings per share of $2.50. Revenue of $985.1 million exceeded expectations of $942.52 million.
$IRM (+0,82%)
Iron Mountain Inc:
Third-quarter earnings per share of $0.48 beat analyst estimates of $0.44. Sales of $1.29 billion below expectations of $1.31 billion.
$SBS (-0,32%)
STRATEC:
Posts Q1-3 sales of €207.7 million (preliminary: €207.7 million), adjusted EBIT margin of 18.3% (preliminary: 18.3%), and net income (adjusted) of €29.5 million (PY: €40.6 million). Outlook confirmed.
$BOSS (+0,1%)
HUGO BOSS:
Achieves Q3 sales of €933 million (PY: €755, analyst forecast: €903.4 million), EBIT of €92 million (PY: €85 million, forecast: €88.1 million) and net income of €58 million (PY: €53 million, forecast: €56.6 million). In the outlook for 2022, the company now expects sales of €3.5 to €3.6 billion (previous: €3.3 to €3.5 billion) and EBIT of €310 to €330 million (previous: €285 to €310 million).
$SGL (+1,88%)
SGL CARBON:
Achieves Q1-3 sales of €853.9 million (previous year: €743.5 million), Ebitda (adjusted) of €136.1 million (previous year: €108.5 million) and net income after minorities of €70.6 million (previous year: €42.6 million). Forecast confirmed.
$PFV (+0,31%)
Pfeiffer Vacuum:
Achieves Q1-3 order intake of €866.5 million (preliminary: €866.5 million), sales of €668.7 million (preliminary: €668.7 million), EBIT of €94 million (preliminary: €94 million) and net income of €66.6 million (PY: €52.1 million). October 17 forecast for revenue and Ebit margin confirmed.
$HNR1 (-0,46%)
Hannover Re:
Achieves 3. Gross premiums written of €8.91 billion (PY: €7.15 billion, analyst forecast: €8.02 billion), combined ratio of 99.6% (PY: 101.5%, forecast: 99.6%), investment result of €400.3 million (PY: €491.1 million), an Ebit of €408.9 million (PY: €324.5 million, forecast: €399 million) and a net profit of €221.9 million (PY: €185.4 million, forecast: €311 million). In the outlook for 2022, the company sees net income in the lower range of €1.4 billion to €1.5 billion, profit target for 2022 remains achievable.
$UN01
Uniper:
Achieves 1st to 3rd. Quarter net result of -€40 billion (PY: -€4.8 billion), net loss includes €10 billion realized costs for replacement volumes; economic net debt at €10.91 billion (PY: €0.324 billion), net loss includes €31 billion expected losses and provisions; adjusted net loss of -€3.22 billion (preliminary: -€3.2 billion, prior year: +€0.487 billion), adjusted EBIT of -€4.75 billion (preliminary: -€4.8 billion, prior year: +€0.614 billion). Concrete earnings forecast currently impossible for the time being.
$O2D (-1,37%)
Telefonica Germany:
Achieves Q3 sales of €2.085 billion (PY: €1.967 billion, analyst forecast: €2.030 billion), service sales of €1.47 billion (PY: €1.42 billion), adjusted OIBDA of €642 million (PY: €613 million, forecast: €640.5 million). In the outlook for 2022, sales and OIBDA are now expected to be in the "lower mid-single-digit percentage range" compared to the previous year (previously: in the "low mid-single-digit percentage range").
$BMW (-0,47%)
BMW:
Reports Q3 sales of €37.18 billion (PY: €27.47 billion, analysts' forecast: €35.53 billion), EBIT of €3.68 billion (PY: €2.88 billion, forecast: €3.5 billion), EBT of €4.1 billion (PY: €3.42 billion) and net income of €3.18 billion (PY: €2.58 billion). Outlook confirmed.
$ZAL (+1,66%)
Zalando:
Achieves Q3 revenues of €2.34 billion (PY: €2.28 billion), Ebit (adjusted) of €13.5 million (PY: €9.8 million) and net result of -€35.4 million (PY: -€8.4 million); number of active customers grows by 8% and exceeds 50 million for the first time. Outlook confirmed.
$COP (-1,21%)
CompuGroup:
Posts Q1-3 revenue of €802 million (preliminary: €802 million), Ebitda of €166 million (preliminary: €166 million) and net income of €59.8 million (PY: 56.6 million). Outlook confirmed.
$RAA (-0,6%)
RATIONAL:
Achieves Q3 sales of €274.2 million (PY: €207 million, analyst forecast: €270 million), Ebit of €70.3 million (PY: €49.7 million, forecast: €64.4 million), Ebit margin of 25.6% (PY: 24.0%) and net income of €53.8 million (PY: €37.8 million). Forecast confirmed.
$KCO (+1,58%)
Klöckner & Co:
Achieves 3rd quarter sales of €2.37 billion (PY: €2.0 billion), Ebitda (adjusted) of €16 million (PY: €277 million) and net result of -€22 million (PY: +€185 million). Outlook confirmed.
#quartalszahlen
#boerse
#börse
#aktien
#paypal
#starbucks
#sandp500
#communityfeedback
#community

Títulos em alta
Principais criadores desta semana