
⠀
📊 𝐑𝐞𝐬𝐮𝐥𝐭𝐬
• GAAP EPS: $3.61 (Normalized Est. $4.50, not directly comparable), +7% YoY.
• GAAP Revenue: $8.893B (Est. $9.54B) ❌, -1% YoY.
• Adjusted Revenue: $9.793B, +9% YoY.
• GAAP Net Income: $2.717B, -1% YoY.
• Adjusted EPS Growth: +17% YoY.
• Gross Bookings Growth: +10% YoY, +11% constant currency.
• Adjusted EBITDA Margin: 47.0%, flat YoY.
• Adjusted Net Income Margin: 35.8%.
⠀
🎯 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
• Q4 Room Nights Growth: +1%–3% YoY.
• Q4 Gross Bookings Growth: +2%–4% YoY, +4%–6% constant currency.
• Q4 Adjusted Revenue Growth: 0%–2% YoY.
• Q4 Adjusted EBITDA Growth: Approximately flat YoY.
• FY2026 Adjusted Revenue Growth: High-single digits.
• FY2026 Adjusted EPS Growth: Low-to-mid teens.
⠀
📌 𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
• GAAP revenue missed consensus by ~6.8%, reflecting a $900M revenue reduction related to an FTC matter.
• Excluding the FTC adjustment, revenue increased 9% YoY to $9.793B.
• The FTC matter also resulted in a separate $100M accrued loss.
• Gross bookings grew 10%, supported by resilient travel demand and approximately 3% higher constant-currency average daily rates.
• Alternative accommodation room nights at Booking.com increased 7% YoY.
• Adjusted EPS increased 17% YoY despite relatively flat adjusted profit margins.
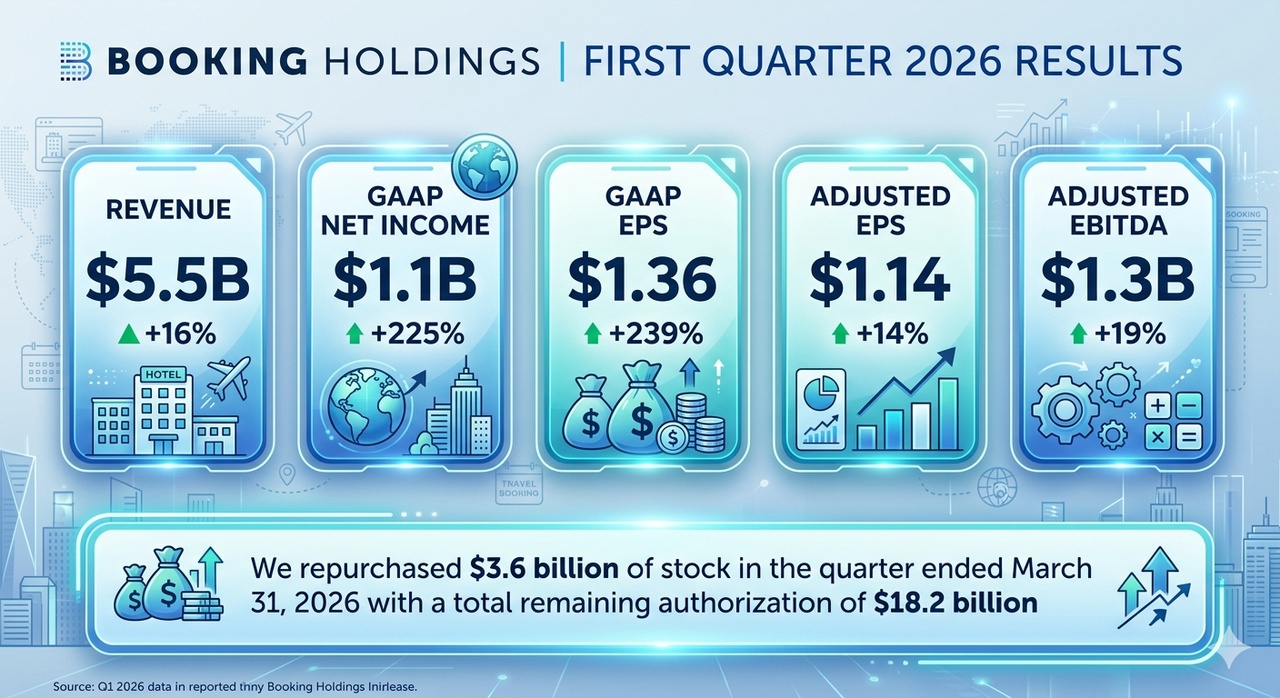
• Repurchased $2.1B in shares during Q3, with $12.4B remaining under its authorization.
• Q4 outlook reflects softer international travel demand, Middle East disruptions and elevated airfares.
• Direct bookings represented a mid-50% share of total room nights over the trailing four quarters.
• Declared a quarterly dividend of $0.42 per share, payable December 31.
⠀
💬 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐂𝐨𝐦𝐦𝐞𝐧𝐭𝐚𝐫𝐲
“As AI transforms the ways to discover, plan, and book travel, we continue to make progress integrating AI across our brands, developing AI-native experiences, and collaborating with industry-leading AI platforms.”