

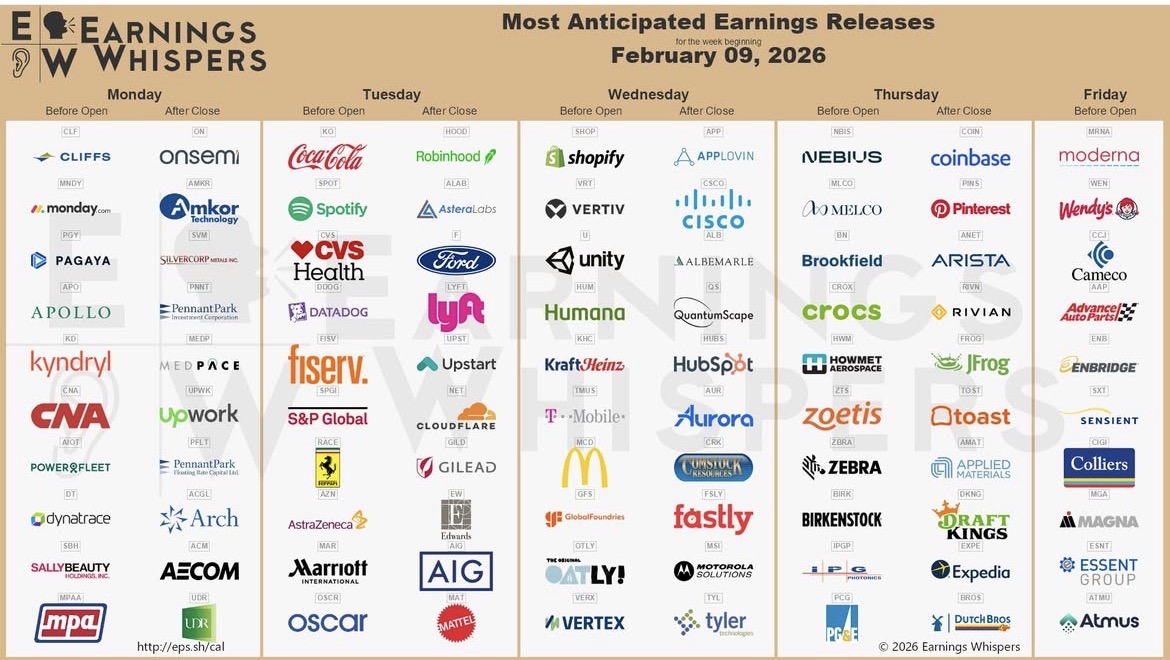
$MNDY (+3,6%)
$PGY
$APO (+0,17%)
$ON (+1,79%)
$AMKR (+0,8%)
$MEDP (+0,55%)
$UPWK (+1,21%)
$ACGL (+0,35%)
$ACM (-0,96%)
$KO (-0,16%)
$SPOT (-2,44%)
$CVS (+0,68%)
$DDOG (+5,69%)
$FI (+0,36%)
$SPGI (+0,22%)
$RACE (-0,54%)
$AZN (-0,54%)
$MAR (+1,11%)
$OSCR (+2,29%)
$HOOD (-2,39%)
$ALAB (+0,39%)
$F (-1,74%)
$LYFT (+1,51%)
$UPST (-1,74%)
$NET (+0,7%)
$GILD (-2,01%)
$EW (+0,99%)
$SHOP (+1%)
$VRT (-0,08%)
$HUM (+0,27%)
$KHC (-1,71%)
$MCD (+0,25%)
$9ZX1
$TMUS (-0,37%)
$APP (+1,49%)
$CSCO (-0,29%)
$ALB (-0,48%)
$HUBS (+0%)
$TYL (+0,28%)
$NBIS (+1,19%)
$BN (+0,09%)
$CROX (-2,28%)
$ZTS (+0,58%)
$BIRK (-2,66%)
$COIN (-2,86%)
$ANET (+3,72%)
$RIVN (-0,8%)
$TOST (+0,11%)
$AMAT (+0,82%)
$DKNG (+4,92%)
$WEN (-0,34%)
$CCO (-0,36%)
$ENB (-1,84%)
Crocs
Ação
Ação
Ticker: CROX
CROX
Price
Discussão sobre CROX
Postos
288Mês·
Will the sell-off continue next week?
1313
12 ComentáriosGehebeltes-EFH@Gehebeltes-EFH
8Mês
•
1212
•
11Mês·
Crocs Q3’25 Earnings Highlights
🔹 Revenue: $996.3M (Est. $961.61M) 🟢; -6.2% YoY
🔹 Adj. EPS: $2.92 (Est. $2.36) 🟢; -18.9% YoY
🔹 Gross Margin: 58.5%; -110 bps YoY
Q4’25 Guidance
🔹 Adj. EPS: $1.82–$1.92 (Est. $1.75) 🟢
🔹 Revenues to be down 8% YoY 🟡
🔹 Crocs Brand to be down 3% YoY
🔹 HEYDUDE Brand to be down mid-20% YoY
🔹 Adj. Op Margin: ~15.5%
🔹 Tax Rate: GAAP ~20%
🔹 FY25 CapEx: $70M–$75M
Segment (YoY)
Crocs Brand
🔹 Revenue: $836M; DOWN -2.5% (CC -3.2%)
🔹 DTC: $472M; UP +2.0% (CC +1.2%)
🔹 Wholesale: $364M; DOWN -7.9% (CC -8.4%)
🔹 North America: $448M; DOWN -8.8%
🔹 International: $389M; UP +5.8% (CC +4.2%)
HEYDUDE
🔹 Revenue: $160M; DOWN -21.6% (CC -21.7%)
🔹 DTC: $91M; DOWN -0.5% (CC -0.7%)
🔹 Wholesale: $69M; DOWN -38.6% (CC -38.7%)
Other Metrics
🔹 DTC Revenue (Consolidated): UP +1.6% (CC +0.9%); Wholesale: DOWN -14.7% (CC -15.1%)
🔹 Share Repurchases: 2.4M shares for $203M (avg. ~$83.03); Authorization remaining ~$927M
🔹 Debt Paydown: $63M
🔹 Cash: $154M | Inventories: $397M | Total Borrowings: $1.32B
CEO Commentary
🔸 “Results came in ahead of expectations… strong cash flow enabled repurchase of 2.4M shares and $63M debt paydown. We see greater potential across both brands and are working to re-gain momentum.” — CEO Andrew Rees
🔸 “Beyond the $50M 2025 gross cost savings, we’ve identified an incremental $100M and are committed to driving operating leverage in 2026.”


1Ano·
Today’s Screen
Today, I’m looking for stocks with > 10% Shareholder yield, FCF yield, and Earnings yield (my personal magic formula) but I’ve also included > 10% Tangible BVPS (5 year) CAGR and a minimum market cap of $500 million for this screen. This combines lots of data into one simple screen covering quality, valuation, and shareholder orientation, while eliminating the smallest companies with skewed numbers.
I like to screen until I’m down to 10-30 stocks, to generate a list of quality companies, trading at fair or below fair prices, to dig deeper into. Here are today’s results:
I currently own Chord and Crocs in different portfolios. Have owned Tri-Point Homes, United Airlines, and Macy’s in the past.
22
1Ano·
Crocs Q1'25 Earnings Highlights
🔹 Adj EPS: $3.00 (Est. $2.49) 🟢
🔹 Revenue: $937M (Est. $907.9M) 🟢; +1.4% YoY (cc)
🔹 Inventories: $391M (Flat YoY)
FY25 Guidance Withdrawn
🔹 Prior guide was EPS $12.70–13.15; Revenue growth +2–2.5%
🔹 Withdrawal due to macro/trade-policy uncertainty
Brand & Segment Highlights
Crocs Brand
🔹 Revenue: $762M; +2.4% YoY (+4.2% cc)
🔹 DTC Revenue: $285M; +1.1% YoY (+2.5% cc)
🔹 Wholesale Revenue: $477M; +3.2% YoY (+5.3% cc)
🔹 North America: $369M; -3.8% YoY (-3.4% cc)
🔹 International: $393M; +8.9% YoY (+12.3% cc)
HEYDUDE Brand
🔹 Revenue: $176M; -9.8% YoY (-9.5% cc)
🔹 DTC Revenue: $65M; +8.3% YoY
🔹 Wholesale Revenue: $111M; -17.9% YoY
Other Key Metrics:
🔹 Gross Margin: 57.8% (vs. 56.0% YoY)
🔹 Adj Oper Margin: 23.8% (vs. 27.1% YoY)
🔹 Cash: $166M (vs. $159M YoY)
🔹 Debt: $1.48B (vs. $1.73B YoY)
🔹 CapEx: $15M (vs. $16M YoY)
🔹 Share Buybacks: $61M (0.6M shares @ avg $100.23)
🔹 $1.3B in remaining repurchase authorization
CEO Andrew Rees Commentary
🔸 “Proud of our Q1 outperformance despite volatility—both Crocs and HEYDUDE contributed to upside.”
🔸 “The current environment presents an opportunity to gain share as we focus on execution and lean into our competitive advantages.”
🔸 “We’re remaining disciplined and transparent while navigating a rapidly shifting trade landscape.”
33
1Ano·
Buy Crocs share
I made a fairly random purchase of Crocs $CROX (-2,28%) share today. Looks clean on the chart and is also doing well operationally. What is your opinion on the share?

1Ano·
Crocs Q4'24 Earnings Highlights:
🔹 Q4 Adj. EPS: $2.52 (Est. $2.22) 🟢
🔹 Q4 Revenue: $990M (Est. $961.92M) 🟢; UP +3.1% YoY
🔸 Upsized Buyback by $1B
FY25 Guidance:
🔹 Adj. EPS: $12.70–$13.15 (Est. $12.74) 🟢
🔹 Revenue Growth: +2% to +2.5% YoY (Includes $62M negative FX impact)
🔹 Crocs Brand Revenue: +4.5% YoY
🔹 HEYDUDE Brand Revenue: DOWN -7% to -9% YoY
🔹 Adj. Operating Margin: ~24%
Q1'25 Outlook:
🔹 Revenue: DOWN -3.5% YoY (Includes $19M negative FX impact)
🔹 Crocs Brand Revenue: FLAT to DOWN -1% YoY
🔹 HEYDUDE Brand Revenue: DOWN -14% to -16% YoY
🔹 Adj. EPS: $2.38–$2.52
🔹 Adj. Operating Margin: ~21.5%
Q4 Segment Performance:
Crocs Brand:
🔹 Revenue: $762M (Est. $747.10M) 🟢; UP +4% YoY
🔹 DTC Revenue: $447M; UP +5% YoY
🔹 Wholesale Revenue: $315M; UP +2.7% YoY
HEYDUDE Brand:
🔹 Revenue: $228M (Est. $214M) 🟢; FLAT YoY
🔹 DTC Revenue: $133M; UP +7.2% YoY
🔹 Wholesale Revenue: $95M; DOWN -8.6% YoY
Geographic Performance:
🔹 North America: $471M; FLAT YoY
🔹 International: $291M; UP +11.5% YoY
FY24 Segment Performance:
Crocs Brand:
🔹 Revenue: $3.28B; UP +8.8% YoY
🔹 DTC Revenue: $1.67B; UP +9.9% YoY
🔹 Wholesale Revenue: $1.61B; UP +7.6% YoY
HEYDUDE Brand:
🔹 Revenue: $824M; DOWN -13.2% YoY
🔹 DTC Revenue: $368M; DOWN -3.9% YoY
🔹 Wholesale Revenue: $456M; DOWN -19.5% YoY
Other Key Metrics:
🔹 Q4 Gross Margin: 57.9% (Est. 56.32%) 🟢; UP +220 bps YoY
🔹 Q4 Adj. SG&A: $373M; 37.7% of revenue, UP +23% YoY
🔹 FY24 Operating Margin: 24.9% (Adj.: 25.6%)
🔹 Operating Cash Flow: $990M in FY24
🔹 Debt Repayment: $323M in FY24
🔹 Share Repurchases: $551M in FY24
Shareholder Updates:
🔸 New Share Repurchase Authorization: Upsized by $1B, totaling $1.3B available
Management Commentary:
🔸 CEO Andrew Rees: "We delivered another record year with strong revenue and earnings growth, particularly from Crocs Brand. HEYDUDE's direct-to-consumer growth is encouraging, and we remain focused on reigniting momentum."
33

1Ano·
How to Invest in the rapidly growing ADHD market. $COLL (-0,97%) , a value stock with promising growth!
Collegium Pharmaceutical is a specialty pharmaceutical company that engages in the development and commercialization of medicines for pain management.
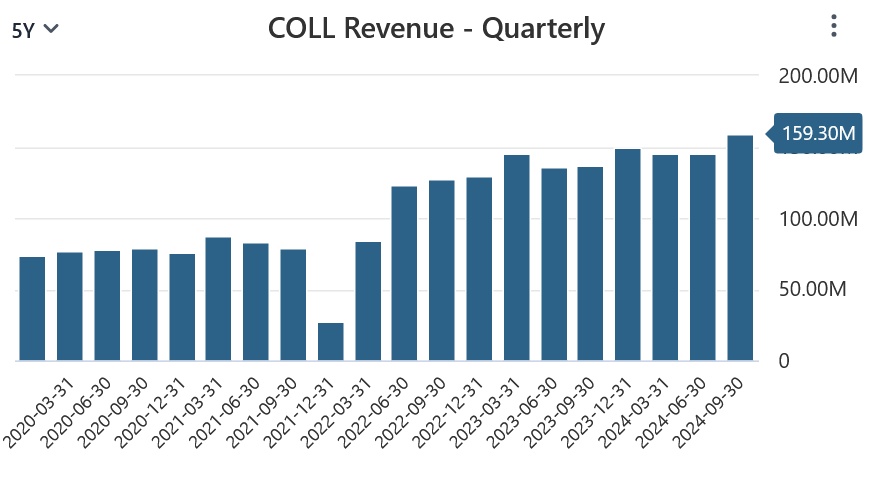
The company is not missing a beat. They are growing revenue quarter after quarter and I believe they are worth a second look. Let me give you some quick insights!
$COLL (-0,97%) has become part of Joel Greenblatt Magic Formula List in August 2023. Since then it has never graduated from the List even after the stock gained over 75%. This suggest that this stock is heavily undervalued. *You can find the updated Magic Formula list at the bottom of this post.
Recently, after going through an acquisition that impacted negatively the financials with one time items, the stock dropped significantly opening up new opportunities to buy in.
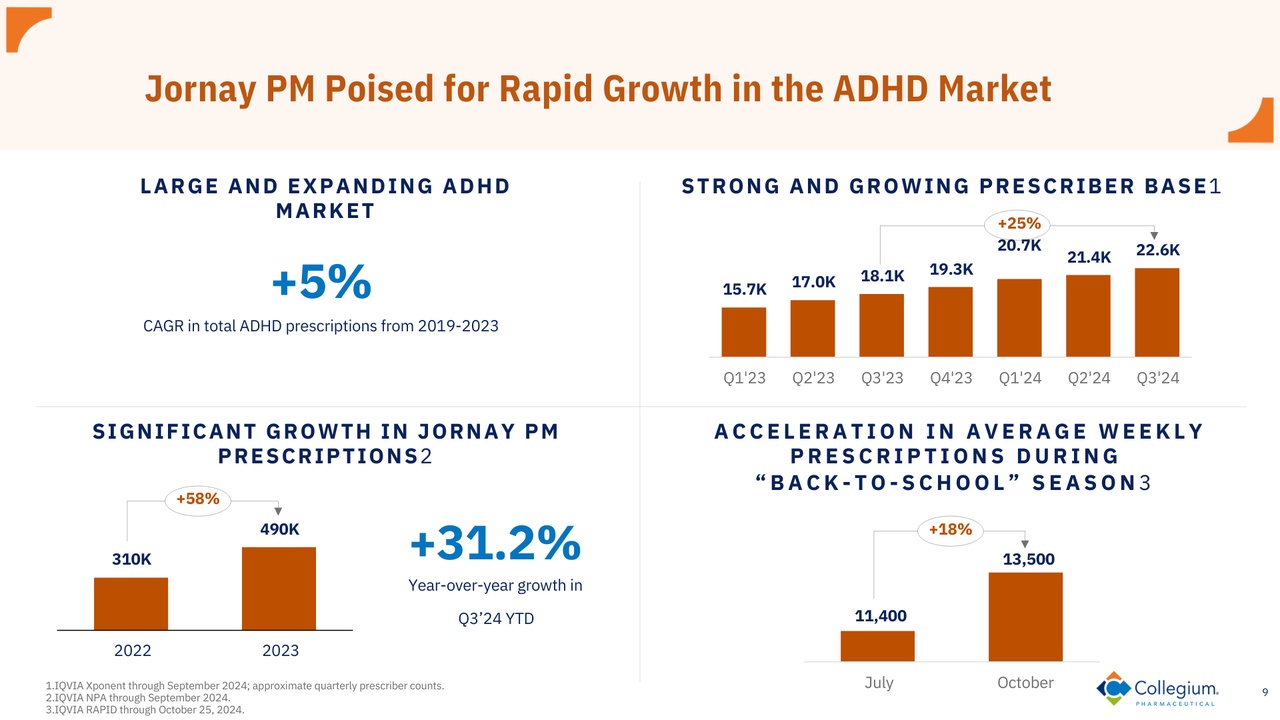
The new acquisition is very promising and will likely drive future growth. $COLL (-0,97%) bought Ironshore that had an established presence in neurology (ADHD) with Jornay PM. The ADHD market is projected to reach $30.6 billion by 2032.
Collegium reported strong Q3 2024 results, with 17% YoY revenue growth and EBIT margins improving to 35.2%, showcasing operational efficiency.
Still, $COLL (-0,97%) faces risks, including high financial debt, integration challenges for Jornay PM, and potential revenue concentration in pain management products.
At the same time, the management is executing very well on important areas:
- Improving the health of the company by paying out debt;
- Promoting a share repurchase program
I believe Collegium has compelling valuation metrics and good growth projections that indicate good upside potential.
In conclusion I think Collegium Pharmaceutical's earnings potential is at least as good as it seems, and maybe even better!
Considering all the above, I don't see many reasons against taking a position on this stock right now and holding it for one year as ruled by Joel Greenblatt.
Magic Formula's list (09/12/2024)
- $MO (-0,78%)
- $AMCX (-0,55%)
- $BWMX (-0,69%)
- $BTMD
- $BMBL
- $COLL (-0,97%)
- $CCSI
- $CROX (-2,28%)
- $DESP
- $TRDA
- $GTX (-4,15%)
- $GCT (+1,18%)
- $HRMY
- $HSII
- $HPQ (+0,52%)
- $INVA (+1,62%)
- $IPG
- $JILL (-1,83%)
- $MED (+1,89%)
- $PARA (-2,45%)
- $MD (-0,41%)
- $PRDO (+0,33%)
- $PLTK (-1,6%)
- $PBYI
- $RGS (+1,16%)
- $RMNI (+1,12%)
- $SIGA
- $SIRI
- $UIS (+1,8%)
- $VYGR (+8,4%)
22
1Ano·
$CROX (-2,28%), is it a value bet?
$CROX (-2,28%) is a notorious stock for Magic Formula investors. Year after year it comes back into the list (you can find the latest Magic formula list after the picture down below).
Both Revenue and Cash flow keep on growing quarter after quarter, but the stock price keeps on following a wavy pattern. It runs up for a while trying to close the valuation gap and then suddenly it pulls back. Let's try to understand the current situation.
------
$CROX (-2,28%) is currently trading at a notable low price-to-earnings (P/E) multiple, well below the averages of the Textile – Apparel industry and the broader Retail-Wholesale sector. With a forward 12-month P/E of 8x, the CROX stock reflects a discount to the industry average of 13.77x and the Consumer Discretionary sector’s average of 19.65x.
$CROX (-2,28%) Stock Looks Undervalued
This shows the CROX stock is undervalued relative to its industry peers, presenting an attractive opportunity for investors seeking exposure to the Consumer Discretionary sector.
Crocs stock price has surged 13.5% year to date, significantly outpacing the industry’s decline of 12.8%. This performance can be attributed to the company’s strategic initiatives, including robust market expansion and product diversification efforts.
Factors Driving the Brand
Crocs is advancing its long-term strategy with key initiatives focused on sustainable growth. The company’s approach centers on three main pillars. These include elevating iconic products across brands to boost awareness and relevance, marketing, digital and retail expansion, and diversifying its product range to appeal to a broader consumer base.
Crocs has strategically expanded its product range, leveraging diversification to attract a broader consumer base. The Crocs brand’s remarkable growth in global awareness and desirability has been fueled by innovative collaborations and unique product offerings.
Current Pressures on CROX
Despite all the positives, Crocs' HEYDUDE brand underperformed, with revenues dropping 17.4% year over year in the third quarter. This decline was led by a 22.9% fall in wholesale revenues and a 9.3% drop in direct-to-consumer (DTC) revenues. Comparable DTC sales for the HEYDUDE brand also decreased by 22.2%.
Looking ahead, Crocs anticipates a relatively subdued consumer environment in the United States until the Black Friday/Cyber Monday holiday period. Per the company, the industry saw heightened promotional activities in China during the mid-season festival, reflecting a more conservative approach by China consumers. As a result, the company expects to see a greater pullback in major cities like Shanghai and Beijing.
Given the challenging macroeconomic conditions, Crocs has issued a cautious outlook for the fourth quarter and 2024, anticipating flat-to-slight revenue growth year over year, in constant currency. The Crocs brand is expected to grow 2% in the fourth quarter, while HEYDUDE revenues may decline 4-6%. International growth is projected to slow due to regulatory challenges in India, and North America faces consumer selectivity and wholesale timing pressures, though DTC revenues remain positive.
For 2024, enterprise revenues are projected to increase 3% year over year in constant currency, which is at the lower end of the previously guided 3-5% growth. Revenues for the Crocs brand are expected to grow 8%, while HEYDUDE brand revenues are anticipated to decline 14.5% due to weaker-than-expected sellouts in both wholesale and digital channels. Previously, management had estimated the Crocs brand’s revenues to grow 7-9% and HEYDUDE’s revenues to decrease 8-10%.
Investment Opinion on CROX
You may find Crocs stock attractive for its undervaluation compared to industry peers, with a lower price-to-earnings ratio. Given strategic initiatives, margin improvements, successful partnerships and a focus on sustainability, the stock presents a compelling investment opportunity for those looking to capitalize on the company’s growth trajectory.
However, CROX faces challenges, including soft revenue expectations, struggles with the HEYDUDE brand and headwinds in China, which could impact its near-term performance. These factors introduce some uncertainty, suggesting a more cautious approach to investing in Crocs at this stage.
Magic Formula's list (01/12/2024)
- $MO (-0,78%)
- $AMCX (-0,55%)
- $BWMX (-0,69%)
- $BTMD
- $BMBL
- $COLL (-0,97%)
- $CCSI
- $CROX (-2,28%)
- $DESP
- $TRDA
- $GTX (-4,15%)
- $GCT (+1,18%)
- $HRMY
- $HSII
- $HPQ (+0,52%)
- $INVA (+1,62%)
- $IPG
- $JILL (-1,83%)
- $MED (+1,89%)
- $PARA
- $MD (-0,41%)
- $PRDO (+0,33%)
- $PLTK (-1,6%)
- $PBYI
- $RGS (+1,16%)
- $RMNI (+1,12%)
- $SIGA
- $SIRI
- $UIS (+1,8%)
- $VYGR (+8,4%)

1Ano·
3 interesting stocks to analyze further!
A quick summary of my analysis on these 3 stocks.
*These stocks were selected from the Magic Formula's list you can find down below after the picture.
Stocks that ends up in the Magic Formula's list are normally beaten up for some reason. I illustrate them as well in my quick analysis.
$HRMY is a commercial-stage pharmaceutical company, focuses on developing and commercializing therapies for patients with rare and other neurological diseases in the United States.
Good news:
- Both revenues and earnings have been growing meaningfully.
- Strong conversion of profit to free cash flow.
- Good momentum
Bad news:
- The most recent earnings report presented headline numbers that were considered soft by shareholders.
Is this stock beaten up for a valid reason?
Frankly I think this is good pick and I don't see any reason why this should not be held into your portfolio for 1 year as advised by Joel Greenblatt. It really sticks out at as one of the market's strongest value stocks in my opinion.
$GCT (+1,18%) is a Chinese comprehensive B2B ecommerce solutions for large parcel merchandise in the United States. On some aspects it looks similar to Alibaba.
Good news:
- Growth on all numbers
- Share repurchase program
- Considered a potential multibagger by many analyst
Bad news:
- Next US presidency is hostile to China imports
Is this stock beaten up for a valid reason?
Many times in the past this company has been beaten up because of it's Chinese origin. Many allude on numbers too good to be true others are scared by the next US presidency. To make it short... there is a lack of trust in this company and it's future. It's undeniably a good company, but will the lack of trust ever evaporate? And will Trump's actions have any effect on it?
$BWMX (-0,69%) is a direct-to-consumer company selling housewares in the United States and Mexico.
Good news:
- Profit was recently significantly reduced by unusual items. It's never great to see unusual items costing the company profits, but on the upside, things might improve sooner rather than later. Unusual items are often not repeated. If those unusual expenses won't repeat, then all else being equal I'd expect its profit to increase over the coming year.
- Constant revenue growth quarter after quarter.
- Very high dividend yield.
Bad news:
- High level of debt.
- Shareholders have been substantially diluted recently.
- Negative momentum.
Is this stock beaten up for a valid reason?
At the moment I believe so, but as soon as the profits rectify, I can see the stock price jumping and finally recognising the true value of the company. But it's kind of a bet on when this will happen. If you are in for the high dividend, you are patient and you are ready to take some risks this might be the stock for you.
Magic Formula's list (24/11/2024)
- $MO (-0,78%)
- $AMCX (-0,55%)
- $BWMX (-0,69%)
- $BTMD
- $BMBL
- $COLL (-0,97%)
- $CCSI
- $CROX (-2,28%)
- $CTMX (+3,47%)
- $TRDA
- $GTX (-4,15%)
- $GCT (+1,18%)
- $HRMY
- $HSII
- $HPQ (+0,52%)
- $INVA (+1,62%)
- $IPG
- $JILL (-1,83%)
- $MED (+1,89%)
- $PARA (-2,45%)
- $MD (-0,41%)
- $PRDO (+0,33%)
- $PLTK (-1,6%)
- $PBYI
- $RGS
- $RMNI (+1,12%)
- $SIGA
- $SIRI
- $UIS (+1,8%)
- $VYGR (+8,4%)
#magicformula
#multibagger
#tenbagger
#joelgreenblatt
#greenblatt
44

1Ano·
Strike: €98.00
Expiry: 20.12.2024
Not a typical move (no LEAP)..... but this one will pay for many Christmases! 😂🤣😅
This is the way to go!
Yes. I only own one flip flop of their shoes and once gifted one to my nephew that I bought from tkmaxx a year ago...... but an 80% gross margin company that pours liquid plastic into a mold to sell for €40+, with soaring profit estimates and a clear plan to enter new markets in Southeast Asia is on my radar. This is a TRADE based on KTS #?? ahead of the vacation season...... but I will make further investment moves on it before the peak of the cycle.
22
2 Comentários
Every time I see someone in those things, it lifts me up a bit. They don't work for me at all...
••
Títulos em alta
Principais criadores desta semana
Dados tempo real da LSX · Dados financeiros e EOD da FactSet