
$UNH (+1,88%)
$DHI (-2,58%)
$RTX (-0,26%)
$HAL (-1,4%)
$MMM (-1,33%)
$NOC (-0,53%)
$MSCI (-0,71%)
$IBKR (-1,55%)
$ISRG (+1,59%)
$COF (-0,67%)
$BN (-1,21%)
$EQT (+0,8%)
$ABBN (-0,83%)
$GEV (-0,94%)
$T (-0,96%)
$CME (+0,6%)
$PM (-1,51%)
$MCO (-0,81%)
$BA (+1,14%)
$UAL (-0,47%)
$OR (-0,6%)
$TXN (-0,06%)
$LRCX (+2,9%)
$NOW (+2,88%)
$IBM (+2,26%)
$TSLA (+4,51%)
$000660
$018260
$NESN (+0,32%)
$SAAB B (+0,23%)
$DSY (+0,89%)
$NOKIA (-0,27%)
$ASC (+0,36%)
$ROG
$NDAQ (-0,54%)
$DOW (+0,6%)
$KDP (-0,1%)
$AAL (-3,64%)
$LMT (+0,1%)
$AXP (+1,44%)
$BX (+0,67%)
$FCX (+0,32%)
$SAP (+1,3%)
$INTC (+2,77%)
$NEM (-0,08%)
$FIX (+2,55%)
Freeport McMoRan
Ação
Ação
Ticker: FCX
FCX
Price
Discussão sobre FCX
Postos
206Mês·
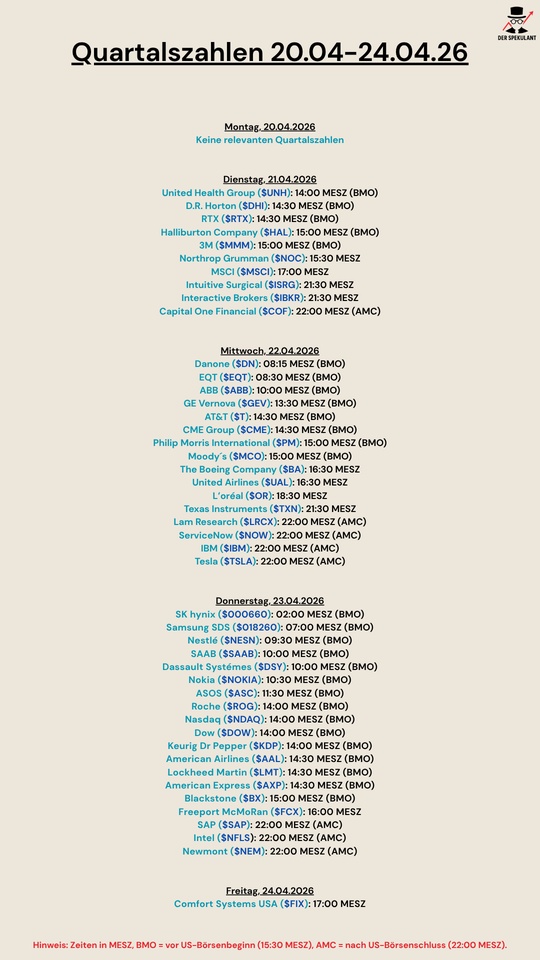
Quarterly figures 20.04-24.04.26
1212

9Mês·
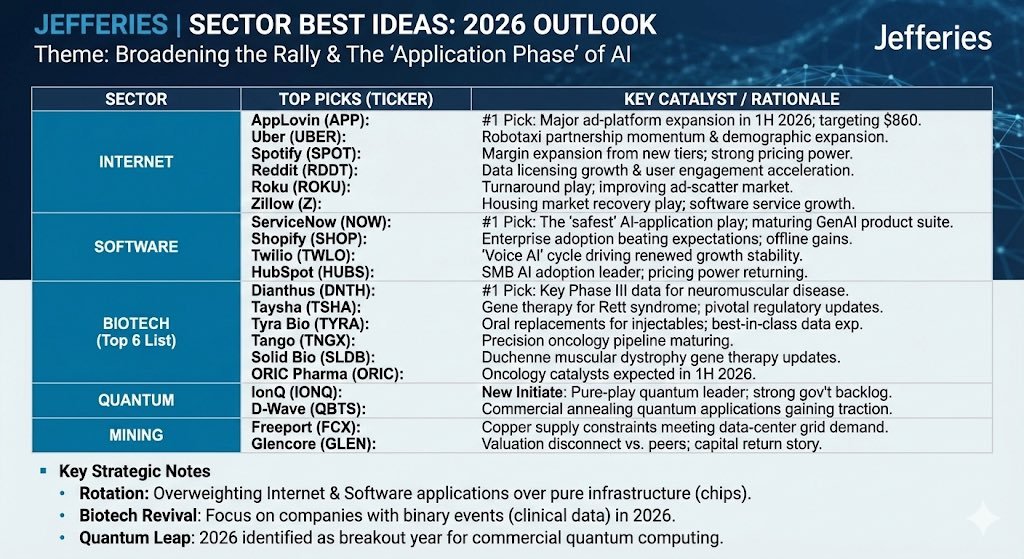
Equities | Jeffries best sectors ideas
$JEF (-2,18%) Top picks per sector for 2026
$APP (+1,19%) , $UBER (-0,02%) , $SPOT (-1,59%) , $RDDT , $ROKU (+0,9%) , $Z (+0,04%) , $NOW (+2,88%) , $SHOP (+1,26%) , $TWLO (+6,13%) , $HUBS (+0%) , $DNTH (+3,11%) , $TSHA , $TYRA , $TNGX , $SLB (+0,21%) , $ORIC (+3,09%) , $IONQ (-2,27%) , $QBTS (-0,09%) , $FCX (+0,32%) , $GLEN (-2,9%)
1111
26 Comentários
Get_Rich_or_Die_Tryin@Get_Rich_or_Die_Tryin
9Mês
••
Ver todas as 25 restantes respostas


9Mês·
Copper Mines Special
Hello my dears,
After my gold mining special, I have now delved even deeper into the world of copper mines.
Copper is experiencing a renaissance as a strategic commodity of the future. At over USD 11,900 per tonne on the London Metal Exchange, the red metal is reaching historic highs - and this is more than just a cyclical swing. The combination of scarce supply, geopolitical risks and explosive growth in demand from AI data centers and electromobility is creating an environment from which selected mining companies can benefit disproportionately. Structural supercycle on the rise: the figures speak for themselves.
Why copper
DID YOU KNOW THAT?
- The typical battery-powered electric vehicle requires about four times as much copper than a conventional combustion vehicle.
- Copper is one of the most widely used metals in the world and one of the most widely recycled.
The scarcity of copper
- We are currently seeing a significant gap in the inability of global copper mine supply to meet long-term demand expectations due to new copper projects, declining grades and increasing social and technical challenges in bringing new projects on stream.
10,000 years
Copper is the oldest mined metal known to man and has been used for over 100 centuries
400 +
copper alloys are currently used, including brass and bronze
33 %
Current demand is met by recycled copper
18 elements
including gold, silver, cobalt and molybdenum are by-products of copper mining
I have picked out 8 mines. But I haven't found a clear favorite, so I need your help with the selection this time.
Which mine is your favorite?
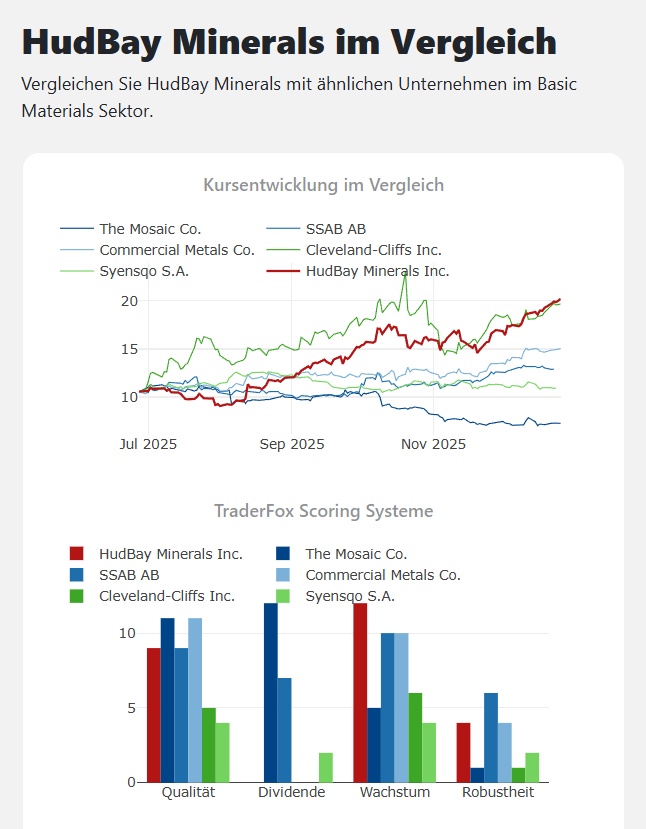
In the quality and growth check are
- HudBay Minerals $HBM (+1,16%)
Freeport-MCMoRan $FCX (+0,32%)
the winners.
In a few years, Hudbay will celebrate its 100th anniversary
Hudbay is a copper-focused mining company with three long-life operations and a world-class pipeline of copper growth projects in the category mining regions of Canada, Peru and the United States.
Hudbay's operating portfolio includes the Constancia mine in Cusco, Peru, the Snow Lake operations in Manitoba, Canada and the Copper Mountain mine in British Columbia, Canada. Copper is the company's main metal, complemented by significant gold production. Hudbay's growth pipeline includes the Copper World project in Arizona, the Mason project in Nevada (USA), the Llaguen project in La Libertad (Peru) and several expansion and exploration opportunities close to existing operations.
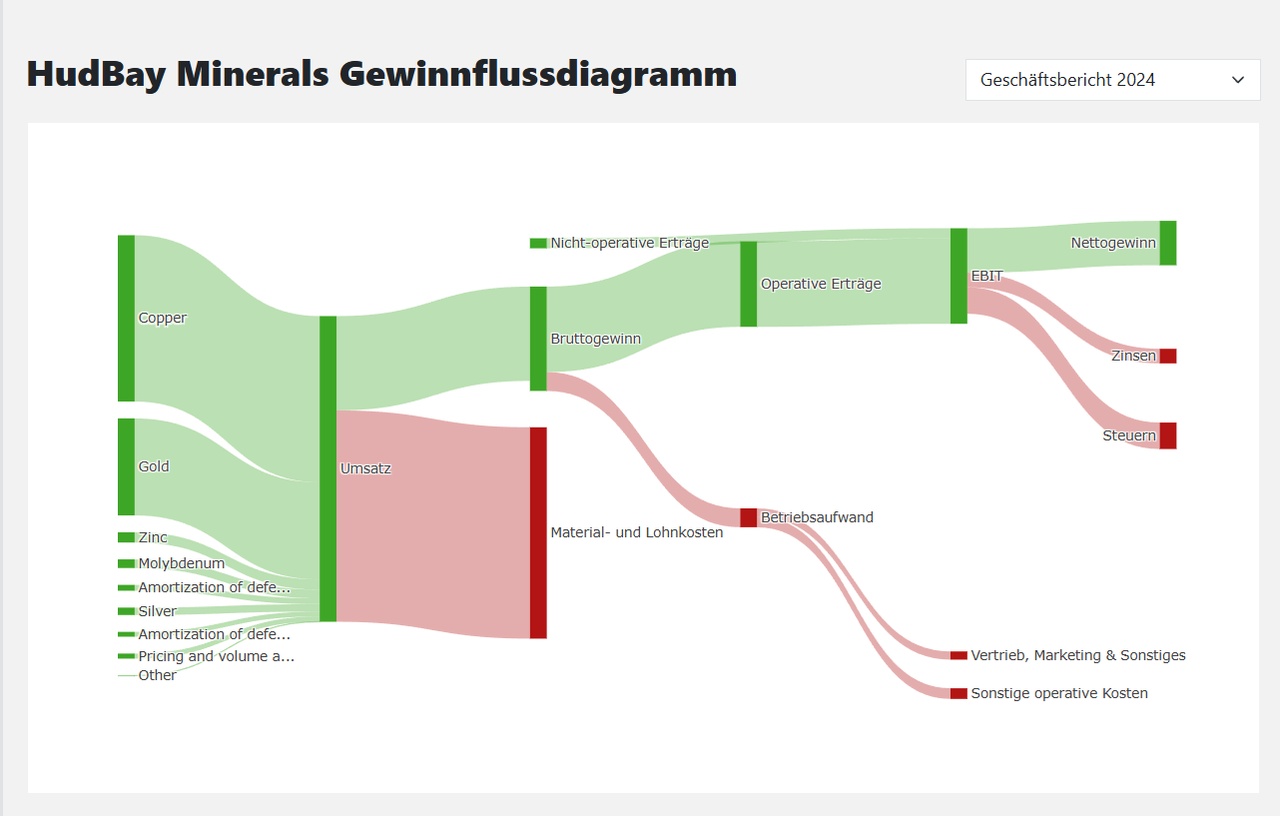
HudBay Minerals Inc. is a resource mining (metals/coal) and resource extraction (diamonds/precious metals) company headquartered in Canada. The HudBay Minerals share is traded under ISIN CA4436281022. In the past financial year, HudBay Minerals generated sales of CAD 2,720.74 million, which corresponds to growth of 19.69% compared to the previous year. Operating profit amounted to CAD 544.97 million, an improvement of 27.85%. Net income for the year amounted to CAD 105.08 million, an improvement of 17.31%. On the balance sheet date, the company had total assets of CAD 7,892.27 million. Reported equity amounted to CAD 3,807.49 million, which corresponds to an equity ratio of 48.24%. Total debt amounted to CAD 1,700.38 million, with a debt to asset ratio of 21.54%. HudBay Minerals employed 2,803 people at the end of the financial year, an increase of 3.51 % compared to the previous year. Revenue per employee amounted to CAD 0.97 million. The company paid a dividend of CAD 0.02 per share for the past financial year, which corresponds to a dividend yield of 0.17 %. The price/earnings ratio (P/E ratio) is 41.81 and the price/book ratio (P/B ratio) is 1.25.
Planning for the future
We have laid the foundations for a new phase of growth based on our long history and proven track record in project development. Our near-term growth profile includes the high-grade Pampacancha satellite camp at our Constancia mine in Peru and the expanded gold and copper-gold zone at our Lalor mine in Snow Lake, Manitoba. Our world-class pipeline includes the recent discovery of the Copper World Complex project in Arizona, as well as the Mason deposit in Nevada, and you will see significant, high-grade properties where we are already in the planning stages of how to unlock their value. Over time, we look forward to expanding our exploration program into Arizona and Nevada.
Is HBM's Copper World JV with Mitsubishi a potential breakthrough?
- HBM signs a $600 million deal with Mitsubishi for a 30% stake in the construction of the Copper World Project.
- HBM's Copper World is in line with Washington's mission to rebuild a domestic supply chain for critical minerals.
- The deal helps HBM defer its initial capital requirements until at least 2028 and increase the IRR owed to 90%.
Ist HBMs Copper World JV mit Mitsubishi ein potenzieller Durchbruch? - 18. November 2025 - Zacks.com
Year
Earnings per share
P/E RATIO
2025 0,84 23,98
2026 1,42 14,20
2027 1,63 12,40
2028 1,89 10,72
Market capitalization in EUR billion 6,69
year
Profit in million
2025 522,65
2026 562,29
2027 642,31
2028 638,73
2029 1.106,00
Year
Free cash flow in € million
2025 237,76
2026 523,46
2027 621,44
2028 416,93
2029 803,64
HBM_InvestorPresentation_November2025_final.pdf
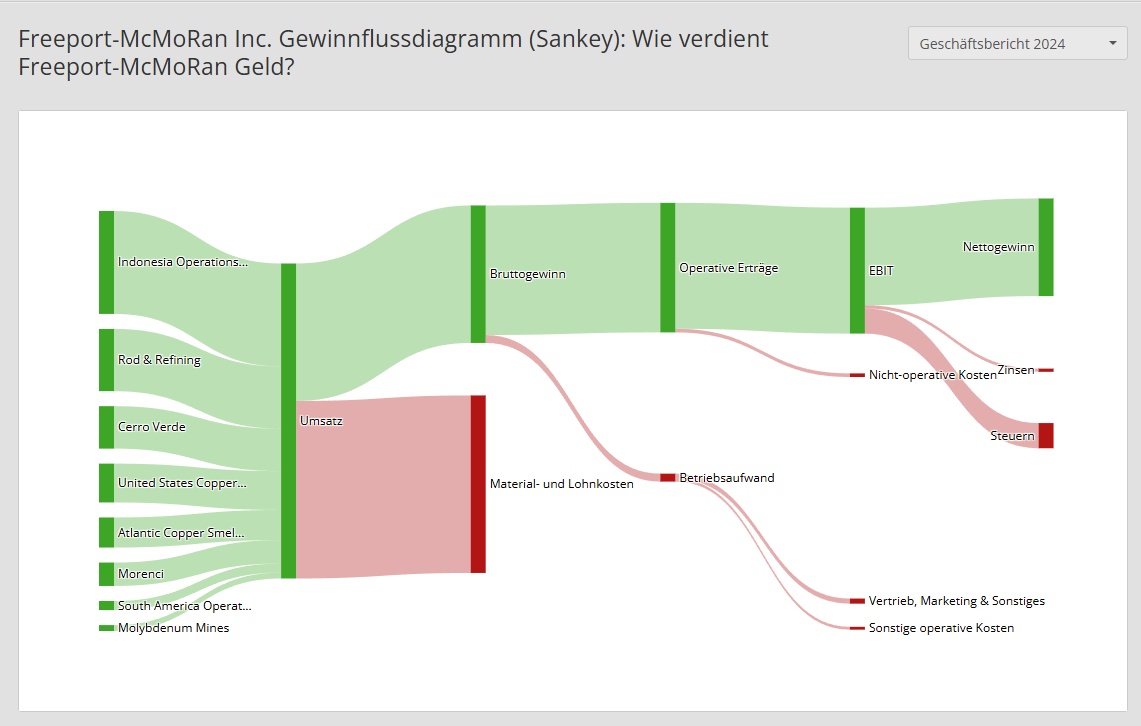
Freeport-McMoRan (FCX) is a leading international metals company dedicated to being a leader in copper. Our company was incorporated under the laws of the State of Delaware on November 10, 1987 and is headquartered in Phoenix, Arizona. We operate large, long-lived, geographically diverse assets with significant proven and probable copper, gold and molybdenum reserves. Our portfolio of assets includes the Grasberg mineral district in Indonesia, one of the largest copper and gold deposits in the world; and significant operations in the Americas, including the large-scale Morenci mineral district in North America and the Cerro Verde asset in South America.
Freeport-McMoRan Inc ("FCX"), formerly known as Freeport-McMoRan Copper & Gold Inc, was formed in 1988 following the discovery of the Grasberg copper and gold deposit in Papua, Indonesia, when FCX's former parent company, then known by the trading symbol "FTX", sold 20 percent of the company in an initial public offering. or IPO. Following the acquisition of Phelps Dodge in 2007, FCX emerged as a dynamic industry leader, combining the assets and technical teams of two great companies. FCX's unique portfolio of mining assets was developed and acquired from several predecessor companies, including Freeport Minerals, Phelps Dodge, Cyprus Minerals, American Metal Company (AMAX) and Climax Molybdenum, among others. The many important milestones that have occurred over the decades make FCX's portfolio of assets difficult to replicate today.
Freeport was named among the ten most transparent companies in the US.
Freeport wurde zu den zehn transparentesten Unternehmen in den USA gewählt | Freeport-McMoRan
Freeport named among leading companies using AI to achieve results
Baghdad autonomous train fleet retrofit fully implemented
Umbau der autonomen Zugflotte Bagdad vollständig umgesetzt | Freeport-McMoRan
Freeport-McMoRan is the quality commodity with comeback potential
Freeport-McMoRan Inc. (ISIN: US35671D8570) operates significant copper, gold and oil and gas reserves worldwide. It is the world's largest molybdenum producer. The foundations of the company were laid by the merger of Freeport Minerals and McMoRan Oil & Gas in 1981. The company was listed on the NYSE in 1988 and its shares have been freely tradable since 1955.
With a return on equity of 15 % and average double-digit growth rates over the last 5 years, Freeport-McMoRan has the qualities to be considered as a long-term investment. This is also illustrated by the good result of 12/15 points in the TraderFox quality check. In addition, the company regularly distributes dividends to shareholders, allowing investors to participate directly in the profits.
Rohstoffe im Rallye-Modus: Diese 3 Aktien gehören aktuell zu den größten Gewinnern
Pivotal-Point tracking Freeport McMoRan. (FCX): Copper giant benefits from strong quarterly figures and all-clear in Grasberg - UBS sees price target at USD 55!
15.12.2025 at 13:00
Freeport-McMoRan is a mining company with a focus on copper, molybdenum and gold. Freeport already reported impressive figures for the 3rd quarter on October 24. At USD 0.35, adjusted earnings per share were well above expectations of USD 0.27. Revenue reached USD 5.82 billion, which was also above the estimated USD 5.65 billion. On November 18, 2025, Freeport-McMoRan announced plans to resume large-scale production in the Grasberg mining district in Indonesia following a serious incident (sludge collapse) in September.
Year
Earnings per share USD
P/E RATIO
2025 1,51 35,20
2026 2,22 23,95
2027 2,93 18,14
2028 2,92 18,16
Year
Profit in € million
2025 2.138,37
2026 3.348,81
2027 4.575,53
2028 5.275,00
2029 4.057,00
Year
Free cash flow in € million
2025 1.907,36
2026 3.874,00
2027 6.249,36
2028 7.627,00
2029 8.992,00
Market capitalization in EUR billion 63,31
Analyst recommendations on Freeport-McMoRan
Buy 16
Overweight 3
Hold 5
Underweight 0
Sell 1
+ 6
2121
14 Comentários
•
33
•
9Mês·
AI infrastructure
AI infrastructure beyond the chips: What are your top 3 shovel stocks for 2026? I am looking for stocks that enable the operation of data centers (power, cooling, connectivity) but do not yet have the 100 P/E ratios of chip manufacturers.
My focus is on $ETN (+0,61%)
$ANET (+4,01%)
$VRT (+0,57%)
$FCX (+0,32%)
$NOW (+2,88%) !
Entry scenarios & opportunities $ETN (+0,61%)
Conservative (deep value): Wait for the range of $215 - $230. This would correspond to the DCF base case and a return to the long-term trend.
Growth-oriented: Entry on a daily RSI reversal above 35 and a simultaneous bullish MACD crossover. Target: Rebound to the EMA 200 (~340).
Savings plan entry: As Eaton is growing structurally (data centers, EV infrastructure), a savings plan at prices below 320 is historically attractive, as the P/E ratio is now back below its 3-year average.
Entry scenarios & opportunities $ANET (+4,01%)
Conservative (value focus): Entry at USD 95.00. This is close to the DCF base case and offers a solid fundamental basis.
Growth-oriented: Entry on a sustained breakout above the resistance of USD 135.00 with a simultaneous increase in volume.
Savings plan entry: Currently possible. Despite the high P/E ratio, the valuation is below the 5-year average (often > 50). Anyone who believes in the AI infrastructure cycle in the long term can build up positions here.
Entry scenarios & opportunities $VRT (+0,57%)
Conservative: Wait for a setback in the area of the DCF base case at USD 145 - 150.
Growth-oriented: Enter now (partial position), as the RSI (< 30) provides a strong buy signal for a mean-reversion trade. Increase on MACD crossover.
Savings plan: Due to the high volatility and the long-term AI theme, a monthly entry is ideal to take advantage of the cost-average effect during price setbacks.
Entry scenarios & opportunities $FCX (+0,32%)
Conservative entry (value-oriented):
Target price: range between $36.00 and $38.50.
Strategy: Buy close to the DCF bear case and the fundamental substance valuation.
Focus: Maximum margin of safety. This price range protects against volatility in the event of falling commodity prices or a global recession.
Growth-oriented entry (technical setup):
Target price: Setback to approx. $47.50.
Strategy: "Buy the dip" at the EMA 20 (exponential moving average) or at the first horizontal support level.
Focus: Use the current momentum. Entry is only made when the extremely overbought RSI (86) has cooled slightly, but the upward trend remains intact.
Savings plan entry (strategic DCA):
Target price: Current price level ($49.15).
Strategy: Regular purchases regardless of the current P/E ratio (dollar-cost averaging).
Focus: Long-term bet on the copper supercycle. Here it is accepted that the share is currently historically expensive, but that the opportunity costs of a missed breakout (above $50) should be avoided.
Entry scenarios & opportunities $NOW (+2,88%)
Conservative (Graham/DCF-Bear): Wait for a setback to the $105.00 - $115.00 range. The fundamental protection provided by the cash flow would be much stronger here.
Growth-oriented: Entry on a bullish MACD crossover on a daily basis, ideally combined with a breakout above the resistance at USD 162.00.
Savings plan entry: Currently attractive. The P/E ratio (forward) has fallen in historical comparison (often > 120) to a moderate 43x for 2026.
Do you have any other ideas? How do you invest?
Have a nice sunny Sunday!

11Mês·
Energy 4.0 - The foundation of a new industry Part 1.
Good morning, dear getquin community.
Over the past few weeks, I’ve been taking a deep dive into the battery and energy storage industry—its entire value chain, the major players, and the hidden champions behind the scenes. Today, I’d like to share this knowledge with you @Tenbagger2024 and show how individual technologies are coming together to form a cohesive energy system. I look forward to hearing your perspectives on this.
It’s no coincidence that Warren Buffett $BRK.B (+0,32%) Berkshire Hathaway. He recognizes early on where real value is created and what role chemical processes play in the development of modern energy and storage systems. That is precisely where it will be determined how efficiently batteries and fuel cells will be produced, operated, and recycled in the future—and who will profit from this transformation in the long term.
Personally, I’m not yet as broadly positioned in this sector as I’d like to be. I’ve already invested in some segments, but the entire value chain still offers enormous potential—and that’s exactly what I wanted to better understand through this analysis, among other things.
I’ve deliberately avoided mentioning personal favorites @Multibagger to keep the analysis neutral. If you’re particularly interested in certain companies, topics, or questions, feel free to mention them here in the comments. I’m open to feedback, additions, and discussions, and if any key players are missing in a particular area, I’ll be happy to add them later. This post ended up being a bit longer because I wanted to present the topic comprehensively and clearly. If you’re primarily interested in the companies, the value chain, and the shovel manufacturers, you can skip ahead to points 13 through 16.
Perhaps Part 2 will cover fuel cells, if that’s what you’d like? I wish you all the best of luck with your investments and, of course, a wonderful Sunday.
Structure of the Post
1. Introduction and Hook
2. Topic and Objective: Value Creation Concept 3. The Battery Industry as a Model
4. Basic Principle of the Battery
5. Applications
6. Battery Life Cycle
7. Future Trends
8. Raw Material Base and Development
9. Value Chain Stages 1–9
10. Value Creation Vectors in the Battery Industry
Value Creation as a Cycle and an Overall Model
11. Macro and Micro Levels and How They Fit Together
12. Significance of Battery Industry 4.0
13. Value Chain with Company Assignments for Stages 1–8
14. Key Players at Each Stage, Plus Overarching Financiers and Strategic Distributors
15. Points of Connection: Hybrid Energy Systems for Data Centers, Industry, and Transportation
16. Energy for Humanoid Robots: The Next Evolutionary Stage of Application
17. Takeaway with a Hidden Question in the Body Text
18. Sources
2️⃣.Topic and Objective of the Article
The battery industry has long been more than just cell manufacturing or e-mobility. It is at the center of a global structural transformation that is redistributing energy, technology, and capital. The goal of this article is to understand the battery as a complete value chain—from raw material extraction through material technologies, production, and application to recycling and recovery.
I will show how genuine value is created along this chain, which industries benefit directly from it, and why the battery industry is becoming a central link in future energy systems. At the same time, the goal is to view the whole as a strategic model—a convergence of technology, economics, and sustainability that extends far beyond the mobility sector.
3️⃣.Basic Principle of the Battery
At its core, a battery is a chemical energy storage device that stores electrical energy in the form of chemical compounds and releases it again when needed. It consists of three main components: an anode, a cathode, and an electrolyte. During charging and discharging, positively charged ions move back and forth between these electrodes. This generates an electric current that can be used to power vehicles, supply machinery, or stabilize energy in grids.
The basic principle is reversible. This means that energy can not only be drawn from the battery but also fed back into it. This simple yet highly effective reaction makes batteries one of the central building blocks of modern energy systems. Thanks to advances in chemistry, materials technology, and manufacturing, performance is steadily increasing, while weight, charging time, and costs are continuously decreasing.
4️⃣.Applications
Today, batteries are far more than just a power source for electric cars. They are the backbone of modern energy systems and key to stabilizing renewable power grids. Their applications range from electric mobility to stationary energy storage to industrial and digital applications.
In the mobility sector, batteries enable the transition from internal combustion engines to electric drive technology and form the foundation of new vehicle platforms. In the energy sector, they serve as buffer storage for solar and wind power, balance out grid fluctuations, and ensure a reliable supply during peak times. In industry, they ensure supply reliability, efficiency, and emergency power solutions, while in data centers they are increasingly being used as emission-free backup systems.
In addition, new areas of application are emerging in aviation and maritime transport, in household and building systems, and in microgrids that supply remote regions or industrial parks with energy independently of the central grid. Batteries are thus a universal energy storage medium that connects sectors and lays the foundation for flexible, decentralized energy architectures.
5️⃣.Battery Life Cycle
A battery goes through a clearly defined life cycle that extends far beyond its actual use. It begins with the extraction and processing of raw materials, continues through cell and system manufacturing to the active use phase, and ends with the recovery and recycling of the materials.
During the production phase, active materials and cells are manufactured from raw materials such as lithium, nickel, manganese, cobalt, graphite, and copper. These cells are then assembled into modules and complete battery packs. During the usage phase, the batteries provide energy for years in vehicles, energy storage systems, or industrial facilities.
Once the end of their service life is reached, the second cycle begins. Cells that are still powerful enough are reused in so-called second-life applications, such as stationary energy storage systems. Finally, the recycling process takes place, during which valuable raw materials such as lithium, nickel, and cobalt are recovered and fed back into the production cycle.
This closed-loop material cycle is the crucial step toward a sustainable battery economy. It reduces dependence on primary raw materials, lowers environmental impact, and makes the entire value chain more resilient in the long term.
6️⃣.Future Trends
The battery industry is facing a period of massive technological and structural change. Progress is shifting from a focus on sheer capacity increases toward efficiency, sustainability, and material independence.
A key trend is the shift toward solid-state batteries, which—thanks to solid electrolytes—are safer, more compact, and more powerful than today’s lithium-ion systems. At the same time, silicon anodes are gaining importance, as they enable higher energy densities and shorter charging times. Sodium-ion batteries open up new possibilities for cost-effective storage solutions, particularly in applications where weight and energy density are less critical.
The digitization of batteries is also advancing. Smart battery management systems analyze the condition, temperature, and state of charge of each cell in real time. This not only improves safety but also extends service life and optimizes operation.
On an economic level, the industry is moving toward vertical integration: manufacturers are securing raw materials, energy suppliers are building their own storage facilities, and technology conglomerates are investing directly in manufacturing capacity. At the same time, political pressure is growing for a circular economy, recycling, and carbon neutrality.
The future of batteries thus lies in a combination of new materials, smart control systems, and closed-loop systems. Those who successfully integrate these three elements will play a decisive role in shaping the dynamics of the energy market in the coming years.
7️⃣.Raw Material Base and Development
The battery industry begins at the source of raw materials. Lithium, nickel, manganese, cobalt, copper, and graphite currently form the basis of nearly all high-performance cells. These metals determine the energy density, stability, and service life of every battery. At the same time, they are the most sensitive part of the value chain, as their extraction, processing, and supply determine costs, sustainability, and geopolitical dependencies.
A significant shift has taken place in recent years. Companies and governments are investing in new mining areas, recycling facilities, and alternative materials to ensure a secure supply. Lithium and nickel, in particular, remain key materials, while cobalt is increasingly being replaced. Graphite is undergoing a transformation toward synthetic and recycled forms, which are intended to reduce dependence on China.
The trend is clearly moving toward material efficiency and a circular economy. Instead of constantly opening new mines, closed-loop systems are emerging in which raw materials are reused multiple times. At the same time, alternative cell chemistries are coming to the fore, relying on abundantly available elements such as sodium, iron, or silicon.
This shift reduces costs, lowers environmental impacts, and increases the independence of entire economies. The raw material base of the battery industry is thus transforming from a linear supply chain into a global, circular material network that combines technology, recycling, and sustainability.
8️⃣.Value Chain
The battery industry follows a clear industrial logic that extends from the extraction of raw materials to the recycling of materials. Each stage in this chain creates its own value and is, at the same time, a prerequisite for the next.
1. Raw Material Extraction – Mining and extraction of lithium, nickel, manganese, cobalt, copper, and graphite from mines and salt lakes. This stage determines the cost structure and environmental footprint of the entire battery.
2. Refining and processing – Processing raw materials into battery chemicals, such as lithium hydroxide or nickel sulfate, which are used in cell production.
3. Materials technology and component manufacturing – Production of cathode, anode, and electrolyte materials, as well as separators, conductive foils, and binders.
4. Cell production – Assembling the materials into electrochemical cells through coating, stacking, and sealing. This step determines capacity, safety, and quality.
5. Module and pack manufacturing—Cells are assembled into modules and complete battery packs, including the battery management system and cooling.
6. System integration – Installation of battery packs in vehicles, energy storage systems, or industrial equipment. This is where the battery, software, and power electronics come together.
7. Use and operation – The battery’s operational phase spanning several years. Digital monitoring and predictive maintenance extend its service life and efficiency.
8. Recovery and Recycling – At the end of the life cycle, materials such as lithium, nickel, cobalt, and graphite are recycled and returned to the production cycle.
Together, these eight stages form the complete industrial cycle of the battery industry. Value is created at every stage, but it is greatest where technology, energy efficiency, and recycling intersect. This is the point at which a supply chain becomes a true value-creation system.
9️⃣.Value Creation Vectors in the Battery Industry
The battery industry is shaped not only by production processes but also by several overarching forces that act like vectors, cutting across all stages of the value chain. These vectors determine which companies remain at the forefront and where value is concentrated in the long term.
1. Technology Vector
Advances in cell chemistry, materials science, manufacturing, and software integration. Companies that scale up in these areas reduce costs and increase energy density, safety, and service life.
2. Digitalization Vector
Data management, condition analysis, cloud-based battery monitoring, and predictive maintenance. This level connects physical systems with AI and makes operations and recycling more predictable.
3. Sustainability Vector
Circular economy, carbon-neutral production, ESG standards, and material recycling. Companies that lead in this area secure long-term approvals and capital.
4. Finance and Investment Vector
Capital flows from government subsidies, private funds, and infrastructure programs that finance manufacturing capacity and research.
5. Infrastructure Vector
Construction of gigafactories, recycling centers, charging infrastructure, and energy storage facilities. This foundation is crucial for scaling up and ensuring supply security.
6. Geopolitical Vector
Location decisions, trade agreements, raw material dependencies, and security interests determine who has access to strategic materials and markets.
These vectors operate simultaneously and reinforce one another. The true dynamics of the battery industry emerge where technology, sustainability, and capital are intelligently intertwined. This is the axis where innovation, returns, and resilience converge.
🔟.Value Creation as a Cycle
The battery industry is increasingly evolving from a linear supply chain into a closed-loop system. Energy, materials, and data flow continuously between production, use, and recycling. The goal is to conserve resources, minimize losses, and increase value throughout the entire life cycle.
The cycle begins with raw material extraction and proceeds through material development, cell manufacturing, and integration, all the way to use in vehicles, energy storage systems, and industrial facilities. After the operational phase, materials are recovered and reused in new batteries. This physical cycle is complemented by a digital data cycle in which all relevant information about the condition, performance, and age of each cell is stored and analyzed.
This creates a system that optimizes itself. Data from operations flows back into research, design, and recycling, making new generations of batteries more efficient, safer, and more sustainable. This combination of physical and digital cycles is the key to genuine value creation in the Battery Industry 4.0.
1️⃣1️⃣.Macro and Micro Levels
The battery industry operates on two interconnected levels that drive and stabilize one another. At the macro level, global structures, political programs, and economic frameworks take shape. At the micro level, technological, chemical, and process-related developments come into play, making these larger trends possible in the first place.
The macro level encompasses everything that drives the industry as a whole: geopolitical interests, energy policy, subsidy programs, trade, infrastructure, and capital flows. This is where the course is set for where gigafactories are built, which countries secure access to raw materials, and how nations reduce their energy dependence.
The micro level describes the technical reality: cell chemistry, material innovation, manufacturing technology, software integration, and recycling processes. This is where actual progress takes place. Every new battery chemistry, every improvement in energy management, or every reduction in the use of rare metals alters the larger system in the background.
Both levels are intertwined. Political decisions and capital flows at the macro level enable technological developments at the micro level, while technological breakthroughs, in turn, trigger new markets, trade structures, and investment cycles. It is precisely at this intersection—where technology, politics, and the economy interact within a closed system—that the strategic potential of the battery industry emerges.
1️⃣2️⃣.The Significance of Battery Industry 4.0
Battery Industry 4.0 stands for the complete digitization and networking of all processes along the value chain. It combines production, energy, data, and sustainability into a single intelligent system that is controlled, monitored, and optimized in real time.
At its core is the integration of physical equipment with digital platforms. Every cell, every machine, and every process provides data that is analyzed using AI and analytics. This creates a self-learning system that detects errors early, ensures quality, and extends the service life of the batteries.
In manufacturing, automated lines, robotics, and machine learning maximize efficiency and precision. During operation, cloud services and IoT sensors enable continuous condition monitoring, which optimizes maintenance, safety, and performance. At the same time, environmental data is collected to make CO₂ footprints transparent and verifiable.
Battery Industry 4.0 is therefore not just a buzzword, but the transition to a fully integrated, data-driven energy industry. It lays the foundation for scalability, cost-effectiveness, and sustainability, and connects research, production, use, and recycling in a closed digital loop.
Visual Overview of the Battery Value Chain
To make the entire structure more tangible, I have divided the battery industry system into three levels:
1. Macro level: global value creation, energy policy, raw material and production networks.
2. Micro level: technological processes, material cycles, and innovation axes.
3. Overall Model: the integration of both levels into a closed-loop system that connects production, use, and recovery.
This diagram illustrates how linear supply chains evolve into a circular, digitally controlled energy system—the very DNA of the Battery Industry 4.0.
➡️Battery Value Creation: Macro–Micro–Overall Model
[R&D] [Engineering] [Digitalization]
↓ ↓ ↓
Raw Materials → Materials → Cells → Systems → Use → Recycling
↑ ↑ ↑
[Supply Chain] [Second Life] [Service]
1️⃣3️⃣.Value Chain with Company Assignments + Hidden Champions
Specialized value is created at every stage along the battery value chain. Companies strategically occupy individual segments or integrate multiple areas to strengthen their position. The combination of material expertise, technological competence, and system integration determines who comes out ahead in global competition.
1. Raw Material Extraction
Lithium, nickel, cobalt, graphite:
$ALB (-0,51%) Albemarle (NYSE: ALB) – U.S. One of the world’s largest lithium producers with mining sites in Chile, Australia, and the U.S. Supplies global cell production with lithium hydroxide for cathode materials
$SQM SQM (NYSE: SQM) – Chile – Specializes in lithium and potash products from the salt lakes of the Atacama Desert. Plays a central role in South America’s battery raw material supply
$9696 (-1,28%) Tianqi Lithium (SHE: 002466 / HKG: 9696) – China – Tianqi Lithium is one of the world’s largest lithium producers, with stakes in major hard-rock lithium projects in Australia (Greenbushes Mine) and processing facilities in China. The company supplies lithium hydroxide and lithium carbonate for cathode materials in the battery industry. Focus on upstream control and chemical processing
$GLEN (-2,9%) Glencore (LSE: GLEN) – Switzerland – A diversified commodities group focused on nickel, cobalt, and copper. A leader in the recycling and reuse of battery waste
$SSW Sibanye Stillwater (JSE: SSW / NYSE: SBSW) – South Africa / U.S. – Sibanye Stillwater is a mining company focused on platinum group metals such as platinum and palladium (important for fuel cell catalysts), as well as nickel and cobalt from recycling and mining. Strategically particularly relevant because it engages in both primary mining and metal recovery. This positions it at the intersection of battery raw materials, fuel cell catalysts, and recycling streams
$PLS (-2,98%) Pilbara Minerals (ASX: PLS) – Australia – A major producer of spodumene concentrate. It is driving the expansion of local lithium value creation in Western Australia
$SYR (-2,41%) Syrah Resources (ASX: SYR) – Australia / Mozambique – Mines natural graphite in Balama, Mozambique, and is establishing anode materials production in the U.S. Strategically important for the Western graphite supply
Copper and other industrial metals:
$FCX (+0,32%) Freeport-McMoRan (NYSE: FCX) – U.S. – One of the world’s largest copper producers. Supplies the battery and electronics industries with copper cathodes from mines in North and South America
$BHP (+0%) BHP Group (NYSE: BHP) – Australia / UK – Global mining conglomerate focused on copper, nickel, and iron. Invests heavily in sustainable mining and the decarbonization of raw material production
$RIO (-0,82%) Rio Tinto (NYSE: RIO) – United Kingdom / Australia – A multinational commodities giant with a growing presence in the lithium sector. A leader in sustainable copper mining and materials processing
Hidden Champions
$SLI (+1,55%) Standard Lithium (NYSE: SLI / TSX-V: SLI) – Canada / U.S. – Standard Lithium is developing direct lithium extraction (DLE) from brine in the U.S. The goal is to extract lithium without traditional hard-rock mining or massive evaporation ponds. This positions the company as a technology-driven lithium developer focused on ensuring North American supply security. This is clearly a second-tier stock with significant upside potential
$VUL (-3,4%) Vulcan Energy Resources (ASX: VUL) – Australia / Germany - Vulcan Energy is working on geothermal-coupled lithium extraction in the Upper Rhine Graben in Germany. Approach: Low-carbon lithium production from thermal brine plus regional supply for the European battery cell industry. This is extremely important geopolitically because it enables lithium from Europe for Europe without relying on traditional mining infrastructure
$LKE (+0%) Lake Resources (ASX: LKE) – Australia – Develops lithium projects using sustainable direct extraction technology (DLE). The goal is to extract lithium with minimal water consumption and CO₂ emissions
$SGML (-0,4%) Sigma Lithium (NASDAQ: SGML) – Canada/Brazil – Produces high-purity lithium concentrate in Brazil with a focus on ESG-compliant mining and local value creation
$ABAT American Battery Technology Company (NASDAQ: ABAT) – U.S. – Combines raw material extraction with the recycling of lithium and nickel. A pioneer in closed-loop material cycles using domestic sources
2. Refining and Processing
These companies process raw materials into battery chemicals, thereby facilitating the transition to materials technology.
$UMI (-4,94%) Umicore (EBR: UMI) – Belgium – A leader in the refining and processing of nickel, cobalt, and lithium. Develops cathode materials and operates recycling centers in Europe and Asia.
$BAS (-0,81%) BASF (ETR: BAS) – Germany – Global chemical company with a growing focus on battery materials, particularly cathode active materials and nickel-manganese chemistries
$003670 POSCO Future M (KRX: 003670) – South Korea – A specialist in cathode and anode materials. Part of the POSCO Group, it supplies LG Energy Solution and Samsung SDI
$051910 LG Chem (KRX: 051910) – South Korea – Develops and manufactures battery materials, polymers, and electrolytes. Closely integrated with LG Energy Solution throughout the entire supply chain
$010130 Korea Zinc (KRX: 010130) – South Korea – Leading provider of rare metal refining. Supplies nickel and zinc products for battery cathodes
Hidden Champions
Ecopro (KRX: 086520) – South Korea – Manufacturer of high-purity cathode materials and precursors for nickel and cobalt chemistries. Key supplier to LG Energy Solution and SK On
Sila Nanotechnologies (private, U.S.) - Develops silicon anode materials to increase energy density and charging speed. Supplies automakers with advanced battery materials
Green Lithium – United Kingdom (private) - Is building Europe’s first large-scale lithium refinery. Focus on ESG-compliant, energy-efficient refining for the European market
Mangrove Lithium – Canada (privately held) - Develops modular refinery plants based on electrochemical processes to convert lithium concentrate into battery-grade lithium hydroxide
$ICL ICL Group (NYSE: ICL) – Israel – Manufactures specialty chemicals and electrolytes for batteries and energy storage. Combines chemical expertise with sustainable process optimization
3. Materials Technology and Component Manufacturing
They supply cathode and anode materials, electrolytes, separators, and coating systems.
$3407 (+0,92%) Asahi Kasei (TYO: 3407) – Japan – Manufacturer of separator films and electrolytes. A global leader in thermal stability and safety
$3402 (+0,97%) Toray Industries (TYO: 3402) – Japan – Develops high-performance polymers and carbon materials for electrodes, separators, and casings
$SOLB (-4,16%) Solvay (EBR: SOLB) – Belgium – Chemical company focused on binders, electrolyte salts, and coatings for cathode and anode production
$MMM (-1,33%) 3M (NYSE: MMM) – U.S. – Supplier of additives, protective coatings, and conductive materials. Strong partner in cell and module manufacturing
$018880 Hanon Systems (KRX: 018880) – South Korea – Specializes in thermal management solutions for battery packs and electric powertrains
$PPG PPG Industries (NYSE: PPG) – USA – One of the world’s leading manufacturers of specialty coatings and functional materials. Develops conductive and protective coatings for battery cells, enclosures, and interconnect components. Supports cell manufacturers with solutions to improve heat dissipation, safety, and service life
Hidden Champions
Nexeon – United Kingdom (privately held) – Develops silicon anode materials to increase energy density in lithium-ion cells. Focuses on lightweight construction and fast-charging capability
Group14 Technologies – U.S. (privately held) – A pioneer in silicon-carbon composites. Collaborates with automakers and cell manufacturers on the next generation of high-energy anodes
$TLG (+0,4%) Talga Group (ASX: TLG) – Australia/Sweden – Integrates graphite mining and anode production. Aims to sustainably produce carbon materials for European cell manufacturing
4. Cell Production
The technological heart of the value chain. This is where capacity, energy density, and cost structures are determined.
$3750 (-1,09%) CATL (SHE: 3750) – China – The world’s largest battery manufacturer with a market share of over 30 percent. A leader in LFP and NMC technologies and a partner to numerous OEMs
$373220 LG Energy Solution (KRX: 373220) – South Korea – Global cell manufacturer with plants in Asia, Europe, and the U.S. Focuses on high-performance cells for e-mobility and energy storage
$SMSN Samsung SDI (KRX: 006400) – South Korea – Focuses on premium cells with high energy density. Close supplier to BMW, Rivian, and other premium manufacturers
$6752 (+3,15%) Panasonic Holdings (TYO: 6752) – Japan – Long-standing partner of Tesla. Building new production facilities in the U.S. and Japan
Northvolt – Sweden (privately held) – European pioneer in sustainable battery manufacturing. Focus on the circular economy, green energy, and closed-loop supply chains
Hidden Champions
$QS QuantumScape (NYSE: QS) – U.S. – Develops solid-state batteries with ceramic electrolytes for higher energy density and safety. Partners with Volkswagen
$SLDP Solid Power (NASDAQ: SLDP) – U.S. – Specializes in solid-state electrolytes and high-performance cells for automotive applications. Collaborations with BMW and Ford
24M Technologies (private, USA) – Develops semi-solid lithium-ion cells with simplified production. Significantly reduces costs and material consumption
$AMPX Amprius Technologies (NYSE: AMPX) – U.S. – Specializes in silicon nanowire anodes with extremely high energy density. Applications in aviation, drones, and robotics
$ENVX (-4,95%) Enovix (NASDAQ: ENVX) – U.S. – Develops 3D silicon cells with a novel architecture. Focuses on safety, fast charging, and compact formats
ProLogium – Taiwan (privately held) – Technology leader in solid-state batteries. Building the first large-scale production plant in Europe with partners from the automotive industry
5. Module and Pack Manufacturing
In this phase, individual cells are assembled into complete battery modules and packs. This is where mechanical engineering, robotics, and precision technology converge with energy chemistry and quality assurance. Companies such as KUKA (ETR: KU2), $ABBN (-0,83%) ABB Robotics (VTX: ABBN), Comau (privately held, Italy), Teamtechnik (privately held, Germany), and $LECN Leclanché (SWX: LECN) supply automated systems for the assembly, welding, testing, and cooling of battery modules. Cell manufacturers such as $300014 EVE Energy (SHE: 300014) or $3750 (-1,09%) CATL (SHE: 3750) also manufacture complete battery systems for the automotive and industrial sectors.
Hidden Champions such as $VAR1 Varta (ETR: VAR1), $MVST Microvast (NASDAQ: MVST), and $FORSE (+15,95%) Forsee Power (EPA: FORSE) are developing modular high-performance batteries for commercial vehicles, rail, shipping, and stationary storage solutions.
These companies combine innovative cell chemistry with thermal management, fast-charging capabilities, and longevity.
At the same time, automakers such as $TSLA (+4,51%) Tesla (NASDAQ: TSLA), $1211 (-0,5%) BYD (HKG: 1211), $VOW3 (+1,27%) Volkswagen (ETR: VOW3), $BMW (+0,18%) BMW (ETR: BMW), $MBG (-0,17%) Mercedes-Benz Group (ETR: MBG), $XPEV Xpeng (NYSE: XPEV), $NIO NIO (NYSE: NIO), and $RIVN Rivian (NASDAQ: RIVN) are increasingly integrating cell production into their own value chains in order to independently control efficiency, energy density, and cooling.
In short: At this stage, market-ready battery systems are developed; these are precisely assembled, thermally stabilized, and digitally monitorable. They form the heart of modern e-mobility and energy storage solutions and serve as the bridge between materials science and application.
6. System Integration
Here, the manufactured battery modules are combined into intelligent complete systems—in vehicles, data centers, networks, or industrial facilities.
This stage integrates hardware, software, and control systems into a functional energy landscape.
Companies such as $SIE (-0,92%) Siemens (ETR: SIE), Hitachi Energy (privately held, Switzerland/Japan), $ETN (+0,61%) Eaton (NYSE: ETN), $VRT (+0,57%) Vertiv (NYSE: VRT), $WRT1V (-3,2%) Wärtsilä (HEL: WRT1V), $SU (-1,84%) Schneider Electric (EPA: SU), and $ABBN (-0,83%) ABB (VTX: ABBN) are developing comprehensive systems for energy flow control, grid stabilization, and digital integration.
Hidden champions such as $PCELL (-4,05%) PowerCell Sweden (STO: PCELL), Volterion (private, Germany), $ADSE (+1,98%) ADS-TEC Energy (NASDAQ: ADSE), AutoGrid Systems (private, U.S.), $EGT Eguana Technologies (TSXV: EGT), $EOSE Eos Energy Enterprises (NASDAQ: EOSE), and Nuvation Energy (private, U.S.) combine battery storage with control electronics, inverters, and AI-based management software. They create modular energy systems that are flexibly scalable and can be deployed to benefit the grid.
In short: This phase sees the emergence of interfaces between technology and the market—systems that not only store electricity but also intelligently control, distribute, and optimize it.
7. Utilization and Application
This is where the battery industry reveals its economic core. In this phase, energy is not only stored but also strategically deployed in mobility, data centers, grids, industry, and private households.
E-Mobility
Batteries are the foundation of electric powertrains. In addition to $TSLA (+4,51%) Tesla (NASDAQ: TSLA), $1211 (-0,5%) BYD (HKG: 1211), $VOW3 (+1,27%) Volkswagen (ETR: VOW3), $BMW (+0,18%) BMW (ETR: BMW), $MBG (-0,17%) Mercedes-Benz (ETR: MBG), and $NIO NIO (NYSE: NIO) are also part of $STLAM (-1,12%) Stellantis (NYSE: STLA), $LCID Lucid Motors (NASDAQ: LCID), and $RIVN Rivian (NASDAQ: RIVN). They are developing their own battery cell chemistries, software, and charging infrastructure.
Hidden Champions such as $VAR1 Varta (ETR: VAR1) and $LECN Leclanché (SWX: LECN) supply modular systems and high-performance cells for specialized applications.
Data Centers and Cloud Infrastructure
The global expansion of AI, cloud, and storage architectures is driving a massive increase in energy consumption. Companies such as $GOOGL (+1,38%) Google (NASDAQ: GOOGL), $MSFT Microsoft (NASDAQ: MSFT), $AMZN (+5,26%) Amazon Web Services (NASDAQ: AMZN), and $ORCL Oracle (NYSE: ORCL) are developing their own energy strategies and software solutions to operate their global data centers more efficiently and with lower CO₂ emissions. Infrastructure partners such as $EQIX Equinix (NASDAQ: EQIX) and $DLR (-1,42%) Digital Realty (NYSE: DLR) are relying on battery and hybrid solutions to ensure grid stability. Technology providers such as $VRT (+0,57%) Vertiv (NYSE: VRT), $SU (-1,84%) Schneider Electric (EPA: SU), and $WRT1V (-3,2%) Wärtsilä (HEL: WRT1V) provide energy management, cooling, and hybrid power systems.
Hidden Champions such as AutoGrid Systems—AI-controlled virtual power plants, $ADSE (+1,98%) ADS-TEC Energy (NASDAQ: ADSE)—modular high-performance storage for server farms.
Energy suppliers and grid operators (NRPG)
This is where the transition between generation and storage takes place. Utilities such as $FLNC Fluence Energy (NASDAQ: FLNC), $NEE NextEra Energy (NYSE: NEE), $ENEL (-2,02%) Enel (BIT: ENEL), $TTE (-0,92%) TotalEnergies (EPA: TTE), $RWE (-3,02%) RWE (ETR: RWE), and $ORSTED (-2,29%) Ørsted (CPH: ORSTED) are investing heavily in battery storage to stabilize grids and manage demand. They are joined by specialized developers such as $AMRC (-3,03%) Ameresco (NYSE: AMRC) and $AES (+0,38%) AES Corporation (NYSE: AES), which implement hybrid storage and power plant projects.
Hidden Champions such as $STEM Stem Inc. (NYSE: STEM) and GridBeyond (privately held, Ireland) connect these systems via software and enable real-time energy trading.
Industrial and residential storage
Decentralized energy systems are increasingly connecting industry, commercial properties, and private households with storage solutions. Sonnen (privately held, Germany)—a subsidiary of $SHEL (-1,08%) Shell (LON: SHEL) is a leader in home storage and energy communities. E3/DC (privately held, Germany) and $EGT Eguana Technologies (TSXV: EGT) provide modular systems for self-consumption and grid independence. Software providers such as TWAICE (private, Germany) monitor storage status, efficiency, and lifespan using digital twins.
Summary of the Usage Level
This phase integrates technology, infrastructure, and digital management. Whether in electric vehicles, cloud data centers, industrial facilities, or private households, batteries serve as the link between energy generation, consumption, and intelligence. This is where it will be determined which technologies will define energy distribution, efficiency, and autonomy in the long term.
9. Quality & Safety / Materials Technology
$KEYS Keysight Technologies (NYSE: KEYS) – U.S. – A leader in measurement technology, signal processing, and test systems for battery and semiconductor applications
National Instruments (NASDAQ: NATI) – U.S. – Develops modular test and measurement systems; now part of Emerson Electric
$FORM FormFactor (NASDAQ: FORM) – U.S. – Specialist in wafer probing and precision measurements in cell and semiconductor manufacturing
$KULR KULR Technology Group (NYSE: KULR) – USA – Specialist in thermal management and safety systems for lithium-ion batteries. The technology originated in the aerospace industry (NASA) and is now used in energy storage systems, electric vehicles, and recycling processes.
9. Recovery and Recycling
These companies close the loop and ensure the recycling of strategic raw materials.
$LICY Li-Cycle (NYSE: LICY) – Canada – Operates recycling facilities for lithium-ion batteries. Recovery of nickel, cobalt, and lithium using hydrometallurgical technology
Redwood Materials – U.S. (privately held) – Founded by Tesla’s former chief technical officer, JB Straubel. A leader in establishing closed-loop material cycles in the U.S.
Primobius – Germany (Neometals/SMS Group joint venture) – Develops modular recycling plants for battery production in Europe. Focus on industrial scalability
$UMI (-4,94%) Umicore (EBR: UMI) – Belgium - Combines materials production and recycling. A leader in the recovery of valuable metals such as platinum, nickel, and cobalt
Stena Recycling (privately held, Sweden) – One of Europe’s leading players in recycling and the circular economy. Processes industrial waste, electronics, and batteries, recovering valuable metals and materials for reuse
Heraeus (privately held, Germany) – A technology group specializing in precious metal recycling and materials technologies. Recovers platinum, gold, silver, and rare metals from industrial and battery waste and uses them to manufacture new functional materials
Hidden Champions
Tozero – Germany (privately held) – An innovative startup specializing in hydrometallurgical battery recycling. Its goal is the complete recovery of lithium, nickel, and graphite
$AMY (+0%) RecycLiCo (TSXV: AMY) – Canada – Develops chemical processes for the efficient recovery of high-purity battery materials
ACE Green Recycling – Singapore (privately held) – Works on CO₂-neutral recycling processes for lead-acid batteries and lithium systems. Focus on energy efficiency and scalability
Along this chain, a global network of specialists, producers, and integrators is emerging. The greatest growth opportunities lie at the intersections—where chemical expertise, digitalization, and the circular economy converge.
1️⃣4️⃣.Equipment manufacturers at each stage, plus overarching financiers and strategic distributors
⚒️ 1. Raw material extraction – “shovels” = exploration, machinery, plant engineering
Who benefits: Machinery manufacturers, chemical and plant equipment suppliers, raw material financiers
$CAT (-0,41%) Caterpillar (NYSE: CAT) – U.S. – mining equipment, transport vehicles for lithium and nickel mines
$6301 (+2,72%) Komatsu (TYO: 6301) – Japan – heavy mining machinery, particularly in South America and Australia
$SAND (+0,5%) Sandvik (STO: SAND) – Sweden – Drilling and rock-cutting equipment (lithium mines)
$FLS (-0,96%) FLSmidth (CPH: FLS) – Processing plants for nickel and cobalt
$EPI A (-1,38%) Epiroc (STO: EPI-A) – Sweden – Specializes in underground drilling, blasting technology, and automated mining solutions
$WEIR (-1,57%) Weir Group (LSE: WEIR) – United Kingdom – Supplies grinding and pumping technology for ore processing and material transport in mines
Hidden Champions
$ANG (+0%) Austin Engineering (ASX: ANG) – Australia – Manufactures mining vehicle components and heavy equipment for open-pit mining
$ORI (+0,71%) Orica (ASX: ORI) – Australia – Leading supplier of industrial explosives and drilling chemicals for exploration and mining
$METSO (+0,7%) Metso Outotec (HEL: METSO) – Finland – Equipment for ore processing and metal recovery
Investors / Funds:
$SPWRC8 BlackRock Natural Resources Fund
$LIT Global X Lithium & Battery Tech ETF
Sprott Physical Battery Metals Trust – Financing of exploration projects
⚗️ 2. Refining & Materials Chemistry – “Shovels” = Process plants, chemical equipment
Who benefits: Chemical plant manufacturers, specialty chemicals, process engineering
$LIN (+1,26%) Linde (NYSE: LIN) – UK – Gas processing, process plants (e.g., electrolytes, carbon-neutral hydrogen for batteries)
$AI (+0,01%) Air Liquide (EPA: AI) – France – industrial gases, CO₂-free syntheses
$WCH (-0,11%) Wacker Chemie (ETR: WCH) – Germany – Silicon compounds for anodes
$BAS (-0,81%) BASF Engineering Services – Germany – Process design & EPC for cathode production
$TE (-0,36%) Technip Energies (EPA: TE) – France – Engineering solutions for chemical refineries
$ANDR (-0,81%) Andritz AG (VIE: ANDR) – Austria – Machinery and plant manufacturer for chemical processing, filtration, and metal separation
$FLS (-0,96%) FLSmidth (CPH: FLS) – Denmark – Supplies large-scale plants for ore processing and metal recovery with a focus on energy efficiency
$VIE (-1,98%) Veolia Environnement (EPA: VIE) – France – Develops industrial water and waste solutions for metal processing and recycling
Hidden Champions
$PYR (+7,06%) PyroGenesis Canada (TSX: PYR) – Canada – Uses plasma technology to refine metals cleanly and efficiently. A sustainable alternative to traditional high-temperature processes
$MMI Metalo Group (TSXV: MMI) – Canada - Specialist in low-carbon metal refining. Develops energy-efficient processes for converting raw materials into battery-grade metals
Financiers / Strategic Partners:
KfW / EIB / EU Innovation Fund – support materials and recycling projects
Breakthrough Energy Ventures (Gates Fund) – invests in new cathode and anode technologies
🧪 3. Materials Technology & Components – “Tools” = Measurement Technology, Machinery, Software
Who benefits: Measuring instruments, lab automation, software for cell research
$TMO (-1,37%) Thermo Fisher Scientific (NYSE: TMO) – U.S. – Materials analytics
$BRKR (+1,31%) Bruker (NASDAQ: BRKR) – U.S. – spectroscopy & materials characterization
$HEN3 (-0,37%) Henkel AG & Co. KGaA (ETR: HEN3) – Germany – Global supplier of industrial adhesives, sealants, and thermal materials, central to battery and electronics manufacturing
$MMM (-1,33%) 3M Company (NYSE: MMM) – U.S. – Supplies high-performance insulation materials, adhesives, and protective coatings for battery cells and modules
$DD (-0,13%) DuPont de Nemours, Inc. (NYSE: DD) – U.S. – Produces polymers, insulating materials, and binders for electrolytes, separators, and cell packaging. Focus on safety and energy efficiency
$AMAT (+1,36%) Applied Materials (NASDAQ: AMAT) – U.S. – Supplier of production and coating equipment for battery and semiconductor manufacturing
Hidden Champions
Bühler Group (privately held, Switzerland) – Manufacturer of precision equipment for powder processing, coating, and material preparation
$AFX (+0,06%) Carl Zeiss Meditec AG (ETR: AFX) – Germany – Leading manufacturer of optical and imaging systems for research, microscopy, and materials analysis. Relevant to cell research and quality control of battery materials
Leica Microsystems (privately held, Germany / part of $DHR (-2,08%) Danaher Corporation, NYSE: DHR – U.S.) – Develops microscopes and imaging systems for materials science and cell analysis. Significant for research and process development in battery cell production
Ionbond (privately held, Switzerland) – A leader in hard coatings for electrodes, contact surfaces, and housings. Extends the service life of critical components
$ENTG Entegris (NASDAQ: ENTG) – USA – Develops specialty chemicals, filtration, and process solutions for ultra-high-purity battery and semiconductor manufacturing
Software & Simulation Providers:
$DSY (+0,89%) Dassault Systèmes (EPA: DSY) – Battery development simulation (CATIA / SIMULIA)
COMSOL AB (privately held, Sweden) – Developer of the multiphysics simulation platform. Enables coupled simulations of electrochemistry, mechanics, and thermodynamics in battery cells and energy systems
🏭 4. Cell & Module Production – “Shovels” = Production Equipment, Robotics, Measurement Technology
Who benefits: Machine builders, automation, quality control
$300450 Wuxi Lead Intelligent (SHE: 300450) – China – Develops automated production lines for cell manufacturing and assembly
Toshiba (TYO: 6502) – Japan – Manufacturer of cells and production systems for energy storage and vehicles
$SIE (-0,92%) Siemens AG (ETR: SIE) – Germany – Supplies digital production and automation software, including “Digital Twin” solutions for battery factories.
KUKA AG (ETR: KU2) – Germany – Robotics and automation expert for battery pack assembly and manufacturing processes
Hidden Champion
Tera Automation (privately held, Italy) – Precision machines for electrode handling and cell stacking
InoBat Auto (privately held, Slovakia) – Modular small-batch cell production with a research focus on material adaptation
Trumpf (privately held, Germany) – A leader in laser welding technology and manufacturing systems for cell housings and battery modules
$M5Z (-2,56%) Manz AG (ETR: M5Z) – Germany – Specialist in machine and plant engineering for cell and module production. Offers complete production lines for electrodes and cells
$DUE (+1,86%) Dürr AG (ETR: DUE) – Germany – Manufacturer of coating and drying systems for battery electrodes. Also supplies cleanroom systems for cell production
Bosch Rexroth (private, Germany) - A leader in production control, linear technology, and battery system integration for automated production lines.
Financing & Infrastructure
EU IPCEI Battery Initiative (Europe) – A European funding program worth billions aimed at strengthening European battery production and research.
Capricorn Partners (private, Belgium) - Venture capital investor focused on cleantech, deep tech, and battery projects in Europe. (Hidden Champion)
InnoEnergy (private, EU / Netherlands) - An EU-backed innovation network for financing and scaling battery startups such as Northvolt or Verkor. (Hidden Champion)
Swedish Growth Fund (private, Sweden) – A government-backed fund that invests in Swedish technology companies and battery manufacturing (Northvolt, Polarium). (Hidden Champion)
⚙️ 5. System Integration & Energy Management – “Components” = Power Electronics, Software, Grid Control
Who benefits: Hardware and software providers that control the energy system
$ABBN (-0,83%) ABB Robotics (VTX: ABBN) – Switzerland – Automation systems and robots for assembly, testing, and quality management
KUKA (ETR: KU2) – Germany – Leading provider of robotics and automation solutions for battery pack assembly
$ENR (-0,79%) Siemens Energy (ETR: ENR) – Germany – Grid integration, medium-voltage connections
$ETN (+0,61%) Eaton (NYSE: ETN) – Ireland – Grid protection, smart power distribution
$SU (-1,84%) Schneider Electric (EPA: SU) – France – BMS & EcoStruxure energy platform
$FLNC Fluence (NASDAQ: FLNC) – U.S. – Battery storage control (software + hardware)
Hidden Champions
Fronius International (privately held, Austria) – Specialist in welding technology and power supply systems for e-mobility
Comau (privately held, Italy) – Automation specialist for battery pack assembly, robotics, and testing systems. Close partnerships with automakers
Teamtechnik (privately held, Germany) – Develops automated test systems and production lines for battery and energy modules
Reis Robotics (privately held, Germany) – Specialist in precision robotics, welding, and joining processes in battery manufacturing
Software / AI:
TWAICE (privately held, Germany) – Offers a software platform for analyzing and optimizing battery lifecycles. Focus on condition monitoring, aging modeling, and second-life applications
AutoGrid Systems (privately held, U.S.) – AI-based software for energy management and grid optimization. Connects battery storage systems, solar farms, and wind farms to form virtual power plants
GridBeyond (private, Ireland) – Develops an AI platform for real-time grid control and energy trading optimization for industry and utilities
⚡ 6. Usage / Applications – “Shovels” = Charging Infrastructure, Power Management, Data Centers
Who benefits: Infrastructure, cloud, and network operators
$CHPT (+3,25%) ChargePoint Holdings (NYSE: CHPT) – U.S. – Operates one of the largest networks of electric vehicle charging stations in North America and Europe. Focus on software and infrastructure management
$ABBN (-0,83%) ABB Ltd. (VTX: ABBN) – Switzerland – Global energy and technology group, a leader in charging infrastructure, grid management, and industrial automation
$SIE (-0,92%) Siemens AG (ETR: SIE) – Germany – Technology and industrial conglomerate, strong in power distribution, automation, and digital grid systems
$VRT (+0,57%) Vertiv Holdings Co. (NYSE: VRT) – U.S. – Leading provider of power, cooling, and infrastructure solutions for data centers and telecommunications
$NVDA NVIDIA Corporation (NASDAQ: NVDA) – U.S. – Develops AI chips and data center architectures that optimize energy efficiency and performance management
$INTC (+2,77%) Intel Corporation (NASDAQ: INTC) – U.S. – Manufacturer of energy-efficient processors and data center platforms, with an increasing focus on AI workloads
$AMD (+1,74%) Advanced Micro Devices (NASDAQ: AMD) – U.S. – Manufactures high-performance processors and GPUs with a focus on improving efficiency in data center applications
Hidden Champions
$WBX (-1,68%) Wallbox N.V. (NYSE: WBX) – Spain – Manufacturer of smart chargers and energy management systems for electric vehicles and building integration
$SMCI Super Micro Computer, Inc. (NASDAQ: SMCI) – U.S. – Leading provider of energy-efficient server and data center architectures for AI and cloud infrastructure
$ALFEN (-3,46%) Alfen N.V. (AMS: ALFEN) – Netherlands – Specialist in smart grids and battery storage. Strong focus on European electromobility
Financiers / Operators:
$EQIX Equinix Inc. (NASDAQ: EQIX) – U.S. – The world’s largest data center operator. Increasingly investing in its own energy storage and microgrid solutions to improve efficiency and stabilize the power supply
$DLR (-1,42%) Digital Realty Trust Inc. (NYSE: DLR) – U.S. – Operates global cloud and colocation data centers. Focuses on integrating battery storage, renewable energy, and energy management systems
$BEP.UN Brookfield Renewable Partners L.P. (NYSE: BEP / TSX: BEP.UN) – Canada – Invests globally in renewable energy, storage technologies, and hydrogen infrastructure. A major financier and operator of hybrid energy systems
♻️ 7. Recycling & Second Life – “Shovels” = recycling technology, sorting machines, chemicals
Who benefits: Recycling plant manufacturers, software, and logistics
$ANDR (-0,81%) ANDRITZ AG (VIE: ANDR) – Austria - Manufacturer of mechanical and chemical processing plants for recycling and battery metal recovery
$NDA (-2,39%) Aurubis AG (ETR: NDA) – Germany – Europe’s largest copper producer and recycler. Entering the battery metal recovery sector to close raw material loops
$UMI (-4,94%) Umicore SA (EBR: UMI) – Belgium – Fully integrated materials and recycling group with closed-loop metal cycles
$LICY Li-Cycle Holdings Corp. (NYSE: LICY) – Canada – Operates hydrometallurgical recycling facilities for lithium-ion batteries
Hidden Champions
Tozero (privately held, Germany) – A startup with innovative hydrometallurgical technology for recovering lithium, nickel, and graphite
$AMY (+0%) RecycLiCo (TSXV: AMY) – Canada – Chemical processing of used batteries. Achieves high purity and low energy consumption
ACE Green Recycling (privately held, Singapore) – CO₂-neutral recycling processes for lithium and lead-acid batteries. Focus on energy efficiency and modular plants
Redwood Materials (private, U.S.) – A startup specializing in battery recycling and secondary raw material production with a focus on closed-loop supply chains
SMS Group (privately held, Germany) – Develops smelting plants and hydrometallurgical systems for metal and battery recycling
Funding Sources:
EU Circular Economy Fund (EU) – Supports European recycling and resource efficiency projects
Breakthrough Energy Ventures (U.S.) – Bill Gates’ climate fund, invests in new recycling technologies
EIT RawMaterials (EU) – EU initiative to support raw materials startups along the battery value chain
💰 8. Overarching Financiers & Strategic Fund Distributors
These players provide capital, technology, or infrastructure to all stages:
$BLK (-0,35%) BlackRock Inc. (NYSE: BLK) – U.S. – The world’s largest asset manager, investing in battery, raw materials, and energy technologies via thematic ETFs
Vanguard Group (private, U.S.) – One of the largest global fund providers, with passive investments in the energy and tech sectors
State Street Global Advisors (private, U.S.) – Manages institutional funds, including those focused on clean tech and infrastructure themes
SoftBank Vision Fund (private, Japan) – A private equity fund with investments in energy, battery, and robotics technologies
Temasek Holdings (private, Singapore) – A sovereign wealth fund focused on sustainable energy and infrastructure projects
$GS Goldman Sachs Group Inc. (NYSE: GS) – U.S. – Offers investments in energy storage and infrastructure projects through CleanTech and sustainable finance funds
$MS Morgan Stanley (NYSE: MS) – U.S. – Global financial services firm with dedicated funds for sustainable infrastructure and battery projects
Global X ETFs (U.S.) – Thematic ETF provider focused on lithium & battery tech, clean energy, and critical materials
$IVZ (+0,56%) Invesco (NYSE: IVZ) – U.S. – Asset manager with strategic holdings in CleanTech and infrastructure ETFs
$BEP.UN Brookfield Renewable Partners (NYSE: BEP) – Canada – Invests in clean energy, battery storage, and hybrid power plants worldwide
Hidden Champions
Khosla Ventures (private, U.S.) – Venture capital firm focused on clean tech, storage technologies, and materials innovation
InnoEnergy (private, EU / Netherlands) – EU-funded innovation network that supports startups along the European battery value chain
1️⃣5️⃣.Interconnections – Hybrid Energy Systems for Data Centers, Industry, and Transportation
Hybrid energy systems combine different energy sources—such as batteries, fuel cells, photovoltaics, wind power, and grid power—into a single, intelligently controlled system. The goal: maximum efficiency, stability, and reliability of supply with minimal emissions.
These systems are at the heart of Energy Infrastructure 4.0. They combine storage, control, and utilization on a single platform. What matters most is no longer which energy source is used, but how it is integrated.
1. Data Centers – Energy Efficiency Through Storage and Grid Intelligence
Core idea: Data centers are continuous consumers of energy. Hybrid systems combining battery storage, fuel cells, and grid management offset peak loads and power servers during grid outages without the need for diesel generators.
Technological integration:
Lithium- or sodium-ion batteries for short-term load peaks
Hydrogen fuel cells for emergency and long-term power supply
Intelligent energy management software (EMS) for load balancing
Relevant companies:
$VRT (+0,57%) Vertiv (NYSE: VRT) – U.S. – Power and cooling infrastructure for data centers
$SU (-1,84%) Schneider Electric (EPA: SU) – France – Digital power distribution, smart grids
$ABBN (-0,83%) ABB (VTX: ABBN) – Switzerland – Energy automation, modular microgrids
$EQIX Equinix (NASDAQ: EQIX) – U.S. – Operator; integrates battery storage and fuel cells
$NVDA NVIDIA (NASDAQ: NVDA) – U.S. – AI-based load control and optimization
2. Industry – Hybrid Power Systems and Load Management
Core Idea: Energy-intensive industries use combined systems comprising storage, renewable sources, and hydrogen to achieve grid independence and cost efficiency.
Technological Integration:
Battery storage (Li-ion, sodium, solid-state) for production peaks
Hydrogen for long-term storage
Heat recovery + grid control via AI
Relevant Companies:
$SIE (-0,92%) Siemens (ETR: SIE) – Germany – Industrial microgrids, energy management
$WRT1V (-3,2%) Wärtsilä (HEL: WRT1V) – Finland – Hybrid power plants for industry and island grids
$TTE (-0,92%) TotalEnergies (EPA: TTE) – France – Integration of solar, batteries, and hydrogen in industrial parks
AutoGrid (private, U.S.) – AI platform for energy management (Hidden Champion)
$ALFEN (-3,46%) Alfen (AMS: ALFEN) – Netherlands – Smart grid and storage systems.(Hidden Champion)
3. Transportation – Energy Infrastructure for New Mobility
Core idea: The transportation sector is increasingly becoming electric, but with a variety of energy sources. Hybrid infrastructures combine battery, hydrogen, and grid systems for road, rail, and aviation.
Technological connections:
Battery swap stations and fast-charging hubs
Hydrogen refueling stations + local electrolysis
Sector coupling between transportation, electricity, and heating
Relevant companies:
$TSLA (+4,51%) Tesla Energy (NASDAQ: TSLA) – U.S. – Energy storage and charging infrastructure
$NIO NIO Inc. (NYSE: NIO) – China – Battery-swapping networks
$005380 Hyundai Motor (KRX: 005380) – South Korea – Combination of battery and fuel cell propulsion
$BLDP (-2,16%) Ballard Power (NASDAQ: BLDP) – Canada – Fuel cells for commercial vehicles
$NEL (-1,29%) Nel ASA (OSL: NEL) – Norway – Hydrogen electrolysis and refueling systems
4. Interconnection Level – Energy System 4.0
At this level, batteries, fuel cells, renewable sources, and digital control converge into a shared flow of data and energy. The key lies in sector coupling: electricity, heat, mobility, and data share a dynamic grid.
Technology Platforms & Drivers:
$ENR (-0,79%) Siemens Energy (ETR: ENR) – Hybrid grid architectures, Power-to-X
Hitachi Energy (privately held, CH/JP) – Control systems and grid stabilization
$ETN (+0,61%) Eaton (NYSE: ETN) – Power distribution, load management
$ADSE (+1,98%) ADS-TEC Energy (NASDAQ: ADSE) – Fast-charging and storage systems. (Hidden Champion)
After examining the value chains and cross-sector applications, I’d now like to show you the whole picture in a simplified system diagram. The diagram visualizes the energy flow of a hybrid energy system: Renewable sources feed electricity into battery storage and fuel cells, which in turn supply consumers such as data centers, industry, and transportation. An AI control system connects all levels into a self-regulating, data-driven循环 system—the foundation of Energy Infrastructure 4.0.
Structure:
1. Energy Sources (top left)
Sun ☀️ → Photovoltaics
Wind 🌬 → Wind turbines
Grid power ⚡ → Feed-in from the public power grid
Hydrogen (H₂) → Produced by electrolysis from surplus energy
2. Conversion and Storage (center of the diagram)
Battery systems (lithium-sodium, solid-state) – short-term energy storage
Fuel cells / hydrogen tanks – Long-term storage and reconversion to electricity
Hybrid control / energy management system – AI-based control of energy flow
➜ Bidirectional arrows between battery ↔ fuel cell ↔ grid symbolize energy exchange and load management
3. Consumers (bottom right)
Data centers – Constant base load, backed up by storage and fuel cells
Industry – Flexible load control, use of hybrid energy for stabilization
Transportation sector – e-mobility, fast-charging hubs, hydrogen logistics
4. Data and Control Layer (above the center)
AI platforms (e.g., AutoGrid, TWAICE, NVIDIA)
Cloud integration for real-time data
Control of energy flow, CO₂ emissions, and costs
5. Feedback (below / base of the system)
Recycling → Raw material recovery → Cell production
Circular arrow visually leads back to the energy sources – symbolizing a closed-loop value chain
The hybrid energy flow illustrates how electricity, hydrogen, data, and raw materials reinforce one another in a circular, data-driven network. This is the foundation of Energy Infrastructure 4.0, which is dynamic, decentralized, and interconnected across sectors.
1️⃣6️⃣.Energy for humanoid robots: the next evolutionary stage of application
The next industrial revolution is no longer taking place solely in data centers or vehicles, but in the convergence of humans, machines, and energy. Humanoid robots symbolize this transition. These are systems that must think, act, and be self-sufficient. Their energy source is what makes them functional in the first place.
This is where battery technology, microgrid systems, and smart energy distribution intersect directly with artificial intelligence. Power density, longevity, and energy efficiency determine how autonomously these machines can operate. Whether in industry, healthcare, logistics, or everyday life, the stability of their energy supply is becoming a strategic factor for entire value chains. Next-generation batteries, solid-state systems, and mini fuel cells form the foundation for this. Companies that develop or supply these technologies are not only creating products but also building the infrastructure for a new form of intelligence that is energy-independent, networked, and scalable.
16.1 Technical Basis: What a Humanoid Really Needs in Terms of Energy
A humanoid robot is, at its core, a mobile energy system. It must walk, grasp, lift, balance, communicate, see, think, and remain safe while doing so. All of this requires a constant supply of energy.
Key requirements: high energy density with low weight, short-term power spikes, thermal stability, energy recovery, and long operating times without manual recharging. Currently, the energy requirements of humanoid robots range from 500 watts to 2 kilowatts, with energy storage capacities of 1 to 5 kilowatt-hours. A system is only considered suitable for industrial use if it can operate autonomously for several hours and recharge itself or swap modules.
16.2 Storage Status Today and in Five Years
Today:
Lithium-ion systems (NMC, NCA) dominate due to their high energy density.
LFP cells excel in safety and lifespan.
In five years:
Silicon anodes will increase energy density and charging speed.
Partially and fully solid-state batteries will improve safety and stability.
Combinations of batteries and fuel cells will emerge for continuous-load applications.
As a result, the robotics energy market is shifting toward modular, interchangeable high-performance cells with active thermal management and smart controls.
16.3 Industry Landscape
A. Cells and High Energy Density
$AMPX Amprius (NYSE: AMPX) – U.S. High-energy-density silicon anodes, ideal for robotics and drones
$ENVX (-4,95%) Enovix (NASDAQ: ENVX) – USA 3D cell architecture, compact and capable of fast charging
$QS QuantumScape (NYSE: QS) – U.S. Develops solid-state cells with ceramic electrolytes
$SLDP Solid Power (NASDAQ: SLDP) – U.S. Solid-state electrolytes for safe, high-performance cells
Sila Nanotechnologies (private, U.S.) Silicon anode materials for lighter systems
B. Battery Pack Architecture and Integration
$TSLA (+4,51%) Tesla Energy (NASDAQ: TSLA) – USA Vertically integrated battery packs including BMS
$NIO NIO Inc. (NYSE: NIO / HKG: 9866) – China Battery swap systems for modular power supply
$LECN Leclanché (SWX: LECN) – Switzerland Modular packs for industry and logistics
C. Actuators and Drive Mechanisms
$6324 (+1,87%) Harmonic Drive Systems (TYO: 6324) – Japan Precision gearboxes for humanoid joints
$6268 (+0,8%) Nabtesco (TYO: 6268) – Japan: Cycloidal gearboxes for high loads and stability
Maxon (privately held, Switzerland): High-performance, high-efficiency motors
D. Power Electronics and Control
$IFX (+0,64%) Infineon Technologies (ETR: IFX) – Germany Power semiconductors for motor control and power distribution
$STM STMicroelectronics (EPA: STM) – Switzerland / France Sensors and energy controllers
$TXN (-0,06%) Texas Instruments (NASDAQ: TXN) – U.S. BMS components and cell monitoring
E. Charging, Power Supply, and Infrastructure
$ADSE (+1,98%) ADS-TEC Energy (NASDAQ: ADSE) – Germany High-performance storage and fast-charging units
Wiferion (privately held, Germany) Inductive charging for autonomous systems
$ALFEN (-3,46%) Alfen (AMS: ALFEN) – Netherlands: Smart grids and charging infrastructure for robotics and industry
F. Control, Fleet Management, and Energy Intelligence
TWAICE (privately held, Germany) Software for battery health and lifespan prediction
AutoGrid (privately held, U.S.) AI-based platform for energy distribution and load control
$NVDA NVIDIA (NASDAQ: NVDA) – U.S. Computing platforms for real-time control and energy management
16.4 Who Has the Most Potential
In the short term: Harmonic Drive Systems, Nabtesco, Maxon—because every humanoid robot needs precise, efficient joints.
Medium term: Amprius, Enovix, Sila, QuantumScape, Solid Power—they increase energy density and operational reliability, the key criteria for autonomy.
System-wide: NVIDIA, AutoGrid, TWAICE – because the future lies not only in storage but also in the intelligent control of energy flow.
16.5 Practical Blueprint – Energy Stack of a Humanoid Robot
Energy Storage: Lightweight, high-energy battery module with active thermal management, based on NMC or silicon.
Drive: BLDC motors with harmonic or cycloidal gearboxes, integrated regenerative braking. Power electronics: Inverters and DC/DC converters from Infineon or STMicro, BMS from Texas Instruments.
Charging Infrastructure: Quick-swap packs, inductive intermediate charging with ADS-TEC or Wiferion.
Intelligence: Status diagnostics via TWAICE, energy coordination via AutoGrid, computational control via NVIDIA.
A stack like this not only makes humanoid robots operational but also economically viable. It’s no longer just about robotics—it’s about energy expertise. Whoever masters this stack controls not only the machine but also the business case behind it.
1️⃣7️⃣.Takeaway
The battery industry has long since evolved from a standalone solution into a multifaceted ecosystem in which materials, technologies, data, and energy flows are intertwined. Hybrid energy systems that combine batteries, fuel cells, and renewable sources are no longer a vision but a reality, evident in data centers, industrial parks, and transportation systems around the world. What matters most is no longer just how energy is generated or stored, but how it is intelligently controlled and integrated into existing grids. This is precisely where the real added value lies: in the ability to synchronize energy flows, data systems, and capital flows. Perhaps this is the point at which it will be decided in the future who will shape true energy autonomy—those who produce energy, or those who can control it precisely?
1️⃣8️⃣.Sources & data used:
International Energy Agency (IEA) – Global EV & Battery Outlook 2024
BloombergNEF – Battery Supply Chain & Energy Storage Report
McKinsey & Company – Battery Value Chain 2030
Fraunhofer ISI – Energy System Analysis: Germany & the EU 2024
Company Reports & Investor Relations:
CATL, Tesla, Northvolt, Siemens Energy, Hitachi Energy
Manz AG, Vulcan Energy, Li-Cycle, Umicore, Albemarle
Market Analyses: Benchmark Minerals Intelligence, S&P Global, Reuters Energy Desk
Research Sources: IEA Hydrogen Roadmap, EU Strategic Raw Materials Act, Battery Passport Initiative (Global Battery Alliance)
Images:
Illustrative image — JLStock / Shutterstock.com
Photo: dpa
https://tse1.mm.bing.net/th/id/OIP.Zs6cG53hAFkOB4TXG0psVgHaDR?pid=Api&P=0&h=180
+ 1
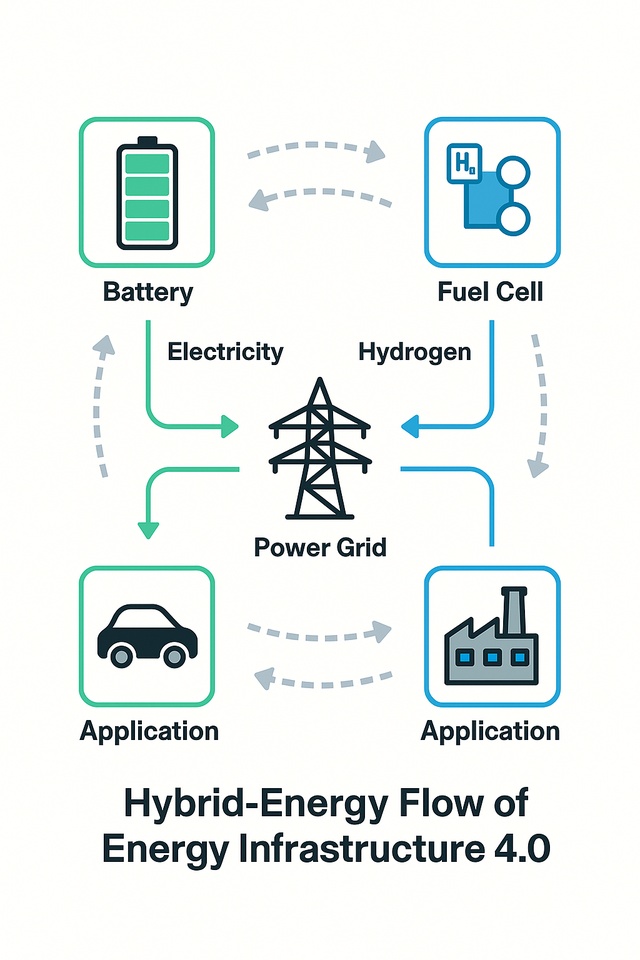
215215
98 Comentários11Mês
Wow, wow, and wow again, you really knocked it out of the park early Sunday morning. I don't want to know how many hours you invested in bringing this topic to the community in all its facets.
A big thank you for that👃👃👃👃
Even though you have refrained from naming your favorites, I would like to briefly mention mine from the smallcaps area.
I think
$AMPX, $SSW, $SLI, $UMICY and $PCELL very interesting and, for me, the most important, promising in terms of price performance.
Of the larger ones in the long term, $6752 and $3750
But of course I haven't looked at all of them in the short time available, but rather the ones that were already in my focus before your master's thesis 😉😊
•
3131
•
11Mês·
Trump lifts strict environmental regulations for copper smelters
US President Donald Trump has once again reversed a regulation introduced by his predecessor Joe Biden. This means that the copper producers Freeport-McMoRan and Rio Tinto will no longer be subject to key environmental regulations.
》It is another step backwards for environmental policy《
On Friday, US President Donald Trump lifted a requirement for copper smelters introduced by his predecessor Joe Biden. The new order means that the two affected plants of Freeport-McMoRan and Rio Tinto will not have to comply with central environmental regulations for the next two years. Copper smelters produce, process and purify material from various raw materials.
The White House justified the move with the aim of promoting the security of the American mineral supply and freeing domestic copper producers from regulatory burdens.
"Imposing these requirements on such a limited and already strained domestic industry risks accelerating further closures," the US government stated.
Both Freeport-McMoRan and Rio Tinto did not initially respond to a request for comment.
The Biden administration's rule, finalized in May 2024, had required the two copper companies to reduce emissions of pollutants such as lead, arsenic, mercury and benzene. Trump had already classified copper as a strategically important raw material for defense, infrastructure and new technologies by decree at the beginning of the year.
As I am only a co-author of this article, I would like to take this opportunity to thank @Tenbagger2024 for the great research 👍🏻
11Mês·
Quartalsberichte 21.10-24.10.25
$NDAQ (-0,54%)
$RTX (-0,26%)
$KO (-0,05%)
$MMM (-1,33%)
$NOC (-0,53%)
$LMTB34
$OR (-0,6%)
$TXN (-0,06%)
$NFLX (-0,8%)
$HEIA (+0,64%)
$SAAB B (+0,23%)
$UCG (-1,73%)
$BARC (-3,61%)
$GEV (-0,94%)
$TMO (-1,37%)
$T (-0,96%)
$MCO (-0,81%)
$IBM (+2,26%)
$SAP (+1,3%)
$TSLA (+4,51%)
$AAL (-1,43%)
$FCX (+0,32%)
$HON (-0,43%)
$DOW (+0,6%)
$NOKIA (-0,27%)
$TMUS (-0,47%)
$INTC (+2,77%)
$NEM (-0,08%)
$F (-1,81%)
$PG (-0,45%)
$GD (-0,59%)
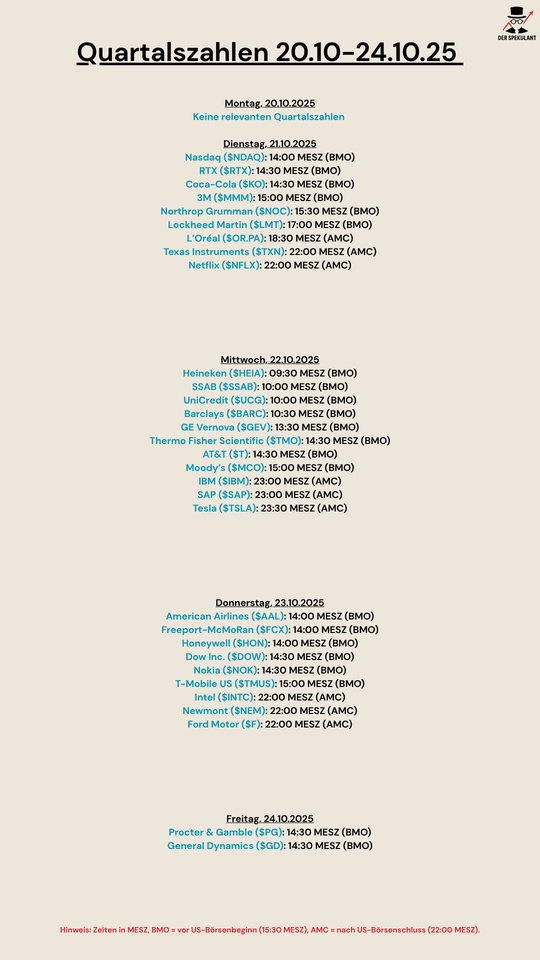
44

1Ano·
Gold price - analysis 🥇🪙
+50% since the beginning of the year
Customs policy
Monetary policy
Gold ETFs
World Gold Council
Gold price forecast
Silver price forecast
Link: https://shorturl.at/ruX9X
$GLD (-0,33%)
$GLD
$ABX (-1,1%)
$NWPG
$FCX (+0,32%)
$GLDA (-0,21%)
$GOLD (-4,05%)
$GOLD
$IGLN (-0,11%)
#gold
#silber
#edelmetalle
88

1Ano·
Supercycles: opportunities and risks for investors
From time to time, there are movements on the markets that last longer than a normal upswing. This is known as a super cycle - a phase in which certain commodities or technologies are in demand for many years and their prices rise significantly. This is usually due to fundamental changes in the economy and society.
A well-known example is China in the 2000s. Rapid construction activity and industrialization led to raw materials such as iron ore or coal becoming increasingly expensive over the course of a decade. In this context, there is often talk of the "commodity supercycle", which was driven by the massive demand of Chinese construction and industrial policy. In recent years, this is how I perceive the technology sector in particular: cloud services, automation and artificial intelligence have caused demand for semiconductors to explode.
I currently have the impression that new super cycles could be on the horizon again. In the uranium sector in particular, it is noticeable that many countries are bringing nuclear energy more into play. This is already reflected in my own portfolio. I differentiate between core stocks and leverage stocks. The core stocks are my basic investments: $CCO (-0,3%) (Cameco) and $YCA (-1,27%) (Yellow Cake). Both are established, comparatively stable and form the foundation on which my uranium strategy rests. Leveraged stocks, on the other hand, are more speculative and react much more strongly to market movements. Here I am betting on planned positions in $NXE (+1,91%) (NexGen Energy), $DML (-0,98%) (Denison Mines) and $PDN (+0,08%) (Paladin Energy). I have currently set orders for these stocks, which will only be executed when the risk/reward ratio is right. This allows me to build up the positions in a controlled manner and keep the risk within limits.
Another example of a possible super cycle is the defense industry. Prices there have already risen sharply in recent years, driven by geopolitical tensions and rising defense spending. I personally missed this trend - but this is precisely the lesson: markets move in waves and anyone who misses a cycle should not look back, but forward. Because there are always new opportunities if you recognize the structural changes early on.
In addition to uranium, copper could also play a role again. The major producers in particular $FCX (+0,32%) (Freeport-McMoRan) and $SCCO (+0%) (Southern Copper) are particularly interesting if the global grid expansion and electrification actually trigger a new boom in demand.
I am interested: What's your take on this? Is a new super cycle emerging here, especially in the uranium sector - or is this more of a short wave? Which stocks do you think are exciting and what strategies are you pursuing yourself?
1Ano·
Copper?
Any opinions on future copper/iron price movements?
After the strong silver and gold rally, they could/should follow suit. In my opinion they are still undervalued, the Chinese are pumping liquidity into the markets, so that could be promising, right?
I don't know many stocks there, something like Rio Tinto with a focus on dividends interests me less, more the growth stocks.
I did a bit of reading and found that in the copper sector $ASCU , $ERO (+1,07%) , $HBM (+1,16%) , iron stocks like $ASX (+2,33%) etc. - but I'm not very impressed by the chart.
$FCX (+0,32%) I remember it from earlier times, but it's also bobbing along.
It's not intended to be a long-term position, but rather a short/medium-term trade. At least it would make sense to me if shares in this sector were to pick up soon.
In terms of returns, however, I see $BMNR (-0,31%) almost a greater leverage, assuming that an ETH rally follows, which I expect.
I look forward to your opinions!
22
2 Comentários
You will look in vain for growth in commodity stocks, they live from their volatility, so you should either prefer other stocks or adjust your strategy... What do you think of digital copper ( $SOL ) xD just kidding.
••
Títulos em alta
Principais criadores desta semana
Dados tempo real da LSX · Dados financeiros e EOD da FactSet