BASF
Price
Discussão sobre BAS
Postos
277

BASF Stock in 2026: Can a Takeover Still Save the Company?
Summary:
To some extent—and it is precisely this “to some extent” that makes the current situation at BASF so complex. At the Ludwigshafen headquarters, the workforce has fallen to its lowest level in more than 70 years, and the site has posted losses for four consecutive years. Against this backdrop, BASF confirmed on September 25, 2026, that it was engaged in exploratory talks regarding a potential acquisition of Evonik Industries—a move that could strategically strengthen its position in the German chemical industry. However, the first attempt has already failed: According to the Financial Times, Evonik rejected the offer of 22.15 EUR per share (total value of approximately 10.3 billion EUR, roughly 23% of BASF’s own market value) as too low. Major shareholder RAG Foundation, which holds a 44% stake in Evonik, is considered a decisive factor in how the situation will unfold. Meanwhile, BASF remains solid from an operational standpoint: Following strong Q2 results with EPS jumping to EUR 4.78, management raised its EBITDA forecast. The stock is currently trading at approximately 50.57 EUR.
Key points:
Ludwigshafen workforce at its lowest level in over 70 years; fourth consecutive year of lossesCoreShift cost-cutting program: up to a 20% reduction in fixed costs in the core business by 2029; at the same time, BASF is investing EUR 1.5 billion annually in Ludwigshafen; BASF inaugurates a new EUR 10 billion plant in Zhanjiang, China — Capital shift draws criticismEvonik rejects BASF’s offer of 22.15 EUR per share (10.3 billion EUR, approx. 23% of BASF’s market value) The RAG Foundation (44% stake in Evonik) is considered a key factor in the future course of events Q2 2026: EPS of 4.78 EUR (previous year: 0.09 EUR), EBITDA forecast raised; Deutsche Bank (Buy, 60 EUR), Bernstein (Outperform, 61 EUR), DZ Bank (Buy, 64 EUR) Price: approx. 50.57 EUR — crossed below the 100-day moving average on September 25
Current Key Figures — BASF Stock (as of September 30, 2026)
Key FigureValueAs of
Price (XETRA: BAS)
approx. 50.57 EUR
September 30, 2026
52-Week High
55.05 EUR
April 14, 2026
52-Week Low
41.48 EUR
November 5, 2025
Distance from 52-Week High
approx. −8 to −9%
September 30, 2026
Revenue Q2 2026
17.21 billion EUR (+9.11% YoY)
July 15, 2026
EPS Q2 2026
4.78 EUR (previous year: 0.09 EUR)
July 15, 2026
EBITDA Forecast for 2026
6.2–7.0 billion EUR, raised after Q2
2026
Workforce in Ludwigshafen
Lowest level in over 70 years
June 2026
Global workforce
approx. 94,900 (−14.4% YoY)
June 2026
Ludwigshafen results
4th consecutive year of losses
2024/2025
Ludwigshafen investment (ongoing)
1.5 billion EUR annually
—
CoreShift cost-saving program
up to −20% fixed costs in core business by 2029
Announced in May 2026
New plant in China (Zhanjiang)
Approx. EUR 10 billion investment, inaugurated in March 2026
March 2026
Evonik Offer (rejected)
EUR 22.15 per share, EUR 10.3 billion total
Reported Sept. 29, 2026
Offer as % of BASF market value
approx. 23%
—
RAG Foundation’s stake in Evonik
approx. 44%
—
Dividend 2025 / expected 2026
2.25 EUR / 2.27 EUR
—
Dividend yield
approx. 4.5%
Sept. 2026
100-day moving average
Crossed below on Sept. 25, 2026 (at 50.46 EUR)
Sept. 25, 2026
WKN / ISIN / Ticker
BASF11 / DE000BASF111 / BAS
—
Deutsche Bank / Bernstein / DZ Bank
Buy 60 EUR / Outperform 61 EUR / Buy 64 EUR
September 28–29, 2026
Next quarterly results (Q3)
October 28, 2026
—
BASF Stock News — All the latest updates at a glance
Date | News | Details | Assessment
September 29, 2026
Evonik Rejects Takeover Offer
According to the Financial Times, Evonik has rejected the offer of 22.15 EUR per share (10.3 billion EUR total, approx. 23% premium) as too low. The RAG Foundation (44% stake) has not commented on the offer price but is considered a decisive factor in determining next steps.
Key
September 28–29, 2026
Analysts Reaffirm Buy Recommendations
Deutsche Bank (Buy, 60 EUR), Bernstein (Outperform, price target lowered from 63 to 61 EUR), and DZ Bank (Buy, 64 EUR) maintain their “Buy” ratings despite the uncertain takeover situation.
Bullish
September 25, 2026
Exploratory talks with Evonik confirmed
BASF officially confirms talks with the RAG Foundation and Evonik Industries. On the same day, the stock crosses below its 100-day moving average.
Neutral
May 2026
CoreShift cost-cutting program unveiled
New restructuring program aims to reduce fixed costs in the core business by up to 20% by 2029—including further job cuts and the outsourcing of service jobs to India.
Bearish
March 2026
New plant in Zhanjiang, China, inaugurated
BASF officially inaugurates its new plant in Zhanjiang, which cost approximately 10 billion EUR—the Group’s third-largest integrated site after Ludwigshafen and Antwerp. The shift of capital away from Germany draws criticism.
Controversial
July 15, 2026
Strong Q2 and Raised EBITDA Forecast
Earnings per share jump to 4.78 EUR (previous year: 0.09 EUR), and revenue rises by 9.11% to 17.21 billion EUR. Management subsequently raises the EBITDA forecast for the full year.
Very Bullish
What does BASF do—and how exactly does the company make money?
Company Description
BASF BASF SE (ISIN: DE000BASF111, WKN: BASF11), headquartered in Ludwigshafen am Rhein, is the world’s largest chemical company. The company organizes its business into eleven business units, which are grouped into six segments—divided into core businesses and standalone businesses.
The four core businesses—and how BASF specifically makes money:
Chemicals: Petrochemicals and Intermediates — form the heart of the BASF Verbund. It generates revenue through the sale of basic chemicals and intermediates to both external customers and its own segments. Materials: Performance Materials and Monomers — one of the world’s leading suppliers of high-performance plastics. Generates revenue through engineering plastics, polyurethanes, and specialty plastics for the automotive and construction industriesIndustrial Solutions: Dispersions & Resins and Performance Chemicals — develops ingredients and additives for industrial applications such as polymer dispersions, resins, and electronic materialsNutrition & Care: Care Chemicals and Nutrition & Health—generates revenue from ingredients for personal care, food, and pharmaceutical products
The real crux of the matter, however, lies not in the segment structure but in the headquarters itself: Ludwigshafen has been struggling for years with high energy costs and overcapacity, and has most recently posted losses for four consecutive years. It is precisely against this backdrop that the potential Evonik acquisition takes on special significance—an acquisition that could create economies of scale and market power, while the core location is simultaneously shrinking. Similar to the RENK Aktie, where a targeted acquisition was intended to open up new market access, BASF is focused on strategic repositioning—only under significantly more challenging structural conditions.
Fundamental Analysis: How Deep Is BASF’s Crisis, Really?
Fundamental Analysis of BASF Stock 2026
The situation is more nuanced than the headlines suggest—the group as a whole is not in danger, but its core German operations certainly are.
Valuation in the context of two conflicting narratives: At the corporate level, BASF is demonstrating operational strength with an EPS jump to 4.78 EUR and an upwardly revised EBITDA forecast (6.2 to 7.0 billion EUR for 2026). At its Ludwigshafen headquarters, however, the workforce has fallen to its lowest level in more than 70 years, and the site has posted losses for four consecutive years. This dual nature—a profitable group as a whole, a loss-making core site—is the real reason why the question “Can a takeover save the group?” is even being asked.
Margin Development and the CoreShift Program: The CoreShift cost-cutting program, unveiled in May, aims to reduce fixed costs in the core business by up to 20% by 2029—including further job cuts and the outsourcing of service jobs to India. At the same time, BASF continues to invest 1.5 billion EUR annually in Ludwigshafen, which shows that management is not opting for a retreat, but rather for a painful yet targeted restructuring.
Financial Health and the Evonik Issue Following the Rejection: With a dividend yield of approximately 4.5%, BASF remains financially viable. However, the fact that Evonik rejected the initial offer of 22.15 EUR per share as too low indicates that a potential deal could end up costing more than originally calculated, which further complicates the financing issue. The RAG Foundation, with its 44% stake, holds the real key to the situation.
Segment Analysis — China as a Counterpoint: The inauguration of the new plant in Zhanjiang—which cost approximately 10 billion EUR—in March 2026 shows where a significant portion of investment capital is currently flowing—not to Germany. This shift in capital is strategically understandable given the lower energy costs in China, but it further intensifies the debate over the future of Germany as a nuclear hub.
Conclusion of the fundamental analysis: BASF as a corporate group is not financially at risk—its operating figures and dividend capacity indicate otherwise. Its German headquarters in Ludwigshafen, however, is facing a genuine, structural crisis that a single acquisition alone cannot resolve. An integration with Evonik could strengthen the group as a whole without resolving the underlying problems at the Ludwigshafen site.
How is the BASF stock price performing?
Current chart analysis and price targets for BASF stock (as of October 1, 2026)
In early September 2026, following strong Q2 results and an upward revision of the EBITDA forecast, the BASF stock price came very close to its 52-week high of 55.05 EUR. Since July 13, 2026, however, the stock has been in a consolidation phase, which intensified technically on September 25—the day Evonik confirmed — when the price crossed the 100-day moving average at EUR 50.46. Evonik’s rejection of the takeover bid on September 29 did not trigger any additional price movement, suggesting that the market had not expected a quick resolution in the first place. The stock is currently trading at approximately 50.57 EUR. A similar pattern of operational strength coupled with structural location issues was most recently also evident in Lufthansa Aktie, where cost pressures at the home market also contrast with a fundamentally positive analyst outlook.
Key price levels:
52-week high: 55.05 EUR (April 14, 2026)52-week low: 41.48 EUR (November 5, 2025)Current price: approx. 50.57 EUR (September 30, 2026)100-day moving average: 50.46 EUR — crossed downward on September 25First resistance: 54.275 EURSecond resistance: 70–71 EURCritical support level: A drop below 46 EUR would confirm renewed weakness
Chart Analysis:
The chemical giant’s stock has been trading sideways for years. It is clear that a strong trading range has formed between 37.50 and 54 EUR. Within this range, I rate the stock as neutral. Should the price fall below 46 EUR, sellers would once again have a slight advantage in pushing the share price toward 37.50 EUR. If this level were to be breached amid strong selling pressure, a further medium-term decline to 28.50 EUR would not be unlikely.
If, on the other hand, the price were to break above 54 EUR, further buying interest could quickly emerge, pushing the price up to around 71 EUR.
Conclusion: Can a takeover still save the BASF Group?
My assessment: Hold / Wait
The honest answer: The Group as a whole doesn’t need saving, but its German headquarters in Ludwigshafen does. An integration with Evonik would strategically strengthen the chemicals business and create economies of scale, but it would not solve the structural problems—high energy costs, overcapacity, four consecutive years of losses—at its actual home base. Evonik’s rejection of the initial offer also shows that even this strategic option won’t come at a bargain price. A similar tension between a solid corporate balance sheet and a challenging home market is currently evident at Deutsche Bank Aktie.
Those who believe in BASF’s long-term fundamentals despite the location-related challenges and view the Evonik issue as a bonus rather than a necessity will find an entry point here with a solid 4.5% dividend yield and analyst targets well above the current price. Those who want to play it safe should watch how the takeover poker game with Evonik and the RAG Foundation unfolds in the coming weeks, wait for the Q3 results on October 28, and see if the price breaks above 54 EUR.
Would Evonik $BAS (-0,15%) get things moving again? What do you think??


This is what happened last week
Tuesday:
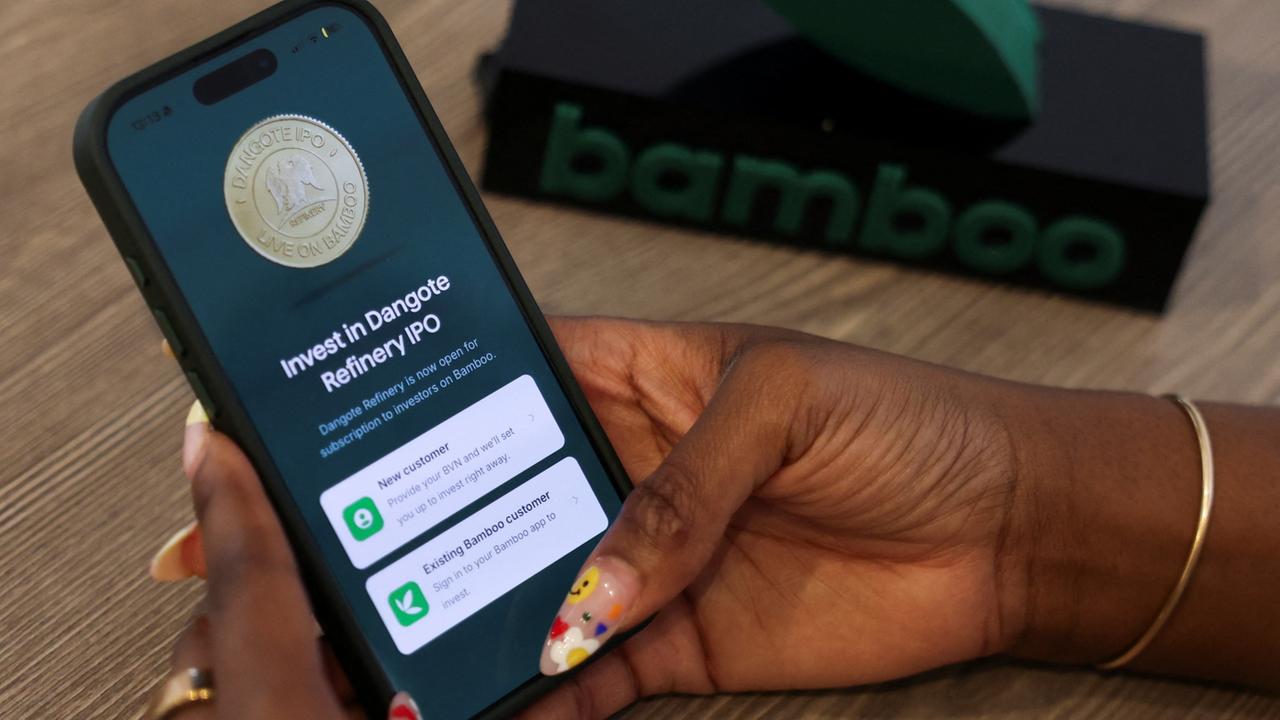
Aliko Dangote is taking his oil refinery public. It is the largest in Nigeria and could now be expanded to become one of the largest in the world. The company benefited from the kerosene shortage in the first half of the year and posted a profit of about 1.8 billion USD.
https://www.tagesschau.de/wirtschaft/energie/oel-boom-nigeria-100.html
Thursday:
U.S. Treasury yields reach new record highs, which also drives up yields in Germany, the U.K., and Japan. The level is now so high that it is weighing on other asset classes, such as stocks.
$NVDA (-0,41%) NVIDIA is now valued at a P/E ratio of just 18—the company hasn’t been this cheap since the 2010s. However, NVIDIA’s margins are so exorbitantly high that many market participants do not believe they can be sustained. Therefore, while the 18 P/E ratio appears cheap, it could rise significantly if margins were to fall sharply.
Friday:
$BAS (-0,15%) BASF is planning to acquire its competitor $EVK (+3,72%) Evonik. As is almost always the case with takeovers, the shares of the target company react very positively, while the buyer’s shares fall. So far, there has been no concrete offer, only initial contact with banks.


Welcome to the Darkside
July 2026 Review
📊 Performance & Markets
🏆 Hot Factor Favorite: $NVDA (-0,41%)
👑 King Midas Factor: $CRM (-0,27%)
💶 1 Swiss franc traded at 1.06 euros.
₿ Crypto & Alternative Investments
Crypto savings plans are underway
There were no new purchases or sales at Timeless; Timeless is now planning to launch a tradable product for the general public. There’s also no news regarding NFTs and music rights.
🍷 Winery
No news.
📈 Individual Stocks, ETFs & Savings Plans
🟢 Buy: Individual stocks on hold until November
🔴 Sale: $SHL (+0,12%)
, $BAS (-0,15%)
🏅 Top of the Month: $BTO (-1,83%)
📉 Flop of the Month: $LIFT (-1,59%)
🚀 Crowdcube & Startups
I’m thinking about buying shares in Lemonaid through the GLS Crowd platform.
🧠 Nao
My savings plans are still on track.
🌴 Personal Recap
I actually won some travel credit in the CHECK24 prediction game and a 10-franc gift card from Kickstr. Unfortunately, starting with the quarterfinals, practically all my predictions were wrong.
I still don’t have a new smartphone, and the special payment hasn’t been made yet either.
Berlin, on the other hand, was absolutely amazing—the Finch concert was truly a world of its own.
Right now, I’m thinking about placing a bet on the price of coffee. I’m also very happy that my $NA9 (+0%) stock is being acquired.
I went to a rum and meat tasting with a very good friend. It was incredibly delicious, and with the heat, the rum really went to my head.
Through an acquaintance I met there, I learned that the owner isn’t averse to investments. That’s why I had the idea to combine a finance get-together with a tasting. Would you book something like that?
To my great delight, I’m getting a refund of about €11,000 from the tax office. I haven’t decided yet what I’ll do with it or how I’ll use the money, though.
Unitplus is going as planned.
🎙️ Podcast Season 3, Episode 1 has launched. Topic: Financial Goals.
🔮 Outlook for August
Various events at work. Family visiting. Another 10 days of vacation starting at the end of August
How about you? How was your July?
If you’d like to learn more, feel free to follow me. And if you don’t like my investments: The block feature still works great. 😄

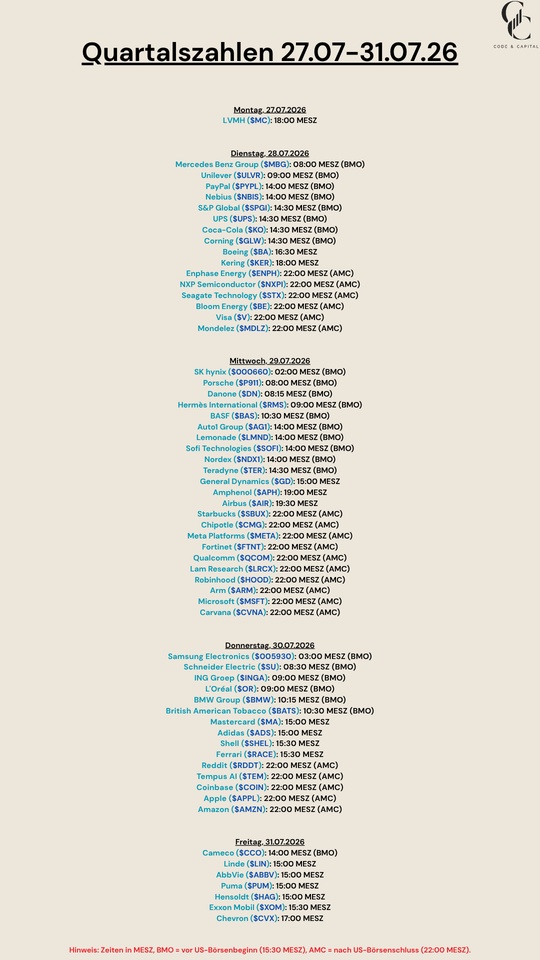
Quarterly Results: July 27–July 31, 26
$MC (-1,54%)
$MBG (-1,34%)
$ULVR (-0,5%)
$PYPL (-0,46%)
$NBIS (+1,36%)
$SPGI (-0,41%)
$UPS (-0,3%)
$KO (-2,47%)
$GLW (+0,23%)
$BA (+0,48%)
$KER (-8,53%)
$ENPH (+2,68%)
$NXPI (-0,3%)
$STX (+3,48%)
$BE (-5,12%)
$V (-0,95%)
$MDLZ (-1,4%)
$000660
$P911 (-3,01%)
$BN (-0,03%)
$RMS (-2,56%)
$BAS (-0,15%)
$AG1 (+0,41%)
$LMND (-0,94%)
$SOFI (-0,84%)
$NDX1 (-1,75%)
$TER (+1,66%)
$GD (-0,46%)
$APH (+1,04%)
$AIR (-1,34%)
$SBUX (-1,16%)
$CMG (-1,8%)
$META (-0,39%)
$FTNT (+3,29%)
$QCOM (+2,25%)
$LRCX (+0,98%)
$HOOD (-1,11%)
$ARM (+0,91%)
$MSFT (+0,62%)
$CVNA (-1,21%)
$005930
$SU (-2,1%)
$INGA (-1,65%)
$OR (+1,62%)
$BMW (+0,76%)
$BATS (-1,1%)
$MA (-1,36%)
$ADS (-1,12%)
$SHEL (+2,32%)
$RACE (-0,98%)
$RDDT (-3%)
$TEM (+6,4%)
$COIN (-2,34%)
$AAPL (-0,05%)
$AMZN (-0,76%)
$CCO (+0,17%)
$LIN (+0,26%)
$ABBV (+0,16%)
$PUM (-0,14%)
$HAG (+2,12%)
$XOM (+2,77%)
$CVX (+2,97%)
Top News Stories from the Past Week
As we do every Sunday, here are the top news stories from the past week.
Monday:
Politically explosive developments on the supervisory board of $VOW (-0,94%) VW. Shareholder Qatar is blocking the sale of VW plants to an Israeli defense contractor, which could use them to manufacture parts for the Iron Dome. The German federal government itself uses the Iron Dome as part of its defense strategy.
Tuesday:
Weak figures from $IBM (+1,09%) IBM are dragging the entire software sector down. Revenue fell significantly short of expectations. In particular, anticipated software investments appear to have failed to materialize.
Wednesday:
$BAS (-0,15%) BASF raises its forecast, but the stock still falls. This is primarily due to the outlook for the second half of the year, in which BASF continues to see risks. In Q2, revenue rose by 16%. The earnings forecast was raised to a range of 6.9–7.7 billion euros.
https://www.deraktionaer.de/artikel/aktien/basf-hebt-prognose-an-aktie-sinkt-dennoch-20404774.html
Friday:
The inflation rate in the eurozone fell to 2.8% in June. Nevertheless, inflation remains well above 2.0%. The ECB is therefore caught in a dilemma between inflation and growth concerns. The next interest rate decision is due in just six weeks.
Trump wants to sell faster access to his posts on Truth Social. The reason is that his posts often move the markets. To put it bluntly, one could say Trump now wants to bring insider trading to market maturity.


Is BASF Heading for a Mega-IPO? Could the Agricultural Division Soon Be Worth More Than Half the Company?
Following the previously reported sale of the coatings business of $BAS (-0,15%) it appears that the restructuring is continuing to move forward. Financial circles are currently speculating about a valuation of the $BAS (-0,15%)agricultural division ranging from 20 to 30 billion euros. What is remarkable about this is that $BAS (-0,15%) the company as a whole is currently valued at only about 45 to 50 billion euros on the stock market. In other words: A business unit that makes up only a portion of the conglomerate could, on its own, be worth nearly half of the current market capitalization.
In my view, this highlights a problem that many large conglomerates face. The stock market often applies a valuation discount (conglomerate discount) to them. Different business segments with varying growth profiles are often valued lower under one umbrella than they would be as standalone companies. This very point was discussed in the latest Handelsblatt podcast. An independently listed agricultural business could therefore command a significantly higher valuation multiple than it would within the $BAS (-0,15%)group.
Of course, there are also risks. The agricultural division is one of the faster-growing and higher-margin segments of $BAS (-0,15%) . A partial spin-off could lead to the remaining group being perceived as more cyclical. At the same time, $BAS (-0,15%) the IPO would bring in fresh capital, while the group would remain the majority shareholder and thus continue to participate in the agricultural division’s future performance. It is precisely this mix of value unlocking and further upside that makes the move interesting, in my view.
Many are also wondering whether existing $BAS (-0,15%)shareholders will automatically receive shares in the new company. As things stand, that is not planned. $BAS (-0,15%) The group is planning a partial IPO, will remain the majority shareholder, and has not yet announced any allocation of shares to existing $BAS (-0,15%)shareholders. Anyone wishing to invest later would likely have to purchase the new shares on the open market.
Personally, I view the planned IPO rather positively so far. If it $BAS (-0,15%) succeed in reducing the group’s valuation discount while remaining the majority shareholder of an agricultural company valued higher on its own, this could also benefit us $BAS (-0,15%)shareholders in the long run.
What do you think? Is the group divesting itself of one of its most attractive business units, or do we see a clever move here in the form of an IPO that could lead to a revaluation of both the individual division and the group as a whole?
~ Not investment advice ~


𝐁𝐀𝐒𝐅: 𝐒𝐭𝐚𝐫𝐤𝐞𝐬 𝐐𝟐, 𝐄𝐫𝐠𝐞𝐛𝐧𝐢𝐬𝐚𝐮𝐬𝐛𝐥𝐢𝐜𝐤 𝐟𝐮̈𝐫 𝟐𝟎𝟐𝟔 𝐚𝐧𝐠𝐞𝐡𝐨𝐛𝐞𝐧
📊 𝐄𝐫𝐠𝐞𝐛𝐧𝐢𝐬𝐬𝐞
• Revenue: €17.2B (+16%, consensus: €16.5B)
• EBITDA before special items: €2.4B (consensus: €2.1B, prior year: €1.6B)
• EBIT before special items: €1.5B (consensus: €1.1B, prior year: €0.7B)
• Net income: €4.1B (consensus: €2.4B, prior year: €79M)
• Free cash flow: -€0.2B (vs. +€0.5B)
⠀
🎯 𝐀𝐮𝐬𝐛𝐥𝐢𝐜𝐤
• EBITDA before special items now expected to be €6.9B–€7.7B (previously: €6.2B–€7.0B)
• Free cash flow still expected to be €1.5B–€2.3B
⠀
📌 Key Points
• Earnings significantly exceed analyst consensus
• Higher prices and sales volumes drive revenue growth
• Gain on disposal from the Coatings transaction contributes significantly to consolidated earnings
• Free cash flow impacted by higher capital tied up due to increased raw material prices

BASF is selling its Coatings division—what does that mean for us shareholders?
With the completion of the sale of the Coatings division to the new company Surventis, $BAS (-0,15%) an important step in the “Winning Ways” strategy. $BAS (-0,15%) It will receive approximately €5.8 billion in cash, while retaining a 40% stake in Surventis. This means the Group is not completely divesting itself of a profitable business but will continue to participate in its future value growth.
In my view, that is precisely the interesting part of the deal. $BAS (-0,15%) It will be able to focus more strongly on its core business in the future, while simultaneously freeing up capital and still retaining the opportunity to benefit from Surventis’s successful development. Should the company continue to gain value under the new ownership structure, $BAS (-0,15%) continue to benefit through the 40% stake.
For us shareholders, the key question now will be how $BAS (-0,15%) the company uses the freed-up funds. Possible options include further debt reduction, investments in the core business, or additional capital returns. In any case, the ongoing share buyback program through 2028 gains additional potential financial flexibility thanks to the inflow of funds.
I therefore view the deal positively overall: $BAS (-0,15%) it simplifies the group’s structure, strengthens the balance sheet, and at the same time keeps a foot in the door in case Surventis continues to gain value in the coming years.
How do you assess this move? Is it a successful allocation of capital, or would you have preferred a complete sale?
https://www.basf.com/cn/en/media/news-releases/asia-pacific/2026/07/apac-26-74
~ Not investment advice ~


Podcast episode 146 "Buy High. Sell Low." Nvidia, Hims & Hers, Take Two / GTA 6, Duolingo, Thyssen, BASF
After 20 minutes the video quality improves. Adobe Studio has apparently failed.
YouTube
https://openyoutu.be/rbWcp0BNRK4
Spotify
https://open.spotify.com/episode/6bgZMA0uhfaIkUUcXeP8ed?si=x6H_k9L_Qb2pVzXgMGxuZg
Apple Podcast
$NVDA (-0,41%)
$HIMS (-3,68%)
$DUOL
$BAS (-0,15%)
$TKA (-0,51%)
$TTWO (-1,7%)
Títulos em alta
Principais criadores desta semana