… which makes it all the more important to take advantage of minor setbacks.
Position expanded
Posts
82Long-term buy-and-hold portfolio focused on a core of global ETFs, supplemented by small-cap stocks, India, and selected high-quality companies. Certain portfolio holdings are locked in and are therefore intentionally excluded from ongoing optimization.
Current savings rate: €1,950/month
€1,000 FTSE All-World $VWRL (+0.54%)
,
€450 MSCI World Small Cap $WSML (+0.7%)
,
€150 FTSE India $FLXI (+1.46%),
150 € Euro Government Bonds $SEGA (+0.46%)
,
€100 Linde $LIN (-1.16%),
50 € Gold $SGBS (+2.29%) and
50 € Bitcoin $BTC.
My goal is to build a broadly diversified long-term portfolio that is continuously optimized. I welcome constructive feedback, alternative perspectives, and engaging discussions on asset allocation, individual securities, and long-term strategy.
Here's the the latest news from Linde $LIN (-1.16%)
(NASDAQ: LIN) Q2 2026 Earnings Release:
🚀 Top-line Performance & Record Revenue
Linde plc $LIN surpassed the $9.29 billion . This represents robust growth of +9.0% year-over-year (organic growth of +4.0%, driven by +2% pricing power and +2% volume). The industrial gas giant thus easily shattered Wall Street’s expectations (the consensus was ~$8.96 to $9.02 billion). The main drivers were the electronics, manufacturing, and chemicals & energy end markets.
🔮 Record-High Backlog
The fact that the engine continues to run with rock-solid predictability is evident from the full order backlog:
Project Backlog: Climbed to the staggering mark of $11.0 billion (driven by massive large-scale orders from the semiconductor/electronics industry and the decarbonization sector).
Cash Flow Machine: Operating cash flow for the quarter was $2.27 billion (+3% Y/Y). After deducting CapEx of 1.44 billion USD, $833 million in net free cash flow.
🤖 Double-digit EPS growth & record margins
The bottom line is that Linde remains the undisputed benchmark for margin discipline:
The GAAP net income rose by +9.0% to $1.93 billion.
Adjusted earnings per share (Adjusted EPS) climbed by +10.0% year-over-year to $4.50 (previous year: $4.09) and hit the upper end of expectations exactly.
The adjusted operating margin reached a rock-solid 29.5% with operating profit of $2.74 billion (+7% Y/Y).
📈 Raised Full-Year Forecast & Perks for Shareholders
Forecast Upgrade: CEO Sanjiv Lamba is raising the bar for the full year 2026. Linde now expects adjusted EPS of between $17.70 and $17.90 (an increase of +8% to +9% year-over-year). For Q3, Linde is projecting adjusted EPS of $4.55 to $4.65 (+6% to +8%).
Capital Return: In the past quarter alone, Linde returned $1.59 billion directly to shareholders through dividends and aggressive share buybacks.
⚡ 💡 Jack’s Conclusion
What a masterclass in precision! 9% revenue growth, a 10% jump in EPS, and a $11 billion order backlog prove that Linde is perfectly leveraging its pricing power and margins despite global macroeconomic uncertainties. That’s defensive, fortress-like quality with built-in immunity to interest rates and inflation!
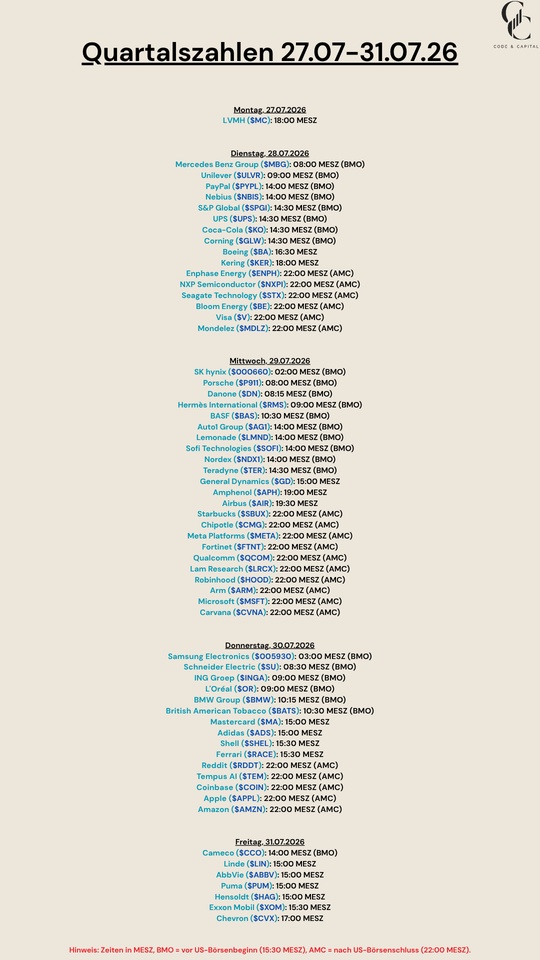
$MC (+0.41%)
$MBG (+2.38%)
$ULVR (+0.02%)
$PYPL (+0.14%)
$NBIS (-1.92%)
$SPGI (-1.41%)
$UPS (+1.48%)
$KO (-0.36%)
$GLW (+4.3%)
$BA (-1.25%)
$KER (+0.95%)
$ENPH (+0.91%)
$NXPI (+2.56%)
$STX (+1.17%)
$BE (+2.44%)
$V (-0.38%)
$MDLZ (-1.07%)
$000660
$P911 (+4.7%)
$BN (+0.92%)
$RMS (+0%)
$BAS (+0.99%)
$AG1 (-0.6%)
$LMND (+1.57%)
$SOFI (-1%)
$NDX1 (+3.02%)
$TER (+3.55%)
$GD (-1.31%)
$APH (-0.19%)
$AIR (+0.39%)
$SBUX (-1.15%)
$CMG (+0.17%)
$META (-0.48%)
$FTNT (+0.75%)
$QCOM (+2.95%)
$LRCX (-0.36%)
$HOOD (+1.74%)
$ARM (+7.05%)
$MSFT (+1.05%)
$CVNA (+2.17%)
$005930
$SU (+3.21%)
$INGA (+1.33%)
$OR (+1.12%)
$BMW (+3.12%)
$BATS (+0.12%)
$MA (-1.09%)
$ADS (-0.05%)
$SHEL (-0.22%)
$RACE (+0.67%)
$RDDT (-5.09%)
$TEM (+12.04%)
$COIN (+1.67%)
$AAPL (-0.16%)
$AMZN (+1.2%)
$CCO (+1.06%)
$LIN (-1.16%)
$ABBV (-0.63%)
$PUM (-0.58%)
$HAG (+0.88%)
$XOM (-1.42%)
$CVX (-0.74%)
Advantages – Why Linde Is a Clear Beneficiary of the AI & Semiconductor Boom
• Structural Winner — Every new chip fab (TSMC, Samsung, Intel) needs Linde gases: nitrogen, argon, hydrogen, silanes, NF₃.
• AI Data Centers — HPC clusters and AI server farms use Linde’s cooling gases → rising demand.
• Helium Shortage — Global supply constraints are driving up prices → Linde benefits from its strong market position.
• Long-Term Contracts — 10–20-year “take-or-pay” deals ensure predictable, stable cash flows.
• Low Competition — Ultra-pure process gases are extremely difficult to produce → high moat.
• Diversified regions — Americas, EMEA, APAC → no concentration risk like that faced by pure-play semiconductor companies.
• Defensive + growth — combination of infrastructure stability and AI growth → a rare mix.
---
Disadvantages / Risks — primarily from Asia
• China is building its own gas production capacity — could cost market share in the long term, but high-purity production remains challenging.
• Geopolitics in Taiwan — the industry’s dependence on TSMC → systemic risk for all suppliers.
• Helium export controls — China halts exports → global risk, but more of an opportunity for Linde.
• Japanese specialty chemicals — strong competition in chemicals, but not in gases.
• Cyclical semiconductor investments — When Capex declines, gas demand also falls (but less sharply than for equipment companies).
• Regulatory risks — Environmental regulations and energy prices can affect margins.

Indirectly, I do benefit from Crazy Musk. $ASML (+1.83%)
Another indirect investment will follow on June 29 with the spin-off of Honeywell Aerospace. (I will only place a first tranche)
Perhaps even my seemingly boring $LIN (-1.16%) might even find a catalyst again.
As one of the most important strategic partners for commercial space travel, Linde has invested around 100 million US dollars in the construction of a new air separation plant in Brownsville, Texas.
Right next to the SpaceX Starbase.
Space travel is an extremely lucrative market for gas companies like Linde - gases are absolutely vital for the launch of a rocket, but account for only a tiny fraction of the total launch costs. So SpaceX is not cutting corners here.
But, of course, the segment currently only accounts for around 1-2%.

Hi there, I would like to share my portfolio here to hear opinions and feedback. XLK is my core which I believe will continue to grow over the longterm. Alphabet is my second biggest position, for the same reason as my XLK holding. 6 other stocks make up the rest, mainly to have a defensive side plus the dividends are also nice. I’m thinking of adding $KTY (+2.73%) , but I prefer to hold no more than what I currently have unless it’s very compelling or if it’s temporary.
Let me know what you think! All opinions are welcome.
$XLKS (+1.48%)
$GOOGL (+0.42%)
$D05 (+0.42%)
$WM (-1.23%)
$LIN (-1.16%)
$ALV (+0.56%)
$BK (-0.75%) ( now BNY) $DG (+0.94%)
- Rising demand for industrial gases due to more satellite launches and larger launch vehicles
- Industrial gases are essential for rocket propulsion, cryogenics, testing and launch operations
- The expansion of commercial space travel could become a long-term growth driver
- UBS expects demand for industrial gases from the space sector to accelerate by the end of the decade
Top creators this week