
$MC (+0.32%)
$JPM (+1.42%)
$GS (-1.43%)
$C (-1.61%)
$UNH (+4.8%)
$JNJ (+2.35%)
$DPZ (-0.38%)
$WFC (+0.39%)
$ASML (-3.24%)
$BAC (-1.88%)
$BLK (+0.68%)
$MS (-2.53%)
$STT (-3.57%)
$TSM (-2.83%)
$IBKR (-3.8%)
$SU (-1.48%)
- Markets
- Stocks
- Schneider Electric
- Forum Discussion
Schneider Electric
Stock
Stock
ISIN: FR0000121972
Ticker: SU
FR0000121972
SU
Price
Discussion about SU
Posts
49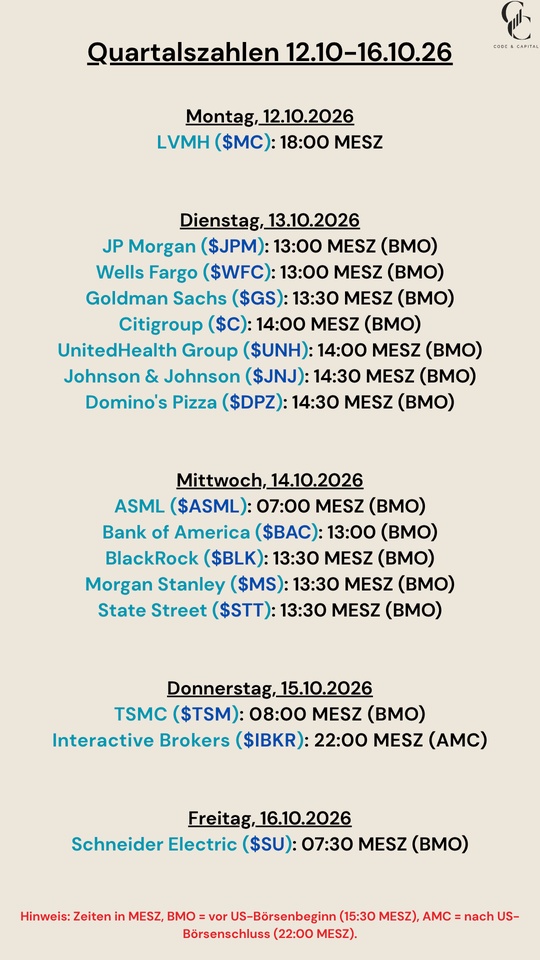

6D·
The desert doesn't regulate itself
So from now on, I'll be keeping an eye on things too. KO had been sitting around for a while and was bought today.
To balance out the portfolio, I also $SIE (-0.65%) and set up DCA on $SU (-1.48%) . Not that it’s getting too speculative.
2626
13 Comments
Get_Rich_or_Die_Tryin@Get_Rich_or_Die_Tryin
6D
•
88
•View all 9 further answers
1Wk·
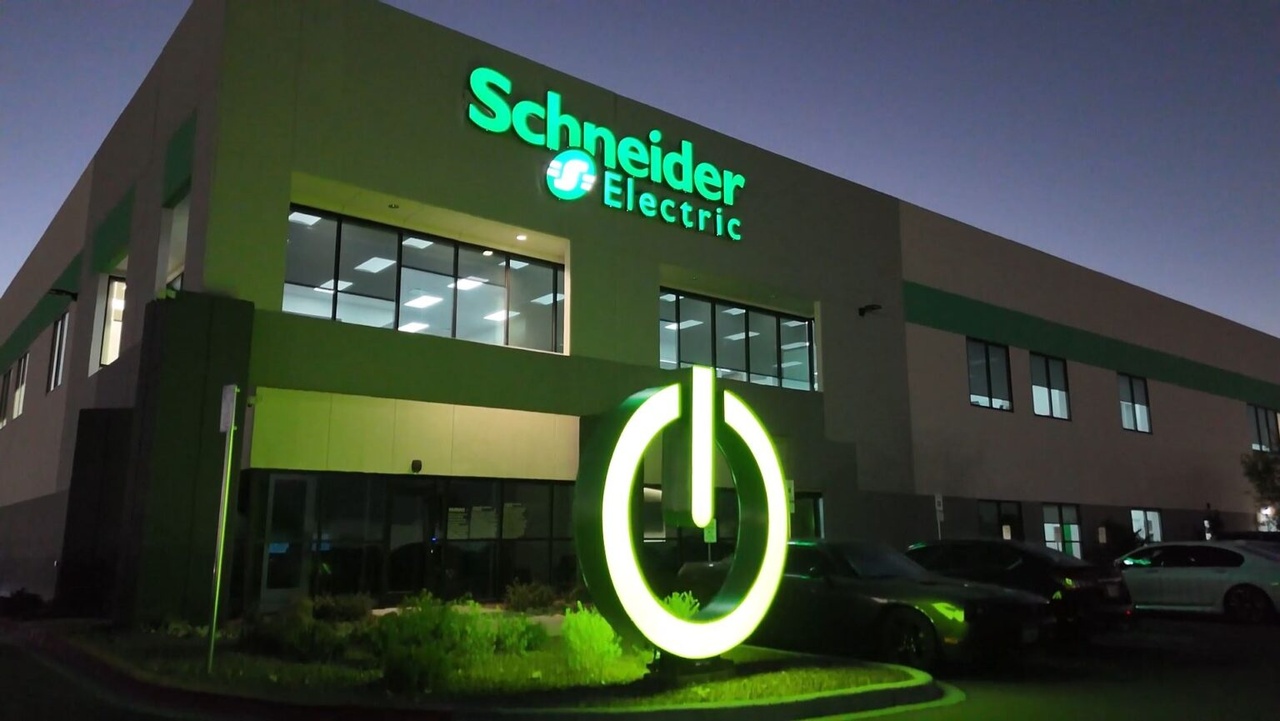
Stocks in Focus: Schneider Electric Strengthens Its Software Division with the Acquisition of PTC
The technology conglomerate Schneider Electric is continuing its acquisition spree with the purchase of the U.S. software provider PTC.
With $PTC (+0%) it aims to $SU (-1.48%) strengthen its footprint in product design, engineering, and data management. The merged company is expected to reduce annual costs by 250 million euros starting in the third year, and Schneider anticipates 800 million euros in revenue synergies.
Acquisition spree —> $SLYG (+0%) and now $PTC (+0%)
Would you $SU (-1.48%) ? Or maybe buy more later?
Best regards 🌊
2Wk·
Final portfolio, at least up to 100-120k for now
Dear Community,
I’d like to present my portfolio once again.
The core of my portfolio is the $VWRL (-0.82%) which I contribute to monthly.
I also hold a few dividend-paying stocks such as $ALV (+0.19%)
$MCD (+1.23%)
$BMY (+4.75%) and $TTE (+0.93%) these stocks are my “dividend stocks”—to be honest, I don’t expect much in the way of returns from them, but they might still surprise me. As for $BMY (+4.75%) I’m not quite sure yet whether I should hold onto this stock or focus more on growth in the healthcare sector— $SYK (-0.87%) For example, looks interesting right now—it might even be my new employer in the future 😜.
Then I also have a bit of growth with dividends, though that’s not my main focus $TSM (-2.83%)
$AVGO (-2.94%)
$SU (-1.48%) and $8001 (+0.04%) Itochu is sort of a middle ground.
Last but not least, of course, $BTC (-1.14%) to cover crypto.
Once I’ve adjusted the positions under $MCD (+1.23%) the top holdings—with a target of about 5,000€ per stock for now and BTC at 3,000€—I plan to add new holdings in the form of $VST (-6.27%)
$XYL (+0.8%) and maybe again $RKLB (-14.14%) , though other holdings are of course possible until then.
Thanks for your support, opinions, suggestions for improvement, etc.
Best regards and have a great start to the weekend,
Florian
10Positions
€76,506.36
16.98%
1616
10 Comments
Wow!
Not a single one of those individual companies outperformed your ETF??
Past performance isn't an indicator of future results when it comes to investing, but...you can see that for yourself, right?
Best,
🥪
Not a single one of those individual companies outperformed your ETF??
Past performance isn't an indicator of future results when it comes to investing, but...you can see that for yourself, right?
Best,
🥪
•
99
•
3Wk·
PART 3: How I'm Trying to Improve Human Investment Decisions Using a Structured AI Research and Control System
Part 3: The Five Categories in Practice
What This Part Is About
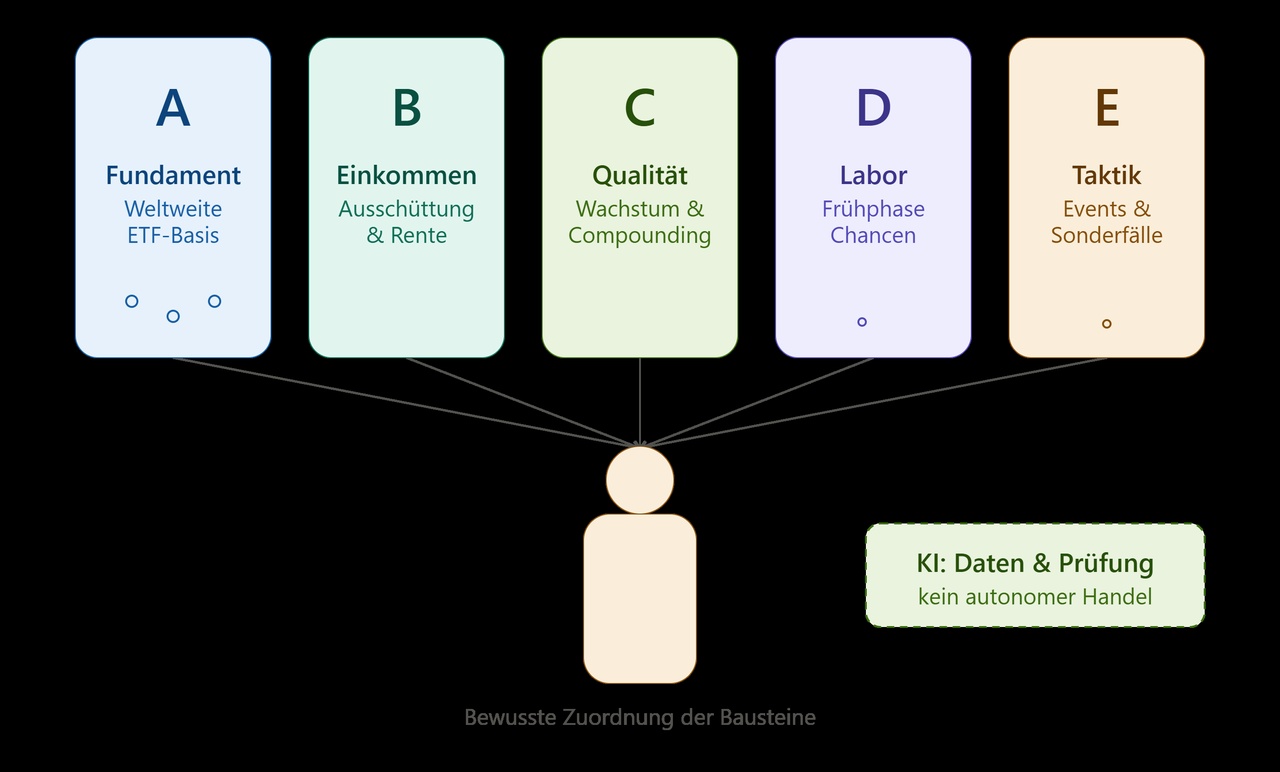
In Part 1, I described the origins of the 55555 system. Part 2 showed how an initial stock idea is transformed into a well-reasoned decision through research, cross-checking, and comparison. Now we’ll look at the practical side: What is the purpose of the five categories, A through E; which stocks are currently included in them; and why do they fit exactly where they are?
The categories are not a ranking from safe to risky. Each serves a different function.
A forms the broad foundation. B is intended to provide ongoing cash flow. C seeks quality growth. D allows for limited asymmetric opportunities. E is intended for tactical situations, events, and special cases. Therefore, what matters is not only whether a company is interesting, but what role it is meant to fulfill within the overall system.
The following chart shows the current confirmed portfolio following the addition of AeroVironment. It deliberately does not include share counts, portfolio values, absolute position sizes, purchase volumes, or absolute gains and losses. The goal is to make the system transparent without disclosing personal financial data.
Grab a cup of coffee or a snack, because the estimated reading time this time is 14 minutes :)
Category A: The Broadly Diversified Foundation
Category A consists of 5 ETFs.
This tier is not intended to identify the most exciting individual stocks, but rather to stabilize the portfolio, provide broad coverage of regions and companies, and reduce dependence on individual investment theses.
Therefore, there is no mechanical price limit for Category A.
The key factors are index quality, costs, diversification, liquidity, and whether the building blocks complement each other effectively.
Categories A and B are the long-term cash flow building blocks for future retirement income enhancement. For this reason, frequent buying and selling is expressly not intended here:
A replacement requires a clear deviation from the objective or a significantly better alternative that is convincing in terms of costs and risks.
Currently, Category A is fully allocated with five building blocks:
VanEck Developed Markets Dividend Leaders $TDIV (+0.41%)
- Dividend component for developed markets
Dividend and region (as of September 16, 2026): approximately 3.0 percent dividend yield, paid quarterly. Rough regional breakdown: Europe 56 percent, North America 16 percent, Asia-Pacific and other markets 28 percent.
Why include it in your portfolio: The ETF brings together established companies with a strong focus on dividends, thereby complementing the portfolio’s foundation with a clear emphasis on income.
Expectations: In the long term, it is expected to deliver robust distributions and broader diversification across developed markets.
Key risk: A focus on dividends may temporarily result in significant overweighting of certain sectors and value stocks; high dividends are no substitute for corporate quality.
L&G Global Quality Dividends $LDGL (-0.31%)
- global quality and dividend component
Dividend yield and region (as of September 16, 2026): Approximately 4.3 percent annualized based on the most recent monthly payment; the fund is still young and does not yet have a full 12-month history. Distributions are made monthly. Rough regional breakdown: North America 35 percent, Europe 29 percent, Asia-Pacific 34 percent, other markets 2 percent.
Why include it in your portfolio: This ETF combines international diversification with quality and distribution characteristics. It is intended to prevent the dividend portion of the portfolio from consisting solely of traditional high-dividend stocks.
Expectations: It is intended to provide exposure to global corporate quality while also delivering regular distributions.
Key risk: Factor strategies can lag behind the broader market for extended periods and, despite their global focus, may develop regional or sector-specific biases.
WisdomTree Europe SmallCap Dividend
$DFE (-0.14%)
- European small-cap stocks
Dividend and Region (as of September 16, 2026): Approximately 3.7 percent dividend yield, paid quarterly. The equity allocation is almost entirely in Europe; the largest countries are the United Kingdom, Sweden, and Norway.
Why include it in your portfolio: This component adds smaller European companies to the portfolio that have little weight in major global indices. At the same time, the dividend component is maintained.
Expectation: It is intended to tap into additional sources of returns beyond global megacaps over the long term.
Key risk: Small-cap stocks are more sensitive to economic conditions, financing costs, and lower liquidity; Europe may also experience prolonged periods of relative weakness.
Fidelity Emerging Markets Quality Income
$FYEQ (-1.13%)
- Emerging markets with a quality filter
Dividend and region (as of September 16, 2026): 2.6 percent dividend yield, paid quarterly. Rough regional breakdown: Asia 81 percent, Europe 3 percent, Middle East and Africa 8 percent, Latin America 3 percent, other markets 5 percent.
Why include it in your portfolio: The ETF incorporates emerging markets into the portfolio without relying exclusively on the largest index holdings. Quality and dividends are intended to mitigate some of the typical risks associated with emerging markets.
Expectations: It aims to combine growth from emerging markets with a more disciplined approach to quality and income.
Key risk: Currencies, politics, regulation, and geopolitical tensions can significantly impact corporate earnings and returns as measured in Europe.
iShares MSCI ACWI
$ISAC (-0.84%)
- Cornerstone of the portfolio and thus the broad global core
Dividend Policy and Regional Breakdown (as of September 16, 2026): Reinvesting dividends, so no ongoing cash distributions; returns are reinvested in the ETF. Rough regional breakdown: North America 66 percent, Europe 12 percent, Asia-Pacific 16 percent, Latin America, the Middle East, Africa, and other markets 6 percent.
Why it’s in the portfolio: It covers developed and emerging markets within a very broad global equity strategy. It is the simplest and most diversified component of the system.
Expectation: It is intended to drive long-term global wealth accumulation, regardless of which individual investments are currently the focus in the rest of the portfolio.
Key risk: Even a global index does not protect against general stock market losses and is often heavily influenced by large U.S. technology companies.
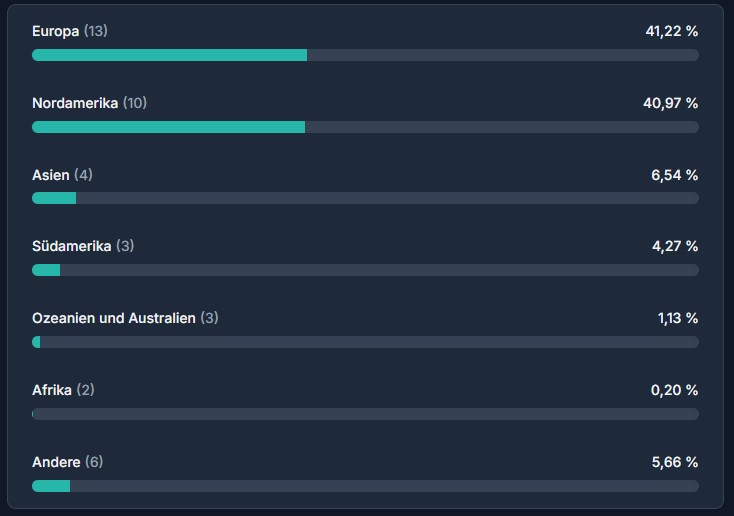
Overall portfolio regions:
Category B: Cash Cows and Regular Dividends
Category B is intended to generate reliable cash flow.
A high percentage alone is not sufficient for this. Before making a new purchase, we review dividend coverage, the balance sheet, debt, the business model, capital allocation, and concentration risks. For new Category B positions, a minimum yield of six percent generally applies. Mechanical price stops are not a priority here; we sell if the dividend or fundamental thesis breaks down or if a clearly better alternative emerges.
Like Category A, Category B is geared toward long-term holding and subsequent recurring income. Price movements alone therefore do not trigger a change in position; dividend coverage, balance sheet, business model, and sustainable cash generation remain the decisive factors.
Currently, this category has a dividend yield of approximately 9% excluding any special dividends!
Cibus Nordic Real Estate
$CIBUS (+0.27%)
- Monthly real estate cash flow
Dividend (as of September 16, 2026): approximately 7.1 percent annualized, paid monthly.
Why it’s in the portfolio: Cibus focuses heavily on food and other everyday necessities. The monthly distribution and largely indexed rents align with the cash flow objectives of this category.
Expectation: The position is intended to provide predictable distributions from a defensive real estate portfolio.
Key risk: Debt levels and refinancing needs remain high. Rising interest rates, weaker like-for-like revenue, or overly aggressive growth through acquisitions would weigh on the investment thesis.
Hercules Capital $HTGC (-0.07%)
- Specialized financier for growth companies
Dividend (as of September 16, 2026): Approximately 10.8 percent based on current regular and supplemental distributions, paid quarterly. Supplemental distributions are not guaranteed.
Why include it in your portfolio: Hercules primarily extends loans to technology- and life sciences-oriented companies. Many loans have variable interest rates, which means returns can initially benefit from higher interest rates.
Expectation: The goal is to achieve an above-average current distribution from a specialized loan portfolio.
Key risk: Loan defaults, a weak venture capital environment, falling interest rates, or a deterioration in distribution coverage could put pressure on cash flow.
Vår Energi $VAR (+2.74%)
- Energy cash flow
Dividend (as of September 16, 2026): approximately 10.0 percent annualized based on the most recent quarterly payment, paid quarterly. The amount remains dependent on the commodity cycle and free cash flow.
Why include it in your portfolio: Vår Energi adds a commodities-related cash flow component to the portfolio. Production, the project pipeline, and distributions offer a different source of returns than real estate or the lending business.
Outlook: The position is expected to benefit from efficient oil and gas production as well as a shareholder-friendly dividend policy.
Key risk: Oil and gas prices, project delays, cost overruns, and political intervention make the dividend more cyclical than that of a traditional defensive dividend stock.
Capital Southwest $CSWC (+0.14%)
- SME financing
Dividend (as of September 16, 2026): approximately 10.8 percent based on the most recently reported annual payments. The regular dividend is paid monthly; supplemental dividends may be paid quarterly.
Why include it in your portfolio: Capital Southwest is another BDC component, but with its own loan portfolio and a different corporate structure. This position complements Hercules and spreads the credit risk across a second manager.
Outlook: We expect recurring income from U.S. small and medium-sized businesses and disciplined distributions from net interest income.
Key Risk: The biggest risks are credit quality, recession, falling interest margins, dilution, and a distribution that grows faster than sustainably earned income.
Chesnara
$CSN (+0.57%)
- Insurance and run-off cash flow
Dividend (as of September 16, 2026): approximately 6.5 percent based on the most recent known 12-month payments, paid semiannually.
Why it’s in the portfolio: Chesnara manages life insurance portfolios and acquires additional portfolios. This results in a cash flow profile that differs significantly from real estate, energy, and BDCs.
Outlook: The position is expected to deliver stable long-term distributions from existing insurance portfolios and disciplined capital allocation.
Key risk: Capital requirements, market fluctuations, the quality of acquisitions, and weaker cash generation could limit dividends and growth.
Category C: Quality Growth and Long-Term Compounding
Category C is intended for companies that can grow revenue, earnings, and free cash flow over many years. Quality and growth are considered separately from the initial entry point. A company can reach the “Champions League” and still be too expensive or technically unfavorable at first.
For active C positions, a 20-percent trailing rule generally applies, whereby actual broker orders and theoretical benchmarks must remain clearly separate.
An open position does not create an obligation to buy.
Nu Holdings $NU (-4.09%)
- digital financial platform in Latin America
Why it’s in the portfolio: Nu combines strong customer growth, a scalable digital platform, and the ability to offer more financial products per customer. The stock also brings regional diversification to the C-segment.
Outlook: In the long term, Nu is expected to profitably monetize its large customer base in Brazil, Mexico, the U.S., and other markets.
Key risk: Credit quality, regulation, currencies, competition, and an overly high valuation could undermine the growth thesis.
Schneider Electric
$SU (-1.48%)
- Electrification, energy efficiency, and automation
Why it’s in the portfolio: Schneider is a high-quality company positioned to benefit from several structural growth themes: rising electricity demand, data centers, automation, grids, and more efficient energy management. The stock was added following a direct comparison with several industrial and energy infrastructure candidates.
Outlook: The position is expected to benefit in the long term from the expansion of electrical infrastructure and the integration of hardware, software, and services.
Key risk: Valuation, economic conditions, integration and execution risks, as well as a significant slowdown in data center or industrial investments, are the main concerns.
Hacksaw $HACK (+0%)
- Growth in digital gaming and platforms
Why include it in the portfolio: Hacksaw represents a scalable, content-driven business model in the regulated online gaming sector. New games and additional markets can contribute disproportionately to earnings with relatively little capital tied up.
Outlook: The goal is long-term growth through new content, distribution, and international expansion.
Key risk: Regulatory changes, dependence on platform partners, shifting gaming trends, and a high valuation could quickly lead to a repricing of growth.
Vincorion $V1NC (+3.22%)
- Specialized energy and defense systems
Why include it in the portfolio: Vincorion complements C with a smaller German specialist that has long-term demand for robust energy and system solutions for safety-critical applications.
Outlook: The position is expected to benefit from increased defense and infrastructure investments as well as improved operational execution.
Key risk: Order delays, project and margin risks, low market liquidity, and customer concentration make the stock more vulnerable than that of a large industrial conglomerate.
RELX
$REL (+0.98%)
- Data-driven information and analytics services
Why include it in your portfolio: RELX has recurring revenue, strong data assets, and deep integration into professional workflows. Its business model is less cyclical than that of traditional industrial companies.
Outlook: The position is expected to grow over the long term through pricing, data, software, and continuous product improvement.
Key risk: An overly high valuation, regulatory issues, technological disruptions, and new AI-based competitors could limit growth and margins.
For Category C, the following applies: A C-rated position may not be downgraded to D.
If the C thesis deteriorates permanently, the position is replaced or sold within the C category.
D is not a catch-all category for damaged quality or growth theses.
A D company, on the other hand, may be upgraded to C if it demonstrably reduces its uncertainties and, in a direct comparison, better aligns with the quality and growth objectives of Category C.
It must , however, like any other security, be at least 10% to 15% better in valuation than the existing holding.
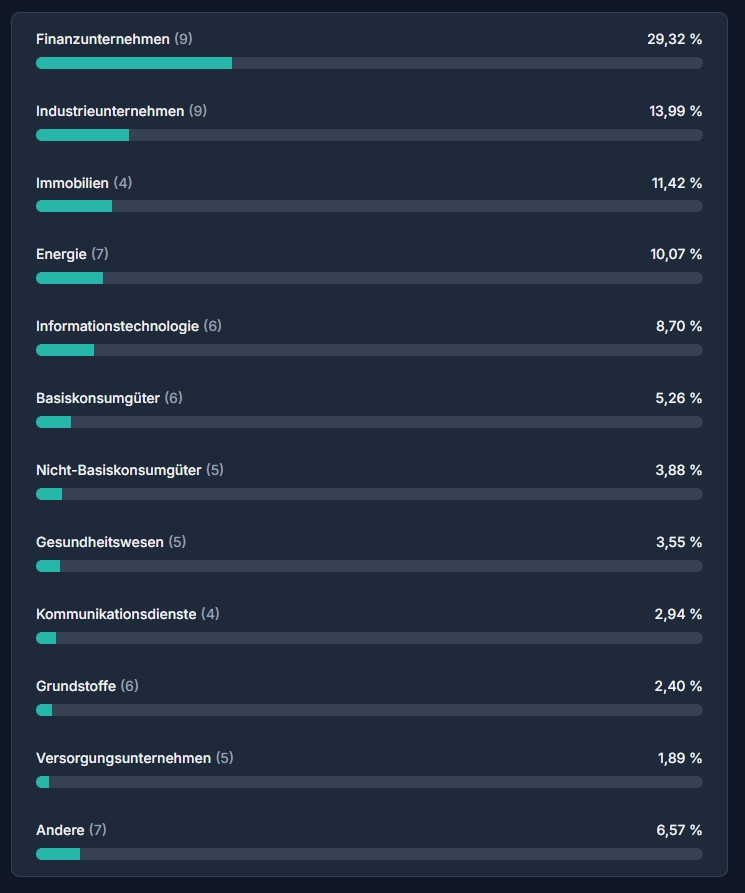
Sector Overview of the Portfolio:
Category D: Limited Asymmetric Opportunities
Category D deliberately accepts a higher degree of uncertainty. Here, we look for situations in which a successful milestone can significantly alter the company’s value, while the position size and exit strategy limit potential losses.
We evaluate the product and technology, financing, cash runway, dilution, customer or pipeline concentration, catalysts, and technical setup.
An open position does not create an obligation to buy.
NeoVolta $NEOV (-6.82%)
- small provider of energy storage systems
Why it’s in the portfolio: NeoVolta offers access to the growing market for residential and small-scale commercial energy storage. The investment case hinges on scaling, sales, and broader market acceptance.
Outlook: If growth is successful, the company could benefit from decentralized power supply, resilience, and increasing solar adoption.
Key risk: Financing, dilution, competition, the company’s small size, and its dependence on strong revenue growth make this a highly speculative position.
Kymera Therapeutics $KYMR
- Targeted Protein Degradation
Why include it in the portfolio: Kymera develops drugs designed to specifically degrade disease-relevant proteins. Successful clinical data could significantly boost the value of several programs and the entire technology platform.
Expectations: The position targets the asymmetric value of clinical progress and potential partnerships.
Key Risk: Clinical failures, side effects, binary data events, high capital requirements, and potential dilution are core risks rather than temporary side effects.
IQM Quantum Computers
$IQMX (-2.19%)
- European quantum computing technology
Why include it in the portfolio: IQM offers direct access to a strategically important future market and has operational systems, orders, and technology partnerships. At the same time, the market is still in its early stages and difficult to evaluate.
Outlook: The position is expected to benefit from growing demand for European quantum infrastructure and technological advances.
Key risk: Long development times, high financing costs, technological competition, and further capital requirements could significantly dilute the company’s value. The risk and stop-loss strategy will therefore be reviewed again.
AeroVironment
$AVAV (-5.42%)
- Drones, counter-UAS, and defense technology
Why it’s in the portfolio: AeroVironment was added following a renewed fundamental and technical review. The investment case combines a strong order backlog with growing demand for unmanned systems, defense solutions, and directed-energy applications.
Outlook: The position is expected to benefit from the transition of key programs to larger-scale production runs and from the structurally rising demand for drones and defense systems.
Key risk: Order timing, government budgets, project integration, valuation, and sharp price fluctuations could lead to significant setbacks despite strong demand.
As of today, the fifth spot in the D category is still open.
Currently, the main contenders are NeurAxis $NRXS , Praxis Precision Medicines, and Rocket Lab $RKLB (-14.14%) are being closely monitored.
NeurAxis has become significantly more attractive following technical improvements, but remains a speculative candidate due to losses, capital requirements, and potential dilution. The spot will only be awarded if quality, financing, catalysts, chart performance, and portfolio value collectively prove compelling.
Category E: Tactical Situations and Special Cases
This category is intended for swings, events, free rides, and clearly documented special cases. E is not a dumping ground for poor positions, nor is it a way to circumvent rules from categories B, C, or D. Before making a tactical purchase, the setup, trigger, risk, target, and exit strategy must be clearly defined. This category may remain empty if no compelling opportunity is available.
Desert Control $DSRT (+2.79%)
- Special Case and Grandfathering
Why it’s in the portfolio: Desert Control is developing technology to improve sandy and dry soils. The position dates back to an earlier phase of the portfolio and is not currently treated as a standard new purchase under the current D rules.
Expectation: The remaining position keeps open the possibility that pilot projects, partnerships, or commercial applications will validate the technology.
Key Risk: Early commercialization, financing, dilution, low predictability, and very high volatility make this investment unsuitable as a core position. It therefore remains explicitly a documented special case.
Teekay Tankers $TNK (-4.16%)
– Momentum Position
Why it’s in the portfolio: We have included Teekay Tankers as a tactical momentum/event position in Category E. The company is currently benefiting from high tanker rates, strong demand for oil transportation, and longer shipping routes due to geopolitical tensions. Added to this are a very solid balance sheet, high free cash flows, and a favorable valuation.
Expectations: Capitalizing on the momentum. For this reason, we do not treat Teekay as a long-term dividend or quality position, but rather as an E-position to be actively monitored with a clear exit strategy.
Key Risk: Despite these strengths, the business is highly cyclical: falling freight rates or an easing of the geopolitical situation could quickly bring earnings back to normal levels.
In addition, for the two open spots in the E portfolio, we are currently reviewing, among other things, selected “fallen angel” stocks, as well as potential rebound or event-driven setups.
Dorian LPG $LPG (-4.43%) and International Seaways $INSW (-4.57%) are examples of strong but highly cyclical momentum plays. DSV $DSV (-0.47%) would be more of a rebound or earnings event than an immediate C-buy.
Such ideas do not automatically become positions; the current chart and a predefined exit strategy are key factors.
Why the categories don’t have to be the same size
The 55555 system means five possible slots per category, not five identical positions and no rigid equal weighting.
A category may remain incomplete.
Capital is not automatically allocated to the next available slot.
First come rule violations and risk control, then vacant slots, the best candidates, and only then possible replacements or additional purchases.
Nor is a replacement made simply because a new name seems more modern or stronger in the short term. A candidate must demonstrably outperform the existing position and improve the overall portfolio by approximately ten to fifteen percent, or replace a clear rule violation. As a result, the category structure does not become an automated trading system, but rather a framework for disciplined decision-making.
The rulebook clearly states that no single sector may account for more than 30% of the portfolio!
This limit includes ETFs as well. So it can happen that a truly good stock can no longer be purchased—due to the sector cap—to avoid creating concentration risk.
What Has Changed Since the Start
The basic idea behind the five tasks has remained the same, but the practical implementation has become more precise. Category E is now active. Balance sheet, debt, and concentration are mandatory review criteria. Champions League, Reserve, Watchlist, and Top 3 Alternates distinguish quality from current buyability.
The Masterbook and Master Status ensure that new decisions, sales, and exceptions do not get lost in old chats and works.
It was particularly important to realize that a system does not improve simply by mechanically applying every rule.
A stop, a score, or an open slot is only part of the decision.
Data quality, company context, portfolio utility, and human judgment remain indispensable.
Preview of Part 4
The fourth and final part focuses on control and further development:
How Masterbook, Master Status, daily closing, lists, transaction history, dividend log, and catalyst calendar work together. I’ll also show how errors, conflicting data, and new information are handled and where the limits of an AI-powered system lie.
Part 3, too, describes exclusively my personal development and decision-making process. It is neither investment advice nor a solicitation to buy or sell securities.
I look forward to questions, suggestions, and constructive criticism. I find it particularly fascinating to see what roles other investors assign to the components of their portfolios and how they distinguish between long-term quality, ongoing cash flow, and limited speculative opportunities.
+ 2
4242
13 Comments
•
66
•
3Wk·
Portfolio thoughts 📈
I started investing in April of this year. My portfolio is based on $VWRL (-0.82%), supplemented by individual tech stocks ($AVGO (-2.94%), $SU, (-1.48%)
$NVDA) (-3.04%) and a Dutch dividend stock ($NN) (-0.56%). I would love to hear your recommendations regarding my portfolio.
7Positions
€11,375.83
3.28%
66
3 Comments
3Wk
Looks really good!
I would suggest you too not buy more stocks.
Just stay with this many Positions until like 50-80k.
I would suggest you too not buy more stocks.
Just stay with this many Positions until like 50-80k.
•
11
•


2Mon·
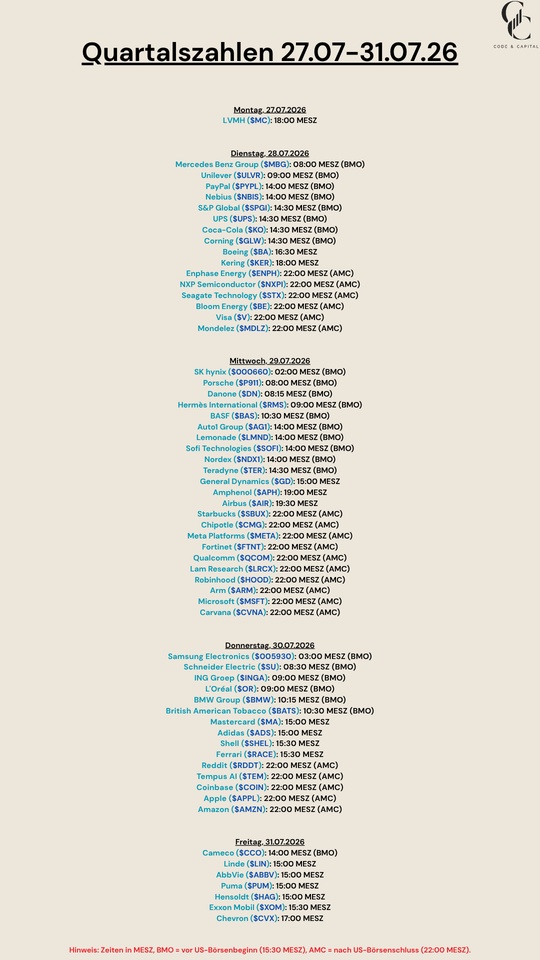
Quarterly Results: July 27–July 31, 26
$MC (+0.32%)
$MBG (-0.78%)
$ULVR (+2.08%)
$PYPL (-0.06%)
$NBIS (-9.96%)
$SPGI (-0.22%)
$UPS (+1.15%)
$KO (+2.23%)
$GLW (-5.3%)
$BA (-0.76%)
$KER (+0.83%)
$ENPH (-8.26%)
$NXPI (-2.49%)
$STX (-4.8%)
$BE (-9.63%)
$V (-0.76%)
$MDLZ (+1.82%)
$000660
$P911 (-0.55%)
$BN (+1.95%)
$RMS (+0.39%)
$BAS (+1.89%)
$AG1 (+0.92%)
$LMND (-1.15%)
$SOFI (-6.54%)
$NDX1 (-3.94%)
$TER (-5.51%)
$GD (+1.01%)
$APH (-3.07%)
$AIR (+0.93%)
$SBUX (+1.17%)
$CMG (+0.55%)
$META (-2.93%)
$FTNT (-3.59%)
$QCOM (-2.36%)
$LRCX (-4.76%)
$HOOD (-8.61%)
$ARM (-7.21%)
$MSFT (-1.43%)
$CVNA (-3.59%)
$005930
$SU (-1.48%)
$INGA (-0.03%)
$OR (+0.95%)
$BMW (+0.02%)
$BATS (+1.55%)
$MA (+0.62%)
$ADS (+0.44%)
$SHEL (+1.16%)
$RACE (-0.71%)
$RDDT (-4.33%)
$TEM (+0.03%)
$COIN (-4.69%)
$AAPL (+1.04%)
$AMZN (-1.44%)
$CCO (-5.1%)
$LIN (+0.73%)
$ABBV (+3.65%)
$PUM (+0.13%)
$HAG (+1.17%)
$XOM (+1.96%)
$CVX (+2.46%)
1414

3Mon·
Analysis of AI Infrastructure Stocks 📈
- Global data center capacity
- Market for liquid cooling in data centers
- Cashing in on the AI gold rush
- "Old industry" as the winner
- ABB $ABBN (-1.6%)
- Cisco $CSCO (-0.61%)
- Hochtief $HOT (-2.11%)
- Nokia $NOKIA (-4.17%)
- Schneider Electric $SU (-1.48%)
- Siemens $SIE (-0.65%)
- Siemens Energy $ENR (-6.2%)
22

3Mon·
Euro AI Backbone - Portfolio Rebalancing in July 2026
Since the wikifolio was created on June 18, a review will not take place until the end of July.
The first rebalancing will take place at the start of the second half of the year.
- The weighting of the VAT Group $VACN (-2.21%) will be reduced from 4.5% to 2.3%.
- The weighting of Nexans $NEX (-1.98%) will be reduced from 1.6% to 0.3%.
- New addition Alfa Laval $ALFA (-1.43%) at 1.7%.
- New addition: Atlas Copco $ATCO B (-1.46%) at 1.7%.
_________________________
Background
Reduction of VAT Group / Addition of Atlas Copco:
One of the goals of the Euro AI Backbone is to cover as much of the value chain as possible. While the VAT Group manufactures vacuum valves, this is now complemented by the global market leader in vacuum pumps.
Reduction in Nexans:
In the cable/infrastructure sector, in addition to Nexans, Prysmian $PRY (-5.59%) and NKT $NKT (-1.82%) are also represented. Prysmian, with its large operational scale, and NKT, with its deep roots in European network expansion, already cover a large portion of this sector.
Addition of Alfa Laval:
In the automation and data center cooling sector, Alfa Laval is the global market leader in thermal heat transfer, separation technology, and fluid control. Alfa Laval complements Siemens $SIE (-0.65%) , Schneider Electric’s $SU (-1.48%) and ABB $ABBN (-1.6%) , as well as RWE $RWE (-1.09%) , Iberdrola $IBE (+0.02%) and Enel $ENEL (+0.24%) .
Hier geht es zum Euro AI Backbone-wikifolio
P.S.: Almost there! The wikifolio has already been bookmarked seven times—just three more to go before the certificate can take the next step toward “Investable” in a few days.
3Mon·
🏗️ Introduction: Euro AI Backbone Wikifolio ⚡⚙️
Dear Community,
To kick off the week, I’d like to introduce you to my “Pick-and-Shovel” wikifolio “Euro AI Backbone” (in German: Backbone). More detailed information will follow; for now, this is just a rough overview.
_________________________
Background
The market’s focus is primarily on the U.S., while Europe often plays a more subordinate role. Yet recent years in particular have made it clear just how dependent Europe is on other countries such as the U.S., Russia, and China.
By the time the “Orange Man” began his second term, it had become clear:
Europe must become more independent —not only in the field of defense but also in the field of AI.
For nearly five years, Goldman Sachs has maintained an index called “EU AI Capex,” which consists of 64 European stocks. This served as the blueprint for my wikifolio.
The wikifolio was launched on June 18, 2026. For the wikifolio to receive “Investable” status, it needs, among other things, 10 bookmarks. So I’d really appreciate it if you could click “Add to Watchlist” on the wikifolio—thanks in advance.
_________________________
The “Pick-and-Shovel” Approach
The wikifolio aims to cover as much of the value chain for operating modern artificial intelligence as possible.
The focus here is primarily on five areas:
- The Shovels: Semiconductors and machinery (e.g., lithography systems, wafer deposition, chip assembly)
- The Gas: Electricity and energy generation (e.g., wind power, hydroelectric power, solar power plants)
- Highways: Networks and cables (e.g., transformers, high-voltage undersea cables, power grid infrastructure, transmission lines)
- The brain: Automation and data center cooling (e.g., liquid cooling, power distribution cabinets, data networks, control systems)
- The Physical Foundation: Construction, emergency power, and security (e.g., construction of the facilities, emergency power generators, cybersecurity)
_________________________
Investment Universe
The portfolio includes European large-, mid-, and small-cap stocks.
Focus: Technology (semiconductor equipment), utilities (electricity, grids), and industrials (automation, specialty cables, data center construction, cybersecurity).
The Core: European market leaders with global monopolies and competitive moats.
The Tech Specialists: Profitable second-tier suppliers as yield boosters.
The foundation: Energy producers, grid operators, and construction specialists for stable cash flows and risk hedging.
Regular rebalancing, which typically takes place at the beginning of each month, prevents concentration risk. While the foundation remains unchanged, the weightings of individual securities may be adjusted. The replacement of individual stocks, the addition of new stocks, or the exclusion of individual stocks can also take place at the beginning of the month.
Initially, the portfolio consists of 37 stocks. There is no cash reserve.
The current allocation of holdings is as follows:
By sector:
- Industrial: 44%
- Utilities: 29%
- Technology: 26%
- Consumer Discretionary: 1%
By country:
- Germany: 24%
- United Kingdom: 14%
- Switzerland: 13%
- Netherlands: 12%
- France: 12%
- Spain: 10%
- Italy: 9%
- Denmark: 2%
- Finland: 2%
- Austria: 2%
Investments are made exclusively in European stocks. None ETFs, no investment certificates, no funds, no leveraged products.
_________________________
Initial Holdings
At the start, the portfolio comprises the following 37 securities, sorted by their current weighting:
Infineon $IFX (-3.29%) , ASML Holding $ASML (-3.24%) , Siemens $SIE (-0.65%) , Enel $ENEL (+0.24%) , Rolls-Royce $RR. (-0.54%) , Schneider Electric $SU (-1.48%) , Iberdrola $IBE (+0.02%) , ABB $ABBN (-1.6%) , VAT Group $VACN (-2.21%) , Siemens Energy $ENR (-6.2%) , Prysmian $PRY (-5.59%) , ASM International $ASM (-1.76%) , BE Semiconductor Industries $BESI (-0.61%) , STMicroelectronics $STM (-4.97%) , RWE $RWE (-1.09%) , E.ON $EOAN (+0.35%) , Legrand $LR (-1.96%) , National Grid $NG. (+1.02%) , Nokia $NOKIA (-4.17%) , SSE $SSE (+0.84%) , EDP Renovaveis $EDPR (-0.84%) , Hochtief $HOT (-2.11%) , Red Eléctrica de España $RED (-0.54%) , Nexans $NEX (-1.98%) , United Utilities $UUGRY (-0.29%) , Enagas $ENG (-0.39%) , Centric $CENTR (-0.19%) , Spirax-Sarco Engineering $SPX (+0%) , Soitex $SOI (-4.66%) , Geberit $GEBN (-0.55%) , Aixtron $AIXA (-0.19%) , Orsted $ORSTED (-2.44%) , Verbund $VER (-0.82%) , SAFRAN $SAF (+0.1%) , Thales $THALES (-0.62%) , NKT $NKT (-1.82%) , Andritz $ANDR (+0.85%)
_________________________
Holding Period
Since infrastructure development is likely to continue for several more years, the holding period is clearly geared toward the long term. Short-term trading is avoided.
_________________________
Sources of Information
The following sources of information are primarily used to identify stocks:
Companies’ quarterly reports and financial statements.
Analyst reports and industry studies from global investment banks.
Business media and financial publications.
_________________________
I’m curious to see how the portfolio will perform over the long term. Monthly updates will keep you informed.
www.wikifolio.comEuro AI Backbone
55
2 Comments
I'm not going to invest, but I'll keep it in mind :)
•
11
•Trending Securities
Top creators this week
Real-time data from LSX · Fundamentals & EOD data from FactSet