Oppenheimer calls SpaceX the "$2T elephant in the room" for telecom as its Qualcomm partnership and $8B spectrum deal push Starlink toward nationwide 5G.
$SPCX (-0.12%)
$QCOM (-1.34%)
$TMUS (+0.52%)
$VZ (+0.55%)
#SpaceX
#Starlink
Posts
205Oppenheimer calls SpaceX the "$2T elephant in the room" for telecom as its Qualcomm partnership and $8B spectrum deal push Starlink toward nationwide 5G.
$SPCX (-0.12%)
$QCOM (-1.34%)
$TMUS (+0.52%)
$VZ (+0.55%)
#SpaceX
#Starlink
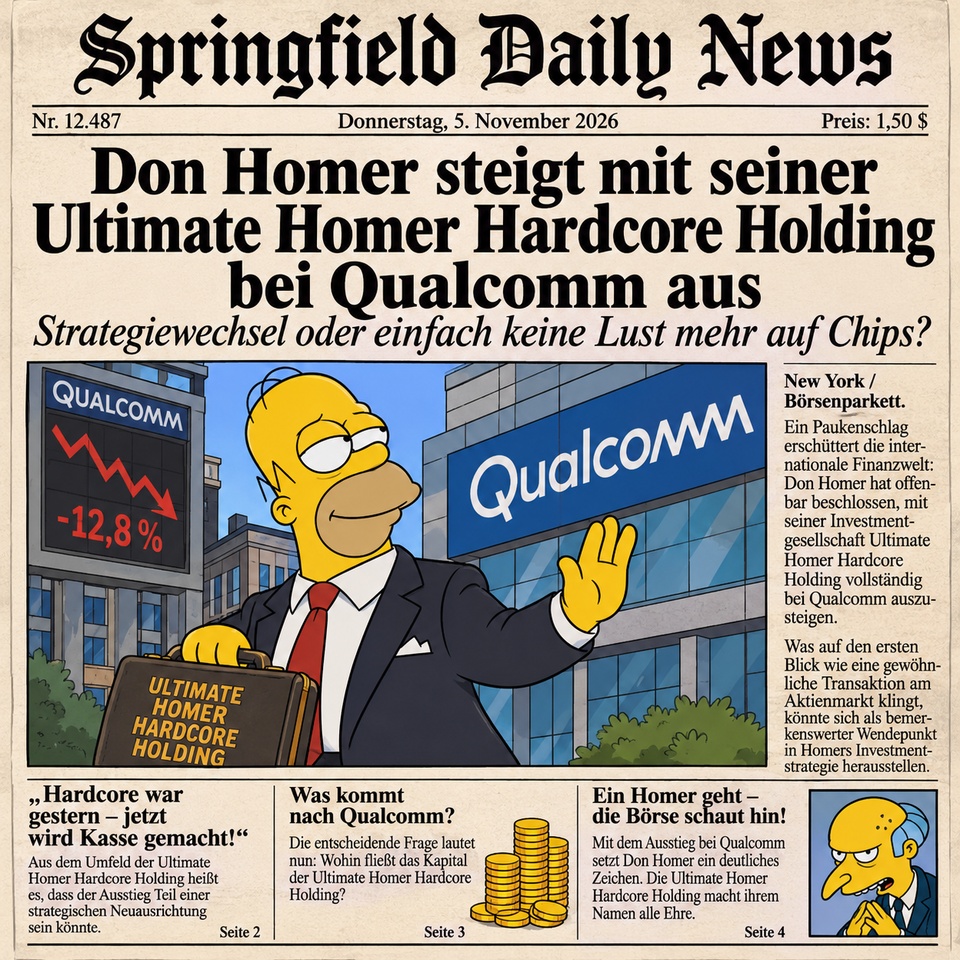
Ultimate Homer Hardcore Holding Exits Investment—A Change in Strategy or Just Tired of Chips?
A bombshell has rocked the international financial world: Don Homer has apparently decided to exit his investment firm Ultimate Homer Hardcore Holding to completely divest from Qualcomm.
What sounds at first glance like a routine stock market transaction could turn out to be a remarkable turning point in Homer’s investment strategy.
Industry experts are taken by surprise. After all, Qualcomm, one of the world’s leading semiconductor companies, is synonymous with technology, innovation, and a major role in the global smartphone and chip business. But Don Homer seems to have other plans.
“Hardcore is a thing of the past—now it’s time to cash out!”
Sources close to Ultimate Homer Hardcore Holding suggest that the exit could be part of a strategic realignment. Whether profit-taking, new investment targets, or simply a personal disagreement with the semiconductor sector is behind the move remains unclear for now.
An insider who wishes to remain anonymous commented on the development, saying:
“When Don Homer makes a decision, there’s no long discussion. Then it’s time to sell. And I mean hardcore!”
The news is likely to be a hot topic on the stock market, at the very least. While Qualcomm continues to work on its technological future, all eyes are now on the prominent investor’s next moves.
What’s next after Qualcomm?
The crucial question now is: Where will Ultimate Homer Hardcore Holding’s capital flow?
Will Don Homer invest in new technology companies? Is he planning a foray into other industries? Or is an even bigger project already in the pipeline?
One thing seems clear: boredom is apparently not part of the holding company’s business model.
Conclusion: One Homer leaves—the stock market takes notice!
By exiting Qualcomm, Don Homer is sending a clear signal. Ultimate Homer Hardcore Holding continues to live up to its name—because if you invest hardcore, you apparently have to be able to sell hardcore, too.
The stock market world is eagerly awaiting the next move.

⠀
📊 𝐑𝐞𝐬𝐮𝐥𝐭𝐬
• Non-GAAP EPS: $2.17 (Est. $2.16) ✅, -28% YoY.
• GAAP Revenue: $10.32B (Est. $10.14B) ✅, -8% YoY.
• Non-GAAP Revenue: $10.44B, -7% YoY.
• GAAP EPS: $1.17 (vs. -$2.89 YoY).
• Non-GAAP Net Income: $2.33B, -28% YoY.
• FY2026 Revenue: $43.12B (Est. $42.87B) ✅, -3% YoY.
• FY2026 Non-GAAP EPS: $10.54 (Est. $10.52) ✅, -12% YoY.
⠀
🎯 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
• Q1 FY2027 Revenue: $10.4B–$11.2B, midpoint $10.8B (Est. $10.56B) ✅.
• Q1 FY2027 Non-GAAP EPS: $2.15–$2.35, midpoint $2.25 (Est. $2.29) ❌.
• Q1 QCT Revenue: $9.0B–$9.6B, including Data Center.
• Q1 QTL Revenue: $1.3B–$1.5B.
• FY2027 Data Center Revenue Target: $5B, reiterated.
• FY2027 Non-Handset Revenue Growth: >60% YoY.
⠀
📌 𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
• Q4 revenue beat consensus by ~1.8%, while adjusted EPS was essentially in line.
• Automotive revenue surged 89% YoY to $1.99B, approaching its first $2B quarter.
• Handset revenue declined 26% YoY to $5.14B, weighing on overall QCT performance.
• IoT revenue increased 4% YoY to $1.89B.
• Combined Automotive and IoT revenue grew 36% YoY.
• QCT revenue declined 8% to $9.02B, with EBT margin contracting 500 bps to 24%.
• Renewed long-term licensing agreements with Apple, Huawei and Transsion.
• Announced a multi-generational AI data center product collaboration with Amazon.
• Expects non-handset revenue to grow more than 60% in FY2027, driven partly by the Data Center ramp.
• Rising semiconductor manufacturing and packaging costs are pressuring margins, with pricing actions expected to fully benefit QCT gross margins in H2 FY2027.
• Returned $11.67B to shareholders in FY2026 through $7.82B in buybacks and $3.85B in dividends.
⠀
💬 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐂𝐨𝐦𝐦𝐞𝐧𝐭𝐚𝐫𝐲
“Fiscal 2027 marks the start of our non-handset revenue inflection, including the ramp of our Data Center business. Non-handset revenues are projected to grow by more than 60% year-over-year, and we are reiterating our fiscal 2027 Data Center revenue target of $5B.”
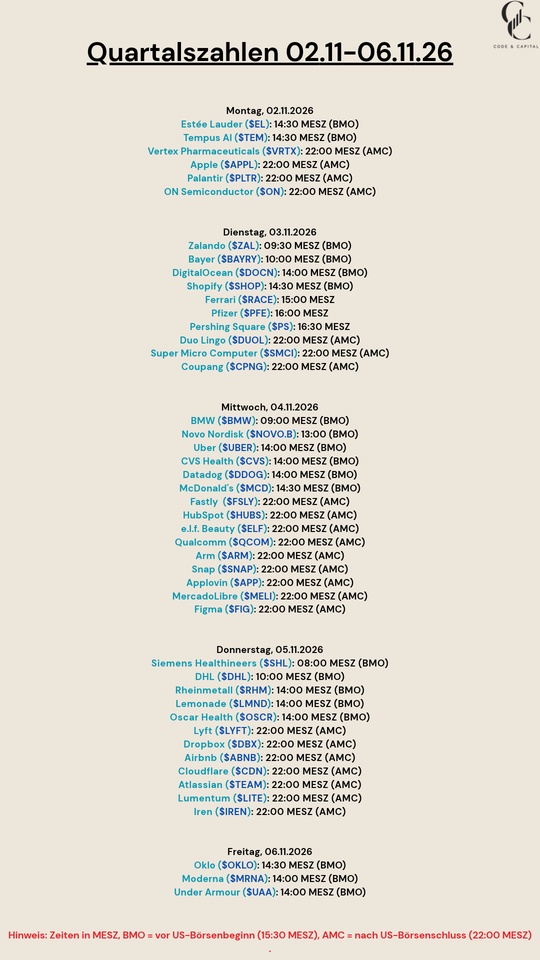
$EL (-2.53%)
$TEM (-3.78%)
$VRTX (+0.07%)
$AAPL (-0.6%)
$PLTR (-3.58%)
$ON (-3.09%)
$ZAL (-2.15%)
$BAYN (+0.41%)
$DOCN (-8.46%)
$SHOP (+1.36%)
$RACE (-1.33%)
$PFE (+0.27%)
$PS (+0.85%)
$DUOL
$SMCI (-5.88%)
$CPNG (-5.37%)
$BMW (-1.17%)
$NOVO B (+0.08%)
$UBER (+0.81%)
$CVS (-0.85%)
$DDOG (-5.59%)
$MCD (+1.26%)
$FSLY (-4.24%)
$HUBS (+6.85%)
$ELF (+1.47%)
$QCOM (-1.34%)
$ARM (-6.68%)
$SNAP (-2.95%)
$APP (+1.82%)
$MELI (-1.77%)
$FIG (+0.91%)
$SHL (-0.28%)
$DHL (+0.26%)
$RHM (-0.04%)
$LMND (-0.17%)
$OSCR (+1.13%)
$LYFT (+0%)
$DBX (+2.47%)
$ABNB (+0.3%)
$NET (-4.29%)
$TEAM (+0.89%)
$LITE (-6.29%)
$IREN (-7.34%)
$OKLO (-3.7%)
$MRNA (-2.61%)
$UAA (-0.9%)
Top Movers
Top Loosers
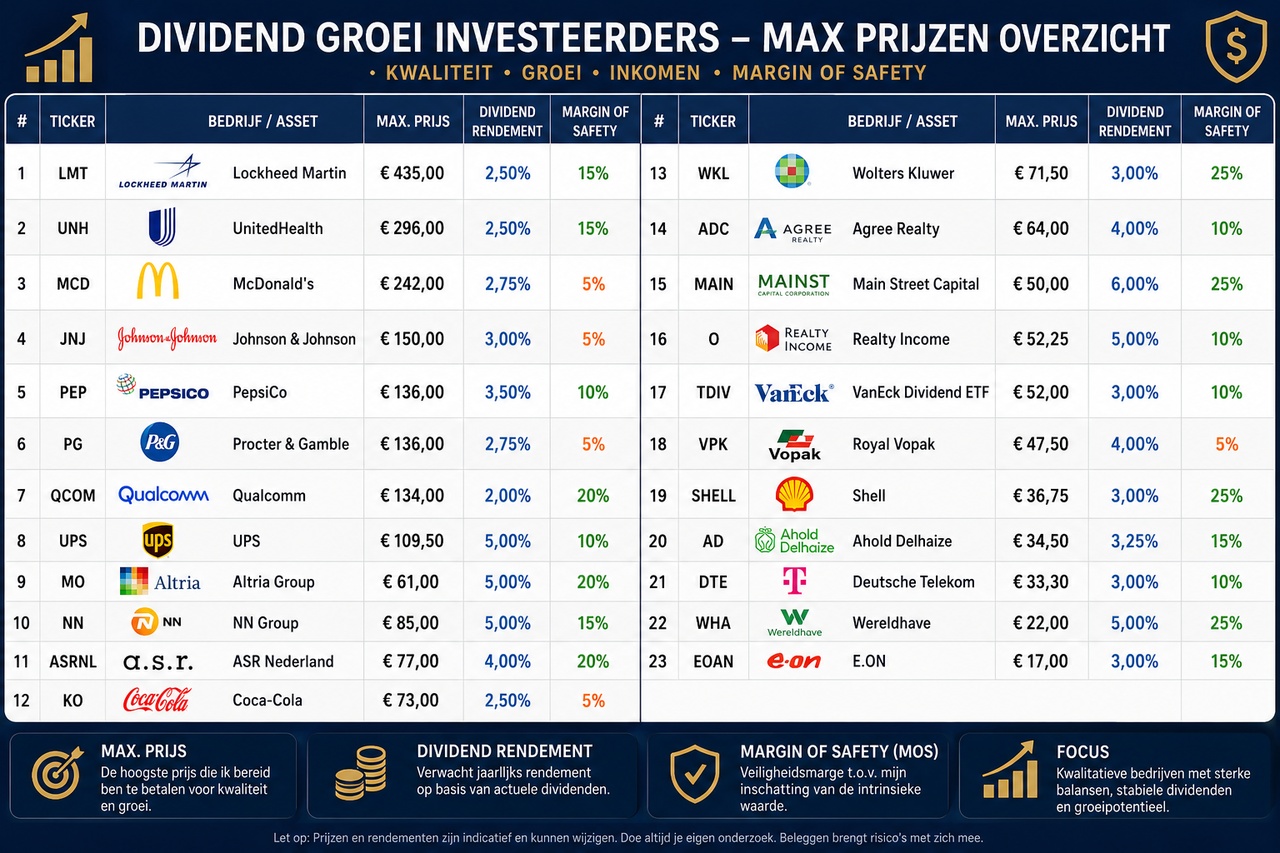
I invest with a focus on dividend growth, quality, and attractive valuations. That’s why I set a maximum purchase price for each position based on dividend yield, growth expectations, and my own Margin of Safety (MOS).
I use this overview as a guide to keep emotions out of my buying decisions and to wait patiently for opportunities.
$LMT (-1.62%)
$UNH (+1.27%)
$MCD (+1.26%)
$JNJ (-1.13%)
$PEP (+1.09%)
$PG (+2.15%)
$QCOM (-1.34%)
$UPS (-0.27%)
$NN (-0.33%)
$ASRNL (-1.27%)
$KO (+0.69%)
$WKL (+0.28%)
$MO (+0.69%)
$ADC (+0.63%)
$MAIN (-0.04%)
$O (-0.28%)
$TDIV (-0.11%)
$VPK (-0.18%)
$SHEL (-1.14%)
$AD (-0.91%)
$DTE (+1.51%)
$WHA (-1.14%)
$EOAN (-1.29%)
There was another nice spike last night at $AMBA (-8.03%) . The technology leader in the low-power and vision AI sectors is reportedly in ongoing talks with $NXPI (-1.96%) . For NXP, it would be a major coup, as this is precisely the missing piece of the puzzle in their segments—one they cannot develop quickly enough on their own. The question is also whether this might stir up trouble, and whether companies like $QCOM (-1.34%)
$NVDA (-3.22%) or $6758 (+0.75%) will jump into the bidding war. Personally, I’d prefer it if $AMBA (-8.03%) remained independent. The company isn’t under any real pressure to sell, though they’re surely aware of their negotiating position. Is anyone else invested here, or at least planning to be?

Here's the next big thing from Qualcomm $QCOM (-1.34%)
(NASDAQ: QCOM) Q3 FY26 Earnings Release, fresh off the US market close:
🚀 Top-Line Performance & Diversification
Qualcomm $QCOM surpassed the $9.90 billion in total revenue. While this represents a slight year-over-year decline, it clearly exceeded Wall Street’s expectations, which were around 9.67 billion USD. The semiconductor division QCT remains the main driver of growth with $8.50 billion, while the highly profitable patent licensing division (QTL) posted a solid 1.30 billion USD .
🔮 Automotive Record & Smartphone Low
The transformation from a pure-play smartphone chipmaker to a platform giant for automotive and edge AI is proceeding at a rapid pace:
Automotive Boom: Revenue in the automotive segment skyrocketed by +61% year-over-year to a record high of $1.59 billion . This marks the 23rd consecutive quarter of double-digit growth for Qualcomm’s Digital Chassis platform.
IoT & Edge AI: The Internet of Things segment grew slightly by +9% to $1.83 billion .
Smartphone Slump (Handsets): Revenue from smartphone chips fell by -20% year-over-year to $5.10 billion. However, CEO Cristiano Amon confirmed that this likely indicates the bottom has been reached in inventory adjustments among Chinese OEM customers.
🤖 Profitability & Outlook
Management also paints a solid picture when it comes to margins and the outlook:
Adjusted earnings per share (Adjusted EPS) stood at $2.21 , was just below the analysts’ consensus (~$2.23).
Q4 Forecast: For the fourth quarter, Qualcomm is forecasting revenue of between $9.70 billion and $10.50 billion and EPS of $2.05 to $2.25 .
Long-term goal: The goal of $40 billion in revenue in the non-smartphone segment by FY2029 remains fully intact, with growth in new markets such as data centers and AI chips expected to accelerate to over +60% in FY2027.
⚡ 💡 Jack’s Conclusion
The pivot from smartphone supplier to automotive and AI edge player is going according to plan! The handset business may have suffered from general smartphone fatigue, but +61% growth in the automotive sector impressively demonstrates that Qualcomm is keeping the cars of the future on their toes. With a valuation of just under 15x P/E, the stock remains one of the most reasonably priced value/quality plays in the semiconductor sector.

👀 Buckle up: Amazon, Meta, and Microsoft report Wed/Thu, with Apple and Qualcomm also on deck. The Magnificent Seven ETF (MAGS) fell 5%+ last week as investors fear runaway AI capex.
$AMZN (-2.38%)
$META (-1.92%)
$MSFT (-0.66%)
$AAPL (-0.6%)
$QCOM (-1.34%)
$MAGS
Top creators this week