
Tough months for HERMES. Solid company though. I’ll keep on buying as it goes down.
- Markets
- Stocks
- Hermes International SCA
- Forum Discussion
Hermes International SCA
Stock
Stock
ISIN: FR0000052292
Ticker: RMS
FR0000052292
RMS
Price
Discussion about RMS
Posts
94


2Wk·
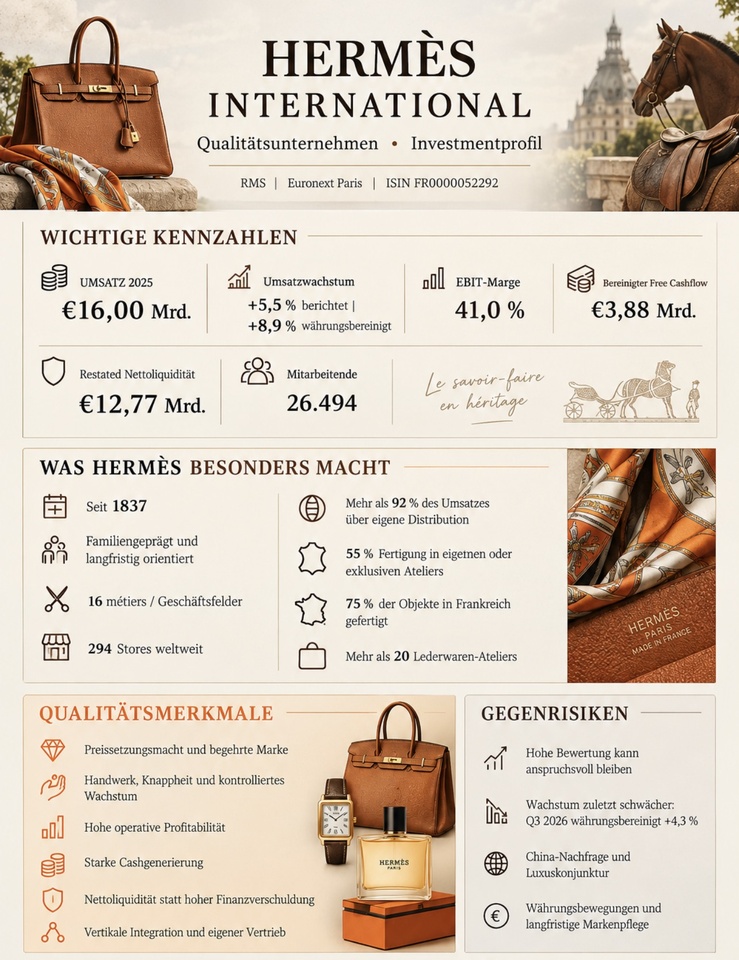
My all-time favorite in terms of quality.
What fascinates me so much about $RMS (+0.72%) is that they’ve achieved something that hardly any other company in the world can pull off: (except maybe $RACE (-0.08%) or $BC)
They don’t just sell luxury—they stand for something that can’t simply be copied. The brand, the craftsmanship, the exclusivity, and that incredible pricing power make Hermès, in my view, one of the best companies out there. That’s exactly why I’m taking a long-term view here. 🧡
Above all, the high U.S. exposure in my portfolio makes European stocks all the more attractive.
Sure, the price could change again in the short term, but anyone who doesn’t buy here countercyclically will regret it when the stock starts to rise again 🙂
66
7 Comments
•
33
•
2Wk·
Watchlist
Hey everyone, which stocks on your watchlist are at the top of your list right now? For me, they would be:
$AAK (+0.85%) (Additional purchase)

3Wk·
Luxury in the Suburbs: How Hermès Is Reinventing Its U.S. Strategy in Response to Changing Markets
The latest financial results paint a clear picture: While Hermès’s revenue on the American continent rose by 15 percent in the first half of the year, it increased by only 2 percent in Asia (excluding Japan). As demand in traditional strongholds such as China has noticeably slowed and the U.S. has emerged as a bright spot—accounting for nearly half of all new millionaires in 2025—the company is pushing for greater geographic diversification of its U.S. market.
Instead of expanding solely in major cities like New York or Beverly Hills, Hermès is increasingly opening boutiques in upscale American suburbs and smaller cities such as Wilmette, Short Hills, Nashville, and Austin. The goal is to be as close to customers as possible. The stores are deliberately located near where the clientele lives—for example, in open-air shopping centers, in former industrial buildings, or right next to upscale dining options—to facilitate spontaneous visits while running everyday errands or walking the dog.
When it comes to design, the brand places great emphasis on individuality and a sense of home: Each store is designed by the same Parisian architecture firm, yet differs completely from all previous stores and visually adapts to the local architecture—for example, with Spanish Revival elements, dragonfly motifs, or red brick. Decorated with photographs and works of art from the family collection—often featuring horse motifs—the boutiques are intended to offer a cozy atmosphere that regularly invites regular customers to stop by for a coffee or a glass of champagne. At the same time, all leather handbags—such as the coveted Birkin Bag—are strictly manufactured in France by family decree to preserve their customary exclusivity.
I’m not quite sure yet what to make of this—whether the concept fits with Hermès. What do you think?

3Wk·
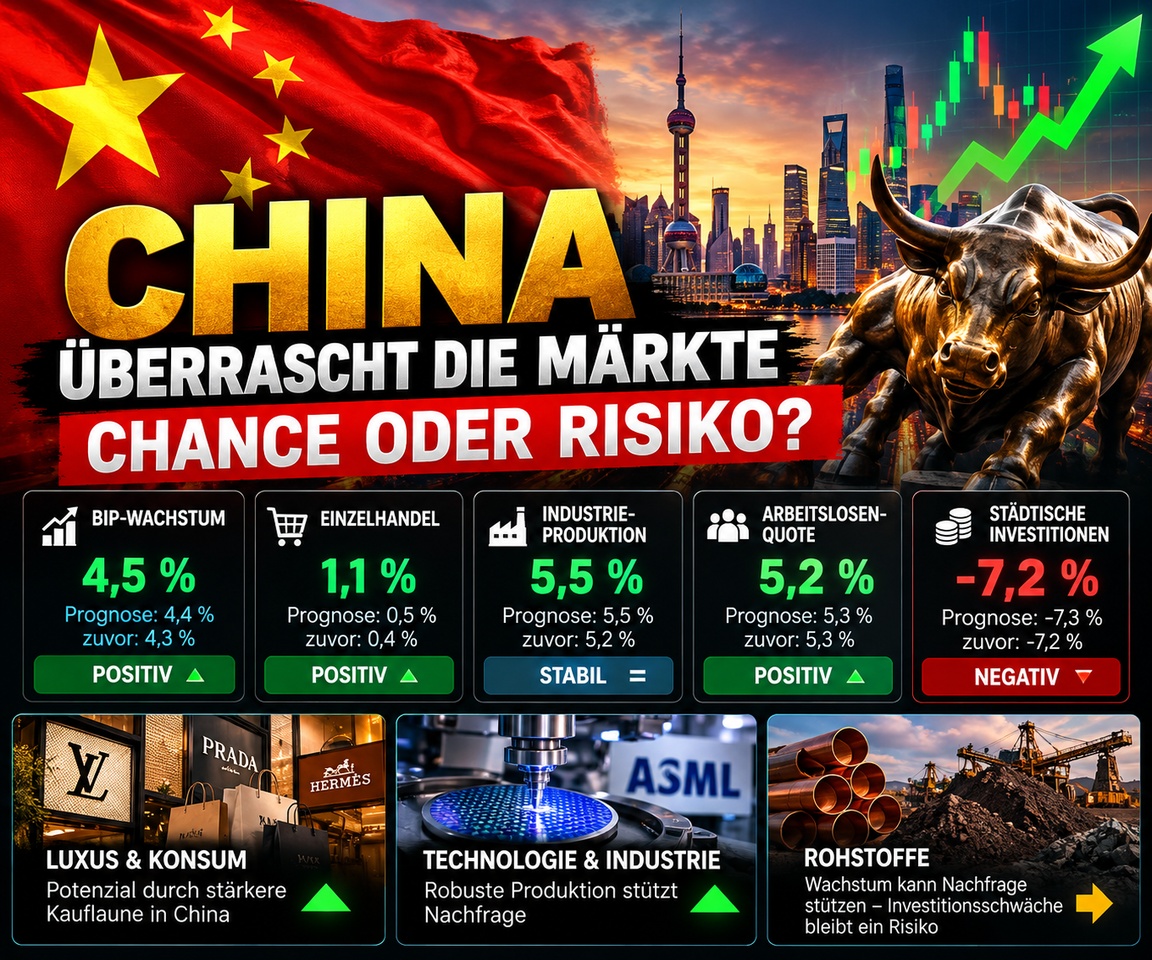
China Surprises the Markets: An Opportunity for Investors or a Deceptive Show of Strength?
China has released new economic data—and some of the figures are better than expected. But anyone who focuses solely on the positive numbers right now may be missing the bigger picture.
An overview of the key figures:
● GDP growth: 4.5% instead of the expected 4.4%
● Retail sales: +1.1% instead of the forecasted +0.5%
● Industrial production: +5.5%, in line with expectations
● Unemployment rate: 5.2% instead of the expected 5.3%
● Urban investment since the start of the year: −7.2%
What does this mean for the stock market?
The positive surprises in economic growth and consumer spending could give Chinese stocks a boost. European companies with significant business in China could also benefit.
I find three sectors particularly interesting:
1. Luxury and consumer goods
Companies such as $MC (-1.01%) , $RMS (+0.72%) and $1913 (-1.25%) could benefit from a recovery in Chinese consumer sentiment. However, the key factor will be whether the improved economic data actually translates into rising sales.
2. Technology and Industry
A robust industrial sector is generally positive for companies along the technology and supply chains. For stocks like $ASML (+5.61%) , however, one should also take export restrictions, investment budgets, and global demand into account.
3. Commodities
Stronger growth can support demand for iron ore, copper, and other industrial metals. The decline in investment, however, remains a warning sign regarding the sustainability of this trend.
The major problem remains weak investment.
While some economic data has been a positive surprise, urban investment has continued to decline since the beginning of the year. This shows that China’s economy is by no means over all its structural problems.
For me, therefore, it is not decisive whether a single figure turns out to be positive. What matters is whether consumption is recovering sustainably and whether companies can actually increase their profits.
My conclusion as an investor:
The figures are a positive sign, but they’re not yet a free pass to a Chinese boom. I wouldn’t buy blindly right now; instead, I’d watch to see which companies are actually improving their financial results and forecasts.
In the end, what counts on the stock market isn’t just economic growth, but what actually trickles down to shareholders.
What do you think?
Do you currently see China as an interesting opportunity—for example, through Chinese stocks, luxury goods companies, or commodity stocks? Or do the risks posed by weak investment outweigh the opportunities?
#China
#Aktien
#Börse
#Investieren
#Dividenden
#LVMH
#ASML
$RIO (+3.92%)
88

3Wk·
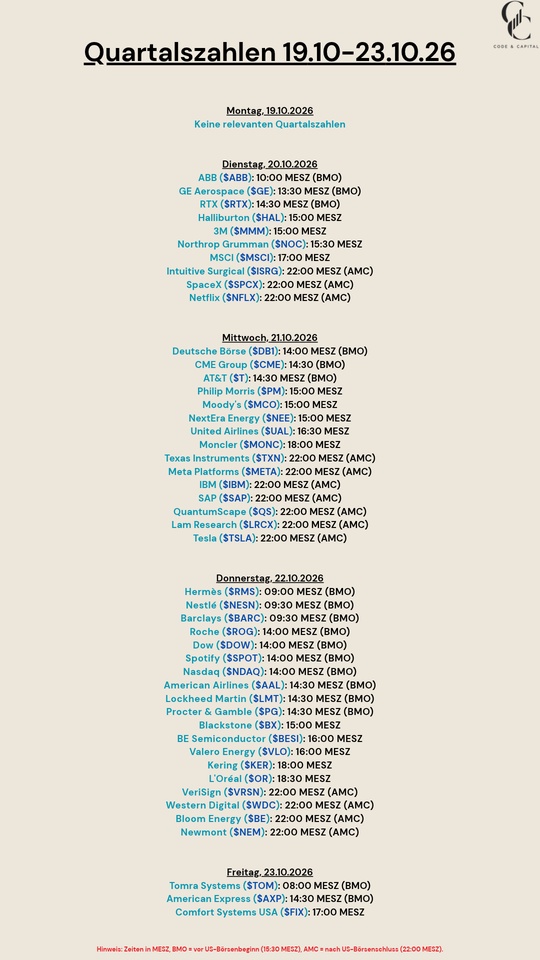
Quarterly Results: Oct. 19–23, 2026
$ABBN (+2.5%)
$GE
$RTX (+2.86%)
$HAL (-0.42%)
$MMM (+0.36%)
$NOC (+1.32%)
$MSCI (+0.1%)
$ISRG (+1.09%)
$SPCX (+4.58%)
$NFLX (-0.11%)
$DB1 (-1.23%)
$CME (-1.36%)
$T (-0.25%)
$PM (-2.81%)
$MCO (-1.1%)
$NEE (-1.03%)
$UAL (+6.45%)
$MONC (-0.22%)
$TXN (+5.3%)
$META (+4.68%)
$IBM (-0.36%)
$SAP (+1.19%)
$QS (+6.53%)
$LRCX (+9.7%)
$TSLA (+4.91%)
$RMS (+0.72%)
$NESN (+0.61%)
$BARC (+2.78%)
$ROP (+3.12%)
$DOW (-2.9%)
$SPOT (-0.92%)
$NDAQ (+0.42%)
$AAL (+6.59%)
$LMT (+2.94%)
$PG (+0.89%)
$BX (+2.99%)
$BESI (+4.43%)
$VLO (+1.57%)
$KER (+1.53%)
$OR (+0.17%)
$VRSN (-1.59%)
$WDC (+9.35%)
$BE (+12%)
$NEM (+2.79%)
$TOM (+3.36%)
$AXP (-0.14%)
$FIX (+9.5%)
99
1Mon·
UBS Downgrades Hermès: The Exclusivity Debate and a Reality Check in the Luxury Segment
The major Swiss bank UBS has fundamentally changed its stance on the French luxury goods group Hermès and downgraded the stock from Neutral to Sell. The price target was slashed from 1,695 euros to 1,168 euros. This significant revaluation marks a remarkable turning point for a stock that has long been considered virtually untouchable in the luxury segment.
At the heart of the analysis are concerns about the brand’s long-term exclusivity. According to analysts, Hermès has been steadily expanding production in recent years. Estimates suggest that approximately 65 percent of revenue in the leather goods segment now comes from non-quota or freely available bags. What was once protected by strict, artificial scarcity is gradually shifting toward a more conventional consumer goods model. As a result of this development, the brand is losing some of its absolute exclusivity.
According to UBS, this also has immediate consequences for the company’s business profile. The company is becoming increasingly cyclical and more vulnerable to economic fluctuations in the global luxury market, as the hoped-for rapid market recovery has proven to be premature. Accordingly, financial forecasts have been significantly revised downward. For 2027, the bank lowered its earnings per share estimates by 10 percent to 43.98 euros, which is noticeably below the broad market consensus. For 2028, an even wider gap from analysts’ expectations is forecast.
A key driver of the weaker earnings outlook is the expected pressure on margins. The operating margin is expected to decline to around 38.3 percent in 2027, which is about 100 basis points below the previous year’s level. This is due to lower economies of scale resulting from slower growth, higher spending on communications and marketing, and negative effects from currency hedging. Added to this is a permanently higher effective tax rate, which the bank now factors into its models. For organic revenue growth, UBS now expects only more moderate rates in the mid- to high-single-digit range in the coming years.
Despite this slowdown in growth, the stock continues to trade at a high valuation level. Based on earnings estimates for 2027 and 2028, the price-to-earnings ratio is estimated to be between 27 and 29 times earnings. From the analysts’ perspective, this valuation implies unrealistically high long-term expectations that are likely to be tempered by operational realities. The new price target of 1,168 euros is based on a combination of an adjusted discounted cash flow model and a peer-group valuation and signals further downside potential at the current price level. The bank cites unexpectedly strong product innovations as a potential risk to this pessimistic assessment, as they could still unexpectedly accelerate global growth.
(Note: So much for a lack of exclusivity and waning demand—with the best will in the world, I simply cannot agree with this UBS analysis here in Zurich! After dutifully boosting Asian sales in Hong Kong just last month, I wanted to make my local contribution at the Hermès store in Zurich on Saturday at 5 p.m. The result: A sign on the door read “Closed due to overcrowding”—you simply couldn’t get in anymore! So I had no choice but to leave my hard-earned money with the competition. It was (in parentheses) absolutely packed there, too, but at least they were charming enough to let me in. In any case, there was absolutely no sign of a cooling consumer mood in Zurich at five o’clock sharp in the afternoon!)
Hong Kong:
Zurich:
66
2 Comments
I mean, downgrading the stock to SELL is just plain stupid! Louis Vuitton, Hermès… those are cyclical stocks—of course they’re struggling right now! But personally, I wouldn’t sell Hermès 🔥
•
33
•1Mon·
Reorder/Price Reduction
At some point, the floor has to show up...
1313
10 Comments
1Mon
I think that as soon as the first household humanoids become available to the wealthy—and it becomes clear that people will want to dress them in special clothes to make them stand out—Hermès will take off again.
•
55
•
1Mon·
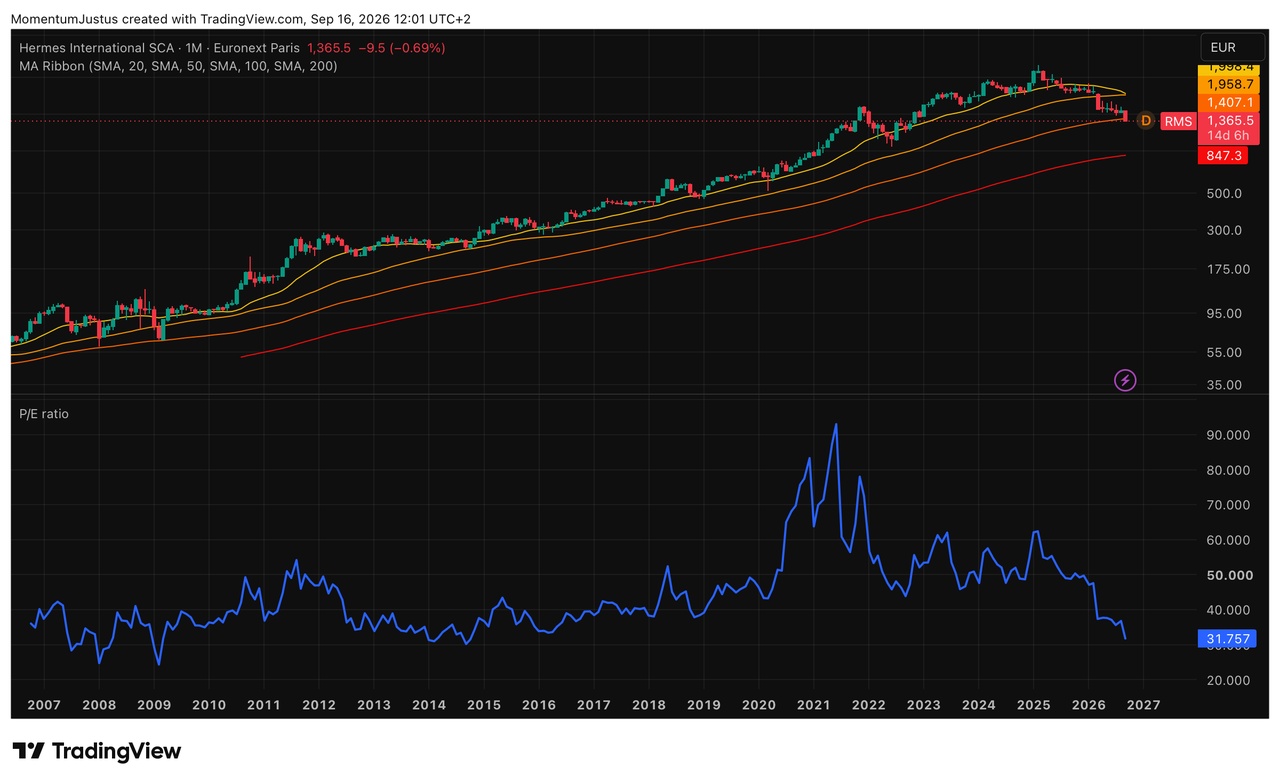
WHEN IN DOUBT… ZOOM OUT. 🔍📈
If you look at the chart we’re entering some pretty interesting technical levels.
Hermes is now even trading below its 1M SMA 100…
Momentum is a bit low atm to be honest… 😂
But look at the historical P/E (blue line).
We’re now back around 2014 valuation lows.
And what was the big fear around 2014? I asked my friend ChatGPT…
CHINA! 🇨🇳
China was slowing down. Luxury spending was weakening. And fears arose around Chinese demand.
Sounds familiar? YES!
Because today we have basically the same discussion again.
This time it’s different?
No. Because as long as $RMS is able to artificially keep demand higher than supply.
They’ve nothing to worry about…
Mr. Market at it again! 🧔🏻♂️🏪📉

Trending Securities
Top creators this week
Real-time data from LSX · Fundamentals & EOD data from FactSet