In my opinion a good opportunity to open position on $NBIS (-5.16%) , 3 units to close this position around 3% of my total portfolio
- Markets
- Stocks
- Nebius Group NV
- Forum Discussion

Nebius Group NV
Stock
Stock
ISIN: NL0009805522
Ticker: NBIS
NL0009805522
NBIS
Price
Discussion about NBIS
Posts
214

2H·
Red day for AI stocks, buying opportunity for me. 📉
I just added more $NBIS (-5.16%) to my portfolio, taking advantage of the pressure on AI infrastructure stocks amid rising interest rates.
55
7 Comments
emppsb@emppsb
2H
•
22
•View all 4 further answers


23H·
Gartner's "Neocloudocalypse": When the AI Boom Turns into a Capital-Destroyer
$IREN (-6.39%)
$CRWV (-1.09%)
$NBIS (-5.16%)
$APLD (-5.81%) Lambda
Gartner predicts that 80% of neoclouds will have to cease independent operations by 2030
Gartner warns of a potential massive consolidation in the AI infrastructure market. The problem: Investments in data centers, GPUs, and energy infrastructure could significantly exceed future revenue potential.
Key figures:
- Approximately 7 trillion U.S. dollars in AI infrastructure investments by 2030.
- Only up to 3.6 trillion U.S. dollars in attributable AI revenue, compared to an estimated revenue requirement of 8.5 trillion U.S. dollars.
- More than 80% of Neocloud providers could lose their independence by 2030.
- Over $4 trillion in infrastructure assets could be subject to write-downs by 2032.
Known scenarios:
🔴 Bear Case: AI monetization falls short of expectations. Overcapacity, price pressure, and high financing costs lead to write-downs, bankruptcies, and falling valuations.
🟡 Base Case: AI demand continues to grow, but not every provider benefits. The market consolidates; financially strong hyperscalers gain market share, while smaller neoclouds are acquired or exit the market.
🟢 Bull Case: AI monetization accelerates, with utilization rates and prices remaining high. Investments pay off, and efficient infrastructure operators achieve attractive returns.
What do you think?
Is this already priced in today, alongside higher yields on government bonds and potential interest rate hikes?
Or am I overlooking something else that’s driving today’s price movements?
@Multibagger
@Klein-Anleger
@Tenbagger-Capital
@Get_Rich_or_Die_Tryin
@Raketentoni
@Pazzzi
1212
13 Comments
Hey there, sorry I didn’t have time to talk to the agent about it until now—here’s our response for you :)
The Gartner figures are essentially correct. However, I’d be a bit more cautious in interpreting them—“Neocloudocalypse” is the sensationalized headline, not Gartner’s actual message.
Gartner actually forecasts:
- just under $1 trillion in AI infrastructure investments by 2026,
- an additional $6 trillion from 2027 to 2030,
- a cumulative revenue requirement of 8.5 trillion dollars to cover investments, financing costs, and an assumed return on investment of 12%,
- but only a maximum of 3.6 trillion dollars in AI revenue that can be attributed to data centers.
That is a massive gap. However, two points should be clarified.
**First: The 80 % does not mean 80 % of companies will go bankrupt.**
Gartner states that more than 80% of providers could cease **independent operations** by 2030. This could include not only bankruptcies but also acquisitions, mergers, partnerships, or strategic shifts.
Furthermore, the figure refers to the number of providers, not 80% of computing power or invested capital. If numerous small neoclouds disappear while a few large providers continue to grow, both statements can be true at the same time:
- massive consolidation,
- a neocloud market that continues to grow strongly.
In June, Gartner ultimately predicted that neoclouds could account for around 20% of a $267 billion AI cloud market by 2030. Gartner therefore does not expect the end of the business model, but rather significantly fewer independent winners.
**Second: The four trillion is not an announced write-down amount.**
Gartner refers to more than $3.5 trillion in investments that could be exposed to a write-down risk by the end of 2030, or more than $4 trillion in at-risk assets by 2032.
“Exposed to write-down risk” does not mean that these four trillion will be written off in full. The assets could yield lower returns, be partially written down, repurposed, or sold to other operators. Equating a write-down risk directly with a certain capital loss of the same amount would be a bit like immediately tearing down every property whose market value has fallen.
**Why are stocks falling so sharply today of all days?**
Yes, Gartner’s report aligns perfectly with today’s sell-off and likely exacerbated concerns. The more immediate trigger, however, was a combination of several factors:
1. U.S. inflation rose to 3.7% in September, exceeding the expected 3.6%.
2. As a result, the market took the prospect of another Fed rate hike more seriously.
3. The two-year U.S. yield jumped by about 7 basis points, and the ten-year yield by about 4 basis points.
4. At the same time, CoreWeave’s bonds came under massive pressure.
5. The yield on a CoreWeave bond rose at times to approximately 15%.
This last point is particularly important: The credit market has suddenly made clear what additional financing could cost for a capital-hungry “neocloud” operator. Reuters explicitly attributes today’s decline in the group’s stock to higher interest rate expectations and growing doubts about the financing of AI expansion.
So this wasn’t just a Gartner report. It was a rather unpleasant mix of soaring inflation, rising yields, weak corporate bonds, and a report published on the very same day that explains exactly why this combination can be dangerous.
**Nevertheless, the companies mentioned should not be lumped together.**
- **CoreWeave** is the most immediate cause for concern: very high debt and lease obligations, massive expansion plans, and, as a result, extreme dependence on the credit market. In the second quarter alone, the company raised more than $10 billion through unsecured debt and convertible bonds.
- **Nebius** also operates a capital-intensive AI cloud model, but has diverse financing channels and now also leverages partnerships in which infrastructure partners provide a portion of the capital or data centers.
- **IREN** is vertically integrated and owns power access, data centers, and computing infrastructure. A significant portion of the GPU investments for large contracts is covered by customer prepayments and project-based financing. This reduces risk but does not eliminate debt, dilution, customer concentration, or the risk of rapid GPU obsolescence. IREN most recently reported approximately $7.4 billion in long-term debt.
- **Applied Digital** is more of a data center developer and lessor than a traditional GPU cloud provider. Its risks lie primarily in construction costs, financing, completion, and the creditworthiness of major tenants. Long-term take-or-pay contracts provide some protection, but they are of little help if a major tenant runs into financing problems of its own.
Incidentally, the LAMB link leads to the cryptocurrency Lambda. This is not the stock of the American AI cloud provider of the same name. Apparently, the wrong Lambda has found its way into the apocalypse.
**My Conclusion**
The Gartner warning should be taken seriously. It very aptly describes the central risk of this boom:
> Demand for AI may grow strongly, yet numerous infrastructure operators may still make poor investments.
What matters is not just whether more computing power is needed, but:
- at what prices it is sold,
- how high the actual utilization rate is,
- how quickly the GPUs become technically obsolete,
- how expensive debt financing becomes,
- how robust the customer contracts are,
- who bears the residual value risk,
- and how much dilution will be necessary to secure financing.
Today’s sell-off is pricing in this risk more heavily. However, it does not mean that Gartner has already been “proven” wrong. The market is simply raising the risk premium for all business models that must invest billions before the corresponding cash flow actually hits the bank account.
Or to put it more succinctly: **AI demand doesn’t have to collapse for capital to be destroyed at the “neoclouds.” It’s enough for demand to grow more slowly than debt, capacity, and depreciation.**
•
99
•
1Wk·
Merlin Properties: The Commercial REIT That Isn't Really One?
$MPTYY is a Spanish REIT, the largest on the Ibex. However, it is one whose traditional business (offices, logistics, shopping centers) is under pressure.
Currently, data centers account for about 10% of rental income; this is expected to rise to 65% by 2032. The situation is quite different at GAV, where data centers already account for 80% of the approximately €13.5 billion.
To date, 160 MW have been leased, including to ($CRWV (-1.09%) , $META (-1.26%) and $NBIS (-5.16%) ).
This is expected to rise to 200 MW by the end of 2026. The pipeline stands at >200 MW. Everything here also depends somewhat on the new regulations in Spain. If they are implemented as announced, things might get tough.
Does anyone know this REIT or is already invested in it? How do you view it compared to “real” data center REITs like $EQIX (-0.56%) or $DLR (-0.47%) ?
Edit: Here are some figures from the last quarter:
- Revenue: Total income reached EUR 307 million, with gross rental income at EUR 292 million, representing a 10% like-for-like increase.
- FFO (Funds From Operations): FFO was EUR180 million, an 8% increase year-over-year.
- FFO Guidance: Full-year 2026 FFO guidance was raised from EUR327 million to EUR340 million, equating to approximately EUR0.55 per share.
- Loan-to-Value (LTV): LTV decreased to 24.5%.
- GAV (Gross Asset Value): GAV increased by 3.7% on a like-for-like basis.
- NTA (Net Tangible Assets): NTA stood at EUR15.99 per share.
- Occupancy: Overall occupancy was 94.7%, with shopping centers at 96.9%, logistics at 95%, and offices at 84.4% in Barcelona.
- Like-for-Like Rental Growth: Overall like-for-like rental growth was 3.3%, with shopping centers leading at 6.4%.
- Tenant Sales (Shopping Centers): Tenant sales increased by 8.4%, and foot traffic grew by nearly 2%.
- Occupancy Cost (Shopping Centers): Occupancy costs remained affordable at 10.8%.
- Data Center Leasing: 160 megawatts of IT capacity was brought online, up from 112 megawatts in the previous quarter.
- Data Center Phase 1 GRI: Estimated gross rental income for Phase 1 is EUR68 million for 2026.
- Data Center Promote: Recognized a promote accrual of EUR101 million for Phase 1, with a payment of nearly EUR20 million in March 2026.
- Capital Recycling: Sold EUR75 million in assets as of July, with an additional EUR90 million in divestments agreed upon.
- Liquidity: Held EUR2.6 billion in liquidity.
An article on regulation: https://www.idealista.pt/en/news/financial-advice-in-portugal/2026/10/06/77877-data-centre-development-will-move-to-portugal
66
2 Comments
$MRL
I think there’s more to see under the original Spanish ISIN than under the ADR. Maybe you could add a link to that in the post so it shows up there, too.
Because of my many positive vacation experiences in Andalusia, I just love Spanish stocks. Still, for practical reasons, I don’t have any in my portfolio except for Iberdrola. Thanks for bringing this stock to my attention ;)
It’s a bet on the European data center boom—especially in Spain—and a bet on the ECB’s interest rates trending downward.
•
22
•
3Wk·
Profit-Taking at AMD
Today, my limit sell order was filled at €525 was filled:
13 shares (15%) of $AMD (-4.35%) were sold—for a whopping +283% return and a realized profit of ~5,043 €.
I’m a big fan of the “Buy & Hold & Check”. But especially with individual stocks, the rule is: High potential always comes with increased risk specific to that individual stock. Gains on paper don’t make anyone rich—you have to realize them bit by bit at some point.
My DCA-out strategy from now on looks like this:
Instead of closing out the entire position at once or blindly holding on, I gradually lock in profits as prices rise:
- The principle: For every €50 increase in price I reduce my remaining position by 15%.
- The next milestones:
- 575 € ➔ Sale of 15% of the remaining position
- 625 € ➔ Sale of an additional 15%
- €675 ... and so on
💡 Why take this step?
Capital protection & rebalancing: With today’s partial sale, I’ve already secured a large portion of my original investment capital. Of course, the taxes aren’t great, but after nearly 300% in just one year, I simply have to take a little bit out of the market.
Emotionless Trading: Fixed limit orders take greed and fear out of the equation.
Upside potential remains intact: The remaining shares continue to form a strong core and benefit fully from the long-term thesis surrounding AI infrastructure and data centers.
I’ll set up a similar DCA exit strategy for $NBIS (-5.16%) .
I’ll likely take profits for the first time when the price reaches €300. But I’ll have to think that through carefully.
💬 How do you handle taking profits on your top performers? Do you have fixed exit criteria, or do you consistently let winners run 100%?
Addendum: The entire profits (after taxes) went directly into $AMZN (-0.59%)
1Yr·
And again 10K of yesterday's profit invested!
After my big $HIMS (-3.06%) yesterday, my limit order to buy was triggered today at a price of $AMD (-4.35%) at a price of € 137.
Nice dip after reasonable earnings and a call with a good outlook for the coming years. I will probably $NVDA (-2.54%) I will probably increase to 10K in case of weakness so that I am well positioned for the future in the semiconductor sector.
Have you bought $AMD (-4.35%) bought more today?
what do you think of the quarterly figures yesterday?
Greetings Bubu 🫡


4Wk·
NEBIUS Raises GPU Prices by Up to 20%
$NBIS (-5.16%) Will raise prices for NVIDIA GPUs on demand starting October 1
• H100: $3.85 → $4.50 (+17%)
• H200: $4.50 → $5.40 (+20%)
• B200: $7.15 → $8.50 (+19%)
• B300: $7.85 → $9.50 (+21%)
• The price increases apply to the most important $NVDA GPU offerings and range from 17% and 21%.
Sounds like a sign of strong demand. I’m curious to see if competitors like $IREN (-6.39%) or $CRWV (-1.09%) will follow suit.
Sources:
finance.yahoo.comNBIS Stock Rallies As Neocloud Operator Hikes Prices; Peers IREN, CRWV Jump As Well
2222
1 Comment
Compute is and will remain the AI constraint 🚀 Without fully operational data centers, no Nvidia chip can function.
•
44
•
1Mon·
Supercycle on limited | Semiconductor 2026
$SOXX (-2.91%) semiconductor mix uptrend in midterm this season and market trend still get more point to high position from 52 weeks low on 254 and high on 655.
Stock market on high demand and performance :
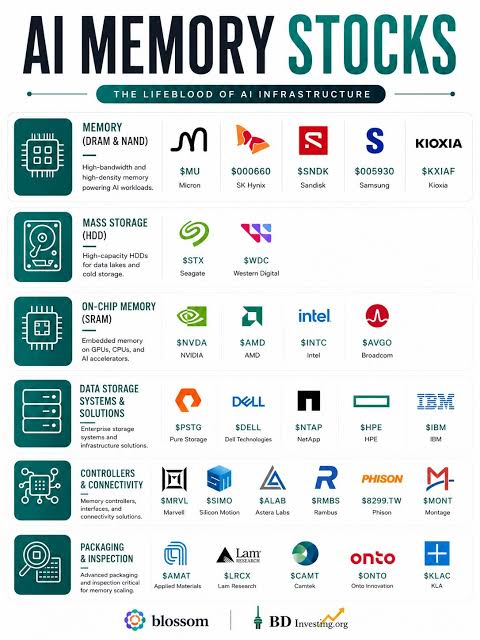
• $SNDK (-3.21%) , $SKHY (-3.41%) , $AVGO (-2.74%) , $STX (-5.67%) , $WDC (-5.32%) (tier 1)
• $INTC (-4.52%) , $AMD (-4.35%) , $NVDA (-2.54%) , $TSM (-3.5%) , $CBRS (tier 2)
ETF and Option on High trends and Fast speed :
• $MU (-0.53%) , $LITE (-5.61%) , $ASML (-1.36%) , $MRVL (-4.31%) , $NBIS (-5.16%) , $SIMO (-5.24%)
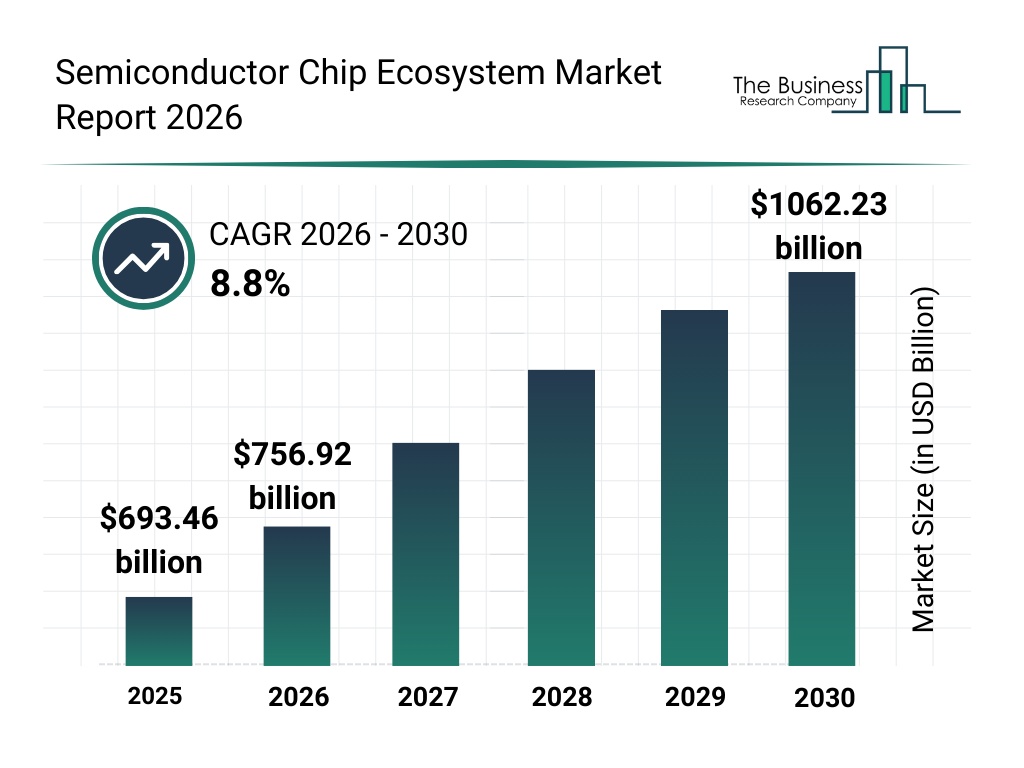
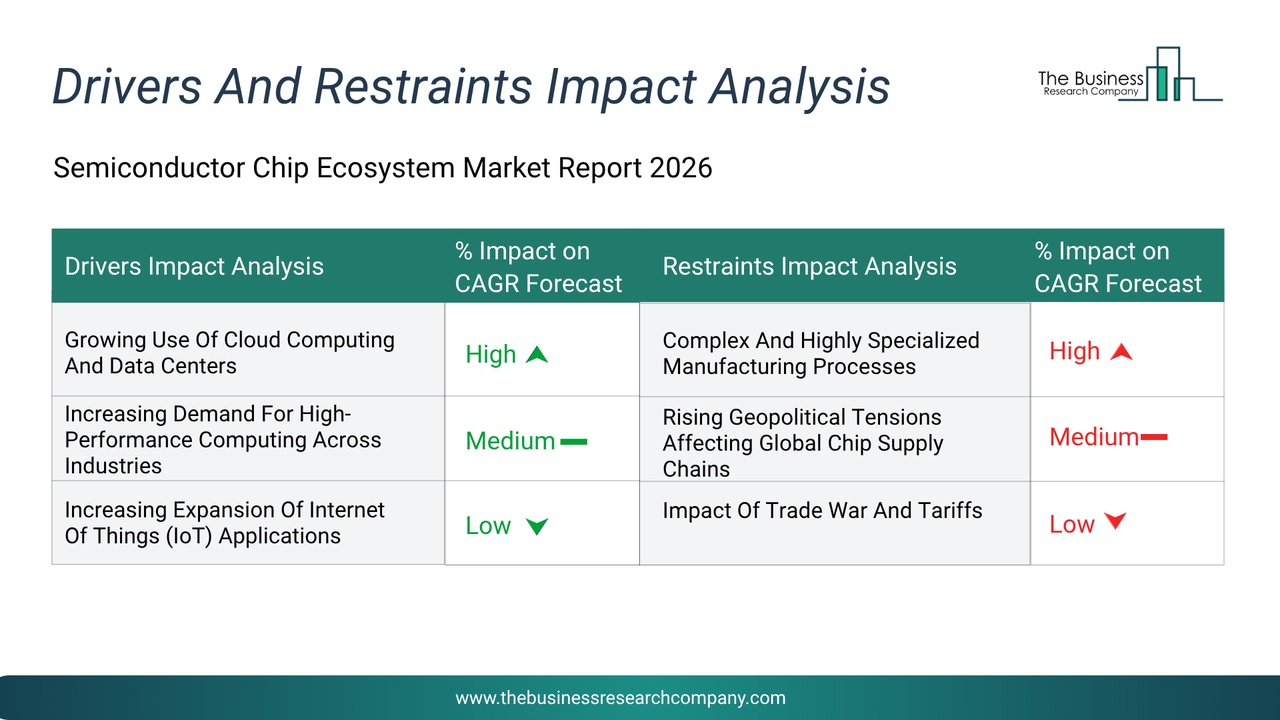
Semiconductor Chip Ecosystem Market still on top list get performance every years and continues keep on high demand for supercycle in Ai supercomputer. Its on thats semiconductor in CAGR get 8.8% to 2030 still possible makes uptrend every years, however in wave cycle on traditional event from average monthly return, semiconductor get works to drive with cycle time frame.
33
1Mon·
Amodei's call for a "pause" targets the wrong part of the AI value chain
Slows down Dario Amodeis Is the call for a slower pace in AI now hampering the industry’s growth? The Anthropic CEO called for this over the weekend in his essay “We Must Pace the Frontier”—to deliberately slow the advancement of AI model capabilities— OpenAI CEO Sam Altman and xAI CEO Elon Musk publicly agreed within hours.
Amodei’s core argument: Recursive self-improvement and security incidents such as the OpenAI Hugging Face incident showed that the models’ capabilities are growing faster than the ability to control them. His three-step plan begins with independent auditors working directly within the companies. By this, he means not
halt to training, but rather more time for safety work to proceed in parallel with progress.
Why many see this as a brake on growth
Within the community, the call is being interpreted as a warning sign regarding the AI industry’s high growth rates. A slower pace in the release of new models could dampen demand for fresh computing power and thus weigh on the valuations of AI companies and Neoclouds. Coinciding with the announcement, market prices for Anthropic and OpenAI shares fell.
Why this misses the actual driver of growth
Amodei’s appeal targets the training of new models—and it is precisely this part of the AI value chain that is now the smaller and shrinking segment. According to Deloitte, by 2026, around two-thirds of global AI computing power will be directed toward inference (the ongoing operation of already trained models).
And it is precisely this demand for inference that is growing faster than ever before:
- $GOOGL (-0.3%)-Cloud order backlog: from $240 billion to $460 billion within one quarter
- Tokens processed by Google: 16 billion per minute, an increase of 60% compared to the previous quarter
- $MSFT (+0.76%): AI order backlog increased more than twelvefold
- GPU rental prices have grown from ~10 million/MW in early 2026 to as much as ~40–50 million/MW today
So the real bottleneck remains computing power itself, not the political will to slow things down. Microsoft and Google each have investment budgets of around $180–190 billion just to meet demand at all. Training pacing is unlikely to make much of a difference to this scarcity as long as current models are already so powerful for users that demand for their use continues to grow.
Overall , the appeal seems more like a shift in priorities—away from a pure race for capabilities and toward greater safety and control. In my opinion, it is wrong to believe that this will act as a brake on the entire AI value chain.
The largest and fastest-growing part of it—inference—remains virtually untouched by the debate.
This announcement could also come at a strategically opportune time: Training new frontier models costs a great deal of money (tens of billions per model). A deliberately slowed pace would alleviate precisely this cost burden and improve the profitability of Anthropic and OpenAI, just before both are set to make potential IPOs . This safety call—which, incidentally, protects their own balance sheets—comes at just the right time for the model providers.
What are your thoughts on this?
$IREN (-6.39%)$NBIS (-5.16%)$NVDA (-2.54%)$AMZN (-0.59%)$AMD (-4.35%)$WULF (-0.46%)$ORCL (+1.11%)$CSNDX (-1.17%)$AVGO (-2.74%)$SPCX (-4.32%)$PLTR (-0.93%)$META (-1.26%)$CRWV (-1.09%)$DELL (-8.32%)$BE (-4.1%)$MU (-0.53%)
Sources:
https://darioamodei.com/post/we-must-pace-the-frontier
https://www.deloitte.com/global/en/about/press-room/2026-tmt-predictions.html
darioamodei.comDario Amodei — We Must Pace the Frontier
88
1 CommentIt's really starting to pick up steam! If a bit of euphoria and FOMO kicks in, we might even see four-digit prices. It's also noticeable that it's being traded pretty heavily—up and down—which means there's a lot of speculation involved.
••
1Mon·
Is Astra really as good as everyone says?
OpenAI announced on September 3, released GPT-6 Astra , which shatters all previous AI benchmarks and can generate a playable first-person shooter map in 28 minutes.
Key metrics from OpenAI’s own release:
- FrontierMath Tier 4: 97.6%
- ARC-AGI-3: 99.9%
- OSWorld 2.0 (computer usage): 72.6% with about 47% less time per task than its predecessor, GPT-5.6 Sol, at 65.7%
- ExploitBench: 100% compared to 78.5% for Sol (previous model)
- Artificial Analysis Intelligence Index: 61.2 compared to 60.9 for Sol and 65.7 for Claude Fable 5.1
However, there’s a catch: Astra isn’t designed to be a better chatbot, but rather as computer operator:
It fills out online forms, updates customer records in a CRM system, organizes calendars, conducts research in the browser, creates documents, spreadsheets, and presentations based on templates, and tests finished websites for errors.
Here’s what users have already built with it in the first week:
Astra no longer explains programs like Blender or Unreal Engine—it operates them itself :
- Game map in 28 minutes: Riley Brown had Astra build a first-person shooter map via Codex with full computer access. The log shows 28 minutes and 16 seconds , 20 edited files and 80 automated tests passed —including weapon and audio timing as well as explosion effects.
- A playable world requiring no prior knowledge: Matt Shumer, neither a 3D artist nor a game developer, had a survival world generated in Unreal Engine and set up as a playable character.
The point here isn’t the graphics, but the duration: Tasks spanning hours and days that the model pursues on its own have been the biggest challenge so far.
Astra is also the first model that OpenAI has classified as “Critical” for cybersecurity:
It can find and exploit unknown security vulnerabilities without a human guiding every step. The released version therefore refuses to perform offensive tasks such as building exploits; this capability is only unlocked through the Daybreak defender program. Sam Altman spoke of a “new capability level” for the model.
The leap forward, then, lies in tasks that run for hours and require the management of multiple programs. In terms of pure cognitive ability, the gap is small—in the independent Artificial Analysis Index, Astra is practically on par with its predecessor and trails Claude Fable 5.1.
Those who just chat will hardly notice a difference. Those who delegate work certainly will.
What does this mean for the AI sector?
A model that runs for 28 minutes straight consumes many times more resources than a short chat session and drastically increases token usage. Agent-based work is thus primarily a source of demand for more computing power—and that ends up with $NVDA (-2.54%)the hyperscalers ($AMZN (-0.59%)$GOOGL (-0.3%)$MSFT (+0.76%)) and the neoclouds ($CRWV (-1.09%)$NBIS (-5.16%)$IREN (-6.39%)), which lease out this capacity.
Sources:
https://openai.com/index/gpt-6-astra/
https://openai.com/index/safety-overview-gpt-6-astra/
https://www.cnbc.com/2026/09/03/open-ai-astra-gpt-6-cyber.html
1212
5 Comments
But Claude has already discovered several cybersecurity vulnerabilities on his own, well before Astra did. That's more of an insight into the competition than actually overtaking them, isn't it?
•
11
•Trending Securities
Top creators this week
Real-time data from LSX · Fundamentals & EOD data from FactSet