
$VZ (+1,03%)
$P911 (+2,89%)
$NOVN (+3,46%)
$PYPL (+1,74%)
$SOFI (+0,79%)
$UPS (+1,32%)
$GLW (-5,64%)
$KO (+0,99%)
$RCL (+3,52%)
$NXPI (+2,94%)
$V (+2,27%)
$STX (-1,3%)
$HOOD (-2,89%)
$SKHY (-3,14%)
$MBG (+1,66%)
$DBK (+3,22%)
$GEV (-0,5%)
$TER (-7,39%)
$ADYEN (-0,36%)
$WM (+3,02%)
$AIR (+1,19%)
$GOOGL (-3,28%)
$CMG (+0,54%)
$FTNT (+6,84%)
$NOW (-12,78%)
$KLAC (-1,03%)
$MSFT (-6,52%)
$CVNA (+6,93%)
$006400
$VOW3 (+1,14%)
$BMY (+0,86%)
$INCY (-0,29%)
$CAT (-9,89%)
$N1CL34
$MO (+4,91%)
$MA (+4,49%)
$AIXA (+8,38%)
$LLY (+5,92%)
$SBUX (-1,03%)
$RDDT (-20,29%)
$RBLX (-18,62%)
$ILMN (-12,81%)
$SNDK (-6,48%)
$INTC (-23,14%)
$MDLZ (+4,96%)
$COIN (-3,57%)
$AMZN (-10,47%)
$TWLO (-18,59%)
$PINS (-14,56%)
$285A (-2,97%)
$CL (+1,84%)
$GD (+4,05%)
$ABBV (+1,88%)
$PUM (+0,48%)
$CVX (+1%)
AbbVie
Azione
Azione
Ticker: ABBV
ABBV
Price
Discussione su ABBV
Messaggi
1814G·
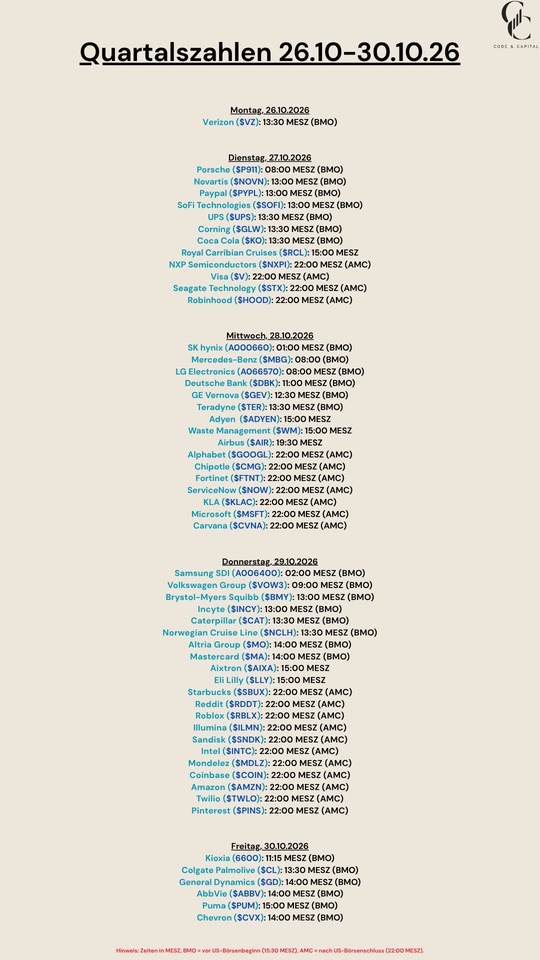
Quarterly Results: Oct. 26–30, 2016
1919
2 Commenti
OberstvonGatow@OberstvonGatow
3G
•
11
•

2Mes·
🦎 Dividend Check: AbbVie Delivers!
Hard numbers and reliable cash flow 📊💰
Today, a $102 dividend was deposited into my account
I’ve had AbbVie in my portfolio since 2021. The results after 5 years? A whopping doubling of book profit and a steady stream of dividends that’s just a joy to watch.
Here are the facts straight from my portfolio:
📌 Position: 59 shares of AbbVie (ABBV)
🏛 Invested since: 2021
💵 Initial investment: 7,404.88 total (125.51 per share)
📈 Performance: +99.87% Paper profit (+$7,395.37)
💸 Cash Flow: $1,527.91 in dividends received
🏆 Total return:+$8,923.28 (+120.5% total return)
🔥 Bonus: The yield on cost is now a whopping 6.48%.
How about you—do you have pharmaceutical heavyweights like AbbVie in your portfolio?
2525
6 Commenti
2Mes
6.5% YoC is really impressive for such a top-tier company... I've been on the waitlist forever.
I'm also very happy with $MRK, though.
I'm also very happy with $MRK, though.
•
22
•
2Mes·
AbbVie Dividend
It’s almost time—AbbVie’s dividend is coming on August 14!
After realizing some solid gains on $JNJ (+1,3%) , I felt my portfolio was missing a pharmaceutical company that consistently delivers and grows—in other words, a true quality stock. That’s why the decision to buy AbbVie in April was pretty easy for me.
I come from the pharmaceutical industry myself and know that enormous sums have to be invested every year in research, as well as in facility development and expansion—yet profits skyrocket when new drugs take off and hit the market!
Did you actually know that more than 90% of developed compounds never make it to market? There are countless reasons for this—lack of approvals, pharmaceutical regulations, lack of efficacy. I never cease to be fascinated by the fact that so much money can still be made despite all that. Imagine if your auto repair shop couldn’t fix 90% of the vehicles that came in. The business would probably go bankrupt in no time.
Despite all these problems in the pharmaceutical industry—I’m firmly convinced that AbbVie will remain in my portfolio for a long time to come. Do you have any pharmaceutical stocks you’re deeply convinced about?
*AI-generated image*
1818
4 Commenti
2Mes
Missed the countercyclical entry point by a few months. Now close to the ATH. Well, when it comes to the dividend, it's not that big of a deal.
•
44
•3Mes·
Keep collecting...
The slight setback following the figures from $CARR (-2,05%) and the weakness in $ACLN (-0,76%) to make a small additional purchase. I also did the same with $NESN (+0,44%) and $MCD (+2,55%) I made small one-time purchases outside of my savings plans.
I’m already very excited about the $ABBV (+1,88%) and $NOVO B (+2,53%) results.
Other than that, the portfolio also hit a new all-time high 🤓
99
1 Commento
••
3Mes·
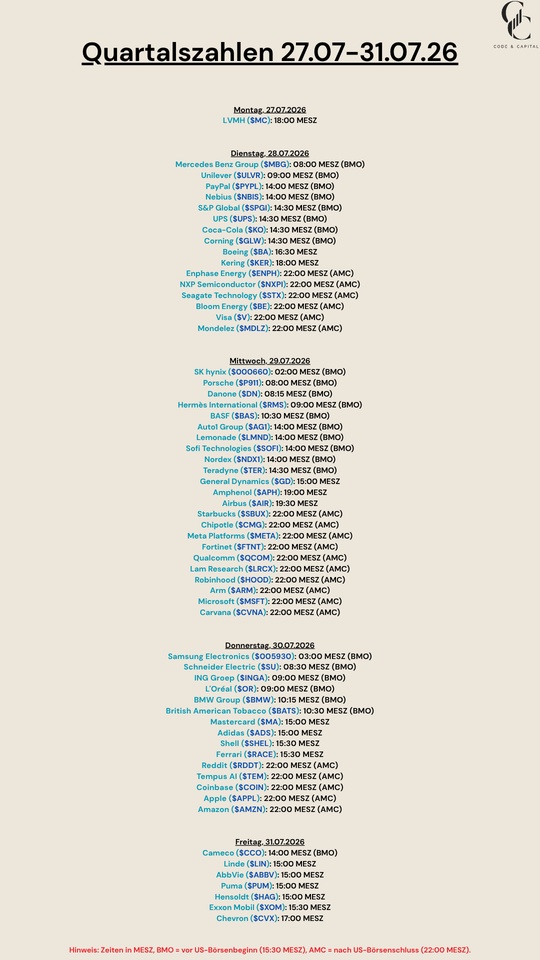
Quarterly Results: July 27–July 31, 26
$MC (-0,74%)
$MBG (+1,66%)
$ULVR (+0,54%)
$PYPL (+1,74%)
$NBIS (-8,24%)
$SPGI (+2,11%)
$UPS (+1,32%)
$KO (+0,99%)
$GLW (-5,64%)
$BA (+2,61%)
$KER (-0,24%)
$ENPH (+1,16%)
$NXPI (+2,94%)
$STX (-1,3%)
$BE (-5,92%)
$V (+2,27%)
$MDLZ (+4,96%)
$000660
$P911 (+2,89%)
$BN (+1,89%)
$RMS (+0,5%)
$BAS (+1,61%)
$AG1 (+4,39%)
$LMND (+0%)
$SOFI (+0,79%)
$NDX1 (+1,1%)
$TER (-7,39%)
$GD (+4,05%)
$APH (+0,72%)
$AIR (+1,19%)
$SBUX (-1,03%)
$CMG (+0,54%)
$META (-0,2%)
$FTNT (+6,84%)
$QCOM (-0,95%)
$LRCX (-2,49%)
$HOOD (-2,89%)
$ARM (-8,76%)
$MSFT (-6,52%)
$CVNA (+6,93%)
$005930
$SU (+0,91%)
$INGA (-2,37%)
$OR (+0,15%)
$BMW (+0,79%)
$BATS (+1,55%)
$MA (+4,49%)
$ADS (+5,42%)
$SHEL (+2,23%)
$RACE (+1,39%)
$RDDT (-20,29%)
$TEM (-1,69%)
$COIN (-3,57%)
$AAPL (+1,68%)
$AMZN (-10,47%)
$CCO (-0,15%)
$LIN (-1,55%)
$ABBV (+1,88%)
$PUM (+0,48%)
$HAG (+2,22%)
$XOM (+0,88%)
$CVX (+1%)
1414

4Mes·
5 singole Stock USA appena aggiunte al mio portafoglio 😎
$PFE (+1,7%) - Pfizer - 45Q
$CWT (+1,42%) - Ca Water Serv - 25Q
$PEP (+0,76%) - PepsiCo, Inc. - 10Q
$VZ (+1,03%) - Verizon Communications - 25Q
$ABBV (+1,88%) - AbbVie - 5Q
Queste 5 singole Stock intendo tenerle a lungo nel mio portafoglio come azioni difensive e per prendere i dividendi sul lungo periodo, da non vendere mai…
99
2 Commenti
$PFE is also part of my dividend portfolio. I am hoping for stable earnings with a rising share price in the long term.
•
33
•
5Mes·
Company presentation: UCB
Hello dear community,
Today I would like to introduce you to another company from the healthcare sector. Let's stay on European soil and take a look at our neighbors in Belgium.
Today's presentation is all about "Union Chimique Belge" $UCB (+3,23%)
🧬 UCB SA $UCB (+3,23%)
: The resurrected growth machine of global biopharma
UCB (Union Chimique Belge) $UCB (+3,23%) is not a sluggish pharmaceutical giant that only milks old patents. It is one of the best-positioned biotech companies in Europe that has not only survived the painful loss of its billion-dollar blockbuster Vimpat, but has turned it around into an unprecedented phase of operational growth. While two years ago the market was still in doubt about the approval pipeline, UCB $UCB (+3,23%) set the course for a decade of protected growth. Its focus is on highly effective, immunological and neurological niche therapies for serious diseases - far removed from interchangeable mass-produced generics.
1. the business model: the 5-pillar growth rocket 🔬💉📈
UCB $UCB (+3,23%) has radically rejuvenated its entire business model and controls the market for specialty therapies with a state-of-the-art product portfolio:
-The global platform blockbuster (Bimzelx®): As the first dual IL-17A and IL-17F inhibitor, Bimzelx is the competition's technological nightmare. It sets new clinical standards in psoriasis and is aggressively taking market share from top dogs such as AbbVies $ABBV (+1,88%) Skyrizi - freshly underpinned by the latest head-to-head study data (BE BOLD), which prove its clear superiority.
💉Bimzelx® (bimekizumab):
USA: Until 2035 (without optional patent extensions).
Europe: Until 2036.
This means that there is no danger from copycat products (biosimilars) for at least another 10 years.
-The rare neurology double hit (Rystiggo® & Zilbrysq®): In the rare neuromuscular disease myasthenia gravis (gMG), UCB $UCB (+3,23%) strategically occupies the market twice - once with a monoclonal antibody and once with a subcutaneous peptide. This allows them to cover almost all patient needs at the same time.
💉Rystiggo® (rozanolixizumab):
Europe: Until 2034
USA: Until 2035
Japan: By 2037
💉Zilbrysq® (Zilucoplan):
Europe & USA: Until 2035
Japan: Until 2040
-Orphan Drug Premium Pricing (Fintepla® & Kygevvi™): With Fintepla in rare forms of epilepsy and the brand new 2026 US approval for Kygevvi (therapy for ultra-rare TK2 deficiency), UCB secures exclusive access to high-priced niche markets with enormous pricing power.
💉Fintepla® (fenfluramine):
Europe: Until 2032
USA: Until 2033 (with some downstream formulation patents even extending to 2038).
2. the key figures 📊
Market capitalization: Approx. EUR 47.7 billion (Listed on Euronext Brussels).
-Sales explosion: In the past financial year, turnover shot up by +26 % (+29 % adjusted for currency effects) to EUR 7.74 billion. The five new growth drivers more than doubled their sales to EUR 3.3 billion!
-EBITDA levers: Adjusted EBITDA exploded by +79 % to EUR 2.64 billion. The margin jumped to 34,0 % - a gigantic proof of the operating leverage (economies of scale of the global drug launches).
-Core EPS: Adjusted earnings per share almost doubled to EUR 9.99.
-Balance sheet restructuring (net cash): Within 12 months, almost EUR 1.5 billion of debt was completely repaid. UCB $UCB (+3,23%) emerged with a clean net cash position into 2026 and is now fully capable of making strategic acquisitions (M&A).
3. why is the share exciting NOW? 🚀
🟢 Decade of patent consolidation: The most important point for pharma investors: the core patents for growth drivers such as Bimzelx do not expire in the USA and Europe until between 2034 and 2037 expire. UCB $UCB (+3,23%) has one of the longest protected portfolios in the entire sector.
🟢US market penetration ignites: For Bimzelx, US commercial insurance coverage for 2026 has been expanded by 36 million patients to over 80%. The real sales tsunami in the USA is only just beginning.
🟢 The pipeline never sleeps: Behind the launches, the next wave is already waiting. The FDA granted fast-track status for the Alzheimer's hopeful Bepranemab at the beginning of 2026.
🟢Commercial excellence beats hype: UCB $UCB (+3,23%) reliably delivers hard numbers. The guidance for 2026 promises another year of high single-digit to low double-digit percentage sales growth despite the upcoming patent expiry of the old epilepsy drug Briviact.
🟢The 5 new hopefuls: They have increased their combined sales in 2025 to more than doubled to over 3.3 billion euros!
4. risks ⚠️
❗️Approval & trial dynamics: Clinical development is expensive. Setbacks in phase 3 trials (such as the upcoming readouts in the second half of 2026) can dampen sentiment in the short term
❗️Copycat erosion (Briviact LOE): Patent protection for the mature epilepsy drug Briviact will expire during 2026 in the US and Europe. This decline in sales must be actively swallowed by Bimzelx & Co.
❗️US regulation & price war: The US biologics market is highly competitive. Rebates to the powerful Pharmacy Benefit Managers (PBMs) could eat into gross margins
❗️Bewertung: With a P/E ratio of over 30, the share is no longer a bargain after the brilliant price rally (close to the 52-week high of ~EUR 290). A lot of growth is already priced in.
5.🚀 Outlook & pipeline catalysts for 2026
The management under CEO Jean-Christophe Tellier and CFO Sandrine Dufour confirmed the guidance for the current year 2026 in the spring:
✅Turnover 2026: Growth in the high single-digit to low double-digit percentage range is expected (in CER).
✅EBITDA 2026: Adjusted EBITDA is expected to increase in the high single-digit to mid teens percentage range.
✅ Pipeline successes: In early 2026, UCB received US FDA approval for Kygevvi™ (therapy for TK2 deficiency, an extremely rare genetic disease). In addition, an important Phase 2b trial with Galvokimig in atopic dermatitis is underway.
🎯 Personal conclusion & Reaper rating 🧐
I personally find UCB $UCB (+3,23%) extremely interesting and is high on my watch list because UCB has achieved the dream turnaround to a compounder and has mastered the tough transition to new products flawlessly. ( which I also think is $NOVO B (+2,53%) hoffe🙇♂️🙄) It is no longer a highly speculative biotech bet, but a highly profitable pharma growth machine with a fortress balance sheet.
Anyone looking for a European alternative to Novo Nordisk $NOVO B (+2,53%) could find the perfect candidate in UCB $UCB (+3,23%) could be the perfect candidate.
BONUS MATERIAL 💀
Jack's mustard: "The story is simply a dream for any quality investor. UCB has managed to do what 80% of pharma companies fail to do: not only have they cushioned the loss of a patent on an old blockbuster, but they have also pushed the successor rocket Bimzelx so brutally into the market that profits are literally exploding. The fact that they are now also completely debt-free takes a massive amount of risk off the table. After the brutal rally since the end of 2023, the stock is currently consolidating healthily around EUR 244 - for me an absolute top entry for the first tranche. If you are patient, you can lay the foundations for a relaxed decade of investment in your portfolio bunker. If the share corrects towards EUR 220, we won't hesitate for long, but will reload!
Rating: 🔥 BUY
Reaper Score:
8,3 / 10 (Based on the spectacular margin expansion, the eliminated debt and the verified sales momentum until the mid-2030s).
@Get_Rich_or_Die_Tryin
@Tenbagger2024
@schlimmschlimm
@Raketentoni and of course all other users ✌️


+ 2

2222
22 Commenti
Thank you! :-) That's great! Another hot thing! I've just skimmed it. But you can already see that I'm going to go into more depth. That's for sure! I can only say again and again, "Respect to you all!" @Tenbagger2024 @Raketentoni @Get_Rich_or_Die_Tryin for the extremely good performances.
•
66
•
5Mes·
Why I bought AbbVie shares
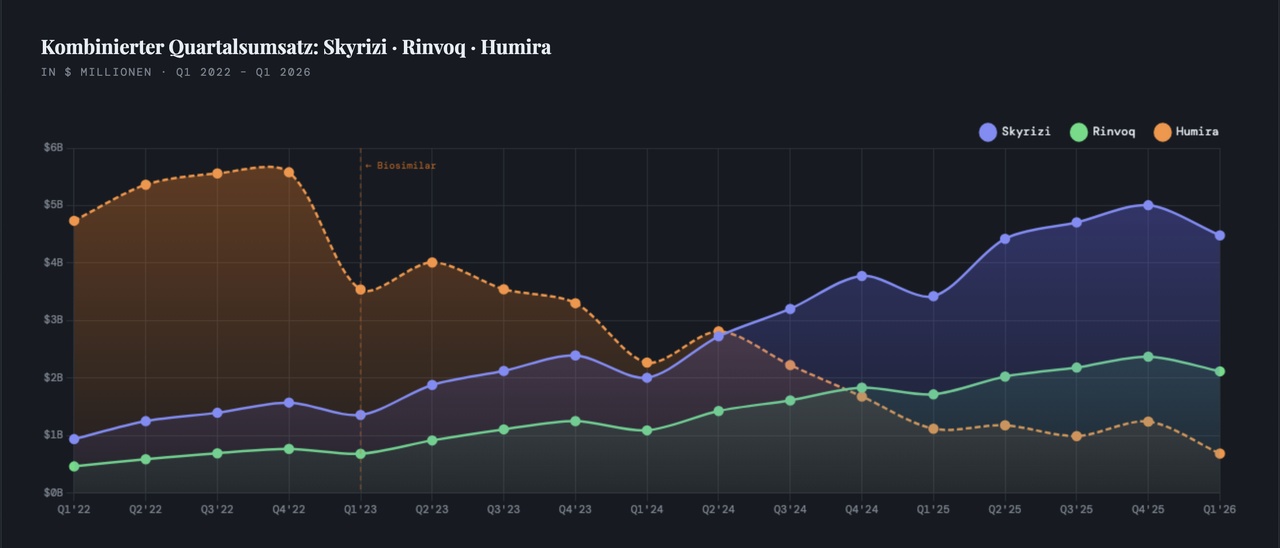
AbbVie $ABBV (+1,88%) has solved a major problem well: the discontinuation of Humira.
Humira was the best-selling drug in the world for many years.
Now copycat products are coming onto the market, which is why sales have fallen as expected.
But the management has mastered this transition well.
The new drugs Skyrizi and Rinvoq are growing strongly.
Not only do they compensate for the decline in Humira, but together they could even generate more sales in future than Humira used to.
What's more:
AbbVie is building a broader base with acquisitions, for example in cancer medicine and neurology. This makes the future more stable.
AbbVie is also strong when it comes to dividends. The company has regularly increased its dividend for many years and earns enough money to continue paying out.
Expected return:
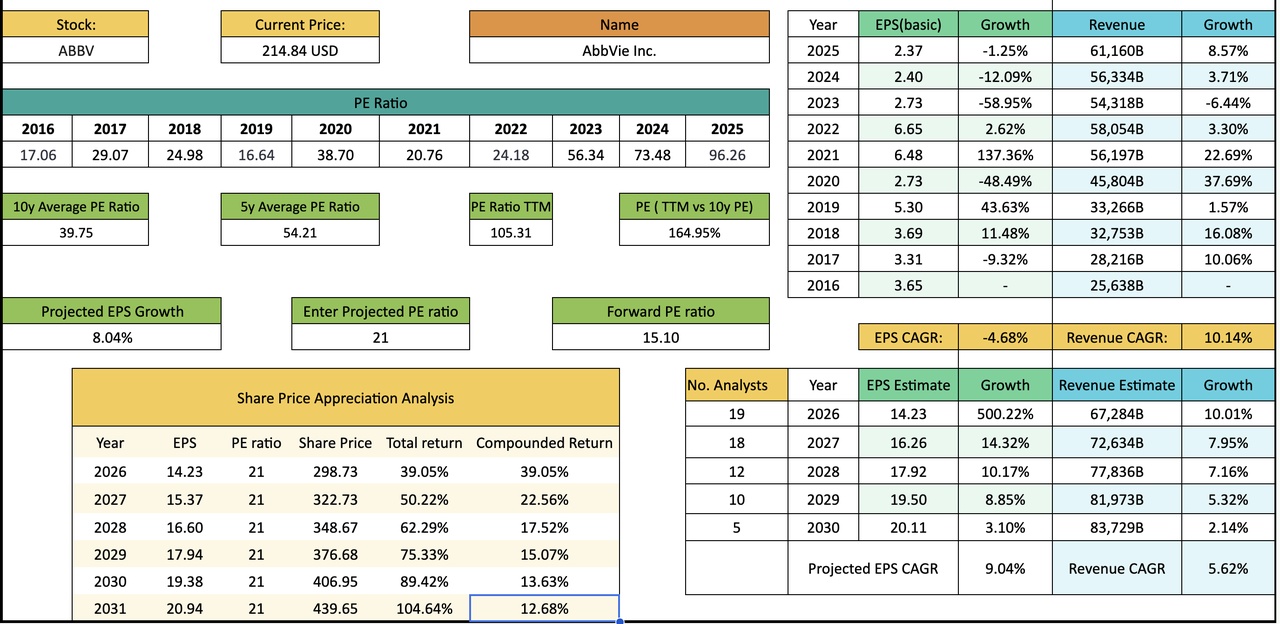
If I assume that AbbVie is valued at a long-term P/E ratio of around 21 and that the company grows by 8.04% annually, then I expect a return of around 12.68% per year from the share price increase alone. This does not include the dividend. Including the dividend, I am looking at a total return of over 15% per year.
In short:
AbbVie is a defensive healthcare company that has passed its biggest stress test and could now be on the verge of new growth again
You can find more stock analysis here: https://youtu.be/Oj_POIWKyVo?si=X04YcJTxc1cKioN7
2020
3 CommentiA dividend investment for the long-term conservative investor
•
44
•5Mes·
Le 18 US Stock che intendo acquistare prossimamente con qualche grafico…
- $MAIN (+1,76%) - Main Street Capital
- $ARCC (+2,23%) - Ares Capital
- $CWT (+1,42%) - Ca Water Serv
- $TGT (+1,56%) - Target
- $SBUX (-1,03%) - Starbucks
- $MKC (+1,38%) - McCormick
- $ABM (+2,12%) - ABM Industries
- $SYY (+1,09%) - Sysco
- $ED (+1,03%) - Consolidated Edison
- $VZ (+1,03%) - Verizon Communications
- $SO (+0,82%) - The Southern Co.
- $MDLZ (+4,96%) - Mondelez International, Inc.
- $MO (+4,91%) - Altria Group, Inc.
- $PEP (+0,76%) - PepsiCo, Inc.
- $KO (+0,99%) - The Coca-Cola Co.
- $PG (+0,95%) - Procter & Gamble Co.
- $ABBV (+1,88%) - AbbVie, Inc.
- $MCD (+2,55%) - McDonald's Corp.
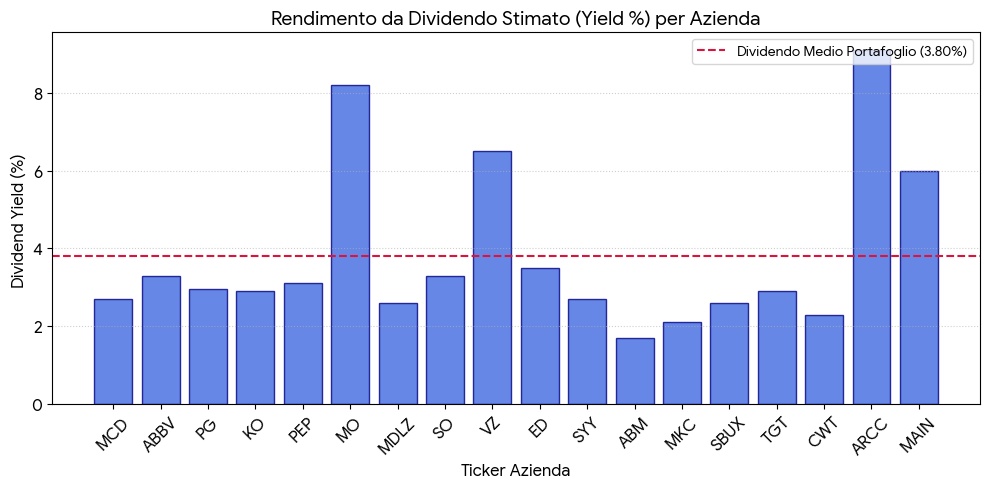
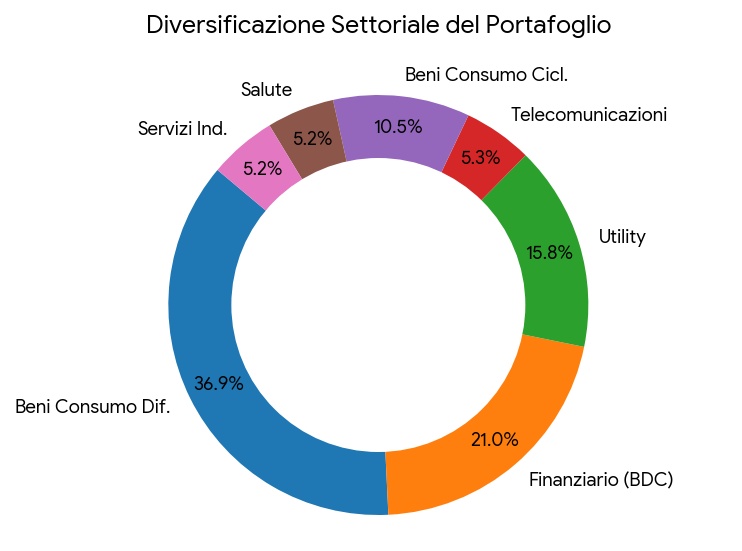
Un portafoglio più orientato alla resilienza la crescita a lungo termine del dividendo e ad avere una parte del mio portafoglio totale (costituito ad oggi da un +90% da ETF) anche una parte più “difensiva” e con aziende che tendono ad umentare il loro dividendo o darne uno già elevato, anche se la maggioranza è inferiore al 4%
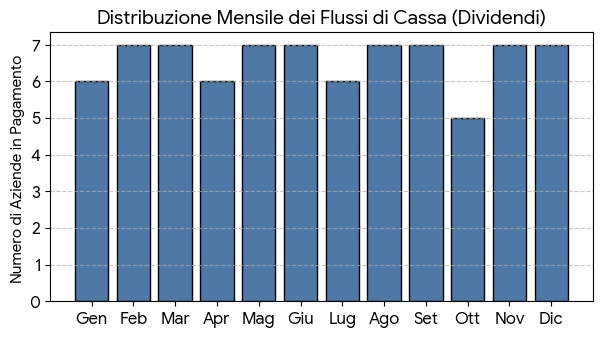
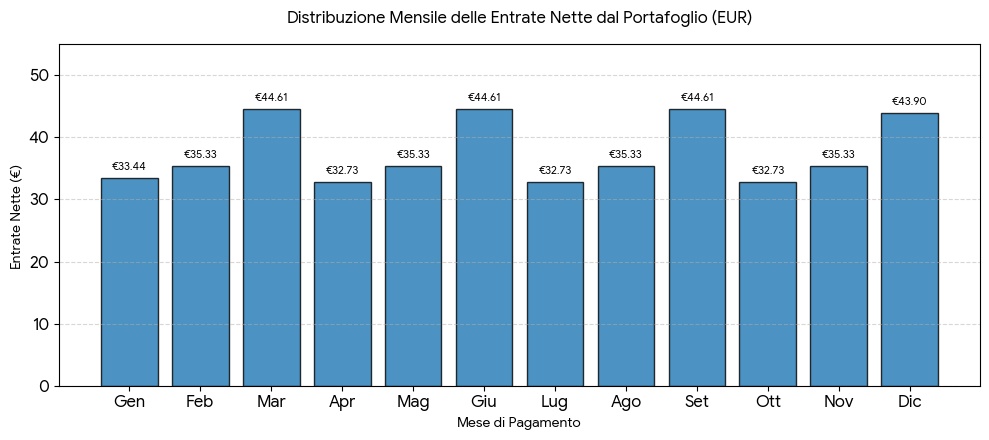
I pagamenti sfasati garantiscono un flusso di cassa costante…
Entrate mensili lorde stimate…
Edit: ecco le distribuzioni mensili tolto il -15% alla fonte negli USA e poi il -26% italiano.
66
11 Commenti
5Mes
Secondo il grafico avresti un dividendo medio di 3,8% lordo circa, togliendo il 15% e poi il 26% avrai il 2,39% netto, con l' $SPYD avresti un 2,23% lordo (Distribuzione del 2025) quindi 1, 65% netto, una differenza di 0,74.
Però nel conteggio ci sono Main ed Ares che non sono dividend aristocrat, potresti ottenere lo stesso dividendo dividendo la somma in 78% ETF, 11% Main ed 11% Ares, in questo modo avresti solo 3 voci da monitorare anziché 20 (ho chiesto a chatgpt quanto devi avere in Main ed Ares per raggiungere il 2,39% netto prendendo come dividend yield la distribuzione del 2025).
Riguardo il messaggio di prima in cui dicevi che i dividendi fossero diminuiti, quello è tutto causa dell'effetto cambio, che avresti anche acquistando i 20 titoli singoli, di fatto un ETF avendo solo dividend aristocrat il dividendo deve per forza di cose aumentare di anno in anno, sennò non sarebbero quello che sono.
Il punto di tutto il discorso è che hai preso delle azioni con l'unica discriminante del dividendo, prova a fare backtest o chiedere all'IA di confrontare questo tuo paniere di azioni con l'indice di riferimento, se noti una sovraperformance nel tempo di ciò che hai selezionato allora bene, sennò è stata tutta fatica sprecata che ti potevi evitare con un ETF che ha un rendimento annuo di quasi il 12%
•
22
•5Mes·
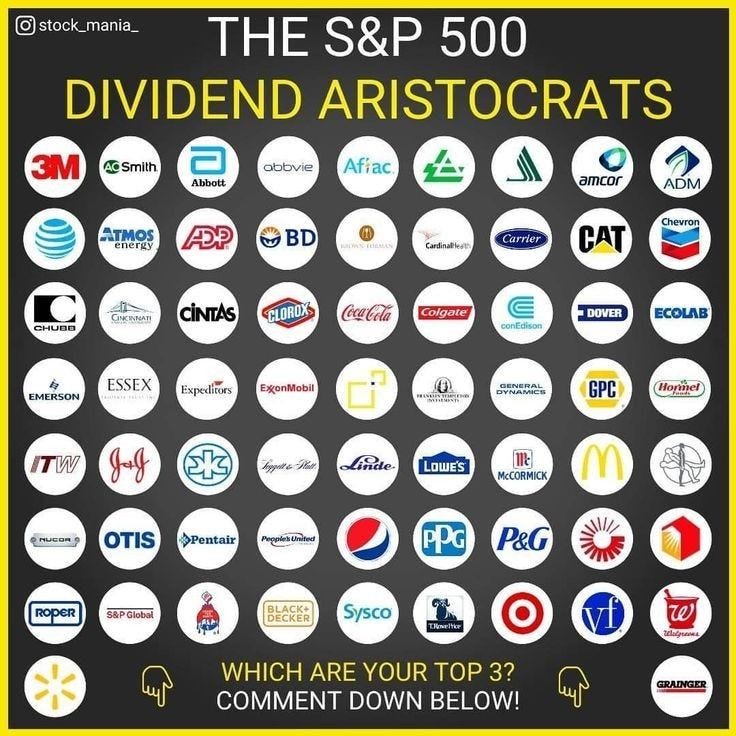
Ecco la lista delle 20 “Stock Statunitensi che intendo aggiungere al mio portafoglio!
Con una spesa di 20 mila € totali intendo impegnare circa 1000€ per singola Stock; ecco l’elenco che mi son fatto, ditemi se vi piace:
Queste 20 singole Stock USA 🇺🇸 intendo tenerle a lungo come investimento orientato ad azioni di valore e al creare un reddito passivo costante ed in crescita, includendo diverse Dividend Aristocrats e Dividend Kings che affiancati a società di sviluppo aziendale (BDC) che pagano dividendi più alti così da sopperire in parte alle relative basse distribuzioni di molte stock più difensive delle 20 Stock selezionate.
88
9 CommentiAs I see it, it's a collection of US large caps, mainly from the consumer goods sector with a few additions from other industries.
If you are betting that the historical growth of established companies like CocaCola will continue, you can certainly follow this approach.
Personally, I would have too many individual stocks to monitor. I think that the share price performance will also lag a good deal behind an investment in tech stocks - but of course that's the famous looking into the crystal ball.
For my own strategy of a distribution portfolio, actual dividends would be too low for me. However, if you are looking for dividend growth and substance, you can certainly add these stocks to your portfolio. Alternatively, there are certainly ETFs that follow the underlying approach (US large caps ex tech).
In any case, I wish you every success 🙂
•
44
•