Shell
Price
Discussione su SHEL
Messaggi
2522 year review
What do you think of my portfolio performance for the last 2 years?
$KO (+2,07%)
$VWRL (-1,04%)
$VUSA (-1,24%)
$VEUR (-0,31%)
$VOW (+2,08%)
$ENI (+1,56%)
$BAYN (-0,89%)
$INTC (-5,89%)
$SAN (-0,06%)
$FCT (+1,36%)
$SL (+0,51%)
$ISP (-0,89%)
$SHEL (+2,49%)
$LDO (+3,2%)
$QBTS (-7,37%)

16 European companies are paying dividends in September. My algorithm only identifies 4 as "OPTIMAL."
Morningstar published its list, and 14 of the 16 companies are British. I ran the 13 I’ve already analyzed through my tool:
🟢 EXCELLENT (4)
• $NWG (-0,49%) NatWest - 5.06%, P/E ratio 8.68x, quality 75/100
• $RKT (+2,28%) Reckitt - 4.16%, P/E ratio 11.6x
• $HSBA (+0,08%) HSBC - 3.70%, P/E ratio 10.36x
• $LLOY (-1,44%) Lloyds - 3.58%, P/E ratio 15.6x
🟣 WATCH (3)
• Relx, AstraZeneca, and Unilever ($REL (+2,05%) , $AZN (-0,98%) , $ULVR (+1,85%) ). Quality businesses, but valuations no longer offer room to run
🟠 CAUTION (4)
• BP (4.87%), Shell (3.39%), Rio Tinto (4.52%), and Barclays ($BP. (+3,12%)
$SHEL (+2,49%) , $RIO (-0,74%) , $BARC (-0,02%) ). High returns that mask cyclicality. The 78% marginal tax rate on oil in the UK doesn’t help
🔴 LOW THRESHOLD (2)
• Rolls-Royce $RR. (-2,1%) : It’s on Morningstar’s list, but pays 0.39%. Quality 35, Opportunity 5
• Glencore $GLEN (+2,37%) : Quality 10/100. A high yield can also mask a declining business
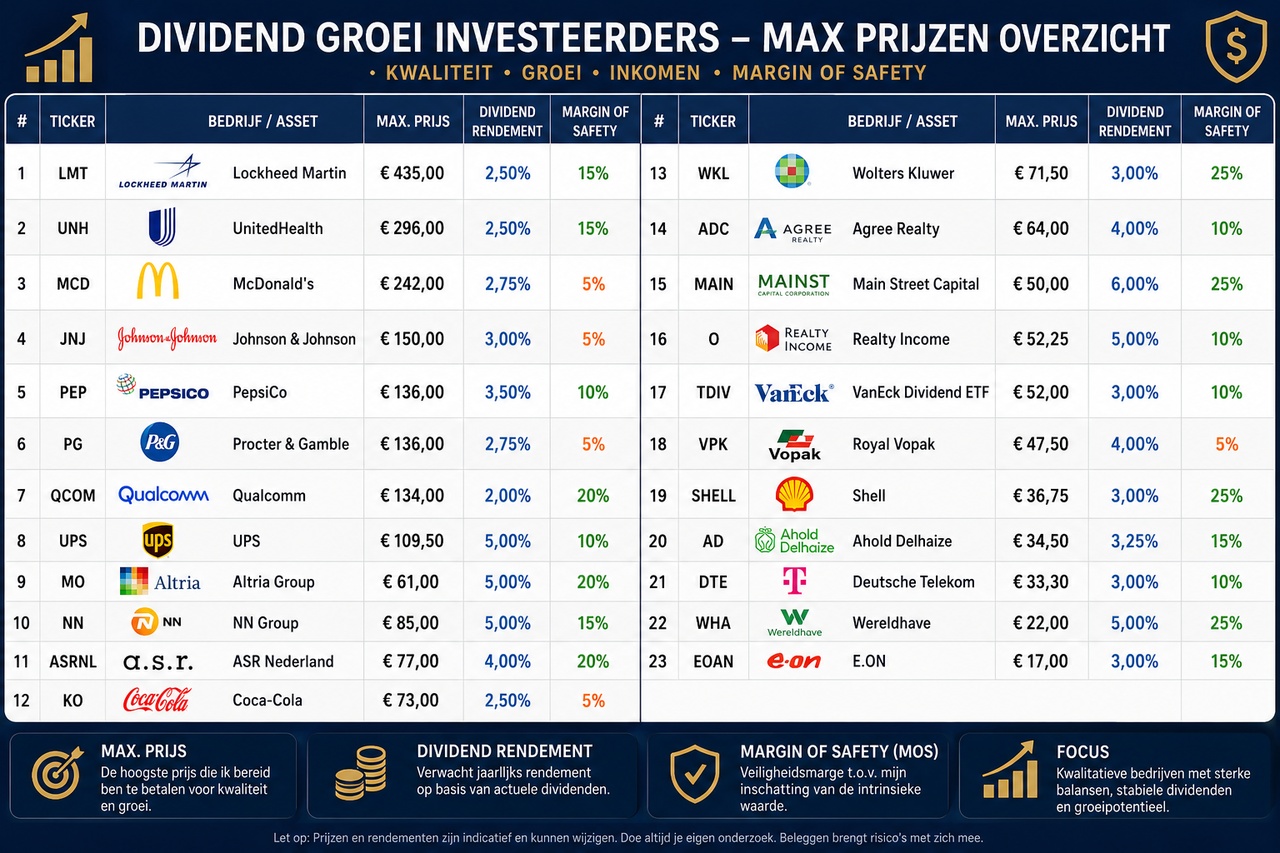
My Maximum Purchase Prices for Dividend-Growth Stocks
I invest with a focus on dividend growth, quality, and attractive valuations. That’s why I set a maximum purchase price for each position based on dividend yield, growth expectations, and my own Margin of Safety (MOS).
I use this overview as a guide to keep emotions out of my buying decisions and to wait patiently for opportunities.
$LMT (+3,31%)
$UNH (-1,66%)
$MCD (+0,02%)
$JNJ (+0,73%)
$PEP (+1,98%)
$PG (+1,17%)
$QCOM (-2,78%)
$UPS (-0,29%)
$NN (-0,24%)
$ASRNL (+0,82%)
$KO (+2,07%)
$WKL (+0,26%)
$MO (+1,55%)
$ADC (+0,51%)
$MAIN (-0,95%)
$O (+0,65%)
$TDIV (+0,13%)
$VPK (+1,23%)
$SHEL (+2,49%)
$AD (-0,57%)
$DTE (+0,98%)
$WHA (-0,41%)
$EOAN (+1,04%)
Record profits
🛢️💰 Exxon, Chevron, BP, Shell, and TotalEnergies posted a combined $48B in Q2 profit and nearly $90B in cash generation, an all-time high, fueled by elevated oil prices from U.S.-Iran tensions.
$XOM (+2,39%)
$CVX (+2,14%)
$BP. (+3,12%)
$SHEL (+2,49%)
$TTE (+2,29%)
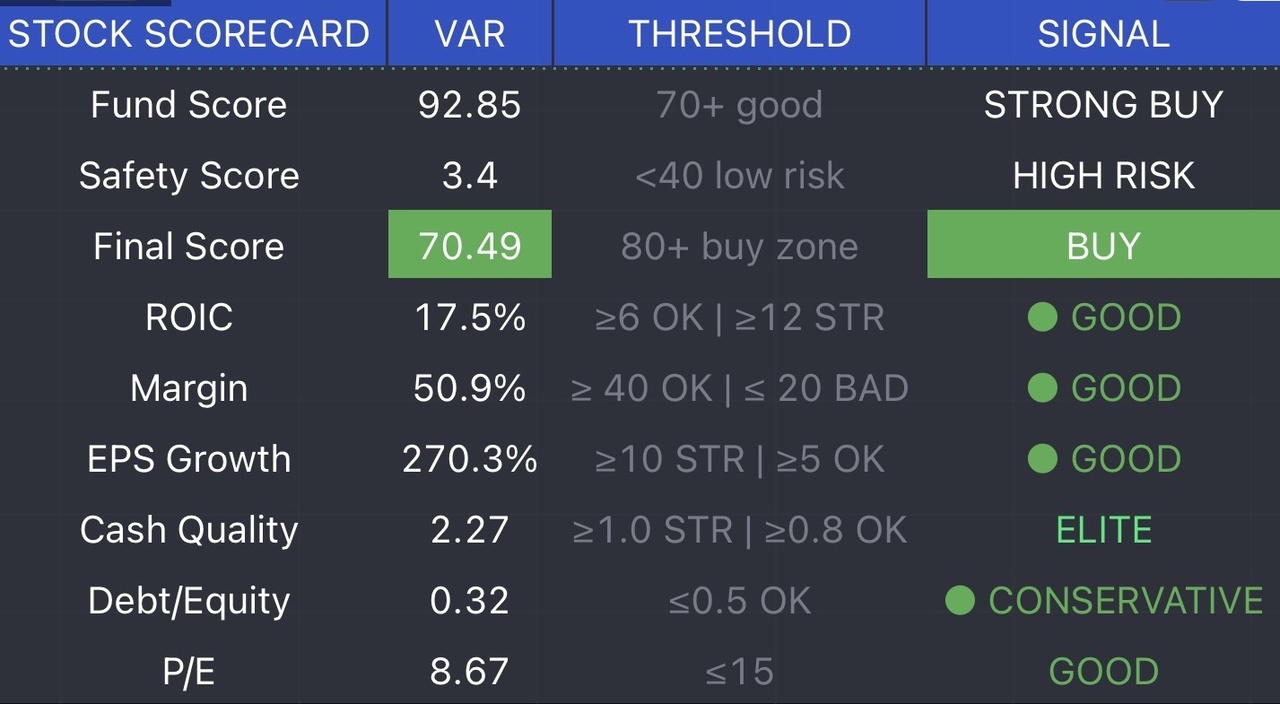
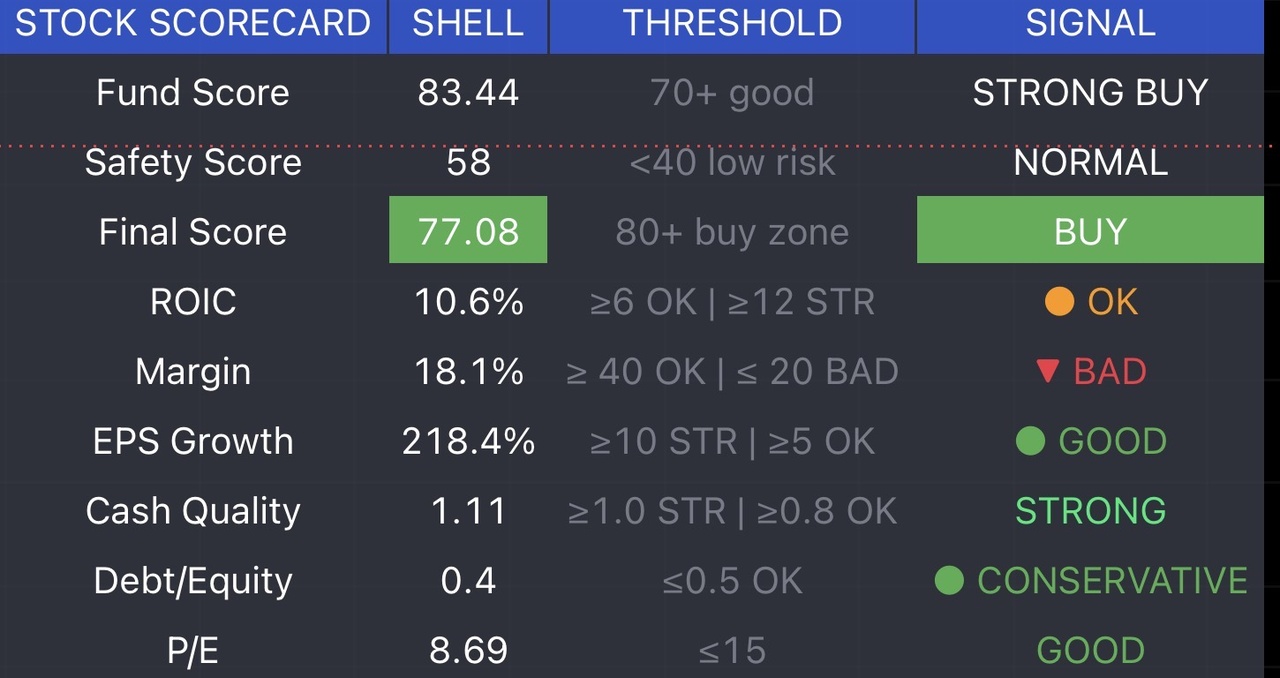
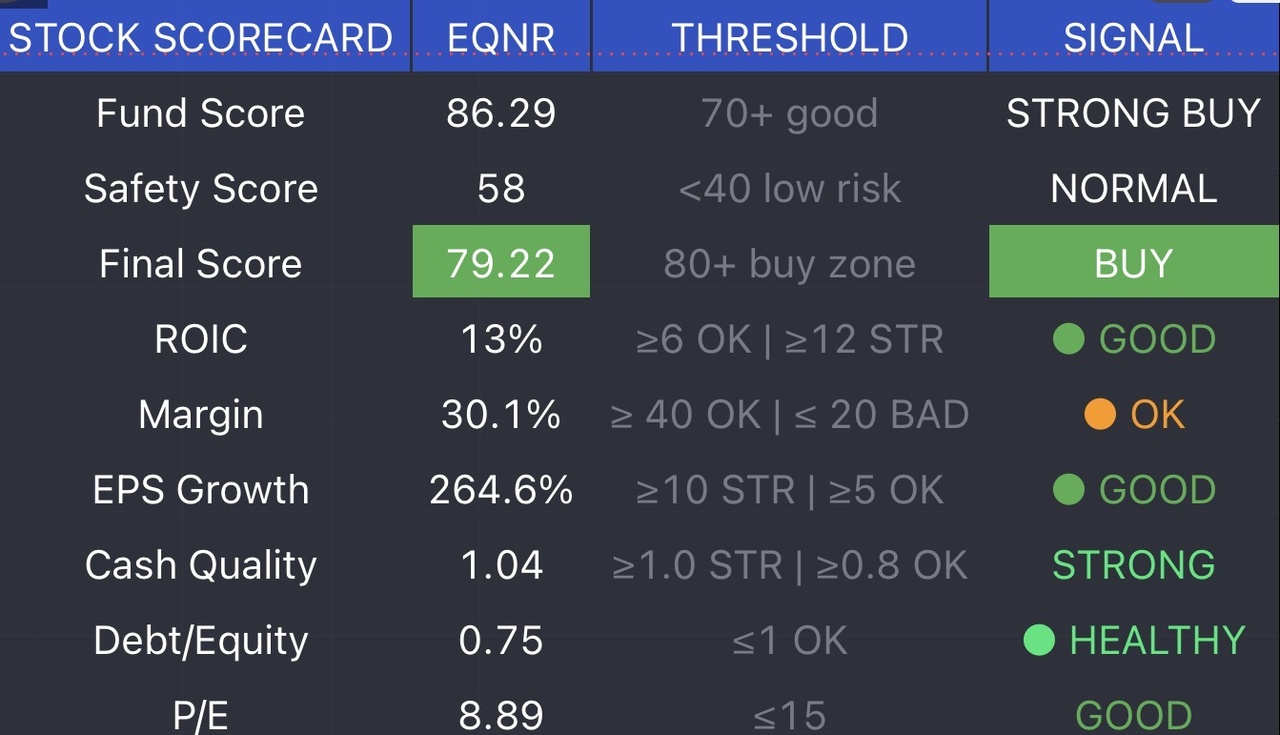
Shell versus VAR energi versus Equinor
$SHEL (+2,49%) came in good
Fund score is at good spot
margin and roic can be better
$VAR (+2,45%) is better placed from what i see
But lot more volatility (safety score)
equinor is the one i would choose, but all 3 will be ok, choose shell or equinor if you plan on holding for 20-years region
final score
Shell was sold
Yesterday, I sold my entire position in $SHEL (+2,49%) at a price of €40, achieving a return of 33% since the start of the investment.
It’s been a good decision so far, given that the stock price fell yesterday and the price of oil has dropped today for the third day in a row to $79 per barrel of Brent.
Once the stock price returns to normal, I’ll $SHEL (+2,49%) again. In my opinion, it remains a solid company with a good dividend policy.
Would you take your profits and reinvest them later in the same company?
𝐒𝐡𝐞𝐥𝐥: 𝐒𝐮𝐫𝐠𝐢𝐧𝐠 𝐂𝐚𝐬𝐡 𝐅𝐥𝐨𝐰 𝐚𝐧𝐝 𝐓𝐫𝐚𝐝𝐢𝐧𝐠 𝐒𝐭𝐫𝐞𝐧𝐠𝐭𝐡 𝐃𝐫𝐢𝐯𝐞 𝐒𝐡𝐚𝐫𝐩 𝐄𝐚𝐫𝐧𝐢𝐧𝐠𝐬 𝐆𝐫𝐨𝐰𝐭𝐡 𝐚𝐧
⠀
📊 𝐑𝐞𝐬𝐮𝐥𝐭𝐬
• Adjusted earnings: $9.84B vs. $6.92B QoQ and $4.26B YoY
• Adjusted EPS: $1.76 vs. $1.22 QoQ and $0.72 YoY
• Adjusted EBITDA: $20.71B vs. $17.74B QoQ
• Operating cash flow: $21.43B
• Free cash flow: $17.52B
• Income attributable to shareholders: $10.82B
⠀
💰 𝐂𝐚𝐩𝐢𝐭𝐚𝐥 𝐑𝐞𝐭𝐮𝐫𝐧𝐬
• Q2 shareholder distributions: $5.2B
• Share buybacks completed: $3.0B
• Cash dividends paid: $2.2B
• Dividend declared: $0.3906 per share
• New buyback programme: $4.2B, including $3.0B of new repurchases and $1.2B carried over
⠀
📌 𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
• Higher realised prices, LNG trading, refining, chemicals and oil-products optimisation supported earnings
• Net debt fell to $41.8B from $52.6B QoQ, while gearing declined to 18.7% from 23.2%
• Shell has delivered $5.8B of structural cost reductions since 2022, including $0.7B in H1 2026
• Production declined to 2.46M boe/d, partly reflecting the impact of the Middle East conflict on Qatari volumes
⠀
💬 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐅𝐨𝐜𝐮𝐬
Shell continues to prioritize performance, capital discipline and portfolio simplification while maintaining substantial shareholder distributions.