
Hypoport shares are struggling to find a bottom: After hitting its lowest level in nearly ten years at around 67 EUR in October, the stock of the Berlin-based platform operator—behind Europace—climbed as high as 91.75 EUR, but closed at 83.60 EUR (−3.2%) on Xetra on November 9, 2026. This puts the stock about 40% below its 52-week high of 138.40 EUR and about 87% below its all-time high of 623.47 EUR from 2021. Operationally, Hypoport is delivering what investors want to see: In the first nine months of 2026, revenue rose by 5% to 479.5 million EUR, EBIT jumped 27% to EUR 30.1 million, and the EBIT margin on gross profit climbed from 12.0% to 14.5%. The catch: Europace’s transaction volume in real estate financing is stagnating at 57.34 billion EUR, while the home savings business has plummeted by 15%, and to reach the midpoint of the EBIT forecast of 40 to 55 million EUR, Hypoport would need to nearly double its prior-year profit in the final quarter. Analysts’ average estimate is 140.80 EUR. From a technical analysis perspective, the situation is clear: Only above 95 EUR will a buy signal emerge with recovery potential up to the 130–155 EUR range; if the stock fails to find a bottom, 57.10 EUR becomes a realistic target.
Key Points
- 9M 2026: Revenue 479.5 million EUR (+5%), gross profit of EUR 207.0 million (+5%), EBIT of EUR 30.1 million (+27%), earnings per share of EUR 2.98 (+30%)
- Q3 alone: EBIT up 42% to EUR 10.8 million, gross profit margin at 15.5%
- Europace real estate financing stable at EUR 57.34 billion for 9M, with savings banks (FINMAS +13%) and cooperative banks (GENOPACE +7%) as drivers
- 2026 forecast unchanged: Gross profit of at least EUR 280 million, EBIT of EUR 40 to 55 million—the fourth quarter must deliver
- Analysts: Average price target of 140.80 EUR (five firms, range 82 to 185 EUR)
- Chart levels: Buy signal above 95 EUR, recovery target 130 to 155 EUR, support at 67.32 EUR, downside target 57.10 EUR
What are Hypoport’s current key metrics?
The Hypoport stock closed at EUR 83.60 (−3.24%) on Xetra on November 9, 2026, and is now valued at only about EUR 0.55 billion on the stock market.
Since the beginning of the year, the stock has lost about a third of its value; in October, it hit a low of around 67 EUR—its lowest level in nearly ten years. All prices refer to Xetra trading in euros (ticker HYQ).
What news is currently driving the Hypoport stock?
Three issues are currently driving the Hypoport stock: the nine-month results released on November 9, 2026; stagnating Europace volume in a shrinking financing market; and the question of whether October’s multi-year low marked the bottom.
On the day the final figures were released, the stock turned negative after initial gains and closed 3.2% lower at 83.60 EUR. Rising construction interest rates are having a particularly negative impact: According to Hypoport, the overall market for real estate financing contracted in the second and third quarters. My analysis of Vonovia Aktie.
What does Hypoport management say about the nine-month results?
CEO Ronald Slabke says he is “overall satisfied with the first nine months of 2026” despite the challenging environment: Against the backdrop of declining financing markets, Hypoport has expanded its market share by acquiring new customers.
At the same time, value creation among existing customers has increased. As early as mid-October, Hypoport had stated that the overall market was under temporary pressure due to rising interest rates and high asking prices from sellers, but that it was defending its own volume by gaining market share from savings banks and cooperative banks.
What went well: The margin leverage is taking effect. Gross profit grew by only 5%, but EBIT rose by 27%—and by as much as 42% in the third quarter. The valuation platform VALUE turned a profit for the first time in the third quarter, the insurance segment moved into the black after nine months, and holding costs fell from 12.6 to 10.6 million EUR.
The catch: Volume is barely growing. Real estate financing on Europace is stagnating at EUR 57.34 billion, building savings fell by 15%, and in the Financing Platforms segment, EBIT dropped from EUR 3.8 million to EUR 3.6 million. The press release dated November 9, 2026, does not include a reaffirmation of the annual targets.
Outlook: The forecast from February remains unchanged, most recently reaffirmed on August 10, 2026: gross profit of at least 280 million EUR, EBIT of 40 to 55 million EUR. Mathematically, Hypoport needs at least EUR 9.9 million in EBIT in the fourth quarter to reach the lower end of the range (Q4 2025: approximately EUR 9.4 million); approximately EUR 17 million would be required to reach the midpoint of the forecast. The preliminary annual figures will be released on March 15, 2027.
What does Hypoport do—and how does the financing platform make its money?
Hypoport is a Berlin-based technology company that operates Europace, the leading B2B financing platform for real estate loans in Germany, and earns a share of the revenue from every financing transaction concluded through the platform.
On Europace, advisors from banks, savings banks, cooperative banks, and brokers compare offers from hundreds of lenders and digitally arrange mortgage loans, home savings contracts, and installment loans. In the first nine months of 2026, real estate financing alone totaled 57.34 billion EUR through the platform.
Real Estate & Mortgage Platforms: This segment, by far the most important, encompasses Europace as well as the platforms FINMAS for savings banks, GENOPACE for cooperative banks, and the valuation platform VALUE. After nine months, gross profit rose by 6% to EUR 128.9 million, and EBIT by 10% to EUR 36.0 million.
Financing Platforms: Here, Hypoport operates platforms for the housing sector as well as for corporate and consumer loans. Gross profit grew by 2% to EUR 51.3 million, while EBIT fell to EUR 3.6 million as rising interest rates and uncertainty dampened demand.
Insurance Platforms: With Smart Insur, Hypoport digitizes the management of insurance policies for brokers. Gross profit rose by 5% to EUR 25.0 million, and EBIT turned from −0.4 to +1.1 million.
How Hypoport Makes Money: Hypoport receives a volume-based fee for every transaction processed through its platforms, in addition to software revenue. Because a portion of revenue is passed on to partners as commission, gross profit is the key performance metric. The model scales: As volume increases, costs grow significantly more slowly. This is precisely why the stock is so closely tied to interest rates and the real estate market—and precisely why banks are both customers and partners, as my analysis Deutsche Bank Aktie shows.
Fundamental Analysis: Is the Hypoport Stock Undervalued After the Plunge?
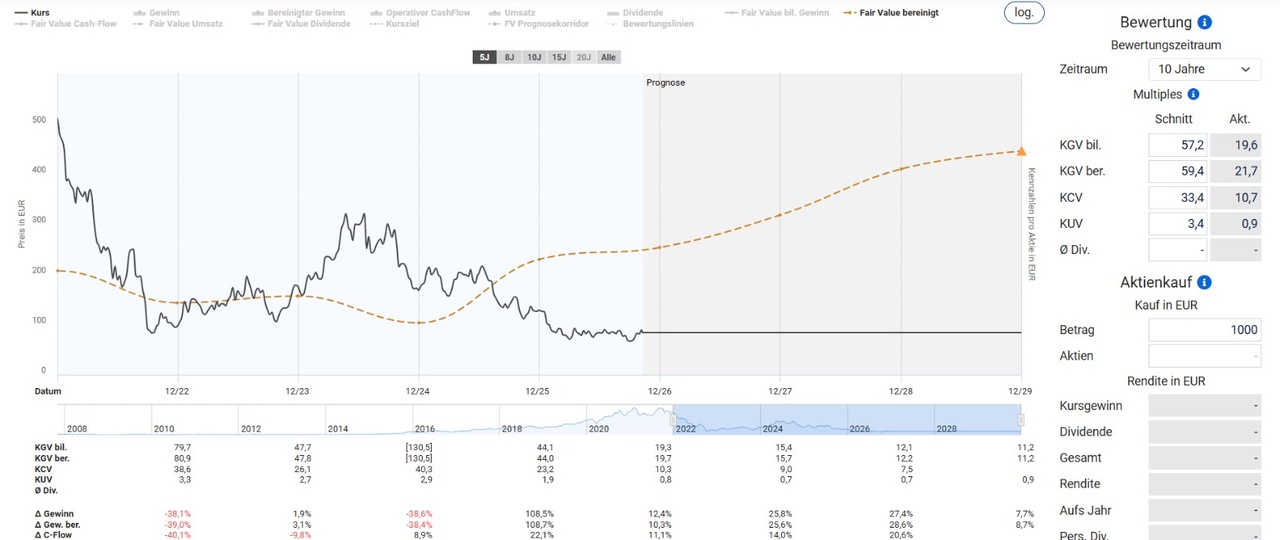
Fundamentally, the Hypoport stock is cheaper than it has been in years: According to Aktienfinder, the adjusted P/E ratio currently stands at 21.7, well below the ten-year average of 59.4.
Based on analyst estimates, it drops to 19.7 for 2026 and 15.7 for 2027, as earnings are expected to grow by more than 25% in 2027. The fair value based on adjusted earnings is around 240 EUR at the end of 2026, which is nearly three times the current price. But be cautious: The historical average P/E ratio stems from the boom years of zero interest rates, when the market paid fantasy prices for platform stocks. A discount is therefore justified—the only question is whether it needs to be this large.
Peer comparison with Scout24 and flatexDEGIRO (adjusted P/E ratio according to Aktienfinder):
- Hypoport: currently 21.7, around 19.7 for 2026, 2027e earnings growth around 26%
- Scout24 (real estate platform): currently 22.4, around 22.1 for 2026
- flatexDEGIRO (online broker): currently 14.2, around 11.1 for 2026
- Price-to-Sales Ratio: Hypoport 0.9, Scout24 8.9
The result is clear: Hypoport is now valued roughly the same as Scout24, even though its earnings are expected to grow significantly faster starting in 2027. In terms of revenue, Hypoport is actually many times cheaper because a large portion of its revenue goes to partners as commissions. Just how mercilessly the stock market is currently punishing software platforms for every dip in growth is also evident in my analysis of SAP Aktie.
Margins: The real progress lies in profitability. The EBIT margin on gross profit rose from 12.0% to 14.5% after nine months, and to 15.5% in the third quarter. Since 2024, Hypoport has nearly tripled its EBIT: from 18 million EUR (2024) to 33 million EUR (2025) and to a projected 40 to 55 million EUR for 2026.
Balance Sheet and Capital Return: Hypoport does not pay dividends and reinvests its profits in its platforms. Between August 17 and October 30, 2026, a share buyback program worth up to 10 million EUR was conducted for employee stock ownership.
The Risk: Hypoport is a leveraged play on the German real estate financing market. If construction interest rates continue to rise or demand remains weak, volume on Europace will stagnate—and then the fuel for the margin story will run out. The midpoint forecast of EUR 47.5 million in EBIT requires a year-over-year increase of approximately 80% in the fourth quarter.
Hypoport Stock Price Targets and 2026 Forecast
Analysts see an average price target of EUR 140.80 for the Hypoport stock, representing about 68% upside potential; however, from a technical analysis perspective, the stock remains in a steep downtrend.
Following the quarterly results, four out of five brokerages have confirmed their “buy” recommendations, though price targets have fallen significantly compared to the summer: Warburg cut its target from 291 to 134 EUR, while Bankhaus Metzler, with a target of 82 EUR, now only recommends “hold.”
Key price levels:
- 52-week high: 138.40 EUR (December 2025)
- Current price: 83.60 EUR (Xetra close on Nov. 9, 2026)
- Buy trigger: 95.06 EUR (red resistance)
- Recovery target: Price range of 130.53 to 154.77 EUR
- Additional level: 330.15 EUR
- Critical downside level: 67.32 EUR (support, bottoming zone)
- Target in the event of a break: 57.10 EUR
- All-time high: 623.47 EUR (2021)
Analysts’ price targets:
- Average price target: 140.80 EUR (average of five firms)
- Berenberg: Buy, 185.00 EUR (September 25, 2026)
- Deutsche Bank Research: Buy, 153.00 EUR (October 27, 2026)
- BNP Paribas Exane: Outperform, 150.00 EUR (October 27, 2026, according to the Hypoport research page)
- Warburg Research: Buy, 134.00 EUR (August 18, 2026)
- Bankhaus Metzler: Hold, 82.00 EUR (September 30, 2026, according to the Hypoport research page)
Chart Analysis:
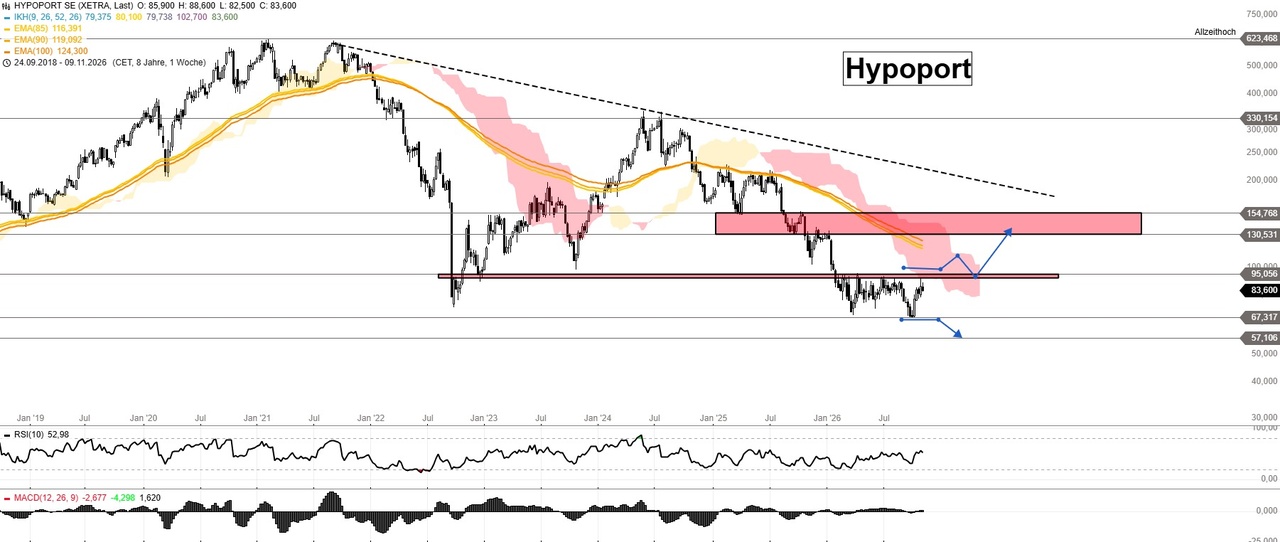
The weekly chart for Hypoport stock tells the story of a dramatic plunge: From its all-time high of 623.47 EUR in 2021, the stock has plummeted by about 87%. Since 2021, a falling downtrend line has pushed down every attempt at a recovery, most recently in the summer of 2024 at the 330.15 EUR level. In early 2026, the stock then broke through the red support zone at 95.06 EUR—since then, the former support line has become a strong resistance level. The price is trading below the Ichimoku cloud and well below the 85-, 90-, and 100-period EMAs, which range between approximately 116 and 124 EUR. Hypoport thus remains in a steep downtrend.
And yet, something is happening: a potential bottom appears to be forming around 67.32 EUR. Here, buyers defended the multi-year low in October, the RSI(10) has recovered to around 53, and the MACD histogram has turned slightly positive. Sellers are losing steam—but this is still only a tentative sign.
The key level is at 95 EUR. If the stock rises above this resistance, that would be a clear buy trigger for me, with further technical recovery trends extending into the price range of 130 to 155 EUR. A pullback to the breakout level of 95 EUR would not be a cause for concern, but rather a typical test of the new support before the path upward clears. This long position would certainly be worth a try—especially since the range lies exactly where most analysts see their price targets.
No one should ignore the downside: If the bottoming process fails and support at 67.32 EUR is sustainably breached, targets of 57.10 EUR would be realistic. That would represent another decline of about 32% from the current price. My analysis of RENK Aktie.
Opportunities and Risks of the Hypoport Stock
Opportunities:
- ✅ Margin leverage: 9M EBIT up 27% with only a 5% increase in gross profit
- ✅ Market share gains among savings banks (FINMAS +13%) and cooperative banks (GENOPACE +7%)
- ✅ Adjusted P/E ratio of around 22 instead of nearly 60 on a ten-year average
- ✅ Analysts’ average target price is 140.80 EUR; four out of five firms recommend buying
- ✅ Potential bottoming out above the support level at EUR 67.32
- ✅ Buy signal above 95 EUR with a recovery target of 130 to 155 EUR
Risks:
- ⚠️ Sharp downtrend since 2021; price below the Ichimoku cloud and EMAs
- ⚠️ Europace volume in real estate financing is stagnating; building savings down 15%
- ⚠️ Rising construction loan rates are dampening the financing market
- ⚠️ Annual forecast not reconfirmed on November 9, 2026; Q4 must deliver strong results
- ⚠️ Financing Platforms segment with declining EBIT
- ⚠️ A break below 67.32 EUR makes 57.10 EUR a realistic possibility
Conclusion: Hypoport Stock—Is It Bottoming Out or Heading for 57 Euros?
Hypoport stock is at a turning point: Above 95 EUR, I’d consider a long position worth a try; if the stock fails to find a bottom, 57.10 EUR becomes a realistic target.
Operationally, Hypoport is delivering a strong margin story—EBIT up 27% after nine months with gross profit up just 5%, market share gains among savings banks and cooperative banks, and a P/E ratio of around 20 instead of the ten-year average of nearly 60. This is offset by stagnant Europace volume, a shrinking financing market, and an annual forecast that was not reaffirmed on November 9, 2026.
From a technical analysis perspective, the roadmap is clear: Hypoport remains in a steep downtrend, but a potential bottom appears to be forming around the 67.32 EUR level. Only a rise above 95 EUR would provide a clear buy signal, with further technical recovery trends extending into the price range of 130 to 155 EUR. If, on the other hand, support at 67.32 EUR is breached, targets of 57.10 EUR would be realistic. Until a breakout occurs, I’m keeping the stock on my watchlist—with the 95-euro mark in my sights.
If you want to see how a stock oscillates between a breakout and a crash—and at which levels that decision is made—you’ll find a very similar scenario in my analysis of BioNTech Aktie.
Sources
- Hypoport SE Investor Relations: Quarterly Reports, Financial Calendar, Ad Hoc Announcements
- Hypoport SE: Research Reports and Analyst Recommendations (as of November 9, 2026)
- Hypoport SE: Insider Information on the 2026 Share Buyback Program (August 12, 2026)
- EQS News: Hypoport Reports Solid Gross Profit Growth and EBIT Increase in the First Nine Months of 2026 (November 9, 2026)
- EQS Ad Hoc: Hypoport SE – Gross Profit Growth and EBIT Increase in the First Nine Months (October 26, 2026)
- EQS News: Hypoport SE – Europace Transaction Volume for the Third Quarter of 2026 (October 15, 2026)
- dpa-AFX via Börsen-Zeitung and DER AKTIONÄR: Hypoport Boosts Profit Thanks to Real Estate Platform (October 27, 2026); Forecast Confirmed (August 10, 2026)
- dpa-AFX Analyser via finanzen.net and finanznachrichten.de: Deutsche Bank (October 27, 2026), Berenberg (September 25, 2026), Warburg Research (August 18, 2026)
- 4investors and Cash-Online: Reports on the nine-month results (November 9, 2026)
- Alpha Vantage and ariva: Xetra price data for HYQ, 52-week high/low, as of Nov. 9, 2026
- Google Trends, Google Ads Keyword Planner (Germany), Google Search Console, as of Nov. 9, 2026
- Stock3: Hypoport SE weekly chart (Xetra, EUR), as of November 9, 2026
- Aktienfinder: Fair value (adjusted earnings), P/E ratio history, and forecasts for Hypoport, Scout24, and flatexDEGIRO, as of November 9, 2026
This is not investment advice—all information is provided solely for financial education purposes.
What do you currently think of $HYQ (-3.57%)?