tonies is growing faster than expected: In the third quarter of 2026, the manufacturer of the Toniebox and its accompanying audio figures increased its revenue by 27.6% to €179.9 million, significantly exceeding the consensus estimate of €171.5 million. The growth is driven by North America, which posted a 42.1% increase and is now the company’s largest market. After nine months, revenue stands at €422.9 million, representing a 33.1% increase. Management confirmed but did not raise its full-year forecast of more than €760 million in revenue with an adjusted EBITDA margin of 9 to 11%. The stock hit a new record high of €14.60 on October 21, 2026, and closed at €13.30 on Xetra on November 12 following the earnings release. From a technical analysis perspective, tonies is in a clear medium-term uptrend, with a procyclical buy signal emerging above €14.60. Analysts have an average price target of €18.31.
Key Points
- Q3 2026: Revenue €179.9 million (+27.6%), consensus €171.5 million
- North America in Q3: +42.1% to €72.7 million; figures: +35.4% to €131.0 million
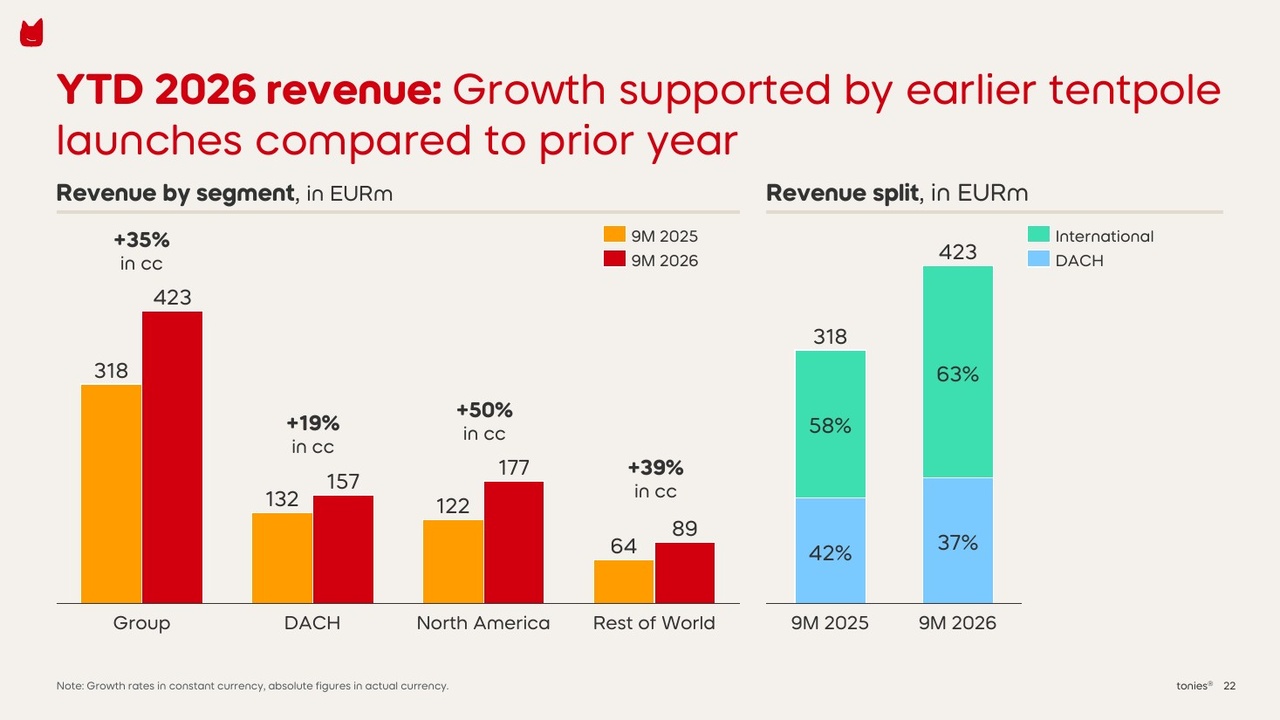
- Nine months: Revenue €422.9 million (+33.1%)
- 2026 forecast confirmed: more than €760 million in revenue, adjusted EBITDA margin of 9 to 11%
- 2030 target: more than €1.4 billion in revenue, adjusted EBITDA margin of 16 to 18%
- Record high of €14.60 on Oct. 21, 2026; Xetra closing price on Nov. 12, 2026: €13.30
- Analysts: Average price target €18.31, range €17.25 to €20.00
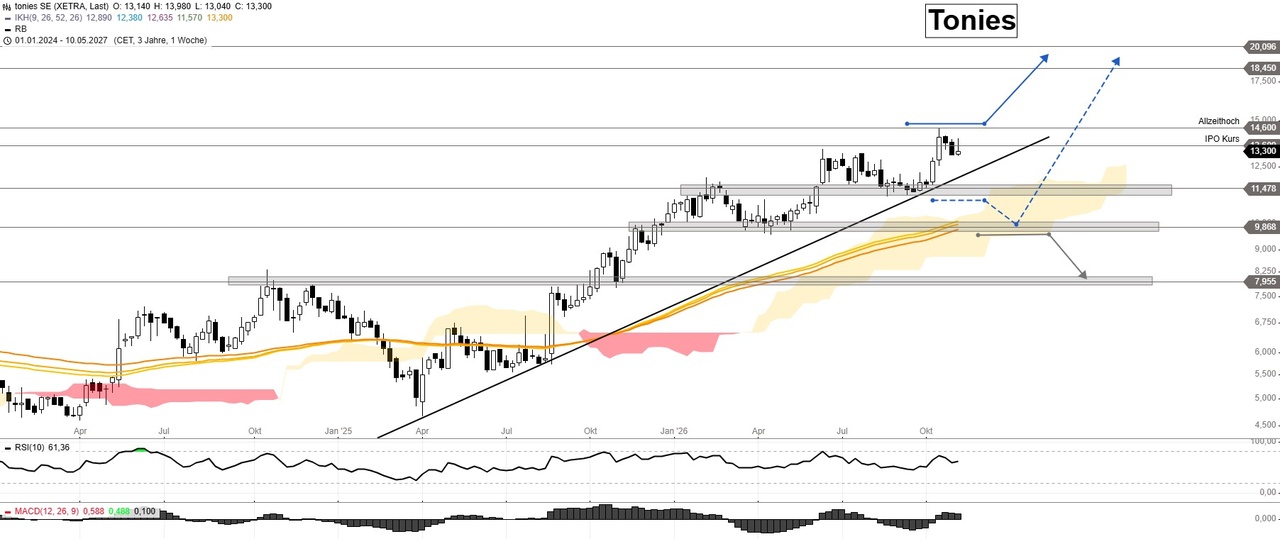
- Chart levels: Buy signal above €14.60, support at €11.47, critical level below €9.80
What are the current key metrics for the tonies stock?
With a market capitalization of approximately €1.69 billion (Xetra closing price as of Nov. 12, 2026), the tonies stock is no longer a bargain: Based on analyst estimates, the P/E ratio for 2026 is around 37 and for 2027 around 23.
Measured against expected revenue of more than €760 million, investors are paying well over double the annual revenue. tonies does not pay a dividend; the company is investing its money in growth and new markets.
- Share price (Xetra: TNIE): €13.30 (closing price on November 12, 2026)
- All-time high: €14.60 (October 21, 2026)
- 52-week low: approximately €7.90 (November 2025)
- Year-to-date performance: approximately +27% (November 12, 2026)
- Market capitalization: approx. €1.69 billion (126.85 million shares) (November 12, 2026)
- Revenue for Q3 2026: €179.9 million (+27.6%) (November 12, 2026)
- Revenue for the first 9 months of 2026: €422.9 million (+33.1%) (November 12, 2026)
- Revenue in North America for the first 9 months of 2026: €177.0 million (+45.3%) (November 12, 2026)
- Revenue for 2025: €630.3 million (+31.2%) (April 14, 2026)
- Adjusted EBITDA for 2025: €54.1 million (margin 8.6%) (April 14, 2026)
- Adjusted EBITDA for H1 2026: €1.8 million (margin 0.7%) (August 20, 2026)
- 2026 Forecast: Revenue > €760 million, adjusted EBITDA margin 9–11% (confirmed Nov. 12, 2026)
- P/E ratio 2026e / 2027e: approx. 37 / approx. 23 (analyst consensus)
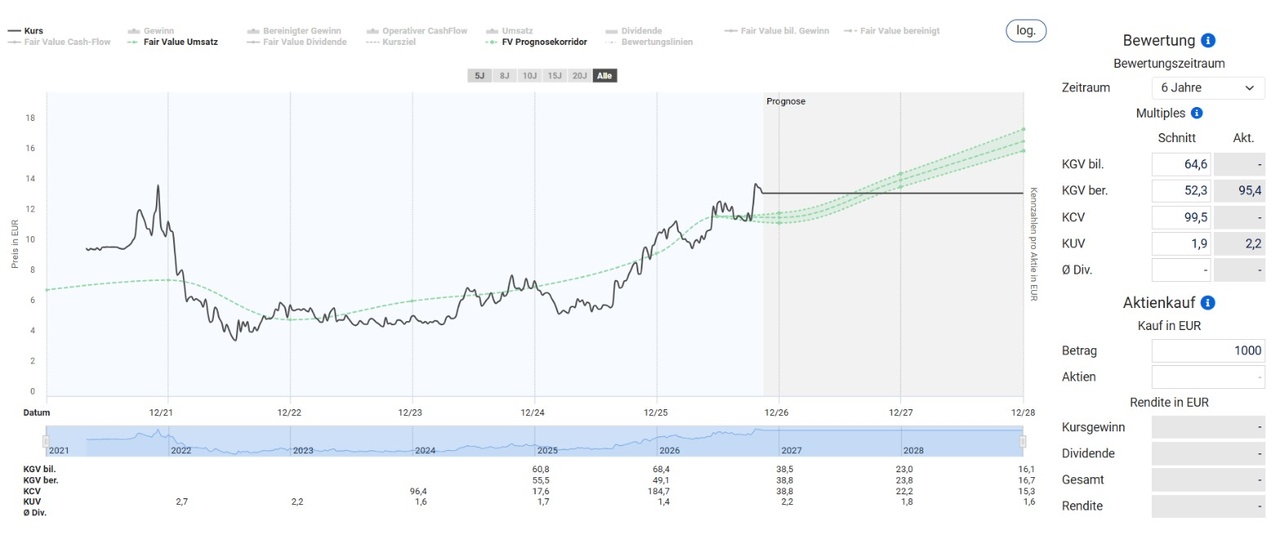
- Fair value at end of 2027 (revenue): approximately €14.22 (average P/S ratio 1.9) (Aktienfinder, Nov. 13, 2026)
- Average analyst price target: €18.31 (+38%), range €17.25–€20.00 (November 13, 2026)
- Dividend: none (—)
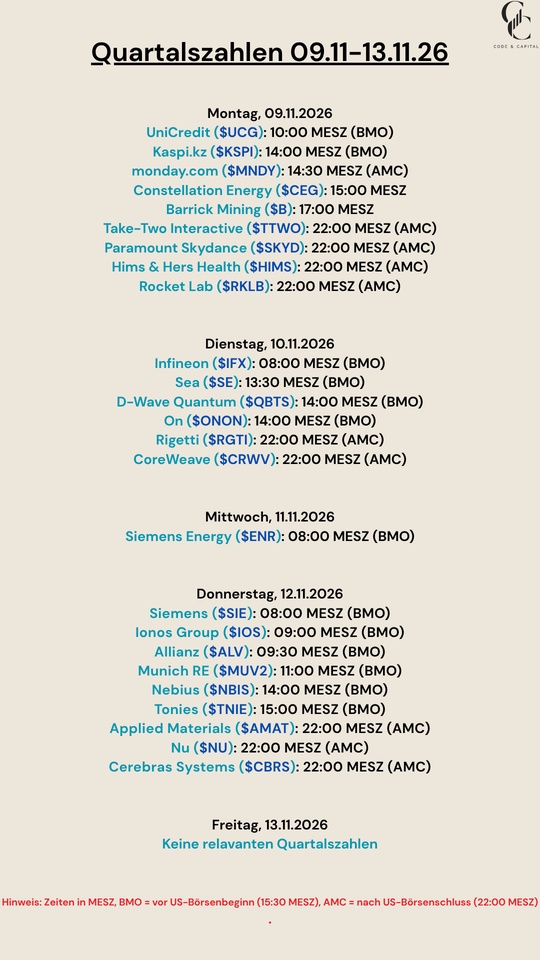
- Next event: Full-Year 2026 Trading Update on February 1, 2027 (tonies IR)
- Index: SDAX (since Dec. 22, 2025) (—)
- WKN / ISIN / Ticker: A3CM2W / LU2333563281 / TNIE (—)
What news is currently driving the tonies stock?
The tonies stock is currently being driven primarily by its strong third quarter—and the question of why the stock fell on earnings day despite a 27.6% increase in revenue.
On November 12, the stock initially opened higher but then turned lower, closing 2.9% lower at €13.30 on Xetra. One reason may be that tonies merely confirmed its full-year forecast rather than raising it. According to the earnings presentation, the earlier launch of key new products shifted revenue from the fourth to the third quarter—after nine months, 56% of the annual forecast has been achieved, leaving 44% to be delivered in the holiday quarter. On the same day, tonies initiated a voluntary recall of the “Helene Fischer – Die schönsten Kinderlieder” figurine due to small parts that could come loose. My analysis of adidas Aktie.
- Nov. 12, 2026 – Q3 well above expectations: Revenue of €179.9 million (+27.6%) instead of the expected €171.5 million; North America +42.1%; figures +35.4%. 2026 forecast confirmed. Stock closes 2.9% lower at €13.30. (Bullish)
- Nov. 12, 2026 – Recall of a Helene Fischer figurine: Voluntary recall due to small parts that can come loose; customers will receive a replacement or refund. Financial impact not quantified. (Neutral)
- October 21, 2026 – New record high at €14.60: Following target price increases by NuWays (€18.50) and Oddo BHF (€17.50), the stock rises above its previous all-time high from December 2021. (Bullish)
- August 20, 2026 – First Half: Strong Growth, Thin Margin: H1 revenue €242.9 million (+38%), adjusted EBITDA only €1.8 million (margin 0.7%), net loss −€27.3 million. Berenberg raises price target to €20. (Neutral)
- June 18, 2026 – Capital Markets Day: 2030 target doubled: More than €1.4 billion in revenue and a 16–18% adjusted EBITDA margin by 2030; at least two new markets per year starting in 2027. (Bullish)
- December 22, 2025 – Inclusion in the SDAX: tonies is added to Deutsche Börse’s small-cap index. (Bullish)
What does tonies’ management say about the quarterly results?
CEO Tobias Wann says tonies is “fully on track, both strategically and operationally” after nine months, while CFO Hansjörg Müller emphasizes that the international growth strategy continues to bear fruit.
tonies did not publish earnings figures in its quarterly report, but the financial position has not changed significantly since the end of June.
What went well: All three regions posted double-digit growth. North America grew by 42.1% to €72.7 million in the third quarter, the Rest of the World by 36.6% to €38.9 million, and the DACH region by 11.4% to €68.3 million. High-margin figures boosted revenue by 35.4% to €131.0 million, while Tonieboxes increased revenue by 12.6% to €43.9 million. The share of international revenue rose to 63% after nine months.
The catch: Despite the strong quarter, the forecast was not raised. Management itself acknowledges in the presentation that the early launch of new products shifted revenue from the fourth quarter to the third, and that the final quarter will face a strong prior-year comparison with the launch of the Toniebox 2. For the crucial Christmas quarter—in which tonies generated roughly half of its annual revenue in 2025—a growth rate of about 8% would suffice on paper. The quarterly report makes no mention of profitability or cash flow. In the first half of the year, the adjusted EBITDA margin was only 0.7%, and cash flow was significantly negative due to inventory buildup ahead of the holiday season.
Outlook: For 2026, tonies expects revenue of more than €760 million, representing currency-adjusted growth of more than 20%; North America is projected to grow by more than 30%. The adjusted EBITDA margin is expected to reach 9 to 11%. By 2030, management aims to double revenue to more than €1.4 billion and enter at least two new countries each year starting in 2027.
What does tonies do, and how does the company make money?
tonies sells the Toniebox, a durable, screen-free audio cube for children, and—most importantly—the accompanying audio figures, which you simply place on the box to play stories, audio plays, and songs.
The company was founded in Düsseldorf in 2013; the holding company, tonies SE, is based in Luxembourg. The Toniebox 2, featuring games via “Tonieplay,” has been available since 2025, and the more affordable Toniebox Lite was added in 2026.
Figures as a Money-Maker: In 2025, tonies generated about 71% of its revenue from the figures (€447.2 million), and only about a quarter from the boxes (€161.2 million). The business model works much like that of printers and ink cartridges: Anyone who owns a box will keep buying new figures over the years—with licenses from Disney, Pokémon, Bluey, and many others. More than 10 million Tonieboxes had been sold by September 2025.
Three regions: North America is the largest market, with €177.0 million in revenue after nine months, ahead of the DACH region (€157.2 million) and the rest of the world, including the United Kingdom, France, and Australia (€88.7 million). The boxes and figures are primarily manufactured in China, with figures also produced in Tunisia. My analysis of how a Chinese hardware manufacturer with its own ecosystem of devices and services is taking the markets by storm is detailed in Xiaomi Aktie.
IPO via a SPAC: tonies went public in 2021 via the SPAC 468 SPAC I, which had been priced at €10.00 per share. Since November 29, 2021, the stock has been traded as tonies SE; the opening price was €12.50. tonies has been part of the SDAX since December 2025.
Revenue by Region for tonies Stock (TNIE), Nine Months of 2026 (as of November 13, 2026) – Source: tonies Investor Relations / Christian Lill
tonies Stock Fundamental Analysis: How Much Is tonies Really Worth?
Fundamentally, tonies is a classic growth stock: Revenue has more than doubled since 2022, but profits are still small and heavily dependent on holiday sales.
For investors, therefore, the key question is whether margins can keep pace with growth.
Growth: Revenue rose from €258.3 million (2022) to €361.0 million (2023) and €480.5 million (2024), reaching €630.3 million in 2025. For 2026, tonies expects more than €760 million; analysts forecast an average of around €781 million, and for 2027, around €945 million.
Margins: Adjusted EBITDA rose to €54.1 million in 2025, with a margin of 8.6%, up from 7.5% in the previous year. The bottom line was a net profit of €13.1 million, corresponding to €0.10 per share. In 2026, the margin is expected to rise to 9–11%, but in the first half of the year it stood at only 0.7% with a net loss of €27.3 million—tonies generates nearly all of its annual earnings in the fourth quarter.
Cash Flow: Free cash flow was negative in 2025 at −€11.9 million because tonies expanded its inventory to accommodate growth. According to NuWays, approximately €64 million flowed out in the first half of 2026. Analysts see this as the company’s key weakness.
Valuation: Based on the analyst consensus for earnings per share (€0.36 for 2026, €0.58 for 2027), the P/E ratio stands at approximately 37 and 23, respectively. Because earnings and cash flows do not yet have a stable track record, the Stock Finder uses revenue as a benchmark for tonies: On average over the last six years, investors paid 1.9 times revenue; currently, the figure is 2.2. Based on revenue estimates from seven analysts, this results in a fair value of approximately €14.22 per share at the end of 2027 (range: €13.76 to €14.64)—slightly above the current price. The valuation is therefore primarily a bet that tonies will achieve its target margin of 16 to 18% by 2030. Just how long a turnaround can take when growth isn’t cooperating is illustrated by Evotec Aktie – where the restructuring is still deep in the red.
Fair Value Valuation of tonies Stock (TNIE) for 2027 (as of Nov. 13, 2026) – Source: Aktienfinder / Christian Lill
tonies Stock Price Targets and Forecast for 2027
Analysts see an average price target of €18.31 for the tonies stock, representing about 38% upside potential—from a technical analysis perspective, a strong buy signal emerges above the record high of €14.60, opening up a target range of €18.45 to €20.10.
As long as the stock holds above €9.80, the uptrend remains intact.
Key price levels:
- All-time high and 52-week high: €14.60 (Oct. 21, 2026)
- Current price: €13.30 (Xetra close Nov. 12, 2026)
- Buy signal: above €14.60
- Target range: €18.45 to €20.10
- Support: €11.47
- Correction target: €9.87
- Critical downside level: €9.80 (below which a correction to €7.95 is expected)
Analyst price targets:
- Average price target: €18.31 (four firms, range €17.25 to €20.00, as of Nov. 13, 2026)
- Berenberg: Buy, €20.00 (August 20, 2026, confirmed September 22, 2026)
- NuWays: Buy, €18.50 (October 21, 2026)
- Oddo BHF: Outperform, €17.50 (October 20, 2026)
- mwb research: Buy, €17.25 (August 20, 2026)
Chart Analysis:
tonies Stock (TNIE) Chart Analysis and Price Targets for 2027 (as of Nov. 13, 2026) – Source: Stock3 / Christian Lill
The tonies stock reached an important milestone in the fall of 2026: The price rose significantly above its initial listing price as tonies SE of €12.50 for the first time and hit a new record high of €14.60 on October 21. After years of trading below these levels, this is a strong signal for early-stage shareholders.
In the medium term, the stock is in a clearly intact uptrend. Since its low in April 2025, it has formed a clean sequence of higher highs and higher lows, supported by a rising trend line. The moving averages are pointing upward, and the price is trading well above the Ichimoku cloud. The indicators also support this picture: The RSI stands at around 61 and still has room to rise, while the MACD is trading above its signal line in positive territory.
The buy signal (blue arrow): A strongly procyclical buy signal will be triggered as soon as the stock sustainably breaks above its record high of €14.60. This would clear the way for the target range between €18.45 and €20.10—representing potential gains of approximately 39% to 51% from the current price.
Where the bulls can remain calm: Bullish market participants currently have little to worry about down to €11.47. A broad support zone runs along that level, where the stock found support on multiple occasions during the spring and summer. Pullbacks down to that level would be nothing unusual within an uptrend.
The indirect scenario (dashed blue arrow): Only a drop below €11.47 would trigger a correction. A possible target would then be the next support zone at €9.87, where the rising moving averages and the upper edge of the Ichimoku cloud converge. From there, a renewed push toward the upside targets would still be possible.
The warning signal (gray arrow): If, on the other hand, the price falls below €9.80, the correction would extend significantly to €7.95. That is the breakout level from the fall of 2024. Only then would the medium-term uptrend be seriously compromised. As long as that is not the case, the upside targets in the range of €18.45 to €20.10 remain possible.
Conclusion: tonies Stock—Is the Next Rally About to Begin?
tonies is growing strongly and is more profitable than it was two years ago; the stock is in an uptrend, just below its all-time high—a breakout above €14.60 would signal the start of the next phase.
Factors working in tonies’ favor include strong growth in North America, the recurring toy figure business, a revenue target of more than €1.4 billion by 2030, and analysts who are unanimously recommending a “buy.” On the other hand, the Nike Aktie —a risk that also looms for tonies, given its production in China.
Factors weighing against the stock include thin margins outside the holiday season, negative cash flow due to inventory buildup, and a valuation with a P/E ratio of around 37 for 2026. From a technical analysis perspective, I consider a strongly procyclical buy signal above €14.60 to be the key; if that occurs, a range of €18.45 to €20.10 is possible. Up to €11.47, the trend remains stable; below €9.80, the correction could extend to €7.95. My analysis of Deutz Aktie.
✅ Opportunities
- Q3 revenue up 27.6% and well above the consensus estimate
- North America grew by 45.3% after nine months and is the largest market
- Recurring figure business accounts for about 71% of revenue
- 2030 target: more than €1.4 billion in revenue and a margin of 16 to 18%
- New markets starting in 2027; Toniebox Lite and Tonieplay as growth drivers
- Buy signal above €14.60, target range €18.45 to €20.10
⚠️ Risks
- 2026 forecast merely confirmed, not raised, despite a strong Q3
- Earnings depend almost entirely on the holiday quarter
- Free cash flow negative due to inventory buildup
- Production is predominantly in China; U.S. tariffs and the dollar exchange rate pose risks
- Valuation at a P/E ratio of around 37 for 2026 is ambitious
- Below €9.80, a correction down to €7.95 looms
Sources
- tonies Investor Relations: Trading Statement for the Third Quarter of 2026 (Nov. 12, 2026)
- tonies Third-Quarter 2026 Earnings Presentation (November 12, 2026)
- tonies Investor Relations: Stock, Shareholder Structure, and Key Figures
- tonies Investor Relations: Financial Calendar
- tonies Press Release: Fiscal Year 2025 (April 14, 2026) and First Half of 2026 (August 20, 2026); Capital Markets Day (June 18, 2026) according to dpa-AFX
- dpa-AFX via finanzen.net, boerse-online, and DER AKTIONÄR: Consensus Q3, analyst reports from Berenberg, NuWays, and mwb research (August 20 to October 21, 2026); finanzen.net: Oddo BHF (October 20, 2026)
- Deutsche Börse (November 29, 2021): Initial listing of tonies SE; tonies IR (April 29, 2021): Placement of 468 SPAC I
- Xetra prices: Alpha Vantage (daily and weekly data through November 12, 2026), investing.com (November 12, 2026)
- Stock3: Weekly chart for tonies SE (Xetra, EUR), as of Nov. 13, 2026
- Aktienfinder: Fair value calculation (revenue) and valuation metrics for tonies, as of November 13, 2026
This is not investment advice—all information is provided solely for financial education purposes.
What do you currently think of $TNIE (-2,07%)?