
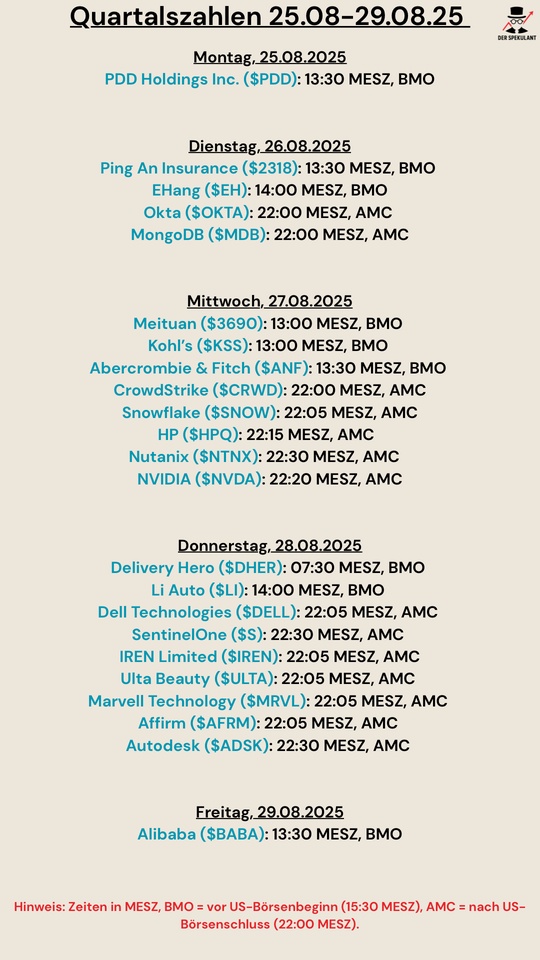
$PDD (-1,62%)
$601318
$EH (+1,66%)
$OKTA (-0,01%)
$MDB (+1,87%)
$3690 (-2,05%)
$KSS (-0,24%)
$ANF
$CRWD (+1,37%)
$SNOW (-0,25%)
$HPQ (+0,21%)
$NTNX (+0,6%)
$NVDA (+1,09%)
$DHER (+1,02%)
$LI (-4,52%)
$DELL (+3,69%)
$S (+1,87%)
$IREN (+2,7%)
$ULTA (+1,75%)
$MRVL (+1,63%)
$AFRM (+1,67%)
$ADSK (-0,05%)
$BABA (-1,52%)
Discussão sobre 3690
Postos
81Ano·
Quartalszahlen 25.08-29.08.25
77


1Ano·
JD.com – Der chinesische E-Commerce-Riese mit Potenzial für 2025?
JD.com – Der chinesische E-Commerce-Riese mit Potenzial für 2025?
JD.com ($9618 (-2,35%)) ist einer der führenden E-Commerce-Anbieter in China und hat sich als ernstzunehmender Konkurrent zu Alibaba etabliert. Nachdem das Unternehmen in den letzten Jahren mit wirtschaftlichen Herausforderungen und regulatorischen Problemen zu kämpfen hatte, stellt sich die Frage: Kann JD.com im Jahr 2025 zu alter Stärke zurückfinden?
Überblick: Was macht JD.com?
JD.com ist ein chinesisches Unternehmen, das ein breites Spektrum an Produkten über seine Plattform verkauft, einschließlich Elektronik, Haushaltswaren und Lebensmitteln. Es betreibt sowohl den traditionellen E-Commerce-Handel als auch ein umfangreiches Logistiknetzwerk, das es ermöglicht, Produkte schneller und effizienter zu liefern.
✅ JD Mall: Die Hauptplattform für den B2C-E-Commerce, die in China einen großen Marktanteil hält.
✅ JD Logistics: Ein führendes Logistikunternehmen, das auch für andere Marken und Plattformen tätig ist.
✅ JD Health & JD Digits: Tochtergesellschaften, die in den Bereichen Gesundheit und digitale Dienstleistungen tätig sind.
✅ Kooperationen mit Walmart und Google: Globale Partnerschaften zur Erweiterung der Reichweite und Innovationskraft.
JD.com setzt auf ein integriertes Geschäftsmodell, das von der Logistik über die Cloud-Dienste bis hin zu digitalen Gesundheitslösungen reicht, was das Unternehmen von anderen Wettbewerbern abhebt.
Konkurrenz: Wer sind die Mitbewerber?
🔸 Alibaba $9988 (-1,63%) (Tmall, Taobao): Der größte E-Commerce-Konkurrent in China mit einer breiteren Marktabdeckung.
🔸 Pinduoduo $PDD (-1,62%)
: Ein aufstrebender Wettbewerber, der sich durch Gruppenkäufe und günstige Preise etabliert hat.
🔸 Amazon $AMZN (+0,95%)
: Auch wenn Amazon in China weniger dominant ist, hat es dennoch eine Präsenz auf dem internationalen Markt, vor allem im Bereich Cloud-Dienste.
🔸 Meituan $3690 (-2,05%)
: Ein weiterer Player im Online-Handel und bei On-Demand-Services, besonders im Bereich Lebensmittellieferung.
JD.com hat den Vorteil, dass es ein starkes Logistiknetzwerk und ein gutes B2B-Geschäft bietet, jedoch wird es weiterhin durch den Wettbewerb und regulatorische Herausforderungen in China belastet.
Chancen: Warum könnte JD.com 2025 ein Comeback erleben?
✅ Starkes Wachstum in Logistik und Cloud: JD Logistics und JD Cloud bieten vielversprechende Wachstumsmöglichkeiten, insbesondere im internationalen Geschäft.
✅ Expansion in ländliche Gebiete: JD.com hat eine starke Präsenz in ländlichen Regionen Chinas und könnte von einer breiteren Urbanisierung und steigender Nachfrage profitieren.
✅ Wiederauflebender E-Commerce-Markt: Trotz der wirtschaftlichen Unsicherheiten wird erwartet, dass der chinesische E-Commerce-Markt langfristig wächst – JD.com könnte davon stark profitieren.
✅ Innovationen in FinTech und Gesundheit: JD.com hat in den letzten Jahren große Schritte im Bereich FinTech und digitale Gesundheitslösungen gemacht. Diese Sektoren könnten in Zukunft stabile Einnahmen liefern.
✅ Reduzierte regulatorische Unsicherheiten: Nach Jahren von regulatorischen Herausforderungen könnte sich die Situation in China stabilisieren, was den Markt für JD.com wieder attraktiv macht.
Risiken: Was könnte JD.com weiterhin belasten?
⚠️ Regulatorische Unsicherheiten: Der chinesische Staat behält immer noch großen Einfluss auf den Markt, und neue Vorschriften könnten JD.com belasten.
⚠️ Wettbewerbsdruck durch Alibaba & Pinduoduo: Die starke Konkurrenz von Alibaba und Pinduoduo bleibt eine große Herausforderung.
⚠️ Konsumschwäche in China: Eine schwache wirtschaftliche Erholung und sinkende Konsumausgaben in China könnten das Wachstum bremsen.
⚠️ Abhängigkeit von B2B: JD.com erzielt einen großen Teil seines Umsatzes im B2B-Bereich. Eine Verlangsamung dieses Marktes könnte die Wachstumsziele beeinträchtigen.
⚠️ Geopolitische Risiken: Spannungen zwischen China und dem Westen könnten sich negativ auf die Geschäftstätigkeit auswirken, insbesondere im internationalen Handel und den Cloud-Diensten.
Fazit: Turnaround-Chance oder Value-Trap?
JD.com hat 2025 das Potenzial, von den Wachstumsbereichen Logistik, Cloud und FinTech zu profitieren. Das Unternehmen hat in den letzten Jahren harte Zeiten durchlebt, aber die Grundlagen sind weiterhin stark. Wenn JD.com seine Marktposition in China halten kann und erfolgreich in neue Geschäftsbereiche expandiert, könnte es ein bemerkenswertes Comeback erleben.
Was denkt ihr? Kann JD.com 2025 wieder durchstarten oder bleibt es weiterhin unter Druck? 🚀
88
1Ano·
Growth stocks 2025
Hello everyone,
I'm currently looking at which stocks could develop wonderfully over the next few years and have enormous growth potential.
As I personally and many others have an investment horizon of over 40 years, I find these stocks quite exciting.
Ideas would be:
$SOFI (-0,5%) SoFi Tech
$TOST (+2,62%) Toast
$MELI (+0,49%) Mercadolibre
$HOOD (+1,22%) Robin Hood
$NU (+0,85%) Nu Holdings
$1810 (-3,05%) Xiaomi
$9868 (-2,78%) XPeng
$3690 (-2,05%) Meituan
$ALB (-0,76%) Albermale
$RKLB (+4,61%) RocketLab
$GRAB (-1,1%) Grab Holdings
What do you think about this topic? And what would be your favorites here?
88
12 Comentários
PewPewPew@PewPewPew
1Ano
•
22
•
1Ano·
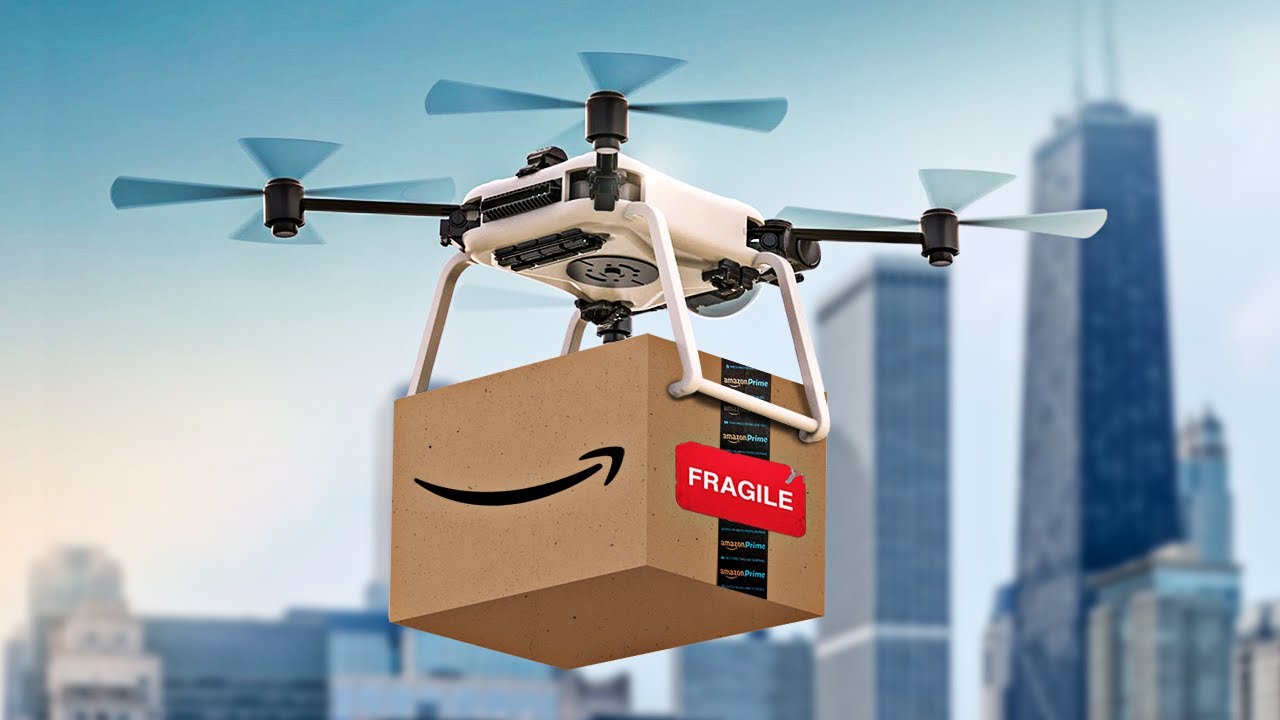
It might be time to invest into drone delivery
The industry is finally at an acceleration point.
In February 2023 U.S. introduced the "Increasing Competitiveness for American Drones Act" which streamlined the approval of licenses for operating drones over American territory.
The advances in Ai have helped develop "detect and avoid" software for autonomous drones.
And at the same time the development of GPUs have allowed these software to be installed on small and light autonomous drones.
It has been 12 years since Jeff Bezos unveiled Amazon's plans to develop "Prime Air" a 30 minutes air drone delivery service. This happened during an episode of the tv show "60 minutes" in November 2013. youtu.be/Fbq6gQVLhWE
Yesterday night I was reading an article about Serve Robotics finance.yahoo.com/nvidia-uber-backing-700-million and I go inspired to make some research into the delivery drone industry. The article talk about $NVDA (+1,09%) and $UBER (+0,06%) investment into $SERV . If you don't want to read the full article, actually @BamBamInvest just made a short summary post of it ( https://getqu.in/RoQSMH/ ).
I investigated on "last mile" delivery also known as "backyard / front yard delivery" . So I will not talk about robotaxi, autonomous truck, ships, airplanes nor I will talk about "micro" delivery drones such as those robots that are already heavily used in hotels in China. All of these surely overlap and compete with each other in the delivery service, but talking about these would defeat the purpose of this post.
So here is my summary of notable drone delivery companies and the current state of the industry.
For starters, there are just two types of delivery drones that are being currently "heavily" deployed for last mile deliveries: with "wings" (UAV) and on wheels.
Delivery on wheels are more complicated and don't see much competition. In U.S. the main player is Serve Robotics ($SERV ). In China is Meituan ( $3690 (-2,05%) ).
Until the beginning of 2024, Amazon ( $AMZN (+0,95%) ) drone delivery service has completely underdelivered 😅 while other players have taken the lead. One of these is Wing, a subsidiary of Google parent company Alphabet ( $GOOG (+1,22%) , $GOOGL (+1,16%) ) wing.com . Wing altogether with DroneUp, flytrex (partner of Causey Aviation Unmanned) and Zipline has completed thousands of commercial air deliveries for Walmart ( $WMT (-0,11%) ).
Wing has the broadest customer base. It operates for Walmart, Doordash ( $DASH (+3,68%) ) Coles groceries ($COL (+0,71%) ), Walgreens ($CVS (+1,31%) ) and different restaurants. It operates mainly in Australia and US.
Zipline is a private company known for making hundreds of thousands of medical air deliveries in Rwanda. flyzipline.com
It's very active in U.S. , a close competitor to Wing.
In December 2022 a partnership with Jumia ( $JMIA (+0%) ) was announced to ease up deliveries in Africa, but since then no further development is known.
DroneUp is also private and basically it's a subsidiary of Walmart. droneupdelivery.com
In the U.S. , until 2023 only 5 drone operators had succeeded at getting air carrier certification from the FAA: Wings ($GOOGL (+1,16%) ), UPS ($UPS (-1,19%) ), Amazon ($AMZN (+0,95%)), Zipline and Causey Aviation Unmanned.
UPS operates wit Matternet's droves. Matternet is a private company. They successfully operate and deliver in dense urban environment.
Causey Aviation Unmanned is a subsidiary of the private company Causey Aviation which is a private jet charter. Causey Aviation Unmanned operates through Flytrex as a provider of Walmart air delivery. Flytrex is also private. causeyaviationunmanned.com
Other notable air drone delivery companies are Ondas holdings ( $ONDS (+1,42%) ) ondas.com . Ondas is known for its military applications in Israel, but it is actually active with Airobotics in the delivery industry airoboticsdrones.com .
The newest Prime Air drone, the MK30, has been unveiled in October 2023 and it's finally being massively deployed bringing Amazon back to the lead.
It’s unlike any other drone being used for package delivery. Faster, quieter, safer, bad weather resistant and very powerful.
At the end of 2024, these new drones replaced the old ones used to deliver in California and Texas. They will also be deployed in a new, third U.S. state and in soon-to-be-revealed destinations in Italy and the UK.
Outside of US, China is leading the way in urban drone deliveries and Meituan ( $3690 (-2,05%) ) is the current market leader both with UAV and drones on wheels.
In Ireland, Manna Aero, has already completed over 100,000 drone deliveries across various locations in Ireland and is trending to hit more than 1,000 daily deliveries in dense urban markets such in Dublin. Manna Aero is a private company manna.aero .
33

2Ano·
Share analysis/share presentation ⬇️
Today we are talking about the company Meituan: $3690 (-2,05%)
What is Meituan and what does it do?
Meituan is a Chinese company that operates a huge online platform. You can find and use various services on this platform. For example, Meituan offers a delivery service where you can order food, groceries or other products and have them delivered. You can also use Meituan to book hotel rooms or buy tickets for events. The platform is very popular in China and offers a convenient way to use various services online.
How many employees does the company have?
Currently, Meituan has a total of around 99,350 employees.
Market capitalization:
Meituan currently has a market capitalization of around 79.01 billion euros.
Strengths of the share:
Some of Meituan's strengths are:
- Broad offering: Meituan offers a variety of services, from delivery services to hotel bookings and ticket sales. This allows you to fulfill many different needs on one platform.
- Efficient delivery services: Meituan is particularly known for its fast and reliable delivery services. You can order food, groceries and other products from the comfort of your own home and they will be delivered to you quickly.
- Large user base: Meituan has a large user base in China, which means that you are used by many people. This means there is a high probability that you will be able to find the services you need quickly and easily.
- User-friendly app: Meituan has a user-friendly app that makes it easy to search, order and use services. The app is intuitively designed and offers a good user experience.
- Good deals and discounts: Meituan often offers attractive deals and discounts for various services. This can help you save money while benefiting from high-quality services.
Weaknesses of the stock:
Some weaknesses of Meituan are:
- Competition: Meituan is in a highly competitive market. There are other companies offering similar services, which leads to high competition.
- Dependence on partners: Meituan relies on partnerships in some areas, e.g. with restaurants or delivery services. Problems or conflicts with these partners could have a negative impact on Meituan's services.
- Logistics challenges: Handling deliveries efficiently can be a challenge, especially in busy areas or at peak times. This could lead to delays or problems with delivery.
- Privacy concerns: As an online platform, Meituan collects data from users to provide personalized services. Some users may have privacy concerns and wonder how their data will be used.
- Dependence on the Chinese market: Meituan mainly operates in China and is therefore heavily dependent on the Chinese market. Changes in the economy or regulatory environment could have an impact on Meituan's business. It is important to note that these are only potential weaknesses and do not necessarily apply to all situations.
A little more about the business model:
Meituan is a Chinese company that operates an online platform offering a wide range of services. Their business model is based on providing local services such as food delivery, restaurant reservations, hotel bookings, movie and event tickets, household services and much more. The main source of their income lies in the commissions they receive from the service providers. For example, when a restaurant orders and delivers food through Meituan, Meituan receives a commission from that restaurant. They also have advertising revenue from businesses that want to advertise on their platform. Meituan uses a combination of an online platform and a mobile app to give their users easy access to services. Users can download the app and register to access a variety of services. They can search for restaurants, read reviews, order food and even track deliveries. The company has also built its own logistics infrastructure to handle deliveries efficiently. They have a fleet of drivers who deliver orders to customers. This allows them to control the quality and speed of deliveries. Meituan has also expanded in recent years and now has a presence in many cities in China. They have expanded their offering to meet the needs of users and strengthen their position in the market. Overall, Meituan's business model is based on providing a convenient platform for local services and generating revenue through commissions and advertising. They have successfully built a large user base and offer a wide range of services to meet the needs of users.
A little more about the industry:
The industry Meituan operates in is referred to as an "online service platform". Meituan is part of the growing sharing economy and offers a wide range of services that make people's everyday lives easier. They focus on local services such as food delivery, hotel bookings and much more. In this industry, they compete with other platforms such as Ele.me and Dianping to offer the best services to users. However, Meituan has established itself as one of the market leaders and is known for its efficiency and variety of services.
When and where was Meituan founded:
Meituan was founded in 2010 in Beijing, China, by Wang Xing. Wang Xing is a well-known Chinese entrepreneur and investor. He founded the company with the aim of creating a platform for local services and making it easier for people to access a variety of services. Since its foundation, Meituan has grown rapidly and has become one of the largest online service platforms in China. The company is headquartered in Beijing and now has a presence in many cities in China. Meituan has established itself as a leading provider of local services and is an important player in the sharing economy.
The aim of Meituan :
Meituan aims to make it easier for people to access a variety of local services and improve their daily lives. The platform offers a wide range of services such as food delivery, hotel bookings, movie and event tickets, household services and much more. The company strives to provide users with convenient and efficient solutions to meet their needs. By utilizing technology and innovation, Meituan aims to make people's lives easier and save them time and effort. The goal is to be a trusted platform where people can find their desired services quickly and conveniently. Meituan aims to improve people's quality of life and help them get the most out of their daily lives.
Your opinion:
Now I would like to hear your opinion on this stock in the comments.
I personally find the company very interesting and will continue to monitor it. It was an unknown company to me until recently, but that's exactly why I wanted to introduce the share to you.
What do you think of Meituan and were you already familiar with this company?
Do you perhaps already have the share in your portfolio?
Please let me know in the comments.
This is of course not investment advice but just my own opinion that I would like to share with you.
44

3Ano·
Hello dear GQLers, and holders of the Tencent Akie $700 (-1,81%) who were affected by the Meituan $3690 (-2,05%) spin-off in January...
This was after all first booked in as a stock dividend, then booked out again and booked in as a spin-off.
Now I noticed that I was charged taxes after step 1, which I was not refunded after derecognition. Here I would have expected a loss in the full amount of the derecognition to recover the tax paid.
The spin-off was then booked as such and the original cost price was split in proportion to the split.
This means that I also pay tax again on the sale😱.
Did this happen to you guys as well and how did you react? Have you contacted your broker?
Or do I have a thinking error here and this is correct?
This is what happened with Smartbroker and TR.
11
4 Comentários
3Ano
Hmm I only got JD $9618 booked, no MeiTuan. Cost price Tencent is still where it was.
•
11
•


Títulos em alta
Principais criadores desta semana
Dados tempo real da LSX · Dados financeiros e EOD da FactSet