
so that $BTC (-5,28%) be able to buy more.
Fidelity US Quality Income ETF
ETP
ETP
ISIN: IE00BYXVGX24
Ticker: FUSD
IE00BYXVGX24
FUSD
Price
Discussione su FUSD
Messaggi
15

1Mes·
And the Winner Is: The Tax Office
On top of that, they’re going to adjust the 2022 taxes.
Well, in that case, bye $FUSD (-1,85%) . I find it astonishing that they’re actually charging interest on the back payment. So, looking back, the severance pay from my old employer ends up being a bit less. But that’s life.
Well, will I still see the 300K this year? The portfolio should still manage a few percentage points of gains by the end of the year. But the upcoming midterms could, of course, work against that (or in its favor—who knows).
1111

1Anno·
Streamlining the portfolio - what would you do?
Dear Community,
Yesterday you were able to help me quickly and effectively. I sold the tiny positions $MATIC (-4,33%) with a considerable loss and $ETH (-3,51%) with a small profit and set up a weekly savings plan on $BTC (-5,28%) set up a weekly savings plan.
In order to simplify and streamline the portfolio even further, I now have the following question for you...
To help you understand my portfolio better, here is a brief explanation:
The main portfolio (currently approx. 150k) is a core-satellite portfolio with 56% $IWDA (-2,7%) , 20% $GGRP (-1,86%) , 12% $WSML (-2,03%) and 12% $XMME (-5,04%) .
With just under 20k is still the $CSPX (-2,94%) in the portfolio.
I have also been holding a separate div growth portfolio (currently approx. 34k) with these stocks for some time:
$MMM (-0,28%) approx. 1500€
$MSFT (-2,95%) approx. 1400€
$ABT (-1,22%) approx. 3300€
$JNJ (+1,54%) approx. 2800€
$PEP (+0,8%) approx. 2700€
$PG (+0,62%) approx. 3300€
$TDIV (-0,52%) approx. 3900€
$WQDS (-1,64%) approx. 3850€
$FGEQ (-1,8%) approx. 3800€
$VWRL (-2,84%) approx. 3750€
$FUSD (-1,85%) approx. 3750€
I save the ETF fraction constantly, nothing should or will change.
I'm just wondering how I should structure the ratio of individual stocks from now on. Should I increase all individual stocks to 5000€ per position or all stocks except Microsoft to 6k? Any other suggestions or ideas? If I simply leave the individual stocks untouched, the money would go into the div ETFs in tranches.
Total TER at 0.22 (which is quite acceptable for me) - and the overlaps are known and also okay for me 😄
Once again, thank you from the bottom of my heart and have a nice rest of Sunday 😎
Best regards
EvD
77
1 CommentoWhat I would do in your position is to maybe merge FGEQ and FUSD into one of them. You already have TDIV als a world ETF. Maybe less options could provide similar results?
You could also merge your world ETF's into one?
Im not a fan of MMM to be honest. Low ROI. Might be good to ditch it and funnel the money into one of the dividend ETF's instead.
Maybe that could be a start?
You could also merge your world ETF's into one?
Im not a fan of MMM to be honest. Low ROI. Might be good to ditch it and funnel the money into one of the dividend ETF's instead.
Maybe that could be a start?
••

1Anno·
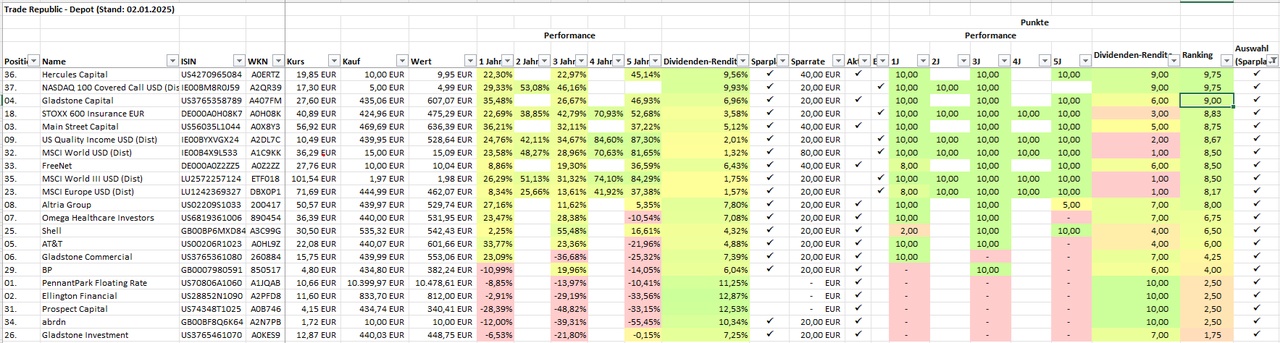
Conversion of my depot from Q2 2025!!!
Thank you for your constructive tips, suggestions and criticism!!! 👍🏻👌🏻 (@Chucky075 , @DADlikesCRYPTO , @Aktienmasseur , @Meikl_22 , @Dividenden-Sammler , @Berliner_Weltenbummler , @Epi)
I sat down and picked my portfolio apart. I evaluated each stock & ETF. I took a close look at the performance and dividend yield of the individual stocks and rated them according to points. Based on this points plan, I selected 6 ETFs for the new portfolio.
From 22 ETF titles, only 6 ETFs remain. I have selected the following ETFs:
- $HMWO (-2,67%)
EUR 460.00 from the savings rate (approx. 82.14%)- $AHYQ (-2,58%)
EUR 40.00 from the savings rate (approx. 7.14%)- $FUSD (-1,85%)
EUR 40.00 from the savings rate (approx. 7.14 %)- $EXH5 (-0,71%)
EUR 40.00 from the savings rate (approx. 7.14 %)- $XIEE (-1,93%)
EUR 40.00 of the savings installment (approx. 7.14 %)- $QYLE (-2,82%)
EUR 40.00 from the savings installment (approx. 7.14 %)
All shares remain in place and are saved through savings plans. Furthermore, I have decided to leave the remaining 16 ETFs in the portfolio, but not to save any more.
The allocation of the portfolio should consist of 70% ETFs and 30% individual shares. The savings installment is EUR 800.00 per month. EUR 240.00 will be invested in individual shares and EUR 560.00 in the above-mentioned ETFs.
What do you think?
Do you have any tips or ideas?
Of course, I hope I've found the right approach now. 🙈🙊
1Anno·
I would appreciate some constructive help!
I have been investing myself since 2013 and started with individual shares and options (leverage products). In my youthful recklessness, I had to learn the hard way. Fortunately, I have been able to recoup my losses very well over the years.
For this reason, I have steered clear of options since 2014 and now only invest in individual shares and ETFs.
In 2023, I started to set up a portfolio for my retirement provision (see below). For this reason, I liquidated my old portfolio with good profits and reinvested them in the new portfolio.
The new portfolio is saved monthly in the amount of EUR 800.00 through savings plans. Some of you are probably wondering about the large position $PFLT (-2,84%). I have held this single share since the beginning and it offers a good cash flow with few price fluctuations.
I follow a dividend strategy myself, so I always have some liquid funds available and can allocate them better to the individual positions.
The position $PSEC (+0,52%) will not continue to be held after a dividend cut.
It's not the best portfolio. But so far I'm satisfied. Nevertheless, I would be very happy to receive help and tips from you. ☺️
Thank you already for your feedback!!! 👌🏻👍🏻
31Posizioni
24.961,29 €
4,25%
33
18 Commenti
1Anno
I find it difficult to judge. It's like a friend asking you whether his new car should have 2 or 4 doors. How would you know? You'll have to ask him what he intends to do with the car and what his expectations are.
So: what are you interested in? Max return? Min max drawdown? Min vola? What is your goal, what is your risk profile?
Without everything, I would always recommend the Epi portfolio: 60% world AG, 20% gold, 20% BTC. Above-average return with average risk. Unfortunately, your suggestions have neither. 🤷
So: what are you interested in? Max return? Min max drawdown? Min vola? What is your goal, what is your risk profile?
Without everything, I would always recommend the Epi portfolio: 60% world AG, 20% gold, 20% BTC. Above-average return with average risk. Unfortunately, your suggestions have neither. 🤷
•
33
•
1Anno·
How I invest at the age of 18
Hi, my name is Max, I'm 18 years old and I'm interested in social media and the stock market.
That's exactly why I'd like to document my financial career on Getquin from now on and talk about it with you. As you can probably tell from the name, my goal is to retire at the age of 50. I would like to make this possible through my share portfolio. Thanks to an inheritance, I had the opportunity to skip the hard road to the first €100,000. However, as I was only 15 years old at the time I found out about the inheritance, I had a lot to learn first. Now I'm 18 years old and already know a bit more. Over time, the stock market has become my hobby and hardly a day goes by when I don't spend time with it.
How it all began
As already mentioned, my interest in the stock market was triggered by the inheritance I received in 2019. Since the deceased relative also had a great interest in the stock market and had invested very successfully for many years, my father thought it would certainly be in his interest if I invested the money too. Fortunately, my father is also very experienced in the stock market, so he was able to explain a lot to me. So it wasn't long before I bought my first ETF with him. This was classically the $IWDA (-2,7%) . I also bought a fund for the Asian region $JQ8Y72 . At the time, this was a recommendation from a friend's bank. However, I sold this fund at some point with a loss of around 25%. That wasn't the best start, of course, but it did teach me how to deal with losses. In those early days, I learned a lot about the stock market from YouTube, but also from other platforms such as Der Aktionär and Finanzen100.
The first individual shares were added in 2023. That was back then $GOOGL (-1,95%) and $DHL (-3,32%) . This was followed by other tech giants such as $AMZN (-3,46%) , $MSFT (-2,95%) and $AAPL (-1,66%) . I now have 17 different individual stocks. Looking at my portfolio, most of them will probably be familiar to you, but there are also some smaller stocks like $EUZ (-2,73%) , $NHH and $LNN (-3,9%) I bought because I find them exciting for the future.
Past and future
Fortunately, my portfolio has performed really well in recent years, in my opinion. This year, too, I am going into the new year with around 20%. Tech stocks in particular have performed strongly and generated decent returns. As I am very optimistic about the tech giants for the next few years, I will continue to hold them in my ETFs despite the doubling. As things stand today, however, I have 2 positions that I would like to change. $DHL (-3,32%) will probably be the first stock to leave my portfolio. Personally, I just don't have the feeling that the company is developing as strongly as many of my other shares. Of course the DHL share is great as a dividend stock, but I want to focus on growth first. That's exactly why I'm going to $GGRP (-1,86%) reallocation. The current replacement is the $FUSD (-1,85%) . I like the quality focus behind these ETFs, but I don't need GGRP's shifted focus on dividend stocks, as I don't really care about dividends at the moment.
In September 2025, I will start my apprenticeship as a bank clerk. From then on, I plan to finally set up my first savings plan. As I'll still be living at home at this point, it should be easy to save a high proportion of my trainee salary. But I'm also making sure that it's not too high - after all, I don't want my quality of life to suffer because of my savings.
Building up additional income
I have been very interested in social media since 2020. When I was 14 years old, I started an Instagram page and reached over 25,000 subscribers within 1-2 years. During this time, I was doing really well financially and I experienced some really great things. For example, I raffled off 120 liters of beer to my community with a brewery. But I'll write a post about that in my subscriber feed soon. After all, the whole thing doesn't really have anything to do with the stock market, which is why I don't want to burden the homepage with it. However, if any of you are still interested, feel free to follow me and read the story soon.
There I will also explain again why I can no longer use the site.
I'm currently trying my hand at YouTube. I'm using artificial intelligence to create videos in the hotel niche. The results are surprisingly good. More on that soon ;)
I'm also currently trying to build up my reach on Instagram. I recently opened an account on Instagram, which should address the same topics as this Getquin account. If you are interested, you are of course welcome to drop by. I'll try to add the link to the account here:
Generation Aktienrente 📈| Vermögensaufbau mit 18 (@aktienrente.mit.50) • Instagram-Fotos und -Videos
With the help of these projects, I hope to be able to build up a more or less passive income in the future, which I can then put directly into my share portfolio. However, to be honest, I also enjoy them as they are, which is why an additional income is not absolutely necessary.
Nevertheless, I will upload regular updates to my feed, which will document my current projects and their developments in detail.
End
This brings us to the end of my first article. I hope I have been able to arouse the interest of at least a few of you and would of course be delighted to receive feedback and suggestions for improving my portfolio and my plans.
I wish you all a happy new year!
20Posizioni
134.046,12 €
33,63%
6666
21 Commenti
1Anno
Welcome Max :) I'm looking forward to further contributions! A happy new year to you too 📈
•
88
•
1Anno·
Tonight I also triggered a limit order at $BTC (-5,28%) triggered a limit order. A first smaller partial tranche has been sold. Everything is going according to plan. I have even revised the targets announced in my #krypto -I have even adjusted some of the BTC targets announced in my post upwards. This means that the limit order was triggered at around USD 106,500 / EUR 99,000. Over USD 10,000 more than planned. The order, which I also placed with a lot of gut feeling after my analysis, happens to be as good as the nightly top 🥰
The next tranche is at 104,000 EUR / 109,300 USD.
Even though my planning and analysis is based on USD prices for crypto, I have set the limit orders in EUR prices.
I am now also publishing what the profits and stakes will be reinvested in. The exact securities I am looking at have not yet been explicitly mentioned.
So far, investments have been made in $HSBA (-3,92%) from the proceeds of $XRP (-4,48%) , $LINK (-5,76%) and the first tranche of $UNI (-4,04%) -sales.
From today's first tranche of $BTC (-5,28%) -sales, I entered $SHEL (+0,11%) I have entered.
What else will come according to plan? $BP. (-0,47%) As a single share. I would then have 3 shares to cover the third month of each quarter with distributions in a separate portfolio. I want to cover the first two months with ETFs, including the first month with either the $EXSB (-1,32%) or (and) $EXX5 (-0,01%) and the second month with the $FUSD (-1,85%) . Will there be any overlaps with my main or one of the two old ETF portfolios in terms of the composition of the securities? For sure! But that doesn't matter to me, as I consider this portfolio, in which the crypto stakes and profits are invested, separately. As you can see from my articles, this is all about building up the basis, the dividends from which I will then use to build up new crypto holdings in the coming bear market so that I don't have to draw on my net salary. This is because the net salary is firmly earmarked for the regular savings plans and the distributions from the main and old portfolios.
Based on the current prices, I think that my second BTC tranche will be the next to fall. The altcoin season should start very soon. I can hardly wait $BCH (-4,77%) , $LTC (-5,95%) , $SOL (-5,26%) , $DOT (-6,51%) , , the rest $UNI (-4,04%) and $MATIC (-4,33%) to finally get rid of it. But I think it will be most exciting with the higher planned tranches at $BTC (-5,28%) and $ETH (-3,51%) .
1616


2Anno·
Hi everyone, I am investing in 3 ETFs $FUSD (-1,85%)
$TDIV (-0,52%)
$IWDA (-2,7%) .
My idea is to diversify the portfolio and reinvest the dividends. Instead of $FUSD (-1,85%), I could use $FUSA (-1,83%) but in the future, it will be easier to use the dividends if I stop reinvesting it.
Should I change any of those ETFs, or my choice is good enough for a long period of 10-20 years?
11
4 CommentiUtente eliminato
2Anno
Il commento è stato cancellato
2Anno·
Hi GetQuin community,
I'm happy with my portfolio and results so far, but always on the lookout for improvements.
This year i've been adding to 2 dividend ETF's : $TDIV (-0,52%) and $FUSD (-1,85%) . Both are excellent choices and allign with my goals: building a safe, robust dividend portfolio that will last for years without dividend cuts. I also keep in mind to choose ETF's with a good CAGR.
The challenge i'm currently exploring is to find an European dividend ETF that has low cost and raises its dividend every year (good CAGR). Most of my stocks and ETF's focus on the USA. If possible I would like to add more diversification by adding European stocks.
It's quite difficult to find well researched articles on dividend ETF's that focus on the European market. I hope the community can assist in finding the right choices.
So far I've found these options:
Any tips / advice would be welcome :)
(I'm based in the Netherlands. TDIV has a slight tax advantage for me considering the dutch domicille.)
13Posizioni
45,77%
33
2Anno·
Swarm knowledge
Hey guys,
Can one of you tell me why I can't make one-off payments on Scalable Capital $FUSD (-1,85%) but can apparently only buy via a savings plan.
The sell button lights up normally and I can sell, but I can't press the buy button.
Thank you very much in advance 😊
9 Commenti

This was also the case with the Global a few weeks ago. After a few days it worked again
•
11
•
2Anno·
Why is the $FGEQ (-1,8%) in contrast to the $FUSD (-1,85%) so favored ? especially when many use it as an addition to an $VWRL (-2,84%) which already has a good diversification as All World. Therefore the $FUSD (-1,85%) should be considered "more sensible" as an addition due to its performance, or am I missing something ?
22
6 Commenti
2Anno
•
33
•Titoli di tendenza
I migliori creatori della settimana
Dati LSX · Dati fondamentali e di fine giornata da FactSet