Source
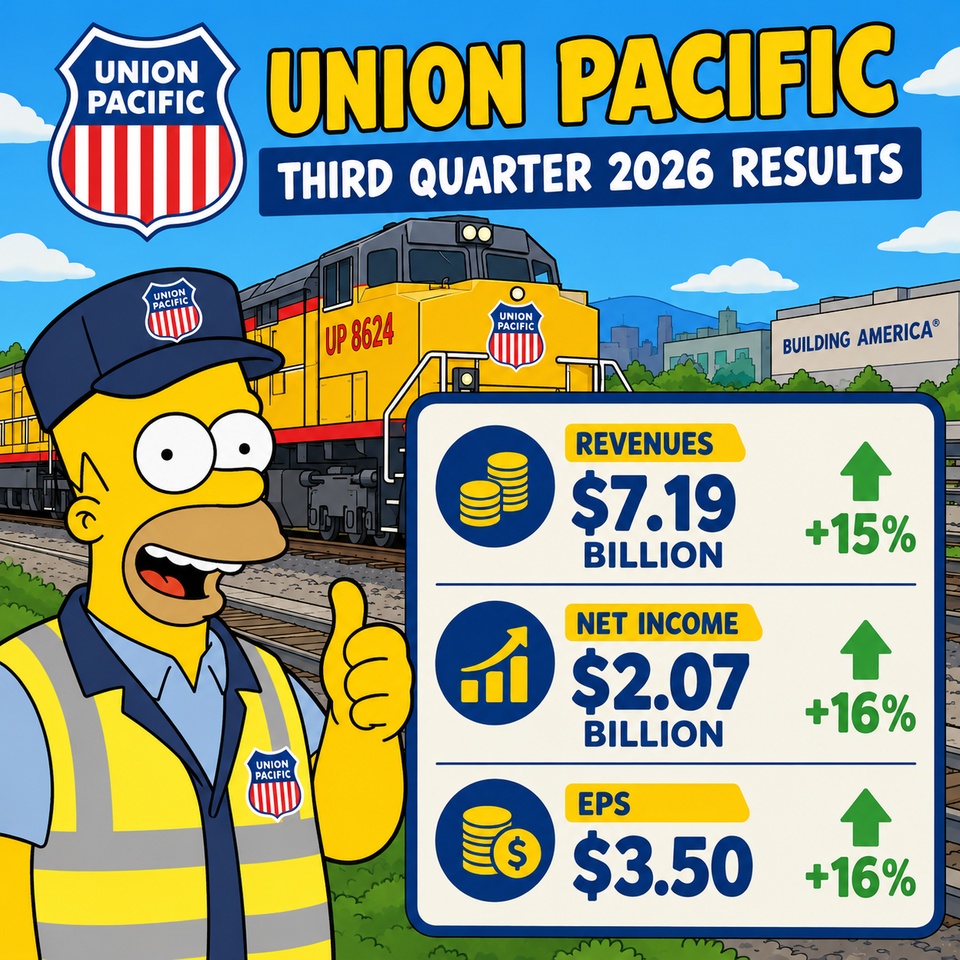
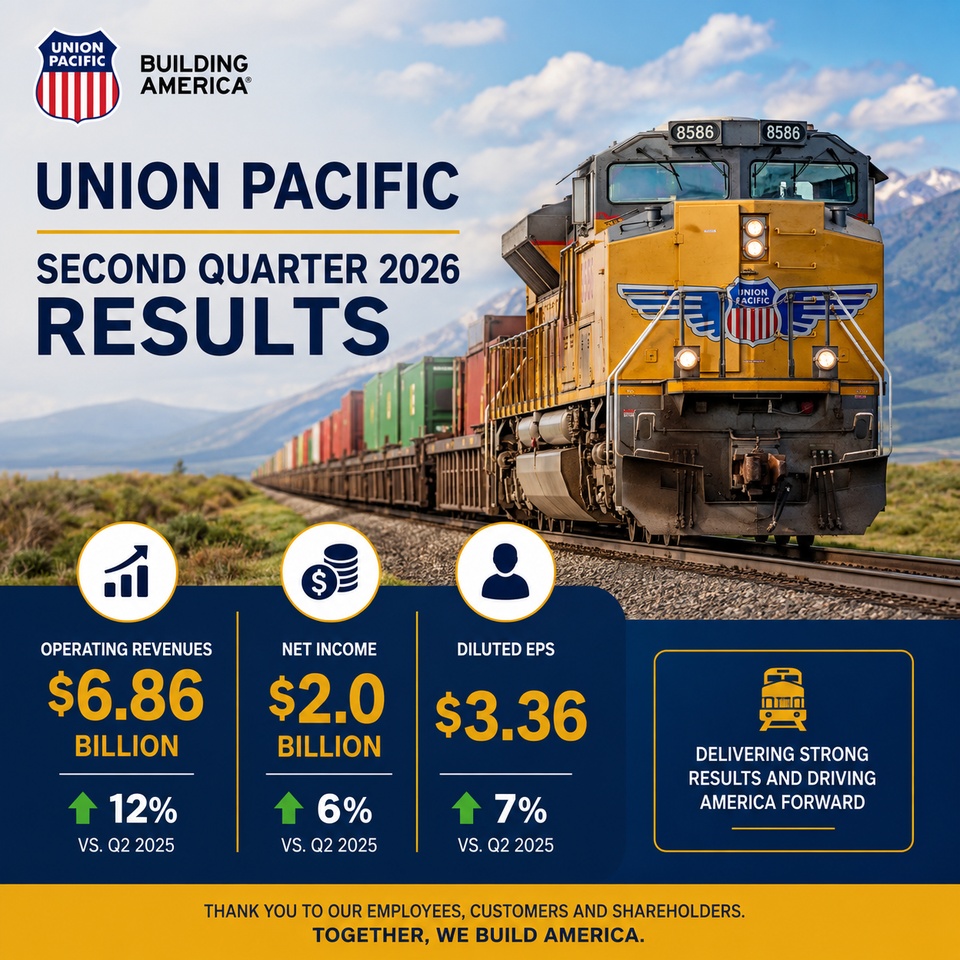
https://investor.unionpacific.com/static-files/6f16f7a4-3c9f-496a-8eb2-17944d5d6c65
Puestos
64Good evening, everyone,
Here's another post from the "Boring DDepot" section :)
I recently rebalanced my portfolio again and sold off $QCOM (+2,97 %) & $WFG (-0,04 %) . I invested the freed-up funds in $MSFT (+0,67 %)
$V (-1,98 %) & $JPM (+0,96 %) since these are long-term positions.
With $QCOM (+2,97 %) , I’d been hoping for better short-term prospects, but those didn’t really materialize, so the money $MSFT (+0,67 %) .
With $WFG (-0,04 %) I sold one of my earliest positions; I’d entered it at a pretty bad time, so I exited with a slight loss for now. However, I may re-enter this position if the wood commodity recovers cyclically and, potentially, demand in home construction rises—that’s what I had actually been speculating on, but it seems it will take a little while longer.
Hopefully, the loss pool has had enough for now, and I’m constantly learning :)
I currently have a savings plan in place for $VWRL (+1 %)
$TDIV (-0,1 %)
$WGLD (+1,45 %) and $BTC (-0,1 %)
I still have some capital available, but I’m not quite sure yet where or how I’ll invest it. The positions in $MSFT (+0,67 %) and $V (-1,98 %) for now, unless they become cheap enough. I’m undecided whether the other stocks are worth adding to; if anything, I’d like to snag another 2 shares of $ALV (+0,65 %) , but they’re pretty expensive right now.
My watchlist currently includes things like
My portfolio is mainly focused on high-quality, “boring” companies; the goal is to generate cash flow right from the start, and I want to feel comfortable with it. The investment horizon is generally long-term—more than 20–30 years—but I also want to start seeing some returns now. Probably not for most people here, but I’m very happy with it right now. Let’s see how the journey continues—I’ll probably wait until the start of next week for now.
I’m always open to feedback, tips, or stocks that would be a good fit here :)

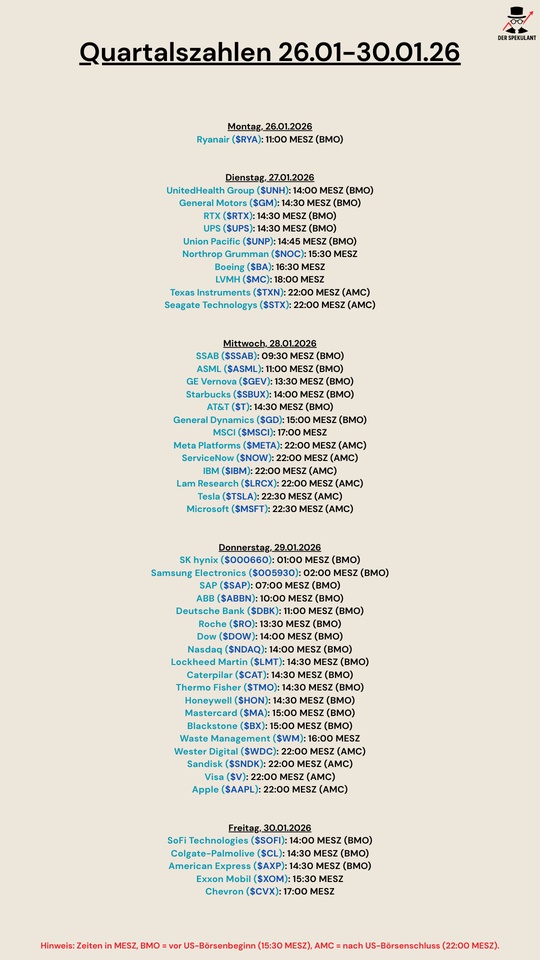
$RYA (+1,48 %)
$UNH (+0,52 %)
$GM (+6,37 %)
$RTX (-1,16 %)
$UPS (+6,12 %)
$UNP (+1,82 %)
$NOC (-2,23 %)
$BA (-10,26 %)
$MC (+1,28 %)
$TXN (+2,59 %)
$STX (-3,09 %)
$SSAB A (+2,19 %)
$ASML (+3,28 %)
$GEV (+5,12 %)
$SBUX (+0,89 %)
$T (+1,02 %)
$GD (-0,41 %)
$MSCI (-2,13 %)
$META (-1,29 %)
$NOW (-1,18 %)
$IBM (-0,74 %)
$LRCX (+1,51 %)
$TSLA (+4,58 %)
$MSFT (+0,67 %)
$000660
$005930
$SAP (-0,08 %)
$ABBN (+2,86 %)
$DBK (+0,8 %)
$ROG (+0,47 %)
$DOW (-0,23 %)
$NDAQ (+0,21 %)
$LMT (-0,81 %)
$CAT (+3,55 %)
$TMO (+2,36 %)
$HON (+0,16 %)
$MA (-0,18 %)
$BX (-1,22 %)
$WM (-2 %)
$WDC (+5,15 %)
$SNDK (+3,56 %)
$V (-1,98 %)
$AAPL (+1,44 %)
$SOFI (+14,25 %)
$CL (-0,95 %)
$AXP (+0,02 %)
$XOM (-2,17 %)
$CVX (-1,31 %)

"Jan 16 (Reuters) - The U.S. Surface Transportation Board on Friday sent back Union Pacific’s $UNP (+1,82 %) proposed $85 billion merger with Norfolk Southern $NSC (+2,66 %) for revision, saying it lacked required information, as part of a review in which the U.S. transport regulator will define what enhanced competition means under tougher merger rules adopted in 2001.
The STB ruled the December application incomplete, citing missing projections of market share and impacts on competition. The board rejected the filing without prejudice, allowing the railroads to refile once the deficiencies are addressed."
www.reuters.com/business/us-rail-regulator-says-union-pacific-norfolk-southern-merger-filing-incomplete-2026-01-16/
$ (-0,61 %)TYL (-0,61 %)
$GE (+3,88 %)
$GD (-0,41 %)
$CHRW (+2,89 %)
$ROL (-2 %)
$TW (+0,41 %)
$CSGP (-14,76 %)
$RKT (-5,56 %)
$CLX (+0,86 %)
$ROST (-1,3 %)
$FAST (-1,22 %)
$CSCO (+1,7 %)
$YUMC (+0 %)
$KOF (-1,78 %)
$ORLY (-0,91 %)
$KO (-1,07 %)
$RY (+0,7 %)
$MDLZ (+0,05 %)
$IMBBY (+0 %)
$A (+1,29 %)
$IDXX (-1,14 %)
$SONY (-0,86 %)
$MSCI (-2,13 %)
$SYY (+0,48 %)
$VLTO WI (+0,27 %)
$DPZ (+1,08 %)
$IDEX (-1,86 %)
$VRSN (-1,1 %)
$COST (-0,85 %)
$ITT (+2,28 %)
$SHW (-1,76 %)
$EPD
$SIE (+2,11 %)
$CP (+1,83 %)
$CTAS (-4,55 %)
$ROG (+0,47 %)
$BK (+0,76 %)
$CNR (+2,24 %)
$PM (+0,75 %)
$TSM (+3,09 %)
$ITW (+0,18 %)
$APD (+1,25 %)
$PG (-0,08 %)
$AAPL (+1,44 %)
$BAC (+0,68 %)
$CPB (+0,92 %)
$VRSK (-3,99 %)
$HSY (-2 %)
$GWRE (-7,65 %)
$HII (+0,8 %)
$GSK (+0,59 %)
$SBUX (+0,89 %)
$ALLE (+1,68 %)
$INTU (-2,07 %)
$MSI (+0 %)
$GWW (-1,79 %)
$UNP (+1,82 %)
$WCN (-2,13 %)
$WM (-2 %)
$NOC (-2,23 %)
$CAT (+3,55 %)
$PAYX (-5,01 %)
$ADP (-1,5 %)
$MCO (-1,96 %)
$SPGI (-0,12 %)
$NDSN (+1,15 %)
$WMT (-0,27 %)
$OTIS (-0,24 %)
$CL (-0,95 %)
Best Companies to Own: Methodology
The companies on this list are covered by Morningstar Research Services’ equity analysts and have shares available to US investors. This means that Morningstar equity analysts have calculated fair value estimates for the shares of the companies that trade on US exchanges. As a result, most of the companies on this list are based in the US.
Within that coverage list, the best companies meet the following criteria:
What Gives a Company an Economic Moat?
Companies with moats have one or more of the following characteristics:
To maintain analysts’ independence, Morningstar Research Services does not publicly rate its parent company Morningstar Inc. Therefore, Morningstar, Inc. is not on the list of the best companies available to US investors.
https://www.morningstar.com/stocks/best-companies-own-2026-edition
One of the largest railway companies in the USA, with a network that is impossible to replicate.
It's an extremely defensive business, with a huge MOATTo enter this sector would require billions, duplicate infrastructure and overcoming strong legal barriers.
As a result, predictable revenues, consistent dividends and aggressive share buybacksThis was one of the factors that weighed most heavily on my decision.
It's exactly the kind of company I'm looking for: a simple, dominant business that's difficult to replace.
Buy & hold... for life.
I decided against $UNP (+1,82 %) and just went shopping on the walk. $CP (+1,83 %) shopping.
The stock fits well into my portfolio, the sector is currently at its lowest point and this is where I hope to see the most growth with a small dividend 💸
Another 16 shares will be bought at the end of the month.
CP has what I missed with CNR. Strong and experienced management that operates cost-efficiently and is focusing on high growth (in terms of the business) through the acquisition of Kansas City Southern.
Yesterday I decided to part with my position at a slight loss. $CNR (+2,24 %) position with some loss... 🚋
As one of my first major investments and also intended as a long-term position, I decided to do so at the time after only a brief look at the superficial key figures. I wasn't really involved here yet and was in the "just try it out" phase. Of course, I also paid far too much for the paper... 😥
Due to the fact that I am taking my journey in the stock/investing universe more and more seriously and I am constantly trying to sift through more information and evaluate it better in order to make informed decisions. Yesterday I decided to draw the line here, mainly due to the management:
When Tracey took over Q1/22 it looked something like this:
EPS C$1.32 // long term debt C$13.383M // net debt to EBITDA 1.92 // shares out 700M
Arrived today in Q3/25:
EPS C$1.87 // long term debt C$21.120M // net debt to EBITDA 2.54 // shares out 620M
Only 6% growth was reported for earnings, and CAPEX of C$2.8B was announced again. The outlook remains at the lower end of the range with mid to high single digit EPS growth...
In addition, there is also the increased pressure from direct competition from CPKC.
During this time, around $8B in new debt was raised (at fairly high interest rates) to buy back shares at the highest valuation. At the same time, the growth prospects are not really exciting and there is a lot of turnover in the management team.
For me, the new M-team does not seem to be really experienced and the handling of the capital allocation is more than questionable.
That's why I'm calling it a day for now ❌
In any case, I've learned something again with this stock and hopefully I can and will project this into the future. I'm now taking much more time with the evaluation and can hold back instead of immediately dumping my money into the market (individual stocks).
I haven't quite thought about where to allocate the money I've freed up yet, but I'm already interested in taking a position in $CP (+1,83 %) or possibly $UNP (+1,82 %) build up.
I know it's looooong 😂But the valuation of $CP (+1,83 %) is currently coming down even further, the growth story seems interesting and the management also looks good.
I may also use the money freed up to increase other positions in the portfolio, we'll see.
Do you have any tips or experience in this regard? Do you check the figures first or whether the management can/will deal with them?
Following the rebalancing of the S&P Quality Aristocrats last Friday, the following stocks were removed from or added to my two ETF indices (50% weighting):
New additions:
$QDEV (+0,58 %): $NOVN (+2,34 %) , $REL (-3,08 %) , $ITX (-0,45 %) , $LSEG (-2,28 %) , $DB1 (-0,67 %) and more
$QUS5 (+0,47 %): $BKNG (-1,28 %) , $MRK (+1,23 %) , $CRM (-2,31 %) , $UNP (+1,82 %) , $COR (-1,03 %) , $CAH (-1,34 %) and more
Kicked out of both indices and therefore according to S&P no longer Quality Aristocrats are among others: $BATS (-0,07 %) , $7974 (-1,49 %) , $HD (+0,4 %) , $LOW (+0,82 %) , $HLT (-2,16 %)
In addition, the allocation of all individual stocks in the indices was reduced again to max. 5 % was limited.
Thanks to the recent rally of $$HY9H (+5,32 %) my current top 10 weighting (ETFs+shares) is as follows:
3.48% Alphabet
3.04% SK Hynix
3.04% Broadcom
2.93% Meta
2.75% Microsoft
2.71% Apple
2.71% NVIDIA
2.55% Taiwan Semiconductor
2.13% Mastercard
2.08% Visa
New portfolio key figures:
P/E: 27.1 (<30) 🟢
Forward P/E: 21.1 (<25) 🟢
P/Β: 11.5 (<5) 🔴
EV/FCF: 28.7 (<25) 🟡
ROE: 42% (>15%) 🟢
ROIC: 19% (>15%) 🟡
EPS growth for the next 5 years: 15% (>7%) 🟢
Sales growth for the next 5 years: 9% (>5%) 🟡
My internal rate of return is currently 20.19%