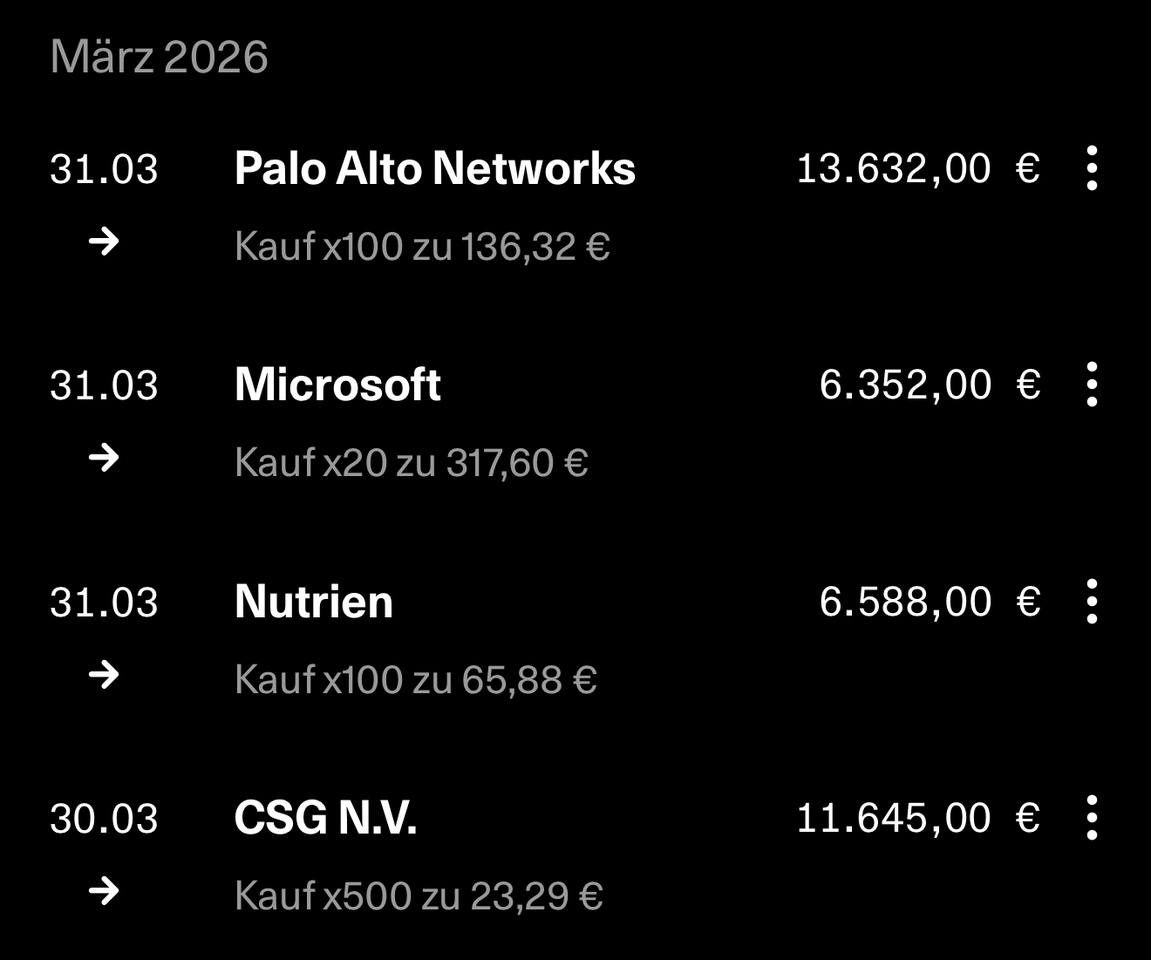
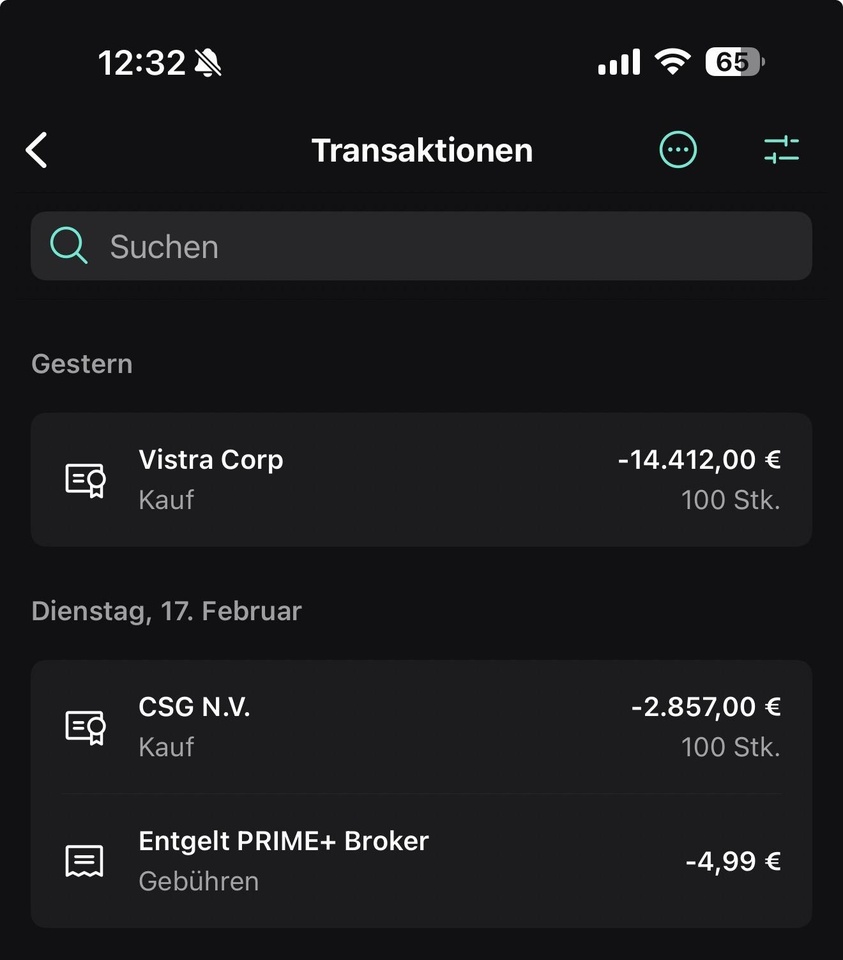
$CSG (+1,21%) must revise downward its profit forecast for the current year. One reason is falling prices for standard ammunition, which is now in less demand than ammunition for longer ranges, the Amsterdam-listed company explained on Wednesday. In addition, the tank business—which has lower margins—now accounts for a larger share of the company’s operations. As a result, the return on sales in 2026 will be only around 21 percent, instead of the previously expected 24 to 25 percent. The revenue forecast of 7.4 to 7.6 billion euros remains unchanged. CSG shares plummeted by 17.7 percent.
In the first nine months of the year, revenue rose by 6 percent to 4.76 billion euros. Adjusted earnings before interest and taxes (EBIT), however, grew only slightly, by 0.4 percent to 1.1 billion euros. This resulted in a return of 23.1 percent. At the end of September, CSG reached a record order backlog of 18 billion euros, representing a three-billion-euro increase since the beginning of the year.
In Germany, CSG acquired a 9.9 percent stake in the Bavarian specialty chemicals company Alzchem, which also produces nitroguanidine for explosives. CSG also has the option to acquire up to 25 percent of the shares. The Czech group had also been rumored to be interested in acquiring a stake in its German competitor KNDS.
Personally, I consider the stock price attractive starting at €8. At that level, there would be a dividend yield of at least approximately 3.5%. Anything else would not be a good deal for me here.