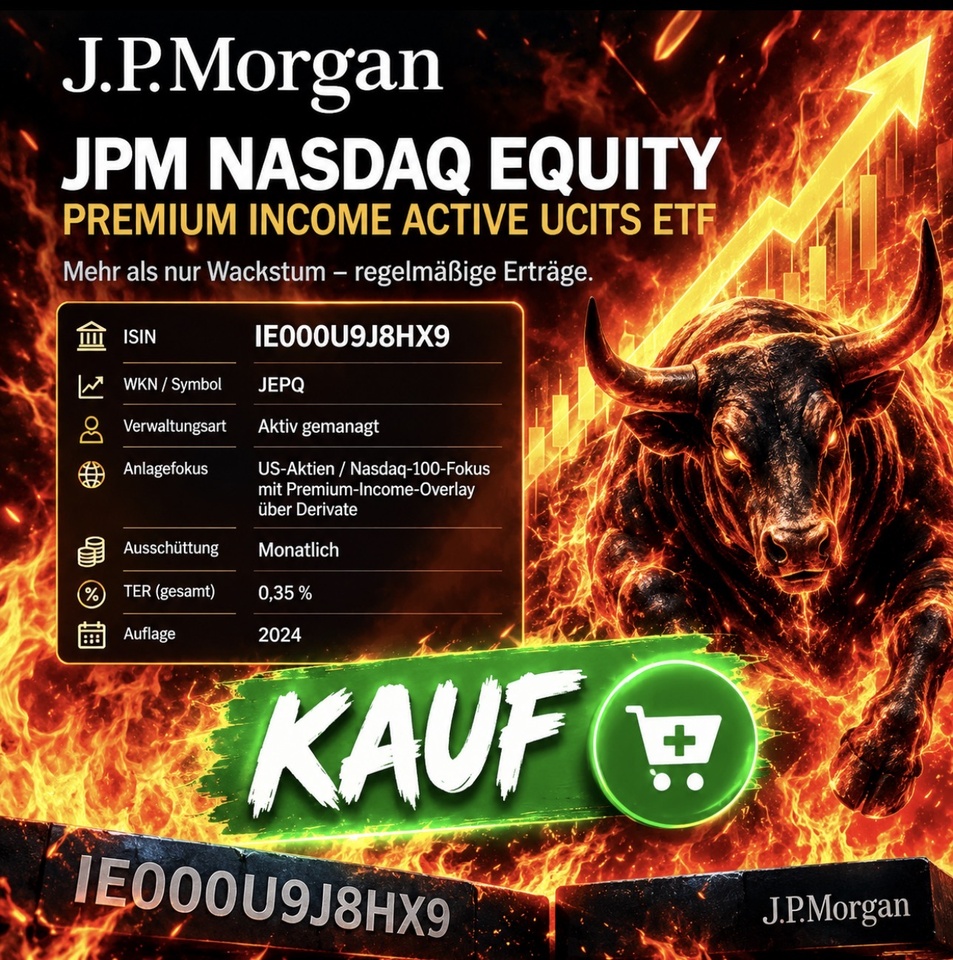
A small purchase and a new addition to the portfolio this month. Next month, $WINC (-0,09 %) . I’ve been involved in crypto since 2021, but I’ve also been investing in stocks—primarily dividend-paying stocks.
iShares World Equity High Income ETF
Price
Discussion sur WINC
Postes
94CC-ETF / New to the Portfolio
Today $WINC (-0,09 %) Added to my portfolio—when will #getquin the monthly dividend payment? Do you have this ETF in your portfolio, too?
Sold JGPI
I have sold my position in $JEGP (+0,2 %) (205 shares) due to the volatile income and disappointing results
I bought:
35 shares of $AD (+1,88 %)
15 shares of $O (-0,25 %)
400 shares of $WINC (-0,09 %)
Going to put the remaining €900 in $VWRL (-0,2 %) or $LDGL (-0,28 %)
Added this covered call ETF to the portfolio today.
The portfolio is designed to generate cash flow and dividends, but it also includes growth stocks.
Do you think this ETF is a good addition? $WINC (-0,09 %)
What do you think?
Whether it's useful depends on your needs
First Monthly Distribution
0.0891 USD
Announcement Date:
September 10, 2026
Expiration Date:
September 17, 2026
Record Date:
September 18, 2026
Payment Date:
September 30, 2026
https://www.londonstockexchange.com/news-article/market-news/dividend-declaration/17779498
Money for Nothing ?!?
Today I’d like to discuss an idea @GoDividend —his so-called “Bauspar-Hebeldepot.” Perhaps some of you have already read his posts on this topic (most recently about two months ago). I find the strategy remarkable for two reasons.
1) This is a very unusual idea. Namely, borrowing at a low interest rate through a home savings contract and investing the funds in securities that pay higher dividends. If the setup works out—and I think it certainly can—you’ve built up some nice leverage from borrowed capital.
2) He’s following through with this even though he’s pretty much the only one with this investment idea, and very few—if any—others here in the forum are pursuing this approach.
Here’s the link to his post https://getqu.in/U6H5wA/
The principle is actually very simple. He pays 2.1% per year in interest on the money borrowed through the home savings loan (in his case, 17,000 euros). He invests the borrowed money in securities such as $WINC (-0,09 %) with a projected distribution of nearly 10%. He takes the difference of just under 8% as a risk premium to account for the possibility that the security’s price could fall and that he’ll have to make up the difference between the security’s value and the loan amount at the end of the loan term.
If the scheme works out, he earns 8% on 17,000 per year (approx. 1,360 euros gross) without investing any of his own money (return on equity = infinite).
Why am I bringing this idea up? I’ll have three land registry entries become available in about two months, and I’m currently considering whether I can use them in a similar way. I don’t have a home savings loan, but I could take out a loan at standard interest rates for real estate financing—e.g., 100,000 at approx. 4.1%–4.4% p.a. Admittedly, I’d need securities with high distributions (and taxes would also eat into that). But it would be a way to generate some additional returns. I think 3% per year on 100,000 would be realistic. With a 10-year loan term, that would add up to a decent amount. Do you think the risk is worth it? Would you do something like this?
I think over 4% is way too much for the risk involved.
I'd say 2.5% is the upper limit for the interest rate on debt financing.
Just my opinion 😊
Monthly Recap 08/26 and Next Milestone...
...another month has come and gone, and nothing has really changed—except that the milestone isn’t a stock market event, but rather my passing the DATEV certification exam (law firm accounting/financial accounting) 🥳
"But investing in yourself often pays off much more than just stubbornly clinging to the past."
Otherwise, there wasn’t much spectacular going on, except for more gradual growth...
...so things continue to look good month-over-month and are also steadily on track for the year...
...the same trend can be seen in the overall view...
...so even though this isn’t a high-flyer portfolio, I’m still looking to the future with confidence, despite all the ups and downs.
And of the last 10% to reach the halfway point, another solid 1.5% has now been achieved (maybe there’s still room for more @Solitair )
》DIVIDENDS《
Unfortunately, this month’s net total was only €91.53 (-13.77% YOY), but this is due to the fact that one stock won’t pay out until next month and another is paying out less.
Looking at the year as a whole, the YOC stands at 6.78%, which is still close to the 7% target, despite investments in growth stocks.
》TOP 3《
$AII (-8,48 %) +53.08% (+61.44%)
$DTE (+0,28 %) +5.70% (+3.76%)
$YYYY (-0,2 %) +5.82% (+1.01%)
》FLOP 3《
$BATS (+0,74 %) -8.92% (+98.49%)
$3750 (-3,18 %) -4.83% (+117.94%)
$HSBA (+0,07 %) -4.60% (+84.70%)
》NEW POSITIONS《
44.14 x $WINC (-0,09 %)
65 x x $FTWG (-0,17 %)
》DISPOSALS《
------
》CONCLUSION《
Everything remains the same, and personal education and professional development continue to be key to success...
With that in mind, here’s to continued success for all of us here in the community 💪🏻

Titres populaires
Meilleurs créateurs cette semaine