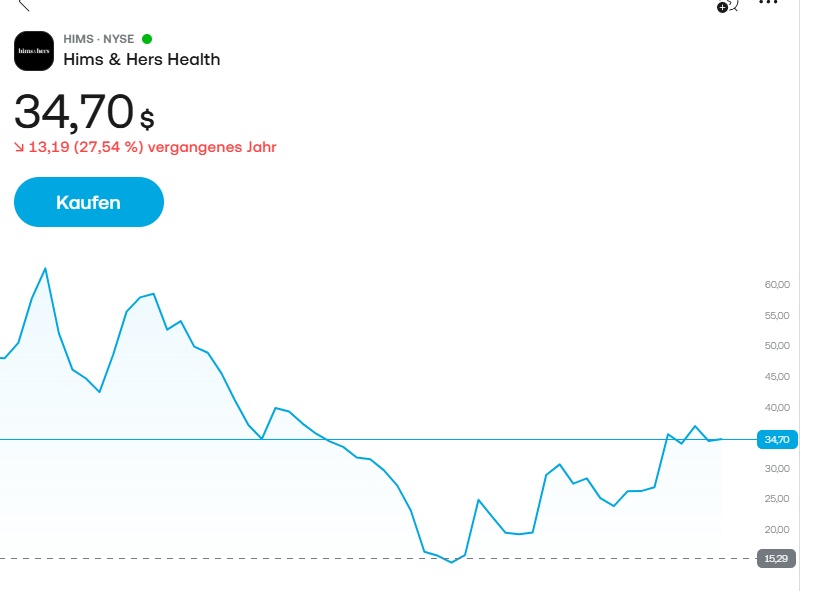
$HIMS (-4,8 %)
⠀
📊 𝐑𝐞𝐬𝐮𝐥𝐭𝐬
• Revenue: $890.4M (Est. $892.77M) ❌, +49% YoY.
• GAAP Net Loss: $33.0M (vs. $15.8M profit YoY).
• Adjusted EBITDA: $82.4M, +5% YoY.
• Gross Margin: 57% (vs. 74% YoY).
• Operating Cash Flow: $65.4M, -56% YoY.
• Free Cash Flow: $26.0M, -67% YoY.
• Subscribers: 2.788M, +13% YoY.
• Monthly Revenue per Average Subscriber: $105, +30% YoY.
⠀
🎯 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
• Q4 Revenue: $875M–$895M, midpoint $885M (Est. $954.58M) ❌.
• Q4 Adjusted EBITDA: $70M–$90M.
• Q4 Adjusted EBITDA Margin: 8%–10%.
• FY2026 Revenue: $3.13B–$3.15B, midpoint $3.14B (Est. $3.21B) ❌.
• FY2026 Adjusted EBITDA: $257M–$277M, reduced.
• FY2026 Adjusted EBITDA Margin: 8%–9%.
⠀
📌 𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
• Q3 revenue was essentially in line with consensus, missing by ~0.3%.
• Revenue growth accelerated to 49% YoY, its second consecutive quarter of acceleration.
• U.S. revenue increased 21% YoY to $657M, while international revenue surged 321% to $233M.
• Subscriber growth of 13% lagged revenue growth, while monthly revenue per subscriber increased 30%.
• Gross margin contracted 1,700 bps YoY to 57%, despite strong top-line growth.
• Adjusted EBITDA increased only 5% YoY, while free cash flow declined 67%.
• Q4 revenue guidance midpoint is ~7.3% below consensus and slightly below Q3 revenue.
• FY2026 revenue guidance was tightened, while adjusted EBITDA guidance was reduced.
• Management cited deliberate marketing-spend pacing ahead of planned Q4 platform expansions.
• Nine-month revenue increased 30% YoY to $2.25B.
⠀
💬 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐂𝐨𝐦𝐦𝐞𝐧𝐭𝐚𝐫𝐲
“Revenue grew 49% year-over-year, our second consecutive quarter of acceleration, with domestic revenue up 21% year-over-year and international revenue up more than 300% year-over-year.”