SOLD
$ASML (+2,28%) Sold for 1668€ 1x
BUY
$JEGP (+0,07%) Buy for 22,025€ 10×
$TDIV (+0,07%) Buy for 52,30€ 5x
$ALFEN (-1,85%) Buy for 14,98€ 15x
$SSLN (-1,53%) Buy for 57,60€ 5x
$SHEL (+0,25%) Buy for 35,96€ 10x
$ALTBG (+0,92%) Buy for 0,49€ 150x
Messaggi
13SOLD
$ASML (+2,28%) Sold for 1668€ 1x
BUY
$JEGP (+0,07%) Buy for 22,025€ 10×
$TDIV (+0,07%) Buy for 52,30€ 5x
$ALFEN (-1,85%) Buy for 14,98€ 15x
$SSLN (-1,53%) Buy for 57,60€ 5x
$SHEL (+0,25%) Buy for 35,96€ 10x
$ALTBG (+0,92%) Buy for 0,49€ 150x
Good morning, dear getquin community.
Over the past few weeks, I’ve been taking a deep dive into the battery and energy storage industry—its entire value chain, the major players, and the hidden champions behind the scenes. Today, I’d like to share this knowledge with you @Tenbagger2024 and show how individual technologies are coming together to form a cohesive energy system. I look forward to hearing your perspectives on this.
It’s no coincidence that Warren Buffett $BRK.B (+0,26%) Berkshire Hathaway. He recognizes early on where real value is created and what role chemical processes play in the development of modern energy and storage systems. That is precisely where it will be determined how efficiently batteries and fuel cells will be produced, operated, and recycled in the future—and who will profit from this transformation in the long term.
Personally, I’m not yet as broadly positioned in this sector as I’d like to be. I’ve already invested in some segments, but the entire value chain still offers enormous potential—and that’s exactly what I wanted to better understand through this analysis, among other things.
I’ve deliberately avoided mentioning personal favorites @Multibagger to keep the analysis neutral. If you’re particularly interested in certain companies, topics, or questions, feel free to mention them here in the comments. I’m open to feedback, additions, and discussions, and if any key players are missing in a particular area, I’ll be happy to add them later. This post ended up being a bit longer because I wanted to present the topic comprehensively and clearly. If you’re primarily interested in the companies, the value chain, and the shovel manufacturers, you can skip ahead to points 13 through 16.
Perhaps Part 2 will cover fuel cells, if that’s what you’d like? I wish you all the best of luck with your investments and, of course, a wonderful Sunday.
Structure of the Post
1. Introduction and Hook
2. Topic and Objective: Value Creation Concept 3. The Battery Industry as a Model
4. Basic Principle of the Battery
5. Applications
6. Battery Life Cycle
7. Future Trends
8. Raw Material Base and Development
9. Value Chain Stages 1–9
10. Value Creation Vectors in the Battery Industry
Value Creation as a Cycle and an Overall Model
11. Macro and Micro Levels and How They Fit Together
12. Significance of Battery Industry 4.0
13. Value Chain with Company Assignments for Stages 1–8
14. Key Players at Each Stage, Plus Overarching Financiers and Strategic Distributors
15. Points of Connection: Hybrid Energy Systems for Data Centers, Industry, and Transportation
16. Energy for Humanoid Robots: The Next Evolutionary Stage of Application
17. Takeaway with a Hidden Question in the Body Text
18. Sources
2️⃣.Topic and Objective of the Article
The battery industry has long been more than just cell manufacturing or e-mobility. It is at the center of a global structural transformation that is redistributing energy, technology, and capital. The goal of this article is to understand the battery as a complete value chain—from raw material extraction through material technologies, production, and application to recycling and recovery.
I will show how genuine value is created along this chain, which industries benefit directly from it, and why the battery industry is becoming a central link in future energy systems. At the same time, the goal is to view the whole as a strategic model—a convergence of technology, economics, and sustainability that extends far beyond the mobility sector.
3️⃣.Basic Principle of the Battery
At its core, a battery is a chemical energy storage device that stores electrical energy in the form of chemical compounds and releases it again when needed. It consists of three main components: an anode, a cathode, and an electrolyte. During charging and discharging, positively charged ions move back and forth between these electrodes. This generates an electric current that can be used to power vehicles, supply machinery, or stabilize energy in grids.
The basic principle is reversible. This means that energy can not only be drawn from the battery but also fed back into it. This simple yet highly effective reaction makes batteries one of the central building blocks of modern energy systems. Thanks to advances in chemistry, materials technology, and manufacturing, performance is steadily increasing, while weight, charging time, and costs are continuously decreasing.
4️⃣.Applications
Today, batteries are far more than just a power source for electric cars. They are the backbone of modern energy systems and key to stabilizing renewable power grids. Their applications range from electric mobility to stationary energy storage to industrial and digital applications.
In the mobility sector, batteries enable the transition from internal combustion engines to electric drive technology and form the foundation of new vehicle platforms. In the energy sector, they serve as buffer storage for solar and wind power, balance out grid fluctuations, and ensure a reliable supply during peak times. In industry, they ensure supply reliability, efficiency, and emergency power solutions, while in data centers they are increasingly being used as emission-free backup systems.
In addition, new areas of application are emerging in aviation and maritime transport, in household and building systems, and in microgrids that supply remote regions or industrial parks with energy independently of the central grid. Batteries are thus a universal energy storage medium that connects sectors and lays the foundation for flexible, decentralized energy architectures.
5️⃣.Battery Life Cycle
A battery goes through a clearly defined life cycle that extends far beyond its actual use. It begins with the extraction and processing of raw materials, continues through cell and system manufacturing to the active use phase, and ends with the recovery and recycling of the materials.
During the production phase, active materials and cells are manufactured from raw materials such as lithium, nickel, manganese, cobalt, graphite, and copper. These cells are then assembled into modules and complete battery packs. During the usage phase, the batteries provide energy for years in vehicles, energy storage systems, or industrial facilities.
Once the end of their service life is reached, the second cycle begins. Cells that are still powerful enough are reused in so-called second-life applications, such as stationary energy storage systems. Finally, the recycling process takes place, during which valuable raw materials such as lithium, nickel, and cobalt are recovered and fed back into the production cycle.
This closed-loop material cycle is the crucial step toward a sustainable battery economy. It reduces dependence on primary raw materials, lowers environmental impact, and makes the entire value chain more resilient in the long term.
6️⃣.Future Trends
The battery industry is facing a period of massive technological and structural change. Progress is shifting from a focus on sheer capacity increases toward efficiency, sustainability, and material independence.
A key trend is the shift toward solid-state batteries, which—thanks to solid electrolytes—are safer, more compact, and more powerful than today’s lithium-ion systems. At the same time, silicon anodes are gaining importance, as they enable higher energy densities and shorter charging times. Sodium-ion batteries open up new possibilities for cost-effective storage solutions, particularly in applications where weight and energy density are less critical.
The digitization of batteries is also advancing. Smart battery management systems analyze the condition, temperature, and state of charge of each cell in real time. This not only improves safety but also extends service life and optimizes operation.
On an economic level, the industry is moving toward vertical integration: manufacturers are securing raw materials, energy suppliers are building their own storage facilities, and technology conglomerates are investing directly in manufacturing capacity. At the same time, political pressure is growing for a circular economy, recycling, and carbon neutrality.
The future of batteries thus lies in a combination of new materials, smart control systems, and closed-loop systems. Those who successfully integrate these three elements will play a decisive role in shaping the dynamics of the energy market in the coming years.
7️⃣.Raw Material Base and Development
The battery industry begins at the source of raw materials. Lithium, nickel, manganese, cobalt, copper, and graphite currently form the basis of nearly all high-performance cells. These metals determine the energy density, stability, and service life of every battery. At the same time, they are the most sensitive part of the value chain, as their extraction, processing, and supply determine costs, sustainability, and geopolitical dependencies.
A significant shift has taken place in recent years. Companies and governments are investing in new mining areas, recycling facilities, and alternative materials to ensure a secure supply. Lithium and nickel, in particular, remain key materials, while cobalt is increasingly being replaced. Graphite is undergoing a transformation toward synthetic and recycled forms, which are intended to reduce dependence on China.
The trend is clearly moving toward material efficiency and a circular economy. Instead of constantly opening new mines, closed-loop systems are emerging in which raw materials are reused multiple times. At the same time, alternative cell chemistries are coming to the fore, relying on abundantly available elements such as sodium, iron, or silicon.
This shift reduces costs, lowers environmental impacts, and increases the independence of entire economies. The raw material base of the battery industry is thus transforming from a linear supply chain into a global, circular material network that combines technology, recycling, and sustainability.
8️⃣.Value Chain
The battery industry follows a clear industrial logic that extends from the extraction of raw materials to the recycling of materials. Each stage in this chain creates its own value and is, at the same time, a prerequisite for the next.
1. Raw Material Extraction – Mining and extraction of lithium, nickel, manganese, cobalt, copper, and graphite from mines and salt lakes. This stage determines the cost structure and environmental footprint of the entire battery.
2. Refining and processing – Processing raw materials into battery chemicals, such as lithium hydroxide or nickel sulfate, which are used in cell production.
3. Materials technology and component manufacturing – Production of cathode, anode, and electrolyte materials, as well as separators, conductive foils, and binders.
4. Cell production – Assembling the materials into electrochemical cells through coating, stacking, and sealing. This step determines capacity, safety, and quality.
5. Module and pack manufacturing—Cells are assembled into modules and complete battery packs, including the battery management system and cooling.
6. System integration – Installation of battery packs in vehicles, energy storage systems, or industrial equipment. This is where the battery, software, and power electronics come together.
7. Use and operation – The battery’s operational phase spanning several years. Digital monitoring and predictive maintenance extend its service life and efficiency.
8. Recovery and Recycling – At the end of the life cycle, materials such as lithium, nickel, cobalt, and graphite are recycled and returned to the production cycle.
Together, these eight stages form the complete industrial cycle of the battery industry. Value is created at every stage, but it is greatest where technology, energy efficiency, and recycling intersect. This is the point at which a supply chain becomes a true value-creation system.
9️⃣.Value Creation Vectors in the Battery Industry
The battery industry is shaped not only by production processes but also by several overarching forces that act like vectors, cutting across all stages of the value chain. These vectors determine which companies remain at the forefront and where value is concentrated in the long term.
1. Technology Vector
Advances in cell chemistry, materials science, manufacturing, and software integration. Companies that scale up in these areas reduce costs and increase energy density, safety, and service life.
2. Digitalization Vector
Data management, condition analysis, cloud-based battery monitoring, and predictive maintenance. This level connects physical systems with AI and makes operations and recycling more predictable.
3. Sustainability Vector
Circular economy, carbon-neutral production, ESG standards, and material recycling. Companies that lead in this area secure long-term approvals and capital.
4. Finance and Investment Vector
Capital flows from government subsidies, private funds, and infrastructure programs that finance manufacturing capacity and research.
5. Infrastructure Vector
Construction of gigafactories, recycling centers, charging infrastructure, and energy storage facilities. This foundation is crucial for scaling up and ensuring supply security.
6. Geopolitical Vector
Location decisions, trade agreements, raw material dependencies, and security interests determine who has access to strategic materials and markets.
These vectors operate simultaneously and reinforce one another. The true dynamics of the battery industry emerge where technology, sustainability, and capital are intelligently intertwined. This is the axis where innovation, returns, and resilience converge.
🔟.Value Creation as a Cycle
The battery industry is increasingly evolving from a linear supply chain into a closed-loop system. Energy, materials, and data flow continuously between production, use, and recycling. The goal is to conserve resources, minimize losses, and increase value throughout the entire life cycle.
The cycle begins with raw material extraction and proceeds through material development, cell manufacturing, and integration, all the way to use in vehicles, energy storage systems, and industrial facilities. After the operational phase, materials are recovered and reused in new batteries. This physical cycle is complemented by a digital data cycle in which all relevant information about the condition, performance, and age of each cell is stored and analyzed.
This creates a system that optimizes itself. Data from operations flows back into research, design, and recycling, making new generations of batteries more efficient, safer, and more sustainable. This combination of physical and digital cycles is the key to genuine value creation in the Battery Industry 4.0.
1️⃣1️⃣.Macro and Micro Levels
The battery industry operates on two interconnected levels that drive and stabilize one another. At the macro level, global structures, political programs, and economic frameworks take shape. At the micro level, technological, chemical, and process-related developments come into play, making these larger trends possible in the first place.
The macro level encompasses everything that drives the industry as a whole: geopolitical interests, energy policy, subsidy programs, trade, infrastructure, and capital flows. This is where the course is set for where gigafactories are built, which countries secure access to raw materials, and how nations reduce their energy dependence.
The micro level describes the technical reality: cell chemistry, material innovation, manufacturing technology, software integration, and recycling processes. This is where actual progress takes place. Every new battery chemistry, every improvement in energy management, or every reduction in the use of rare metals alters the larger system in the background.
Both levels are intertwined. Political decisions and capital flows at the macro level enable technological developments at the micro level, while technological breakthroughs, in turn, trigger new markets, trade structures, and investment cycles. It is precisely at this intersection—where technology, politics, and the economy interact within a closed system—that the strategic potential of the battery industry emerges.
1️⃣2️⃣.The Significance of Battery Industry 4.0
Battery Industry 4.0 stands for the complete digitization and networking of all processes along the value chain. It combines production, energy, data, and sustainability into a single intelligent system that is controlled, monitored, and optimized in real time.
At its core is the integration of physical equipment with digital platforms. Every cell, every machine, and every process provides data that is analyzed using AI and analytics. This creates a self-learning system that detects errors early, ensures quality, and extends the service life of the batteries.
In manufacturing, automated lines, robotics, and machine learning maximize efficiency and precision. During operation, cloud services and IoT sensors enable continuous condition monitoring, which optimizes maintenance, safety, and performance. At the same time, environmental data is collected to make CO₂ footprints transparent and verifiable.
Battery Industry 4.0 is therefore not just a buzzword, but the transition to a fully integrated, data-driven energy industry. It lays the foundation for scalability, cost-effectiveness, and sustainability, and connects research, production, use, and recycling in a closed digital loop.
Visual Overview of the Battery Value Chain
To make the entire structure more tangible, I have divided the battery industry system into three levels:
1. Macro level: global value creation, energy policy, raw material and production networks.
2. Micro level: technological processes, material cycles, and innovation axes.
3. Overall Model: the integration of both levels into a closed-loop system that connects production, use, and recovery.
This diagram illustrates how linear supply chains evolve into a circular, digitally controlled energy system—the very DNA of the Battery Industry 4.0.
➡️Battery Value Creation: Macro–Micro–Overall Model
[R&D] [Engineering] [Digitalization]
↓ ↓ ↓
Raw Materials → Materials → Cells → Systems → Use → Recycling
↑ ↑ ↑
[Supply Chain] [Second Life] [Service]
1️⃣3️⃣.Value Chain with Company Assignments + Hidden Champions
Specialized value is created at every stage along the battery value chain. Companies strategically occupy individual segments or integrate multiple areas to strengthen their position. The combination of material expertise, technological competence, and system integration determines who comes out ahead in global competition.
1. Raw Material Extraction
Lithium, nickel, cobalt, graphite:
$ALB (-1,26%) Albemarle (NYSE: ALB) – U.S. One of the world’s largest lithium producers with mining sites in Chile, Australia, and the U.S. Supplies global cell production with lithium hydroxide for cathode materials
$SQM SQM (NYSE: SQM) – Chile – Specializes in lithium and potash products from the salt lakes of the Atacama Desert. Plays a central role in South America’s battery raw material supply
$9696 (-1,87%) Tianqi Lithium (SHE: 002466 / HKG: 9696) – China – Tianqi Lithium is one of the world’s largest lithium producers, with stakes in major hard-rock lithium projects in Australia (Greenbushes Mine) and processing facilities in China. The company supplies lithium hydroxide and lithium carbonate for cathode materials in the battery industry. Focus on upstream control and chemical processing
$GLEN (+2,01%) Glencore (LSE: GLEN) – Switzerland – A diversified commodities group focused on nickel, cobalt, and copper. A leader in the recycling and reuse of battery waste
$SSW Sibanye Stillwater (JSE: SSW / NYSE: SBSW) – South Africa / U.S. – Sibanye Stillwater is a mining company focused on platinum group metals such as platinum and palladium (important for fuel cell catalysts), as well as nickel and cobalt from recycling and mining. Strategically particularly relevant because it engages in both primary mining and metal recovery. This positions it at the intersection of battery raw materials, fuel cell catalysts, and recycling streams
$PLS (+2,1%) Pilbara Minerals (ASX: PLS) – Australia – A major producer of spodumene concentrate. It is driving the expansion of local lithium value creation in Western Australia
$SYR (-1,15%) Syrah Resources (ASX: SYR) – Australia / Mozambique – Mines natural graphite in Balama, Mozambique, and is establishing anode materials production in the U.S. Strategically important for the Western graphite supply
Copper and other industrial metals:
$FCX Freeport-McMoRan (NYSE: FCX) – U.S. – One of the world’s largest copper producers. Supplies the battery and electronics industries with copper cathodes from mines in North and South America
$BHP (+0,66%) BHP Group (NYSE: BHP) – Australia / UK – Global mining conglomerate focused on copper, nickel, and iron. Invests heavily in sustainable mining and the decarbonization of raw material production
$RIO (+0,47%) Rio Tinto (NYSE: RIO) – United Kingdom / Australia – A multinational commodities giant with a growing presence in the lithium sector. A leader in sustainable copper mining and materials processing
Hidden Champions
$SLI (-3,23%) Standard Lithium (NYSE: SLI / TSX-V: SLI) – Canada / U.S. – Standard Lithium is developing direct lithium extraction (DLE) from brine in the U.S. The goal is to extract lithium without traditional hard-rock mining or massive evaporation ponds. This positions the company as a technology-driven lithium developer focused on ensuring North American supply security. This is clearly a second-tier stock with significant upside potential
$VUL (+3,72%) Vulcan Energy Resources (ASX: VUL) – Australia / Germany - Vulcan Energy is working on geothermal-coupled lithium extraction in the Upper Rhine Graben in Germany. Approach: Low-carbon lithium production from thermal brine plus regional supply for the European battery cell industry. This is extremely important geopolitically because it enables lithium from Europe for Europe without relying on traditional mining infrastructure
$LKE (+2%) Lake Resources (ASX: LKE) – Australia – Develops lithium projects using sustainable direct extraction technology (DLE). The goal is to extract lithium with minimal water consumption and CO₂ emissions
$SGML (+4,4%) Sigma Lithium (NASDAQ: SGML) – Canada/Brazil – Produces high-purity lithium concentrate in Brazil with a focus on ESG-compliant mining and local value creation
$ABAT American Battery Technology Company (NASDAQ: ABAT) – U.S. – Combines raw material extraction with the recycling of lithium and nickel. A pioneer in closed-loop material cycles using domestic sources
2. Refining and Processing
These companies process raw materials into battery chemicals, thereby facilitating the transition to materials technology.
$UMI (+2,22%) Umicore (EBR: UMI) – Belgium – A leader in the refining and processing of nickel, cobalt, and lithium. Develops cathode materials and operates recycling centers in Europe and Asia.
$BAS (+0,73%) BASF (ETR: BAS) – Germany – Global chemical company with a growing focus on battery materials, particularly cathode active materials and nickel-manganese chemistries
$003670 POSCO Future M (KRX: 003670) – South Korea – A specialist in cathode and anode materials. Part of the POSCO Group, it supplies LG Energy Solution and Samsung SDI
$051910 LG Chem (KRX: 051910) – South Korea – Develops and manufactures battery materials, polymers, and electrolytes. Closely integrated with LG Energy Solution throughout the entire supply chain
$010130 Korea Zinc (KRX: 010130) – South Korea – Leading provider of rare metal refining. Supplies nickel and zinc products for battery cathodes
Hidden Champions
Ecopro (KRX: 086520) – South Korea – Manufacturer of high-purity cathode materials and precursors for nickel and cobalt chemistries. Key supplier to LG Energy Solution and SK On
Sila Nanotechnologies (private, U.S.) - Develops silicon anode materials to increase energy density and charging speed. Supplies automakers with advanced battery materials
Green Lithium – United Kingdom (private) - Is building Europe’s first large-scale lithium refinery. Focus on ESG-compliant, energy-efficient refining for the European market
Mangrove Lithium – Canada (privately held) - Develops modular refinery plants based on electrochemical processes to convert lithium concentrate into battery-grade lithium hydroxide
$ICL ICL Group (NYSE: ICL) – Israel – Manufactures specialty chemicals and electrolytes for batteries and energy storage. Combines chemical expertise with sustainable process optimization
3. Materials Technology and Component Manufacturing
They supply cathode and anode materials, electrolytes, separators, and coating systems.
$3407 (+2,49%) Asahi Kasei (TYO: 3407) – Japan – Manufacturer of separator films and electrolytes. A global leader in thermal stability and safety
$3402 (+1,11%) Toray Industries (TYO: 3402) – Japan – Develops high-performance polymers and carbon materials for electrodes, separators, and casings
$SOLB (+1,81%) Solvay (EBR: SOLB) – Belgium – Chemical company focused on binders, electrolyte salts, and coatings for cathode and anode production
$MMM 3M (NYSE: MMM) – U.S. – Supplier of additives, protective coatings, and conductive materials. Strong partner in cell and module manufacturing
$018880 Hanon Systems (KRX: 018880) – South Korea – Specializes in thermal management solutions for battery packs and electric powertrains
$PPG PPG Industries (NYSE: PPG) – USA – One of the world’s leading manufacturers of specialty coatings and functional materials. Develops conductive and protective coatings for battery cells, enclosures, and interconnect components. Supports cell manufacturers with solutions to improve heat dissipation, safety, and service life
Hidden Champions
Nexeon – United Kingdom (privately held) – Develops silicon anode materials to increase energy density in lithium-ion cells. Focuses on lightweight construction and fast-charging capability
Group14 Technologies – U.S. (privately held) – A pioneer in silicon-carbon composites. Collaborates with automakers and cell manufacturers on the next generation of high-energy anodes
$TLG (-4,33%) Talga Group (ASX: TLG) – Australia/Sweden – Integrates graphite mining and anode production. Aims to sustainably produce carbon materials for European cell manufacturing
4. Cell Production
The technological heart of the value chain. This is where capacity, energy density, and cost structures are determined.
$3750 (-0,59%) CATL (SHE: 3750) – China – The world’s largest battery manufacturer with a market share of over 30 percent. A leader in LFP and NMC technologies and a partner to numerous OEMs
$373220 LG Energy Solution (KRX: 373220) – South Korea – Global cell manufacturer with plants in Asia, Europe, and the U.S. Focuses on high-performance cells for e-mobility and energy storage
$SMSN Samsung SDI (KRX: 006400) – South Korea – Focuses on premium cells with high energy density. Close supplier to BMW, Rivian, and other premium manufacturers
$6752 (+3,18%) Panasonic Holdings (TYO: 6752) – Japan – Long-standing partner of Tesla. Building new production facilities in the U.S. and Japan
Northvolt – Sweden (privately held) – European pioneer in sustainable battery manufacturing. Focus on the circular economy, green energy, and closed-loop supply chains
Hidden Champions
$QS QuantumScape (NYSE: QS) – U.S. – Develops solid-state batteries with ceramic electrolytes for higher energy density and safety. Partners with Volkswagen
$SLDP Solid Power (NASDAQ: SLDP) – U.S. – Specializes in solid-state electrolytes and high-performance cells for automotive applications. Collaborations with BMW and Ford
24M Technologies (private, USA) – Develops semi-solid lithium-ion cells with simplified production. Significantly reduces costs and material consumption
$AMPX Amprius Technologies (NYSE: AMPX) – U.S. – Specializes in silicon nanowire anodes with extremely high energy density. Applications in aviation, drones, and robotics
$ENVX (+1,2%) Enovix (NASDAQ: ENVX) – U.S. – Develops 3D silicon cells with a novel architecture. Focuses on safety, fast charging, and compact formats
ProLogium – Taiwan (privately held) – Technology leader in solid-state batteries. Building the first large-scale production plant in Europe with partners from the automotive industry
5. Module and Pack Manufacturing
In this phase, individual cells are assembled into complete battery modules and packs. This is where mechanical engineering, robotics, and precision technology converge with energy chemistry and quality assurance. Companies such as KUKA (ETR: KU2), $ABBN (+2,77%) ABB Robotics (VTX: ABBN), Comau (privately held, Italy), Teamtechnik (privately held, Germany), and $LECN Leclanché (SWX: LECN) supply automated systems for the assembly, welding, testing, and cooling of battery modules. Cell manufacturers such as $300014 EVE Energy (SHE: 300014) or $3750 (-0,59%) CATL (SHE: 3750) also manufacture complete battery systems for the automotive and industrial sectors.
Hidden Champions such as $VAR1 Varta (ETR: VAR1), $MVST Microvast (NASDAQ: MVST), and $FORSE (+0,39%) Forsee Power (EPA: FORSE) are developing modular high-performance batteries for commercial vehicles, rail, shipping, and stationary storage solutions.
These companies combine innovative cell chemistry with thermal management, fast-charging capabilities, and longevity.
At the same time, automakers such as $TSLA Tesla (NASDAQ: TSLA), $1211 (-2,68%) BYD (HKG: 1211), $VOW3 (-1,1%) Volkswagen (ETR: VOW3), $BMW (-1,25%) BMW (ETR: BMW), $MBG (-1,06%) Mercedes-Benz Group (ETR: MBG), $XPEV Xpeng (NYSE: XPEV), $NIO NIO (NYSE: NIO), and $RIVN Rivian (NASDAQ: RIVN) are increasingly integrating cell production into their own value chains in order to independently control efficiency, energy density, and cooling.
In short: At this stage, market-ready battery systems are developed; these are precisely assembled, thermally stabilized, and digitally monitorable. They form the heart of modern e-mobility and energy storage solutions and serve as the bridge between materials science and application.
6. System Integration
Here, the manufactured battery modules are combined into intelligent complete systems—in vehicles, data centers, networks, or industrial facilities.
This stage integrates hardware, software, and control systems into a functional energy landscape.
Companies such as $SIE (+0,98%) Siemens (ETR: SIE), Hitachi Energy (privately held, Switzerland/Japan), $ETN (-0,31%) Eaton (NYSE: ETN), $VRT Vertiv (NYSE: VRT), $WRT1V (+4,52%) Wärtsilä (HEL: WRT1V), $SU (+3,09%) Schneider Electric (EPA: SU), and $ABBN (+2,77%) ABB (VTX: ABBN) are developing comprehensive systems for energy flow control, grid stabilization, and digital integration.
Hidden champions such as $PCELL (+0,14%) PowerCell Sweden (STO: PCELL), Volterion (private, Germany), $ADSE (+0,05%) ADS-TEC Energy (NASDAQ: ADSE), AutoGrid Systems (private, U.S.), $EGT Eguana Technologies (TSXV: EGT), $EOSE Eos Energy Enterprises (NASDAQ: EOSE), and Nuvation Energy (private, U.S.) combine battery storage with control electronics, inverters, and AI-based management software. They create modular energy systems that are flexibly scalable and can be deployed to benefit the grid.
In short: This phase sees the emergence of interfaces between technology and the market—systems that not only store electricity but also intelligently control, distribute, and optimize it.
7. Utilization and Application
This is where the battery industry reveals its economic core. In this phase, energy is not only stored but also strategically deployed in mobility, data centers, grids, industry, and private households.
E-Mobility
Batteries are the foundation of electric powertrains. In addition to $TSLA Tesla (NASDAQ: TSLA), $1211 (-2,68%) BYD (HKG: 1211), $VOW3 (-1,1%) Volkswagen (ETR: VOW3), $BMW (-1,25%) BMW (ETR: BMW), $MBG (-1,06%) Mercedes-Benz (ETR: MBG), and $NIO NIO (NYSE: NIO) are also part of $STLAM (-6,27%) Stellantis (NYSE: STLA), $LCID Lucid Motors (NASDAQ: LCID), and $RIVN Rivian (NASDAQ: RIVN). They are developing their own battery cell chemistries, software, and charging infrastructure.
Hidden Champions such as $VAR1 Varta (ETR: VAR1) and $LECN Leclanché (SWX: LECN) supply modular systems and high-performance cells for specialized applications.
Data Centers and Cloud Infrastructure
The global expansion of AI, cloud, and storage architectures is driving a massive increase in energy consumption. Companies such as $GOOGL (+1,24%) Google (NASDAQ: GOOGL), $MSFT Microsoft (NASDAQ: MSFT), $AMZN (+1,01%) Amazon Web Services (NASDAQ: AMZN), and $ORCL Oracle (NYSE: ORCL) are developing their own energy strategies and software solutions to operate their global data centers more efficiently and with lower CO₂ emissions. Infrastructure partners such as $EQIX Equinix (NASDAQ: EQIX) and $DLR (+0,65%) Digital Realty (NYSE: DLR) are relying on battery and hybrid solutions to ensure grid stability. Technology providers such as $VRT Vertiv (NYSE: VRT), $SU (+3,09%) Schneider Electric (EPA: SU), and $WRT1V (+4,52%) Wärtsilä (HEL: WRT1V) provide energy management, cooling, and hybrid power systems.
Hidden Champions such as AutoGrid Systems—AI-controlled virtual power plants, $ADSE (+0,05%) ADS-TEC Energy (NASDAQ: ADSE)—modular high-performance storage for server farms.
Energy suppliers and grid operators (NRPG)
This is where the transition between generation and storage takes place. Utilities such as $FLNC Fluence Energy (NASDAQ: FLNC), $NEE NextEra Energy (NYSE: NEE), $ENEL (+1,48%) Enel (BIT: ENEL), $TTE (+0,41%) TotalEnergies (EPA: TTE), $RWE (+1,06%) RWE (ETR: RWE), and $ORSTED (+2,66%) Ørsted (CPH: ORSTED) are investing heavily in battery storage to stabilize grids and manage demand. They are joined by specialized developers such as $AMRC (+3,08%) Ameresco (NYSE: AMRC) and $AES (-0,04%) AES Corporation (NYSE: AES), which implement hybrid storage and power plant projects.
Hidden Champions such as $STEM Stem Inc. (NYSE: STEM) and GridBeyond (privately held, Ireland) connect these systems via software and enable real-time energy trading.
Industrial and residential storage
Decentralized energy systems are increasingly connecting industry, commercial properties, and private households with storage solutions. Sonnen (privately held, Germany)—a subsidiary of $SHEL (+0,25%) Shell (LON: SHEL) is a leader in home storage and energy communities. E3/DC (privately held, Germany) and $EGT Eguana Technologies (TSXV: EGT) provide modular systems for self-consumption and grid independence. Software providers such as TWAICE (private, Germany) monitor storage status, efficiency, and lifespan using digital twins.
Summary of the Usage Level
This phase integrates technology, infrastructure, and digital management. Whether in electric vehicles, cloud data centers, industrial facilities, or private households, batteries serve as the link between energy generation, consumption, and intelligence. This is where it will be determined which technologies will define energy distribution, efficiency, and autonomy in the long term.
9. Quality & Safety / Materials Technology
$KEYS Keysight Technologies (NYSE: KEYS) – U.S. – A leader in measurement technology, signal processing, and test systems for battery and semiconductor applications
National Instruments (NASDAQ: NATI) – U.S. – Develops modular test and measurement systems; now part of Emerson Electric
$FORM FormFactor (NASDAQ: FORM) – U.S. – Specialist in wafer probing and precision measurements in cell and semiconductor manufacturing
$KULR KULR Technology Group (NYSE: KULR) – USA – Specialist in thermal management and safety systems for lithium-ion batteries. The technology originated in the aerospace industry (NASA) and is now used in energy storage systems, electric vehicles, and recycling processes.
9. Recovery and Recycling
These companies close the loop and ensure the recycling of strategic raw materials.
$LICY Li-Cycle (NYSE: LICY) – Canada – Operates recycling facilities for lithium-ion batteries. Recovery of nickel, cobalt, and lithium using hydrometallurgical technology
Redwood Materials – U.S. (privately held) – Founded by Tesla’s former chief technical officer, JB Straubel. A leader in establishing closed-loop material cycles in the U.S.
Primobius – Germany (Neometals/SMS Group joint venture) – Develops modular recycling plants for battery production in Europe. Focus on industrial scalability
$UMI (+2,22%) Umicore (EBR: UMI) – Belgium - Combines materials production and recycling. A leader in the recovery of valuable metals such as platinum, nickel, and cobalt
Stena Recycling (privately held, Sweden) – One of Europe’s leading players in recycling and the circular economy. Processes industrial waste, electronics, and batteries, recovering valuable metals and materials for reuse
Heraeus (privately held, Germany) – A technology group specializing in precious metal recycling and materials technologies. Recovers platinum, gold, silver, and rare metals from industrial and battery waste and uses them to manufacture new functional materials
Hidden Champions
Tozero – Germany (privately held) – An innovative startup specializing in hydrometallurgical battery recycling. Its goal is the complete recovery of lithium, nickel, and graphite
$AMY (-4,55%) RecycLiCo (TSXV: AMY) – Canada – Develops chemical processes for the efficient recovery of high-purity battery materials
ACE Green Recycling – Singapore (privately held) – Works on CO₂-neutral recycling processes for lead-acid batteries and lithium systems. Focus on energy efficiency and scalability
Along this chain, a global network of specialists, producers, and integrators is emerging. The greatest growth opportunities lie at the intersections—where chemical expertise, digitalization, and the circular economy converge.
1️⃣4️⃣.Equipment manufacturers at each stage, plus overarching financiers and strategic distributors
⚒️ 1. Raw material extraction – “shovels” = exploration, machinery, plant engineering
Who benefits: Machinery manufacturers, chemical and plant equipment suppliers, raw material financiers
$CAT (+2,45%) Caterpillar (NYSE: CAT) – U.S. – mining equipment, transport vehicles for lithium and nickel mines
$6301 (-0,27%) Komatsu (TYO: 6301) – Japan – heavy mining machinery, particularly in South America and Australia
$SAND (+1,29%) Sandvik (STO: SAND) – Sweden – Drilling and rock-cutting equipment (lithium mines)
$FLS (+2,19%) FLSmidth (CPH: FLS) – Processing plants for nickel and cobalt
$EPI A (+2,3%) Epiroc (STO: EPI-A) – Sweden – Specializes in underground drilling, blasting technology, and automated mining solutions
$WEIR (-0,65%) Weir Group (LSE: WEIR) – United Kingdom – Supplies grinding and pumping technology for ore processing and material transport in mines
Hidden Champions
$ANG (+0%) Austin Engineering (ASX: ANG) – Australia – Manufactures mining vehicle components and heavy equipment for open-pit mining
$ORI (+1,77%) Orica (ASX: ORI) – Australia – Leading supplier of industrial explosives and drilling chemicals for exploration and mining
$METSO (+3,1%) Metso Outotec (HEL: METSO) – Finland – Equipment for ore processing and metal recovery
Investors / Funds:
$SPWRC8 BlackRock Natural Resources Fund
$LIT Global X Lithium & Battery Tech ETF
Sprott Physical Battery Metals Trust – Financing of exploration projects
⚗️ 2. Refining & Materials Chemistry – “Shovels” = Process plants, chemical equipment
Who benefits: Chemical plant manufacturers, specialty chemicals, process engineering
$LIN (+1,6%) Linde (NYSE: LIN) – UK – Gas processing, process plants (e.g., electrolytes, carbon-neutral hydrogen for batteries)
$AI (+2,08%) Air Liquide (EPA: AI) – France – industrial gases, CO₂-free syntheses
$WCH (+1,08%) Wacker Chemie (ETR: WCH) – Germany – Silicon compounds for anodes
$BAS (+0,73%) BASF Engineering Services – Germany – Process design & EPC for cathode production
$TE (-1,72%) Technip Energies (EPA: TE) – France – Engineering solutions for chemical refineries
$ANDR (+0,06%) Andritz AG (VIE: ANDR) – Austria – Machinery and plant manufacturer for chemical processing, filtration, and metal separation
$FLS (+2,19%) FLSmidth (CPH: FLS) – Denmark – Supplies large-scale plants for ore processing and metal recovery with a focus on energy efficiency
$VIE (+1,57%) Veolia Environnement (EPA: VIE) – France – Develops industrial water and waste solutions for metal processing and recycling
Hidden Champions
$PYR (+1,8%) PyroGenesis Canada (TSX: PYR) – Canada – Uses plasma technology to refine metals cleanly and efficiently. A sustainable alternative to traditional high-temperature processes
$MMI Metalo Group (TSXV: MMI) – Canada - Specialist in low-carbon metal refining. Develops energy-efficient processes for converting raw materials into battery-grade metals
Financiers / Strategic Partners:
KfW / EIB / EU Innovation Fund – support materials and recycling projects
Breakthrough Energy Ventures (Gates Fund) – invests in new cathode and anode technologies
🧪 3. Materials Technology & Components – “Tools” = Measurement Technology, Machinery, Software
Who benefits: Measuring instruments, lab automation, software for cell research
$TMO Thermo Fisher Scientific (NYSE: TMO) – U.S. – Materials analytics
$BRKR (+2,5%) Bruker (NASDAQ: BRKR) – U.S. – spectroscopy & materials characterization
$HEN3 (+0,46%) Henkel AG & Co. KGaA (ETR: HEN3) – Germany – Global supplier of industrial adhesives, sealants, and thermal materials, central to battery and electronics manufacturing
$MMM 3M Company (NYSE: MMM) – U.S. – Supplies high-performance insulation materials, adhesives, and protective coatings for battery cells and modules
$DD (+0,58%) DuPont de Nemours, Inc. (NYSE: DD) – U.S. – Produces polymers, insulating materials, and binders for electrolytes, separators, and cell packaging. Focus on safety and energy efficiency
$AMAT (+1,69%) Applied Materials (NASDAQ: AMAT) – U.S. – Supplier of production and coating equipment for battery and semiconductor manufacturing
Hidden Champions
Bühler Group (privately held, Switzerland) – Manufacturer of precision equipment for powder processing, coating, and material preparation
$AFX (+0,74%) Carl Zeiss Meditec AG (ETR: AFX) – Germany – Leading manufacturer of optical and imaging systems for research, microscopy, and materials analysis. Relevant to cell research and quality control of battery materials
Leica Microsystems (privately held, Germany / part of $DHR (+1,2%) Danaher Corporation, NYSE: DHR – U.S.) – Develops microscopes and imaging systems for materials science and cell analysis. Significant for research and process development in battery cell production
Ionbond (privately held, Switzerland) – A leader in hard coatings for electrodes, contact surfaces, and housings. Extends the service life of critical components
$ENTG Entegris (NASDAQ: ENTG) – USA – Develops specialty chemicals, filtration, and process solutions for ultra-high-purity battery and semiconductor manufacturing
Software & Simulation Providers:
$DSY (+0,24%) Dassault Systèmes (EPA: DSY) – Battery development simulation (CATIA / SIMULIA)
COMSOL AB (privately held, Sweden) – Developer of the multiphysics simulation platform. Enables coupled simulations of electrochemistry, mechanics, and thermodynamics in battery cells and energy systems
🏭 4. Cell & Module Production – “Shovels” = Production Equipment, Robotics, Measurement Technology
Who benefits: Machine builders, automation, quality control
$300450 Wuxi Lead Intelligent (SHE: 300450) – China – Develops automated production lines for cell manufacturing and assembly
Toshiba (TYO: 6502) – Japan – Manufacturer of cells and production systems for energy storage and vehicles
$SIE (+0,98%) Siemens AG (ETR: SIE) – Germany – Supplies digital production and automation software, including “Digital Twin” solutions for battery factories.
KUKA AG (ETR: KU2) – Germany – Robotics and automation expert for battery pack assembly and manufacturing processes
Hidden Champion
Tera Automation (privately held, Italy) – Precision machines for electrode handling and cell stacking
InoBat Auto (privately held, Slovakia) – Modular small-batch cell production with a research focus on material adaptation
Trumpf (privately held, Germany) – A leader in laser welding technology and manufacturing systems for cell housings and battery modules
$M5Z (+0%) Manz AG (ETR: M5Z) – Germany – Specialist in machine and plant engineering for cell and module production. Offers complete production lines for electrodes and cells
$DUE (+0,06%) Dürr AG (ETR: DUE) – Germany – Manufacturer of coating and drying systems for battery electrodes. Also supplies cleanroom systems for cell production
Bosch Rexroth (private, Germany) - A leader in production control, linear technology, and battery system integration for automated production lines.
Financing & Infrastructure
EU IPCEI Battery Initiative (Europe) – A European funding program worth billions aimed at strengthening European battery production and research.
Capricorn Partners (private, Belgium) - Venture capital investor focused on cleantech, deep tech, and battery projects in Europe. (Hidden Champion)
InnoEnergy (private, EU / Netherlands) - An EU-backed innovation network for financing and scaling battery startups such as Northvolt or Verkor. (Hidden Champion)
Swedish Growth Fund (private, Sweden) – A government-backed fund that invests in Swedish technology companies and battery manufacturing (Northvolt, Polarium). (Hidden Champion)
⚙️ 5. System Integration & Energy Management – “Components” = Power Electronics, Software, Grid Control
Who benefits: Hardware and software providers that control the energy system
$ABBN (+2,77%) ABB Robotics (VTX: ABBN) – Switzerland – Automation systems and robots for assembly, testing, and quality management
KUKA (ETR: KU2) – Germany – Leading provider of robotics and automation solutions for battery pack assembly
$ENR (+1,05%) Siemens Energy (ETR: ENR) – Germany – Grid integration, medium-voltage connections
$ETN (-0,31%) Eaton (NYSE: ETN) – Ireland – Grid protection, smart power distribution
$SU (+3,09%) Schneider Electric (EPA: SU) – France – BMS & EcoStruxure energy platform
$FLNC Fluence (NASDAQ: FLNC) – U.S. – Battery storage control (software + hardware)
Hidden Champions
Fronius International (privately held, Austria) – Specialist in welding technology and power supply systems for e-mobility
Comau (privately held, Italy) – Automation specialist for battery pack assembly, robotics, and testing systems. Close partnerships with automakers
Teamtechnik (privately held, Germany) – Develops automated test systems and production lines for battery and energy modules
Reis Robotics (privately held, Germany) – Specialist in precision robotics, welding, and joining processes in battery manufacturing
Software / AI:
TWAICE (privately held, Germany) – Offers a software platform for analyzing and optimizing battery lifecycles. Focus on condition monitoring, aging modeling, and second-life applications
AutoGrid Systems (privately held, U.S.) – AI-based software for energy management and grid optimization. Connects battery storage systems, solar farms, and wind farms to form virtual power plants
GridBeyond (private, Ireland) – Develops an AI platform for real-time grid control and energy trading optimization for industry and utilities
⚡ 6. Usage / Applications – “Shovels” = Charging Infrastructure, Power Management, Data Centers
Who benefits: Infrastructure, cloud, and network operators
$CHPT (-6,73%) ChargePoint Holdings (NYSE: CHPT) – U.S. – Operates one of the largest networks of electric vehicle charging stations in North America and Europe. Focus on software and infrastructure management
$ABBN (+2,77%) ABB Ltd. (VTX: ABBN) – Switzerland – Global energy and technology group, a leader in charging infrastructure, grid management, and industrial automation
$SIE (+0,98%) Siemens AG (ETR: SIE) – Germany – Technology and industrial conglomerate, strong in power distribution, automation, and digital grid systems
$VRT Vertiv Holdings Co. (NYSE: VRT) – U.S. – Leading provider of power, cooling, and infrastructure solutions for data centers and telecommunications
$NVDA (+1,35%) NVIDIA Corporation (NASDAQ: NVDA) – U.S. – Develops AI chips and data center architectures that optimize energy efficiency and performance management
$INTC Intel Corporation (NASDAQ: INTC) – U.S. – Manufacturer of energy-efficient processors and data center platforms, with an increasing focus on AI workloads
$AMD (+2,26%) Advanced Micro Devices (NASDAQ: AMD) – U.S. – Manufactures high-performance processors and GPUs with a focus on improving efficiency in data center applications
Hidden Champions
$WBX (+5,13%) Wallbox N.V. (NYSE: WBX) – Spain – Manufacturer of smart chargers and energy management systems for electric vehicles and building integration
$SMCI Super Micro Computer, Inc. (NASDAQ: SMCI) – U.S. – Leading provider of energy-efficient server and data center architectures for AI and cloud infrastructure
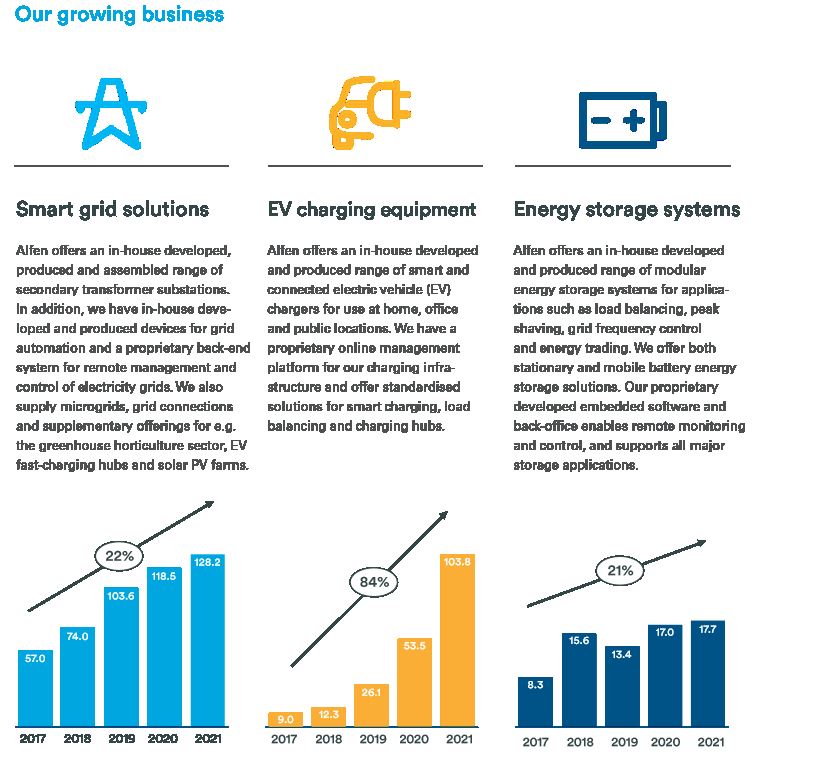
$ALFEN (-1,85%) Alfen N.V. (AMS: ALFEN) – Netherlands – Specialist in smart grids and battery storage. Strong focus on European electromobility
Financiers / Operators:
$EQIX Equinix Inc. (NASDAQ: EQIX) – U.S. – The world’s largest data center operator. Increasingly investing in its own energy storage and microgrid solutions to improve efficiency and stabilize the power supply
$DLR (+0,65%) Digital Realty Trust Inc. (NYSE: DLR) – U.S. – Operates global cloud and colocation data centers. Focuses on integrating battery storage, renewable energy, and energy management systems
$BEP.UN Brookfield Renewable Partners L.P. (NYSE: BEP / TSX: BEP.UN) – Canada – Invests globally in renewable energy, storage technologies, and hydrogen infrastructure. A major financier and operator of hybrid energy systems
♻️ 7. Recycling & Second Life – “Shovels” = recycling technology, sorting machines, chemicals
Who benefits: Recycling plant manufacturers, software, and logistics
$ANDR (+0,06%) ANDRITZ AG (VIE: ANDR) – Austria - Manufacturer of mechanical and chemical processing plants for recycling and battery metal recovery
$NDA (+2,22%) Aurubis AG (ETR: NDA) – Germany – Europe’s largest copper producer and recycler. Entering the battery metal recovery sector to close raw material loops
$UMI (+2,22%) Umicore SA (EBR: UMI) – Belgium – Fully integrated materials and recycling group with closed-loop metal cycles
$LICY Li-Cycle Holdings Corp. (NYSE: LICY) – Canada – Operates hydrometallurgical recycling facilities for lithium-ion batteries
Hidden Champions
Tozero (privately held, Germany) – A startup with innovative hydrometallurgical technology for recovering lithium, nickel, and graphite
$AMY (-4,55%) RecycLiCo (TSXV: AMY) – Canada – Chemical processing of used batteries. Achieves high purity and low energy consumption
ACE Green Recycling (privately held, Singapore) – CO₂-neutral recycling processes for lithium and lead-acid batteries. Focus on energy efficiency and modular plants
Redwood Materials (private, U.S.) – A startup specializing in battery recycling and secondary raw material production with a focus on closed-loop supply chains
SMS Group (privately held, Germany) – Develops smelting plants and hydrometallurgical systems for metal and battery recycling
Funding Sources:
EU Circular Economy Fund (EU) – Supports European recycling and resource efficiency projects
Breakthrough Energy Ventures (U.S.) – Bill Gates’ climate fund, invests in new recycling technologies
EIT RawMaterials (EU) – EU initiative to support raw materials startups along the battery value chain
💰 8. Overarching Financiers & Strategic Fund Distributors
These players provide capital, technology, or infrastructure to all stages:
$BLK (+0,51%) BlackRock Inc. (NYSE: BLK) – U.S. – The world’s largest asset manager, investing in battery, raw materials, and energy technologies via thematic ETFs
Vanguard Group (private, U.S.) – One of the largest global fund providers, with passive investments in the energy and tech sectors
State Street Global Advisors (private, U.S.) – Manages institutional funds, including those focused on clean tech and infrastructure themes
SoftBank Vision Fund (private, Japan) – A private equity fund with investments in energy, battery, and robotics technologies
Temasek Holdings (private, Singapore) – A sovereign wealth fund focused on sustainable energy and infrastructure projects
$GS Goldman Sachs Group Inc. (NYSE: GS) – U.S. – Offers investments in energy storage and infrastructure projects through CleanTech and sustainable finance funds
$MS Morgan Stanley (NYSE: MS) – U.S. – Global financial services firm with dedicated funds for sustainable infrastructure and battery projects
Global X ETFs (U.S.) – Thematic ETF provider focused on lithium & battery tech, clean energy, and critical materials
$IVZ (+1,31%) Invesco (NYSE: IVZ) – U.S. – Asset manager with strategic holdings in CleanTech and infrastructure ETFs
$BEP.UN Brookfield Renewable Partners (NYSE: BEP) – Canada – Invests in clean energy, battery storage, and hybrid power plants worldwide
Hidden Champions
Khosla Ventures (private, U.S.) – Venture capital firm focused on clean tech, storage technologies, and materials innovation
InnoEnergy (private, EU / Netherlands) – EU-funded innovation network that supports startups along the European battery value chain
1️⃣5️⃣.Interconnections – Hybrid Energy Systems for Data Centers, Industry, and Transportation
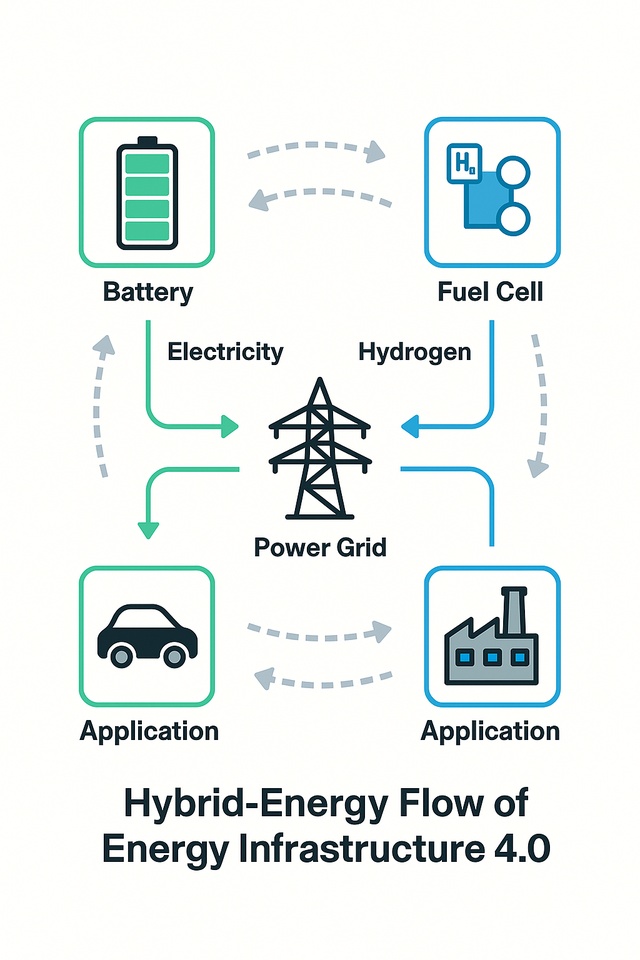
Hybrid energy systems combine different energy sources—such as batteries, fuel cells, photovoltaics, wind power, and grid power—into a single, intelligently controlled system. The goal: maximum efficiency, stability, and reliability of supply with minimal emissions.
These systems are at the heart of Energy Infrastructure 4.0. They combine storage, control, and utilization on a single platform. What matters most is no longer which energy source is used, but how it is integrated.
1. Data Centers – Energy Efficiency Through Storage and Grid Intelligence
Core idea: Data centers are continuous consumers of energy. Hybrid systems combining battery storage, fuel cells, and grid management offset peak loads and power servers during grid outages without the need for diesel generators.
Technological integration:
Lithium- or sodium-ion batteries for short-term load peaks
Hydrogen fuel cells for emergency and long-term power supply
Intelligent energy management software (EMS) for load balancing
Relevant companies:
$VRT Vertiv (NYSE: VRT) – U.S. – Power and cooling infrastructure for data centers
$SU (+3,09%) Schneider Electric (EPA: SU) – France – Digital power distribution, smart grids
$ABBN (+2,77%) ABB (VTX: ABBN) – Switzerland – Energy automation, modular microgrids
$EQIX Equinix (NASDAQ: EQIX) – U.S. – Operator; integrates battery storage and fuel cells
$NVDA (+1,35%) NVIDIA (NASDAQ: NVDA) – U.S. – AI-based load control and optimization
2. Industry – Hybrid Power Systems and Load Management
Core Idea: Energy-intensive industries use combined systems comprising storage, renewable sources, and hydrogen to achieve grid independence and cost efficiency.
Technological Integration:
Battery storage (Li-ion, sodium, solid-state) for production peaks
Hydrogen for long-term storage
Heat recovery + grid control via AI
Relevant Companies:
$SIE (+0,98%) Siemens (ETR: SIE) – Germany – Industrial microgrids, energy management
$WRT1V (+4,52%) Wärtsilä (HEL: WRT1V) – Finland – Hybrid power plants for industry and island grids
$TTE (+0,41%) TotalEnergies (EPA: TTE) – France – Integration of solar, batteries, and hydrogen in industrial parks
AutoGrid (private, U.S.) – AI platform for energy management (Hidden Champion)
$ALFEN (-1,85%) Alfen (AMS: ALFEN) – Netherlands – Smart grid and storage systems.(Hidden Champion)
3. Transportation – Energy Infrastructure for New Mobility
Core idea: The transportation sector is increasingly becoming electric, but with a variety of energy sources. Hybrid infrastructures combine battery, hydrogen, and grid systems for road, rail, and aviation.
Technological connections:
Battery swap stations and fast-charging hubs
Hydrogen refueling stations + local electrolysis
Sector coupling between transportation, electricity, and heating
Relevant companies:
$TSLA Tesla Energy (NASDAQ: TSLA) – U.S. – Energy storage and charging infrastructure
$NIO NIO Inc. (NYSE: NIO) – China – Battery-swapping networks
$005380 Hyundai Motor (KRX: 005380) – South Korea – Combination of battery and fuel cell propulsion
$BLDP (+0,36%) Ballard Power (NASDAQ: BLDP) – Canada – Fuel cells for commercial vehicles
$NEL (+0,31%) Nel ASA (OSL: NEL) – Norway – Hydrogen electrolysis and refueling systems
4. Interconnection Level – Energy System 4.0
At this level, batteries, fuel cells, renewable sources, and digital control converge into a shared flow of data and energy. The key lies in sector coupling: electricity, heat, mobility, and data share a dynamic grid.
Technology Platforms & Drivers:
$ENR (+1,05%) Siemens Energy (ETR: ENR) – Hybrid grid architectures, Power-to-X
Hitachi Energy (privately held, CH/JP) – Control systems and grid stabilization
$ETN (-0,31%) Eaton (NYSE: ETN) – Power distribution, load management
$ADSE (+0,05%) ADS-TEC Energy (NASDAQ: ADSE) – Fast-charging and storage systems. (Hidden Champion)
After examining the value chains and cross-sector applications, I’d now like to show you the whole picture in a simplified system diagram. The diagram visualizes the energy flow of a hybrid energy system: Renewable sources feed electricity into battery storage and fuel cells, which in turn supply consumers such as data centers, industry, and transportation. An AI control system connects all levels into a self-regulating, data-driven循环 system—the foundation of Energy Infrastructure 4.0.
Structure:
1. Energy Sources (top left)
Sun ☀️ → Photovoltaics
Wind 🌬 → Wind turbines
Grid power ⚡ → Feed-in from the public power grid
Hydrogen (H₂) → Produced by electrolysis from surplus energy
2. Conversion and Storage (center of the diagram)
Battery systems (lithium-sodium, solid-state) – short-term energy storage
Fuel cells / hydrogen tanks – Long-term storage and reconversion to electricity
Hybrid control / energy management system – AI-based control of energy flow
➜ Bidirectional arrows between battery ↔ fuel cell ↔ grid symbolize energy exchange and load management
3. Consumers (bottom right)
Data centers – Constant base load, backed up by storage and fuel cells
Industry – Flexible load control, use of hybrid energy for stabilization
Transportation sector – e-mobility, fast-charging hubs, hydrogen logistics
4. Data and Control Layer (above the center)
AI platforms (e.g., AutoGrid, TWAICE, NVIDIA)
Cloud integration for real-time data
Control of energy flow, CO₂ emissions, and costs
5. Feedback (below / base of the system)
Recycling → Raw material recovery → Cell production
Circular arrow visually leads back to the energy sources – symbolizing a closed-loop value chain
The hybrid energy flow illustrates how electricity, hydrogen, data, and raw materials reinforce one another in a circular, data-driven network. This is the foundation of Energy Infrastructure 4.0, which is dynamic, decentralized, and interconnected across sectors.
1️⃣6️⃣.Energy for humanoid robots: the next evolutionary stage of application
The next industrial revolution is no longer taking place solely in data centers or vehicles, but in the convergence of humans, machines, and energy. Humanoid robots symbolize this transition. These are systems that must think, act, and be self-sufficient. Their energy source is what makes them functional in the first place.
This is where battery technology, microgrid systems, and smart energy distribution intersect directly with artificial intelligence. Power density, longevity, and energy efficiency determine how autonomously these machines can operate. Whether in industry, healthcare, logistics, or everyday life, the stability of their energy supply is becoming a strategic factor for entire value chains. Next-generation batteries, solid-state systems, and mini fuel cells form the foundation for this. Companies that develop or supply these technologies are not only creating products but also building the infrastructure for a new form of intelligence that is energy-independent, networked, and scalable.
16.1 Technical Basis: What a Humanoid Really Needs in Terms of Energy
A humanoid robot is, at its core, a mobile energy system. It must walk, grasp, lift, balance, communicate, see, think, and remain safe while doing so. All of this requires a constant supply of energy.
Key requirements: high energy density with low weight, short-term power spikes, thermal stability, energy recovery, and long operating times without manual recharging. Currently, the energy requirements of humanoid robots range from 500 watts to 2 kilowatts, with energy storage capacities of 1 to 5 kilowatt-hours. A system is only considered suitable for industrial use if it can operate autonomously for several hours and recharge itself or swap modules.
16.2 Storage Status Today and in Five Years
Today:
Lithium-ion systems (NMC, NCA) dominate due to their high energy density.
LFP cells excel in safety and lifespan.
In five years:
Silicon anodes will increase energy density and charging speed.
Partially and fully solid-state batteries will improve safety and stability.
Combinations of batteries and fuel cells will emerge for continuous-load applications.
As a result, the robotics energy market is shifting toward modular, interchangeable high-performance cells with active thermal management and smart controls.
16.3 Industry Landscape
A. Cells and High Energy Density
$AMPX Amprius (NYSE: AMPX) – U.S. High-energy-density silicon anodes, ideal for robotics and drones
$ENVX (+1,2%) Enovix (NASDAQ: ENVX) – USA 3D cell architecture, compact and capable of fast charging
$QS QuantumScape (NYSE: QS) – U.S. Develops solid-state cells with ceramic electrolytes
$SLDP Solid Power (NASDAQ: SLDP) – U.S. Solid-state electrolytes for safe, high-performance cells
Sila Nanotechnologies (private, U.S.) Silicon anode materials for lighter systems
B. Battery Pack Architecture and Integration
$TSLA Tesla Energy (NASDAQ: TSLA) – USA Vertically integrated battery packs including BMS
$NIO NIO Inc. (NYSE: NIO / HKG: 9866) – China Battery swap systems for modular power supply
$LECN Leclanché (SWX: LECN) – Switzerland Modular packs for industry and logistics
C. Actuators and Drive Mechanisms
$6324 (+1,12%) Harmonic Drive Systems (TYO: 6324) – Japan Precision gearboxes for humanoid joints
$6268 (-0,7%) Nabtesco (TYO: 6268) – Japan: Cycloidal gearboxes for high loads and stability
Maxon (privately held, Switzerland): High-performance, high-efficiency motors
D. Power Electronics and Control
$IFX (+7,77%) Infineon Technologies (ETR: IFX) – Germany Power semiconductors for motor control and power distribution
$STM STMicroelectronics (EPA: STM) – Switzerland / France Sensors and energy controllers
$TXN Texas Instruments (NASDAQ: TXN) – U.S. BMS components and cell monitoring
E. Charging, Power Supply, and Infrastructure
$ADSE (+0,05%) ADS-TEC Energy (NASDAQ: ADSE) – Germany High-performance storage and fast-charging units
Wiferion (privately held, Germany) Inductive charging for autonomous systems
$ALFEN (-1,85%) Alfen (AMS: ALFEN) – Netherlands: Smart grids and charging infrastructure for robotics and industry
F. Control, Fleet Management, and Energy Intelligence
TWAICE (privately held, Germany) Software for battery health and lifespan prediction
AutoGrid (privately held, U.S.) AI-based platform for energy distribution and load control
$NVDA (+1,35%) NVIDIA (NASDAQ: NVDA) – U.S. Computing platforms for real-time control and energy management
16.4 Who Has the Most Potential
In the short term: Harmonic Drive Systems, Nabtesco, Maxon—because every humanoid robot needs precise, efficient joints.
Medium term: Amprius, Enovix, Sila, QuantumScape, Solid Power—they increase energy density and operational reliability, the key criteria for autonomy.
System-wide: NVIDIA, AutoGrid, TWAICE – because the future lies not only in storage but also in the intelligent control of energy flow.
16.5 Practical Blueprint – Energy Stack of a Humanoid Robot
Energy Storage: Lightweight, high-energy battery module with active thermal management, based on NMC or silicon.
Drive: BLDC motors with harmonic or cycloidal gearboxes, integrated regenerative braking. Power electronics: Inverters and DC/DC converters from Infineon or STMicro, BMS from Texas Instruments.
Charging Infrastructure: Quick-swap packs, inductive intermediate charging with ADS-TEC or Wiferion.
Intelligence: Status diagnostics via TWAICE, energy coordination via AutoGrid, computational control via NVIDIA.
A stack like this not only makes humanoid robots operational but also economically viable. It’s no longer just about robotics—it’s about energy expertise. Whoever masters this stack controls not only the machine but also the business case behind it.
1️⃣7️⃣.Takeaway
The battery industry has long since evolved from a standalone solution into a multifaceted ecosystem in which materials, technologies, data, and energy flows are intertwined. Hybrid energy systems that combine batteries, fuel cells, and renewable sources are no longer a vision but a reality, evident in data centers, industrial parks, and transportation systems around the world. What matters most is no longer just how energy is generated or stored, but how it is intelligently controlled and integrated into existing grids. This is precisely where the real added value lies: in the ability to synchronize energy flows, data systems, and capital flows. Perhaps this is the point at which it will be decided in the future who will shape true energy autonomy—those who produce energy, or those who can control it precisely?
1️⃣8️⃣.Sources & data used:
International Energy Agency (IEA) – Global EV & Battery Outlook 2024
BloombergNEF – Battery Supply Chain & Energy Storage Report
McKinsey & Company – Battery Value Chain 2030
Fraunhofer ISI – Energy System Analysis: Germany & the EU 2024
Company Reports & Investor Relations:
CATL, Tesla, Northvolt, Siemens Energy, Hitachi Energy
Manz AG, Vulcan Energy, Li-Cycle, Umicore, Albemarle
Market Analyses: Benchmark Minerals Intelligence, S&P Global, Reuters Energy Desk
Research Sources: IEA Hydrogen Roadmap, EU Strategic Raw Materials Act, Battery Passport Initiative (Global Battery Alliance)
Images:
Illustrative image — JLStock / Shutterstock.com
Photo: dpa
https://tse1.mm.bing.net/th/id/OIP.Zs6cG53hAFkOB4TXG0psVgHaDR?pid=Api&P=0&h=180
+ 1


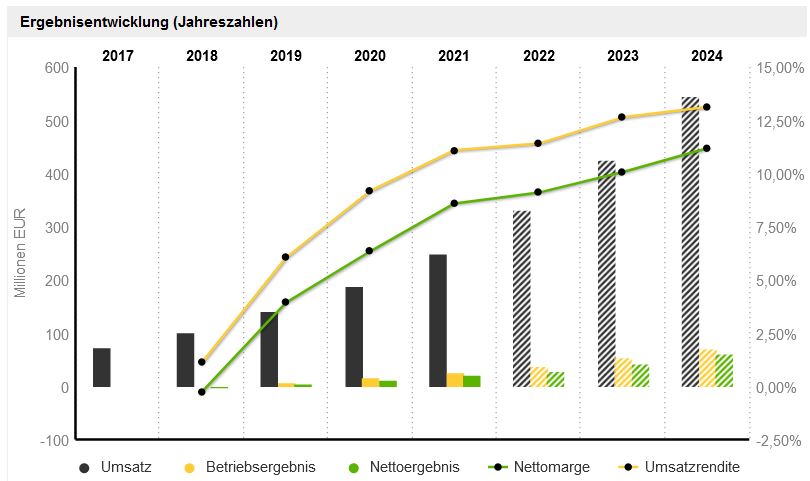
Since 2020, the number of shares has remained the same, which means that Alfen has not diluted its shareholders’ value.
At the current price, the Market Value is €252 million.
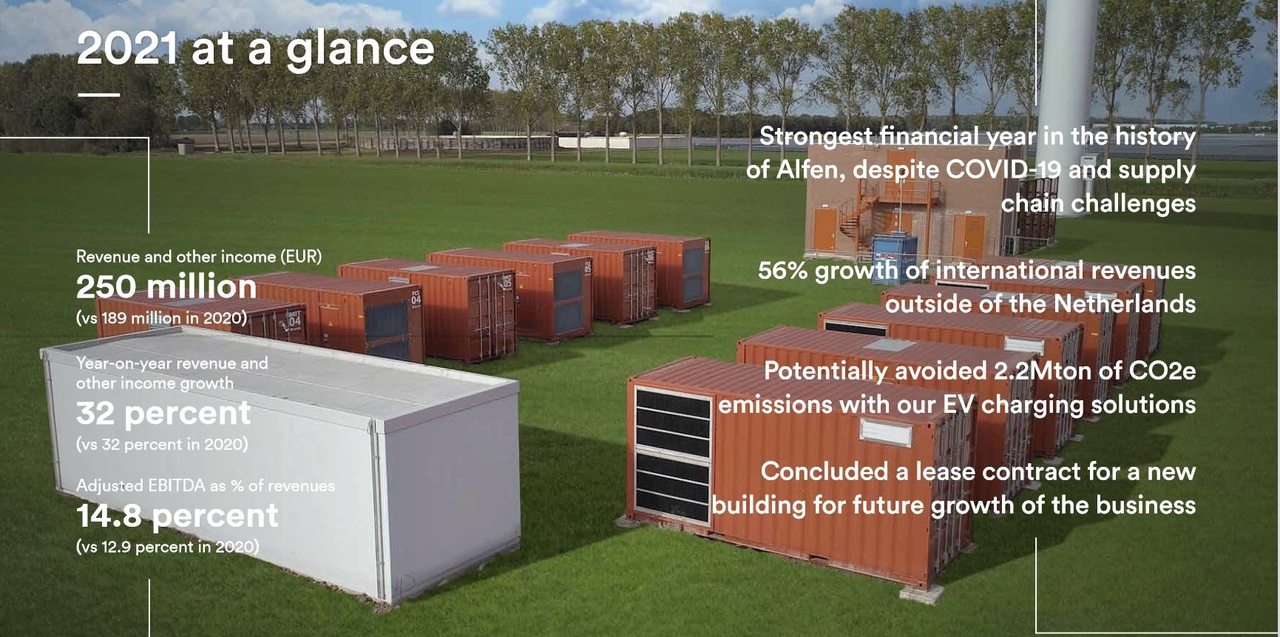
At the end of 2021 Alfen was worth €1,915 million, and at its peak in 2022 (with a share price of €120.8), it reached €2,626 million — more than ten times its current value.
I believe this company is well positioned to be worth more than it has been in the past, and therefore, from today’s depressed level, it could increase in value by more than 1,000%.
The stock entered the market at €10, rose to a peak above €120, and then returned to its base at €10.
In 2017, at the time of its IPO, Alfen’s annual sales were €73 million.
They then grew to a peak of €505 million in 2023.
Since then, there was a 3.4% decline in 2024, and for 2025 another drop of 4.5% is expected, to €466 million. Because of two years of small revenue declines, the share price collapsed by more than 90%.
Analysts following Alfen expect sales to return to growth in the coming years, although at a slow average annual pace of 6.3%.
I believe Alfen is well positioned to grow faster than analysts currently anticipate.
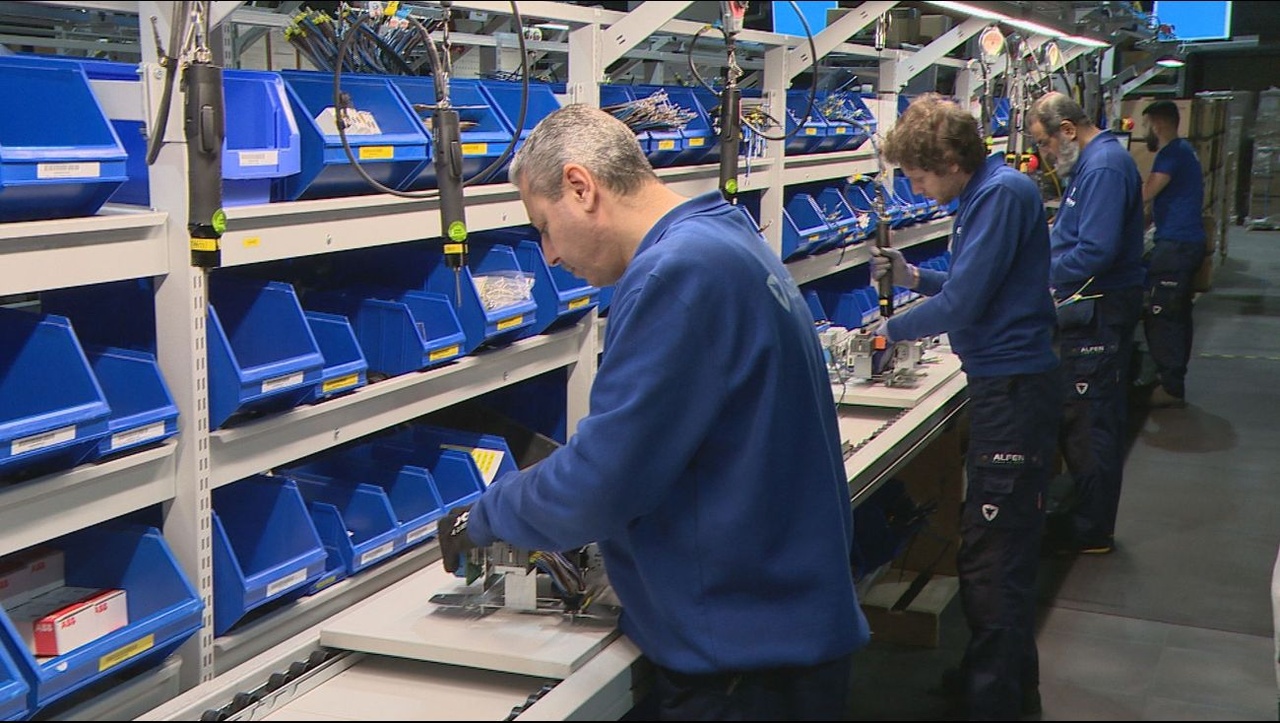
In recent years, Alfen has invested heavily in a new headquarters and factory, equipped with more than 6,000 solar panels, three substations produced by Alfen itself, and over 100 electric vehicle charging points (also made by Alfen).
The goal was both to achieve economies of scale and to showcase what the factories and companies of the future should look like.
The problem is that this large investment weakened the balance sheet and put Alfen in a delicate financial position, forcing it to negotiate covenants with its lending bank. Those reports spooked many investors, who feared the company might not be able to meet its obligations and could even face bankruptcy.
In 2018, the company’s financial debt stood at €20.1 million, while by December 31, 2024 it had risen to €51.5 million. Of that amount, €41.2 million relates to real estate leasing, the majority connected to the new factory in the Netherlands.
On the liquidity side, in 2018 Alfen had just €1 million in cash and equivalents, compared with €17.7 million at the end of 2024.
In other words, since 2018 net financial debt (including leases) rose from €19 million to €33.8 million — not particularly alarming for a company generating around €500 million in annual revenues.
In Q1 2025, the balance sheet situation does not appear to have worsened (free cash flow was a positive €0.2 million), and results for Q2 2025 will be released on August 20.
This situation once again shows that what matters most to investors are profits, not revenues.
In this case, profits have fallen back to the 2018 base level (the break-even point), and the share price has also returned to its base of around €10.
Analysts remain cautious and are projecting a slow recovery in profits over the next few years, but I see no reason why the recovery cannot be faster.
To secure new financing to replace the old facility, Alfen had to implement cost-cutting measures (and these measures have been reinforced recently), which should make the company more efficient over the medium and long term.
Demand for its products seems to have merely slowed for now, but in my view it will return strongly in 2026 and beyond.
Therefore, it would not surprise me if, after returning to break-even, Alfen could, perhaps by 2027 or 2028, report profits even higher than the €54 million achieved in 2022.
I have strong conviction that the energy transition, after a two- or three-year pause that is already passing, will continue its long-term upward trajectory.
The European Commission still requires that from 2035 onward, only electric cars may be sold in the European Union, and that transformation will demand many more substations, vastly more electric vehicle chargers, and significantly more energy storage batteries.
Do you own Alfen? What’s your opinion about this company?
$ALFEN (-1,85%) Goes into reorganisation cutting between 140-150 jobs this news comes shortly after $ACRM (-3,4%) announced that EVbox is closing in the netherlands wich was the main competitor.
The EV infrastructure market is in heavy weather.
So dear friends...
Waiting for the maturity date of my 10y Treasury bond, interest payment will be taken along and, a little too early in the short term, but in the longer term shifted into 20+ Treasury at approx. 5 % p.a.. $IBTL (+0,09%) .
Furthermore, I finally got rid of my Global Clean Energy, albeit with a slight minus, but I see the cost pressure there immensely, and I also didn't like the weighting of the ETF "anymore".
With my savings rates, I'm trying to underperform Apple a little to get away from the almost 4 percent portfolio weighting. Apple is too annoying for me, at least in terms of the iPhone. Year after year, less and less innovation regarding smartphones, now under time pressure only a "half-finished" cell phone released in Germany.
On the other hand, I am quite happy with my portfolio.
I will continue to invest in real estate shares in the future, $DHL (+2,51%) I would like to push them to 1.5 %. I see an anti-cyclical opportunity here, the key figures seem to be okay. And the economy will also enjoy an upswing again at some point. Big player, albeit boring for some. But would like to upgrade it as a small individual share and hold it for the long term...dividend tastes good.
$PATH (-2,36%) and $ALFEN (-1,85%) will still think about a plan to sell, or one day one share will give way for the other.
We don't need to discuss Freyr and Halo, everyone starts at some point and unfortunately they are no longer tradable on L&S.
I am open to constructive criticism.
Have a nice evening and good luck 😅😅
Great...
$ALFEN (-1,85%) cuts its outlook for 2024 and declines with -52% today. Alfen had a position of 4% in my portfolio. Bad day for me today.
More information by Nathan Vifflin:
June 26 - Dutch energy storage specialist and EV infrastructure provider Alfen cut 2024 revenue and EBITDA guidance on Wednesday amid a slowdown in the energy storage market and hurt by lower EV sales in Europe.
WHY IT'S IMPORTANT
A significant number of large deals anticipated for Q2 have been postponed in its energy storage segment. However, deals closed after Q2 will mostly contribute to 2025 revenues.
In its Smart Grid Solutions segment, moisture defects in its prefabricated concrete housing products caused the company to take an one-off impairment charge of 7.5 million euros ($8.03 million) to cover the impact.
With EV sales in Europe growing at a slower pace than expected, Alfen also took a more modest outlook for the second half of the year with regards to its EV Charging segment. Additionally, it took an impairment charge of 3.6 million euros in the segment due to obsolete inventory.
BY THE NUMBERS
Alfen now expects 485 to 520 million euros in revenue for 2024, down from 590 to 660 million euros, and 2024 adjusted EBITDA margin in the mid-single digit percentage.
The company's two impairment charges totaled 11.1 million euros, and it expects 2024 free cash flow to be negative.
KEY QUOTES
"Alfen expects customer decision-cycles to start to shorten once battery prices stabilize, as demand for EVs increase in line with battery manufacturer’s expectations," it said in a statement.
"Increased lead times to obtain and realize a grid connection in countries such as the Netherlands and Sweden are causing further delays," it said, adding that "EV sales are likely to accelerate again in 2025 once affordable models are launched (starting end of 2024, continuing into 2025)"
--GER English version below
Dear congregation, I have a question for you: Leave it or Keep it?
I started investing toward the end of 2023 (aside from small amounts of crypto in 2021). I’ve bought various ETFs; the largest one is now $VWRL (+0,54%) and is also linked to my savings plans.
I intend to keep it as the strongest holding in my portfolio, along with and $IBGX (-0,18%) . In addition, $VWRL (+0,54%) , I also have a savings plan in a relatively well-performing active fund focused on India Equity Large Cap. I plan to keep these two or three funds as the main holdings in my portfolio.
A while back, I shared the composition of my portfolio and asked for feedback. The issue was that I still own other small ETFs (e.g., $WFIN (-0,19%) , $WENS (+0,09%) etc.—along with others worth less than 1,500 euros).
Now the question is: Should I keep them? If so, until when? I don’t intend to put any more money into them, since I want to diversify across 2 or, at most, 3 benchmark ETFs (as much as possible). That’s why I plan to restructure my portfolio a bit.
Also, I’m not sure whether I should reduce my exposure to individual stocks. As you can see, I’m currently focusing on 6 stocks—5 of which are relatively growth-oriented, and 1 that is—if I may say so—more of a gamble. These are$NVDA (+1,35%)
$LLY (-1,06%)
$LMT (-0,52%)
$ALV (+1,42%)
$XOM (+0,06%)
$ALFEN (-1,85%) .
Am I overlooking something here? Or is the diversification good enough?
Time horizon: 10–15 years before I start selling anything.
---ENG
Dear community, a question for you: Keep it or sell it?
I started investing (aside from small amounts of crypto in 2021) around the end of 2023. I’ve bought various ETFs; the largest one now is $VWRL (+0,54%) and I’ve also set up savings plans.
I plan to keep it as the strongest holding in my portfolio, along with $IUIT (+0,81%) and $IBGX (-0,18%) . Along with $VWRL (+0,54%) I also have a savings plan in a relatively well-performing active fund focused on large-cap Indian equities. I plan to keep these two or three as the main holdings in my portfolio.
I shared the portfolio composition a while ago, looking for feedback. The issue that came up was that I own other small holdings of ETFs (i.e. $WFIN (-0,19%) , $WENS (+0,09%) etc... with others amounting to less than 1,500 euros).
Now the question is: Should I keep them? If so, until when? I have no intention of putting more money into them, as I’d prefer to have 2 or at most 3 benchmark ETFs that are diversified (to the extent possible). Hence my plan to restructure things a bit.
Also, I’m unsure whether to reduce my exposure to individual stocks. Right now—as you can see—I’m focusing on 6 stocks: 5 of them are relatively growth-oriented, and 1 more—if I may say so—is a bit of a gamble. These are $NVDA (+1,35%)
$LLY (-1,06%)
$LMT (-0,52%)
$ALV (+1,42%)
$XOM (+0,06%)
$ALFEN (-1,85%) .
Am I missing something here? Or is the diversification good enough?
My time horizon is 10–15 years before I start selling anything.

Tip of the day!
Topic electromobility in Germany 🇩🇪
At Tuesday's meeting of the EU Parliament, it was agreed that motorists should be able to find a charging station at least every 60 kilometers within the main European transport axes. In addition, hydrogen refueling stations are to be built every 200 kilometers.
Since Compleo has encountered massive difficulties in Germany with regard to credits
I have been betting more and more on Alfen.
News fit and the consolidation seems to be completed.
In addition, they are already earning money and will certainly continue to grow solidly🤩.
Am already + 4 percent in plus, definitely continue to expand with further strength.
General data
The Dutch achieved revenue growth of 76 percent to 440 million euros with an EBITDA margin of 18 percent compared to 14.8 percent in 2021. For 2023, the company forecasts revenues of 540- 600 million euros.
Source
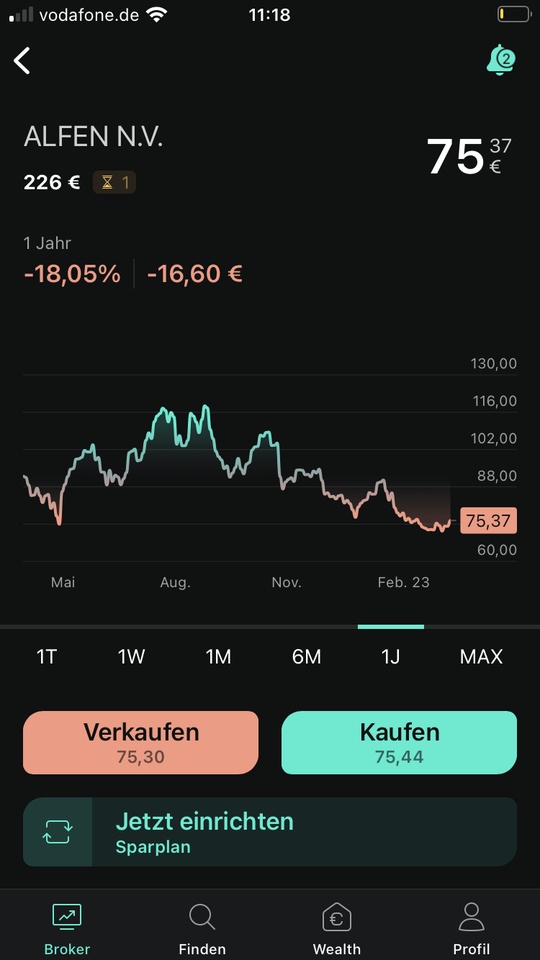

---𝐀𝐤𝐭𝐢𝐞𝐧𝐯𝐨𝐫𝐬𝐭𝐞𝐥𝐥𝐮𝐧𝐠---
Alfen N.V.
NL0012817175
Alfen N.V. is at the heart of the energy transition with its solutions. With transformers, energy storage, charging stations for electric cars and a wide range of other products and services, Alfen is the center and link in the power grid. With a wide range of products developed in-house and extensive experience as a system integrator, Alfen is working on the power grid of the future: reliable, sustainable and innovative [1]. Alfen is the market leader in the Netherlands in these areas. However, Alfen would like to continue to conquer the European market on this basis. Significant subsidiaries are located in the Netherlands, Finland and Belgium, with 61% of sales still generated directly from projects in the Netherlands, 38% in the EU and a marginal share outside the EU [2].
Revenue segments [2]:
Smart grid solutions (intelligent power grids): 52% of revenue.
Energy storage systems: 7% of sales
EV charging equipment (EV charging stations): 41% of sales
Key figures:
-KGV 2021: 89.1 [3]
-KGV 2022e: 61.3 [3]
-KGV 2023e: 43.0 [3]
-PEG 2022e (P/E/growth rate): 61.3/30%= 2.04 (rule of thumb: < 1 = very favorable)
-PEG 2023e: 43.0/30% = 1.43
-Goodwill: 0.13% of equity; 0.6% of 2021 earnings [2].
Goodwill contribution: https://app.getquin.com/activity/ymidZwhlTk
-Sales growth*: 2020 to 2021: 32% ; 2021 to 2022: 33.2%; 2022 to 2023: 37,88%
-EBIT growth*: 2020 to 2021 61%; 2021 to 2022: 33% ; 2022 to 2023: 41,8%
*10-year view not possible as data only available from 2015 (2015 sales €50 million). Due to industry and history, 10-year view not used. Annual report confirms the assumption of 30%.
Market Averages (EU) [5]:
-Aver. P/E Power: 16.99
-Aver. PEG Power: 1.71
-Aver. KGV Electronics (General): 30.73
-Aver. PEG Electronics (General): 0.95
Present Value Calculation = 89,46 € -->created by yourself
-Parameters/Data: G 2021; Required Return 10%, Growth 25% (conservative)
Share price as of 23.03.2022: € 84.32
Rubric - What would Buffet say (data from Annual Report 2021 [2]):
Criteria to be read in detail: https://app.getquin.com/activity/XcuRrJwmyP
Income Statement:
-Research and development: n/a (no data evident from Income Statement).
-Selling, general and administrative expenses: 21.48% of sales -->good!
-Gross margin: 35.97% -->good, tendency increasing! (Buffet's target: at least 40%)
-Net margin: 8.59% in 2021 (9.1% in 2022e) -->ok! (Buffet's target: >20%)
-Interest expense: 3.6% of operating profit-->very good! (Buffet's target: <15%)
Balance Sheet:
-Treasury shares: no buybacks planned!
-Debt < 4xEBIT: Verschuldung 3,7 --> ok!
Cash Flow Statement:
Capital Expenditures:
2021: 54% of net profit (Buffet's target: <50%)
2020: 80,6% des Reingewinns
2019: 118,9 % des Reingewinns
-->development ok, considering the industry, which has high investment needs. To this end, the cash position will be continuously expanded (2019: 134k; 2020: 52m; 2021: 47.2m).
Key Note:
For asset-intensive and project-driven companies, I like to look at the development of inventories, in conjunction with sales. It is good to see here that inventories are continuously growing in line with sales. This is also a sign that the order situation is good and that there are no particularly "slow-moving items" that will have to be written off at some point to reduce profits: The inventory turnover rate (sales/average inventory level) also indicates how often the company "turns over" its inventories within a year, i.e. how often the inventory is "emptied" in a year (even if this happens in practice on a rolling basis and the inventory is never completely empty - hopefully).
Inventory turnover rate 2021: 8.11 (249/30.7)
Inventory turnover 2020: 1.16 (19.9/17.15)
Inventory turnover rate 2019: 1.2 (14.4/ 11.95)
Sales 2021: 249 million
Sales 2020: 189 million
Sales 2019: 143 million
Inventories 2021: 41.5 million
Inventories 2020: 19.9 million
Inventories 2019: 14.4 million
Inventories 2018: 9.5 Mio
Burggraben:
Alfen is in a growing market with many opportunities. However, I do not see a concrete competitive advantage. However, with their charging stations and energy storage systems, the order books will certainly not be empty. Alfen wants to unify its solutions and systems to serve the entire supply chain (smart grids, electricity storage, charging stations). This strategy definitely makes them competitive. To that end, I definitely like the key figures.
Peer Group/Competition:
Siemens Energy
-KGV: negative (2021), 2022e: 154; 2023e: 21.4
-PEG 2022: 154/30 = 5.13; 2023: 0.71
Growth assumption analogous to Alfen. However, existing data could indicate more like 20-30%.
https://www.siemens-energy.com/de/de.html
Blink Charging
Profit zone hardly predictable. Growth given, however, still long way to go! Company is still at the beginning. Sales at just under 21 million in 2021!
Wallbox NV
No profit yet. Profit probably not until 2024/25, but very difficult to forecast. Growth, however, given, analogous to Alfen.
https://wallbox.com/de_de/ueber-uns/vi-er-wallbox
Non-public competition:
Nexgrid
Swissgrid
VTTI
Company classification according to Peter Lynch [4]:
Fast Grower (growth rate >20% )
Conclusion:
I find Alfen extremely exciting. The market allows for a lot of imagination. They have been in a major sideways chart move since January 2021. My hope is that they will serve this again and return in the €60-70 range. Of course, you can not be sure. Possibly there is also a good resistance at about 80€. The e-mobility company would do very well in my portfolio, since I do not really serve this sector yet. One thing to keep in mind, however, is the competition. In addition to the aforementioned peer group, I also see classic car manufacturers, which of course also include Tesla or VW, as competitors to a certain extent, even if not in all segments of Alfen.
As usual, you can also find my collected analyses under the following link:
https://app.getquin.com/activity/YyIXcpDduz?lang=de&utm_source=sharing
As always, no investment advice!
Sources:
[1] https://alfen.com/de/ueber-alfen
[2] https://alfen.com/sites/default/files/media/documents/Alfen%20Annual%20Report%202021.pdf
[3] https://de.marketscreener.com/kurs/aktie/ALFEN-N-V-42452474/fundamentals/
[4] https://diyinvestor.de/peter-lynch-6-kategorien-fuer-die-einordnung-von-unternehmen/
[5] https://pages.stern.nyu.edu/~adamodar/New_Home_Page/datafile/pedata.html
Graphs Source:
Earnings trend: https://de.marketscreener.com/kurs/aktie/ALFEN-N-V-42452474/fundamentals/
2021 at a glance: https://alfen.com/sites/default/files/media/documents/Alfen%20Annual%20Report%202021.pdf
Growing Businesses Overview: https://alfen.com/sites/default/files/media/documents/Alfen%20Annual%20Report%202021.pdf
Company homepage: