

Key figures for the first half of 2026:
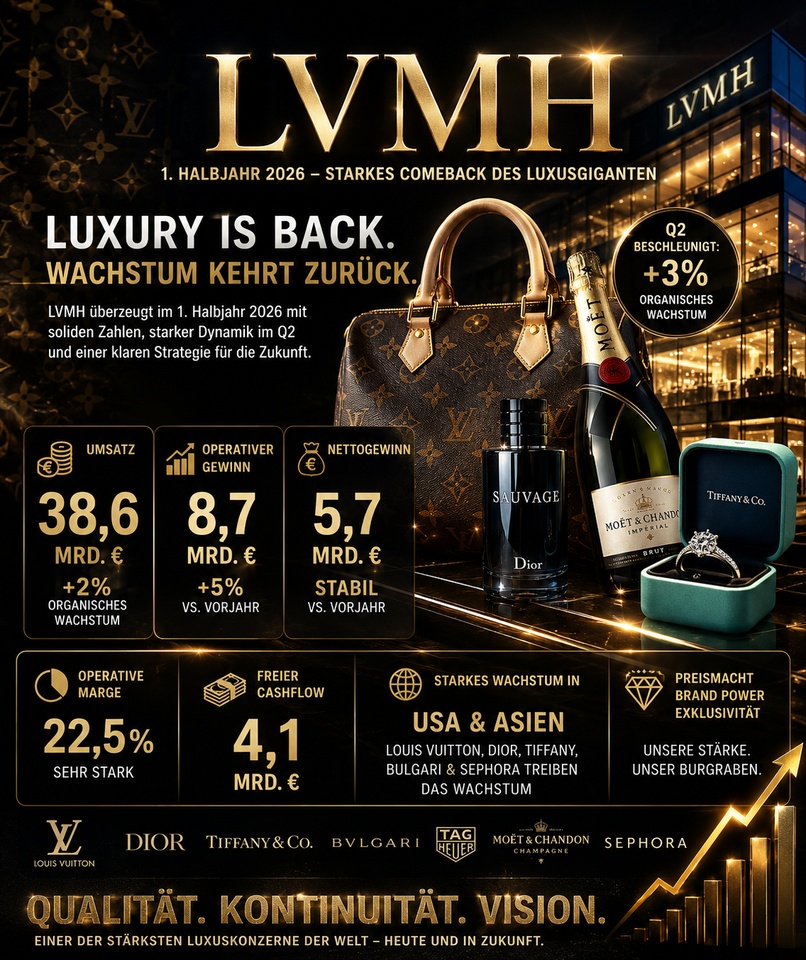
• Revenue: €38.6 billion
• Organic growth: +2%
• Growth accelerated to +3% in the second quarter
• Operating profit: €8.7 billion
• Net profit: €5.7 billion
• Free cash flow: €4.1 billion
• Operating margin: a strong 22.5%
I find it particularly exciting that momentum improved again in the second quarter. After a prolonged period of weakness, growth is returning—primarily thanks to strong demand in the U.S., a recovery at Dior, and outstanding results from Tiffany, Bulgari, and Sephora. (Reuters)
Why I continue to view LVMH as exceptional in the long term:
LVMH doesn’t sell products—LVMH sells desirability. Brands like Louis Vuitton, Dior, Tiffany, Bulgari, TAG Heuer, Moët & Chandon, and Sephora have an enormous moat. These brands cannot simply be copied.
In addition:
• enormous pricing power
• billions in free cash flow
• one of the strongest balance sheets in Europe
• continuous dividend increases
• family-led management with a long-term perspective
Of course, the luxury business remains cyclical. When the global economy weakens, LVMH also faces headwinds. That’s exactly why I’m currently paying close attention to the return to growth—because it could mark the beginning of a new cycle. (Investing.com)
For me, LVMH remains one of Europe’s highest-quality companies.
I’m not investing here for the next quarter—but for the next 10 to 20 years.
#LVMH
#LouisVuitton
#Dior
#Luxury
#Dividenden
#DividendGrowth
#Qualitätsaktien
#ValueInvesting
#Langfristig
#Cashflow
#Europa
#Aktien
#Börse
#Investieren
#Getquin
$MC (-0,14%)
$CDI (-0,86%)
$CHDRY (+1,48%)
$BRBY (+1,81%)
$MONC (+0,87%)
$1913 (+0%)