The housing group $LEG (-0,32%) increased its operating profit (AFFO) by 4.9% to 190.1 million euros in the first nine months and expects to post earnings in the middle of the forecast range of 220 to 240 million euros by year-end. For the coming year, the company anticipates a further increase of 4%. This would more than offset the adverse effects of rising interest expenses. Investments in the existing portfolio are expected to remain at around 35 euros per square meter. The company also intends to maintain its policy of distributing 100% of AFFO as well as a share of proceeds from real estate sales. Regarding the valuation of its portfolio, LEG anticipates a decline of up to 1% by year-end, which would reverse the appreciation seen at mid-year. The loan-to-value (LTV) ratio currently stands at 46.5%. The annual target of 45% is unlikely to be met due to the decline in value and slower-than-expected sales. By the end of September, 1,300 apartments had been sold for a gross total of 189 million euros.
LEG Immobilien
Price
Discussione su LEG
Messaggi
15Instone Lowers Forecast Due to Sluggish Sales
The residential developer Instone Real Estate Group no longer expects to meet its targets for the fiscal year. The company explained that the assumption made when the forecast was issued—that the conflict in the Middle East would have only a short-term impact on business operations—has not been borne out. Rising interest rates and uncertainty are dampening buyer demand and slowing decision-making processes, causing institutional transactions to be postponed until 2027. The Executive Board now expects sales of 500 to 600 million euros (instead of 650 to 750 million euros), adjusted revenue of 450 million euros (instead of 550 to 600 million euros), and adjusted after-tax profit of 25 to 30 million euros (instead of 35 to 40 million euros). The gross profit margin, however, is expected to improve from 24% to over 28%. In the first nine months, revenue (288 million euros) and profit after taxes (12.2 million euros) were below the prior-year figures (347.5 million euros and 21.4 million euros, respectively). Excluding institutional transactions, sales totaled 173.3 million euros (previous year: 229.0 million euros).
I’ll just keep posting updates like this until people here in the forum realize that even the residential sector won’t be a sure thing in the coming months, even if the record dividend is tempting.


A Backdoor Takeover?
$GS (-0,73%) According to a regulatory filing released yesterday, it holds 28.28% of the voting rights in the housing group LEG Immobilien $LEG (-0,32%) . The vast majority of these consist of financial instruments such as call options on shares. The 5% threshold was already exceeded on October 20. On the same day, Grand City announced that it had acquired 20.04% of LEG’s shares from financial investors and intended to increase its stake to 29.9% if necessary. These developments may be related. According to information the “Handelsblatt” obtained from financial circles, Goldman Sachs did not purchase the shares for itself but on behalf of a client. “Experts suspect that Goldman Sachs is supporting GCP in its investment in LEG and is acting as a so-called financial intermediary,” the newspaper writes.
So, who is it acting for $GS (-0,73%) ? :)
I see a takeover bid coming soon. Is this a good trade opportunity? What does the community think?
Aroundtown Enters the LEG Market Through Grand City
$AT1 (+0,12%)
-Subsidiary Grand City joins $LEG (-0,32%)
...
Grand City Properties has acquired a block of shares in the residential real estate group LEG Immobilien from financial investors, thereby becoming the largest single shareholder with a 20.4% stake. Grand City states that it could increase this stake to 29.9% or, if market conditions are right, sell it again. Like those of other housing companies, LEG’s stock has been trading at a low since the recent rise in interest rates. Based on yesterday’s closing price, the newly acquired stake has a market value of just under 700 million euros, while the pro-rata book value of LEG’s real estate portfolio stands at 1.8 billion euros. Grand City apparently sought to take advantage of the price discount. In addition, Grand City owns many apartments in LEG’s home market of North Rhine-Westphalia. Grand City, in turn, is majority-owned by Aroundtown. With this investment in LEG, the residential business—accounting for 42%—will become Aroundtown’s largest division. LEG Immobilien reacted neutrally to the transaction.
Things are slowly getting underway. I’m also starting to get a little excited about residential real estate stocks, but I think holding off for a few more months will lead to lower equity prices. However, some of the NAV discounts are already really tempting, even when you factor in that they’ll likely have to depreciate significantly again. Also $VNA (-0,79%) , $TEG (-1,01%) , $GYC (+0,52%)
Which stock do you find most attractive for getting started? Right now, I’m leaning most toward $TEG (-1,01%) and $LEG (-0,32%)
@investron Is this something for your dividend portfolio?

A Wave of Refinancing Amid Rising NPL Ratios
There are a lot of people here who believe in $VNA (-0,79%)
$LEG (-0,32%) or $AT1 (+0,12%) and similar stocks and currently find the price and dividend attractive. For all of them, here’s a news article that sums up my opinion on this very well and explains why I don’t (yet) see any good entry prices:
The wave of upcoming refinancing in the real estate market is reaching its peak: About a quarter of the financing on the books of local real estate lenders is due in the next two years. This is according to the latest banking survey by EY-Parthenon of 90 real estate-financing banks in Germany. Just under a third of the institutions report a non-performing loan ratio of between 4% and 6%. For a quarter of the surveyed lenders, the ratio is even higher. Nearly half of the lenders have seen this ratio worsen. According to the European Banking Authority, 6.8% of commercial real estate loans were nonperforming in the first quarter, corresponding to a volume of approximately 18 billion euros. More than 40% of financial institutions told EY that, in individual cases, they had been unable to find a viable financing solution. The proportion of respondents expecting real estate prices to rise has plummeted from 30% to 2% within half a year. In both the private and institutional residential segments, one in ten expects prices to fall.


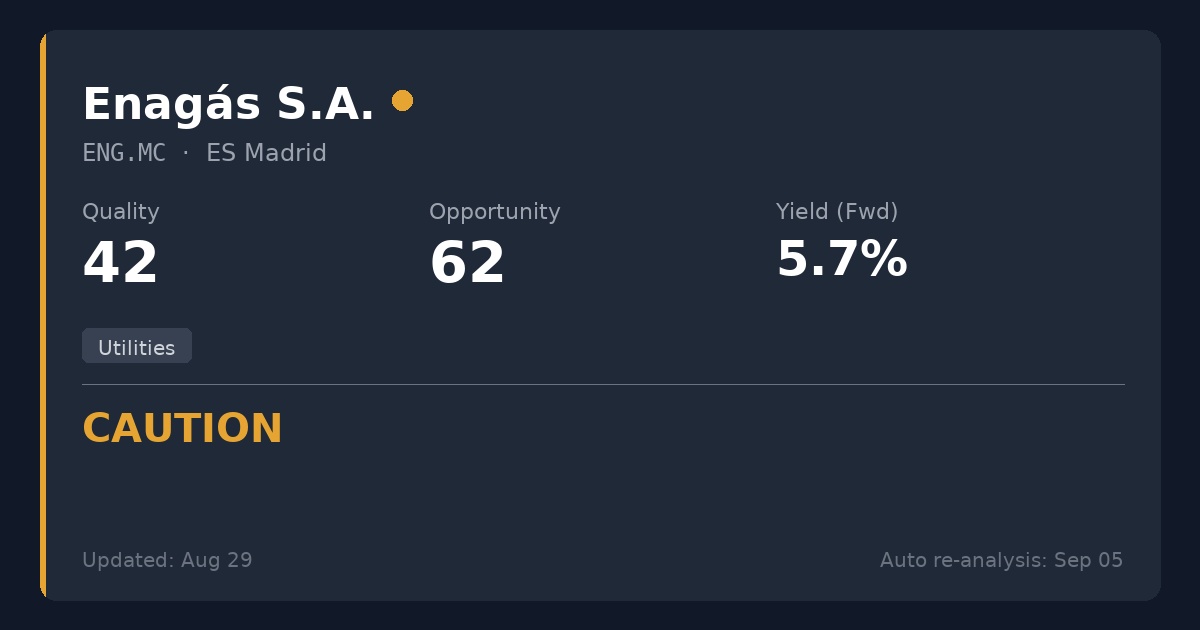
I closed my Enagás position with a 14% loss... and the position is still in the black. I'm reallocating to three beaten-down European stocks.
Source: Enagás ($ENG (+1%)
)
- Price: -14% since my purchase.
- Dividends received on the position: ~50% of the investment → the overall trade is profitable.
- Why am I selling? The investment thesis has changed. The dividend was cut by 16.4% in 2024 to finance its shift to hydrogen, and the coverage ratio based on free cash flow is only 0.36x. My model rates it as 🟠 CAUTION (Quality 42 / Opportunity 62): fossil gas in structural decline + unproven bet.
Entry: 3 European stocks that the model rates as 🟢 OPTIMAL
- Gecina ($GFC (-0,85%)
) — Parisian REIT. Yield 7.86%, a discount of 49% off NAV. Quality 75 / Opportunity 85. - LEG Immobilien ($LEG (-0,32%) )— German residential real estate. Yield 5.87%, a discount of 55% discount to NAV. Quality 75 / Opportunity 90.
- Vinci ($DG (-0,2%)
) — infrastructure. P/E 12.7, yield 4.23% + total shareholder yield of 10.76%. Quality 83 / Opportunity 85.
Same pattern across all three: non-monetary devaluations due to interest rates that are weighing on the price, while rent and cash flow remain solid. A temporary problem, not a broken business model.
To be honest: LEG took a hit in 2024 (-39.8%) as part of a strategic reset and has already rebounded (+10.2% in 2025), and Vinci’s toll road concessions expire between 2032 and 2036. They aren’t perfect—that’s why they’re cheap.
Do you see value in Gecina and LEG at these discounts, or is the European real estate sector still under pressure from interest rates?

The turn of the year is approaching - what's coming in 2026?
Good evening dear community :)
From an investor's point of view, 2025 has been a very successful year (so far). ETFs have done well and most sectors have also had a good year. Now I wanted to hear from the community which sector and possibly which share from this sector you would prefer for 2026. Do you think it will be tech again, among others, or do you have 1-2 lagging sectors / stocks on your list?
I'm curious and would be delighted to hear from you. This time next year I would then present the result ;)
Please write which industry / title and why? I would like to make the start .
My first sector is chemicals and specifically the chemical industry in Europe. If you look at the charts, most stocks have been in the doldrums for 5 years. I am of the opinion that everything is (really) priced in for most shares now and not much is expected anymore. As I don't expect a global recession, I would say that the chemical sector will experience a boost again in 2026. I would specifically opt for $IMCD (+1,15%)
My second sector is real estate. I expect interest rates to fall in the US, which should further boost our German real estate stocks. Even though there are many issues that the sector has to overcome, I believe that the lost year 2025 could be made up for in 2026. My idea here is the $LEG (-0,32%) . 0.5 book value, insider buying and upgrades by analysts support my thesis that 2026 could possibly be better again.
Let's hear from you.
Have a nice evening :)


Analyst updates, 25.11.
⬆️⬆️⬆️
- MORGAN STANLEY upgrades ROBINHOOD to Overweight. Target price USD 55. $HOOD (-1,87%)
- BARCLAYS raises the price target for DEUTSCHE TELEKOM from EUR 37 to EUR 39.50. Overweight. $DTE (+0,94%)
- BERENBERG raises the target price for SIEMENS ENERGY from EUR 35 to EUR 70. Buy. $ENR (-0,65%)
- UBS raises the target price for RHEINMETALL from EUR 570 to EUR 630. Neutral. $RHM (-4,71%)
- BARCLAYS raises the price target for 1&1 from EUR 17 to EUR 20. Equal-Weight. $1U1 (-1,23%)
- DEUTSCHE BANK RESEARCH upgrades VESTAS from Hold to Buy. $VWS (+3,75%)
- DEUTSCHE BANK RESEARCH raises the price target for VONOVIA from EUR 33 to EUR 38. Buy. $VNA (-0,79%)
- DEUTSCHE BANK RESEARCH raises the price target for TAG IMMOBILIEN from EUR 16 to EUR 18. Buy. $TEG (-1,01%)
- DEUTSCHE BANK RESEARCH upgrades AROUNDTOWN from Sell to Hold. Target price EUR 2.80. $AT1 (+0,12%)
- DEUTSCHE BANK RESEARCH raises the price target for LEG IMMOBILIEN from EUR 90 to EUR 105. Buy. $LEG (-0,32%)
- DEUTSCHE BANK RESEARCH upgrades DEUTSCHE WOHNEN from Hold to Buy and raises target price from EUR 19 to EUR 28. $DWNI (+0,89%)
- STIFEL raises the price target for NOVARTIS from CHF 106 to CHF 109. Hold. $NUVN
- DEUTSCHE BANK RESEARCH upgrades JD SPORTS FASHION from Sell to Hold. $JD. (-0,43%)
- DEUTSCHE BANK RESEARCH raises the price target for ALSTOM from EUR 22 to EUR 25. Buy. $ALO (-1,64%)
- MORGAN STANLEY raises the price target for DEUTSCHE BÖRSE from EUR 213 to EUR 232. Equal-Weight. $DB1 (-0,21%)
- KEPLER CHEUVREUX raises the target price for ECKERT & ZIEGLER from 57.30 EUR to 60.30 EUR. Buy. $EUZ (+3,23%)
- BARCLAYS raises the target price for UNITED INTERNET from EUR 23 to EUR 26. Equal-Weight. $UTDI (+0,73%)
- JEFFERIES raises the price target for HEIDELBERG MATERIALS from 142.10 EUR to 145.50 EUR. Buy. $HEI (-1,93%)
⬇️⬇️⬇️
- DEUTSCHE BANK RESEARCH lowers the price target for KION from EUR 55 to EUR 50. Buy. $KGX (-1,77%)
- DEUTSCHE BANK RESEARCH lowers the price target for CTS EVENTIM from EUR 114 to EUR 106. Buy. $EVD (-8,2%)
- GOLDMAN downgrades ORSTED from Buy to Neutral and lowers target price from DKK 520 to DKK 445. $ORSTED (-1,18%)
- DEUTSCHE BANK RESEARCH lowers the price target for H&M from SEK 200 to SEK 190. Buy. $HM B (-0,55%)
- MORGAN STANLEY lowers the price target for MERCK KGAA from EUR 200 to EUR 190. Overweight. $MRK (+1,17%)
- BARCLAYS lowers the target price for THYSSENKRUPP from EUR 4.40 to EUR 4. Underweight. $TKA (-1,64%)
- MORGAN STANLEY downgrades ING to Equal-Weight. Target price EUR 17.50. $ING (-1,32%)
- JPMORGAN lowers target price for RWE from EUR 48 to EUR 47.50. Overweight. $RWE (+0%)
⬆️⬆️⬆️
- BOFA raises the price target for WALMART from USD 95 to USD 105. Buy. $WMT (+0,61%)
- JEFFERIES raises the price target for WALMART from USD 100 to USD 105. Buy. $WMT (+0,61%)
- HAUCK AUFHÄUSER IB raises the target price for RHEINMETALL from EUR 680 to EUR 750. Buy. $RHM (-4,71%)
- WARBURG RESEARCH raises the target price for RHEINMETALL from EUR 600 to EUR 700. Buy. $RHM (-4,71%)
- JPMORGAN raises the price target for SALESFORCE from USD 310 to USD 340. Overweight. $CRM (+0,44%)
- WARBURG RESEARCH raises the target price for LEG IMMOBILIEN from EUR 81.60 to EUR 90.50. Hold. $LEG (-0,32%)
- DEUTSCHE BANK RESEARCH raises the price target for HEIDELBERG MATERIALS from EUR 116 to EUR 137. Buy. $HEI (-1,93%)
- KEPLER CHEUVREUX raises the price target for GFT TECHNOLOGIES from EUR 31 to EUR 32. Buy. $GFT (+2,74%)
- ODDO BHF raises the target price for TALANX from EUR 76 to EUR 78. Underperform. $TLX (+1,03%)
- KEPLER CHEUVREUX raises the target price for THYSSENKRUPP from EUR 3.70 to EUR 3.80. Hold. $TKA (-1,64%)
⬇️⬇️⬇️
- STIFEL lowers the price target for BAYER from EUR 36 to EUR 28. Hold. $BAYN (-0,91%)
- LBBW downgrades ENI from Buy to Hold and lowers target price from EUR 16.70 to EUR 15. $ENI (+2,35%)
- WARBURG RESEARCH lowers the target price for SFC ENERGY from EUR 29 to EUR 27. Buy. $F3C (-2,88%)
- WARBURG RESEARCH lowers the target price for TECHNOTRANS from EUR 23 to EUR 21. Buy. $TTR1 (+4,36%)
- DEUTSCHE BANK RESEARCH lowers the price target for CUREVAC from USD 3.90 to USD 2.50. Hold. $CVAC
- BERENBERG lowers the price target for ASTRAZENECA from GBP 150 to GBP 140. Buy. $AZN (-0,4%)
Pre-market news
$VOW (-2,29%) Volkswagen Vz. pre-market -0.85% +++ Media report on missed savings target
$LEG (-0,32%) LEG Immobilien pre-market -4% +++ Convertible bond burdened
$DHER (-0,56%) Delivery Hero pre-market +1.55% +++ JPMorgan brings mergers into play
$AT1 (+0,12%) Aroundtown pre-market +4.8% +++ After figures, outlook raised
Aroundtown generates revenue of €770.8m (previous year: €815.3m), net rental income of €587.6m (previous year: €596m), FFO 1 of €154.1m (previous year: €175.3m) and a net result of -€329.6m (previous year: -€1.3bn) in the first half of the year. In the outlook for 2024, the company now sees FFO1 of €290 to €320 million (previously: €280 to €310 million).
Titoli di tendenza
I migliori creatori della settimana