
My $IREN (-7,34 %) sinks in the AI storm 🌊, so I've anchored on $MP (-7,71 %) : Q3 beat with a surprise profit, GM magnet deliveries from Q4, insiders buying, and +3.4% on a red day. Back in at $39. ⚓
MP Materials
Stock
Stock
Ticker: MP
MP
Price
Debate sobre MP
Puestos
39
1Semana·
𝐌𝐏 𝐌𝐚𝐭𝐞𝐫𝐢𝐚𝐥𝐬 𝐐𝟑 𝟐𝟎𝟐𝟔: 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝐒𝐮𝐫𝐠𝐞𝐬 𝟏𝟕𝟔%, 𝐀𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐄𝐁𝐈𝐓𝐃𝐀 𝐓𝐮𝐫𝐧𝐬 𝐏𝐨𝐬𝐢𝐭𝐢𝐯𝐞, 𝐆𝐌
⠀
📊 𝐑𝐞𝐬𝐮𝐥𝐭𝐬
• Revenue: $147.7M (+176% YoY)
• Revenue + Price Protection Income: $155.8M
• GAAP EPS: -$0.12 vs. -$0.24 YoY
• Adjusted EPS: $0.04 vs. -$0.10 YoY
• GAAP Net Loss: -$20.7M vs. -$41.8M YoY
• Adjusted Net Income: $8.8M vs. -$17.8M YoY
• Adjusted EBITDA: $41.1M vs. -$12.6M YoY
• Operating Loss: -$22.1M vs. -$67.0M YoY
• Cash & Short-Term Investments: $1.34B
⠀
🎯 𝐎𝐮𝐭𝐥𝐨𝐨𝐤
• GM Magnet Deliveries & Revenue: Beginning Q4 2026
⠀
📌 𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
• NdPr production increased 41% to 1,018 metric tons
• NdPr sales volume surged 94% to 1,020 metric tons
• NdPr oxide and metal revenue jumped 227% to $101.0M
• Materials segment revenue surged 322% to $133.5M
• Materials adjusted EBITDA reached $47.8M vs. -$14.5M YoY
• Magnetics segment revenue declined 15% to $18.6M, with adjusted EBITDA falling 44% to $5.3M
• Completed General Motors magnet qualification, clearing the way for commercial deliveries in Q4
• $31.6M sale of SEG+ rare earth materials to a U.S. aerospace and defense customer contributed to quarterly growth
• Price protection agreement generated $8.1M in additional income
• Rare earth concentrate production declined 3% to 12,887 metric tons
• Initial magnet production ramp-up increased start-up costs to $14.2M from $1.4M YoY
• Nine-month operating cash outflow improved to $7.8M from $108.9M YoY
• Nine-month capital expenditures surged to $420.3M from $110.0M YoY
• Cash and short-term investments declined from $1.83B at year-end 2025 to $1.34B
• Long-term debt stood at $936.3M
⠀
💬 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐂𝐨𝐦𝐦𝐞𝐧𝐭𝐚𝐫𝐲
“Most importantly, we completed the GM qualification process, with saleable magnet deliveries and revenue beginning in the fourth quarter.” - CEO James Litinsky
33
2Semana·
Info
So, the next purchases have been made—here’s a brief overview of the structure.
95% goes into securities, just under 2.5% into gold, and 2.5% into fixed-income securities.
Of that, just under 78% is in ETPs and the remaining 22% in stocks.
As for sector weighting, currently just under 28% is in financials, 22% in information technology, 9% in semiconductors, 8% in real estate stocks, and ~6% in major banks; the rest is further diversified.
What is the goal? Well, part of the goal is to preserve and grow capital—as we all know.
To that end, my father and I decided to use a ready-made ETF ($GERD (-0,98 %) ) that has a weighting of just under 75%. About 5% is in gold and an overnight swap. The remaining 20% consists of individual stocks, such as $MP (-7,71 %) ,$PG (+2,15 %) ,$JNJ (-1,13 %) , $CAT (-4,11 %) or even $KHC (+0,09 %) .
How do we determine which stocks to include in the portfolio—specifically, the background stocks required for Ki, such as $MP (-7,71 %)
$CMS (+0,83 %)
$CRWD (-2,63 %)
$RKLB (-5,01 %)
$SYM (-0,99 %) and $AVGO (-2,54 %) . The key factors for these companies are, first and foremost, energy consumption, security, raw materials, robotics, and systems.
However, we’ll also include a few standard holdings in the portfolio, such as $SHEL (-1,14 %)
$MCD (+1,26 %)
$TSLA (-2,36 %)
$CVX (-1,12 %) or $BAC (-1,56 %) . Since, in our opinion, these are strong and important fundamentals.
As I said, in a few days there will most likely be a portfolio post where you can critique it however you like.
This is currently our decision and strategy, and thanks to it, we’re already up nearly 20k in profit since our first purchases this week.
Best regards. ✌🏻
66
17 Comentarios
Epi@Epi
2Semana
•
1313
•Ver todas las 4 respuestas adicionales

3Semana·
Watchlist
Hey everyone, which stocks on your watchlist are at the top of your list right now? For me, they would be:
$AAK (-0,75 %) (Additional purchase)


3Lun·
Gains
$AXTI (-6,27 %) 18%
$MP (-7,71 %) 19%
$COHR (-5,45 %) 24%
All of them sold yesterday.
+20k$
Not bad 👌
$NBIS (-4,39 %) already with a stop loss on more 5,5k gains.
22

3Lun·
MP Materials Great Results, But I’m Still Not Convinced
I’ve been holding MP Materials for quite some time and this is probably one of the positions I’ve found hardest to make a decision on.
The Q2 results were actually much better than I was expecting. Revenue increased 89% YoY to $108.5M, adjusted EBITDA turned positive at $28.5M, NdPr production increased 41% and NdPr sales more than doubled. The magnetics business in Texas also generated $16.5M in revenue and $7.5M in adjusted profit.
On top of that, MP continues to benefit from US price support and signed another agreement with a US aerospace and defense customer.
So, looking at the business itself, I have to admit that the latest results were encouraging.
And this is exactly what makes the decision to sell difficult.
I originally planned to liquidate my position and use the capital elsewhere, mainly because I felt there were better opportunities in my portfolio and because MP still carries a lot of execution risk. I’m also sitting on a significant loss, which obviously makes the decision psychologically harder.
But after these results, I’m starting to question whether selling now would simply mean giving up on the thesis just as some of the pieces are beginning to fall into place.
The Texas magnetics operation is starting to contribute, processing revenues are growing rapidly, EBITDA has turned positive and the company is becoming more vertically integrated.
At the same time, there are still plenty of uncertainties. The business remains exposed to rare earth prices, government support, execution risk and the huge capital requirements involved in building the full supply chain.
So I’m genuinely undecided.
33

3Lun·
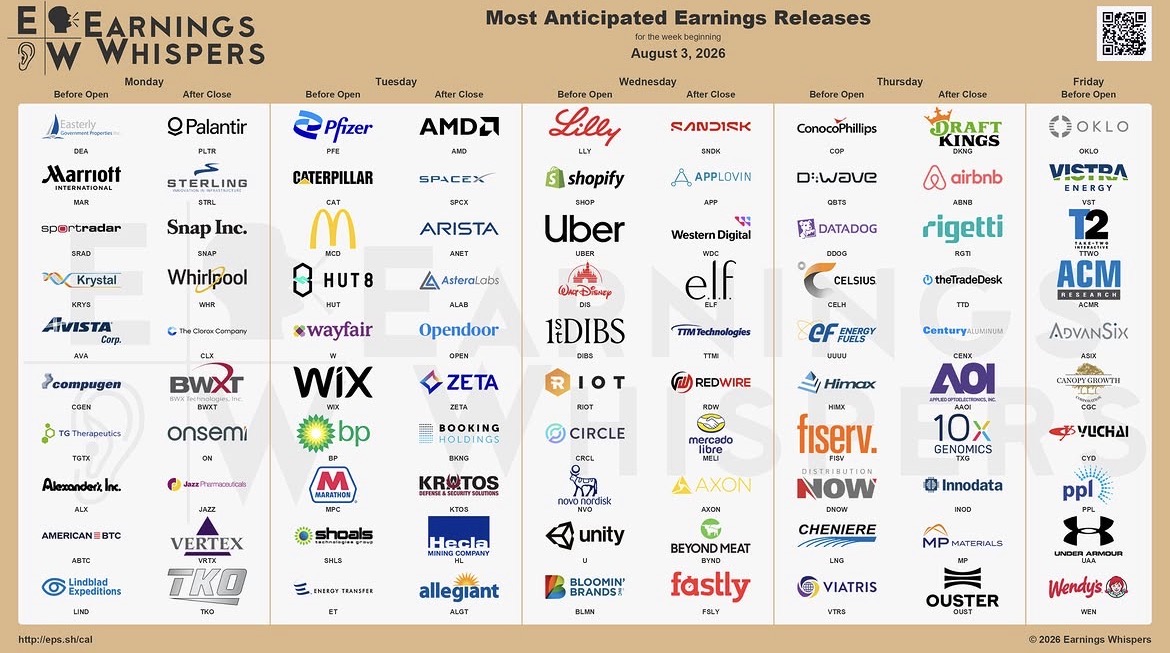
Let's move on to the next round!
$MAR (+1,72 %)
$KRYS (-2,13 %)
$PLTR (-3,58 %)
$STRL (-9,05 %)
$SNAP (-2,95 %)
$WHR (-2,53 %)
$CLX (+0,99 %)
$BWXT (-4,67 %)
$ON (-3,09 %)
$VRTX (+0,07 %)
$PFIZER
$CAT (-4,11 %)
$MCD (+1,26 %)
$HUT (-5,88 %)
$WIX (-0,82 %)
$W (-0,49 %)
$BP. (-1,23 %)
$SHLS
$AMD (-4,07 %)
$SPCX (-0,12 %)
$ANET (-4,61 %)
$ALAB (-6,7 %)
$OPEN (-3,74 %)
$ZETA (-0,61 %)
$BKNG (-0,9 %)
$KTOS (-5,85 %)
$HL (-6,14 %)
$LLY (-0,39 %)
$SHOP (+1,36 %)
$UBER (+0,81 %)
$DIS (+0,27 %)
$RIOT (-1,02 %)
$CIRC
$NOVO B (+0,08 %)
$U (-1,09 %)
$SNDK (-6,94 %)
$APP (+1,82 %)
$WDC (-3,04 %)
$ELF (+1,47 %)
$MELI (-1,77 %)
$AXON (-2,26 %)
$TTMI (-7,07 %)
$RDW (-7,97 %)
$QBTS (-8,16 %)
$DDOG (-5,59 %)
$CLA (+0 %)
$FI (-0,87 %)
$LNG (-1 %)
$UUUU (-7,73 %)
$HIMX (-7,67 %)
$ABNB (+0,3 %)
$RGTI (-4,84 %)
$TTD (-4,88 %)
$AAOI (-7,94 %)
$TXG (-4,27 %)
$INOD (-7,7 %)
$OUST
$MP (-7,71 %)
$OKLO (-3,7 %)
$VST (-1,94 %)
$TTWO (-5,49 %)
$ACMR (-8,05 %)
$WEED (-1,96 %)
$UAA (-0,9 %)
2525
13 Comentarios
And all this while on vacation🫣😂😭
•
1010
•

5Lun·
"Rare earths" the next big investment theme?
An electric car needs up to 2 kg of rare earths for the motor alone. Wind turbines, smartphones, semiconductors, military technology and much more - literally nothing without these raw materials.
The problem for the West: at times, China controlled over 80% of global production. Export restrictions are not a worst-case scenario, they are already a reality. And Western supply chains therefore have demonstrable weak points.
This is precisely where it becomes interesting for investors: North America, Europe and Australia are building up their own capacities in a targeted manner. Subsidized, politically desired, structurally necessary. If production increases more slowly than technology-driven demand, prices can rise sharply.
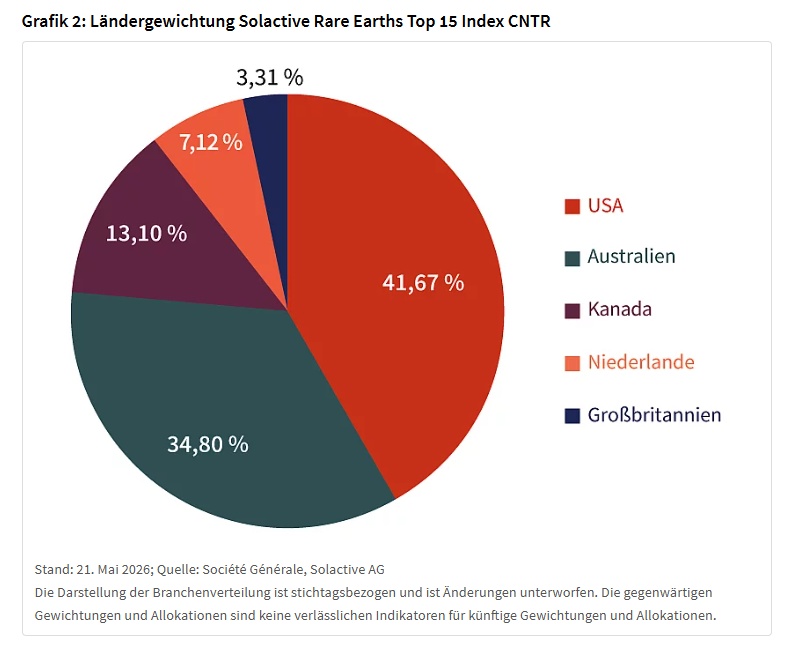
The very new Solactive Rare Earths Top 15 Index tracks 15 companies along the entire value chain - from $LYSDY (-1,85 %) (Australia) to $MP (-7,71 %) (USA), exclusively from Western markets, rule-based selection with AI data analysis.
The current ideas magazine analyzes the topic in detail: Opportunities, risks, index methodology and specific investment opportunities.
This article is part of an advertising partnership with Société Générale
1111
8 Comentarios5Lun
Rare earths have been the next big investment theme for 15 years. 😅
•
1212
•

5Lun·
Analysis of rare earths
17 chemical elements
Strategic metal age
Scarcity as a political factor
Lynas Rare Earths
Iluka Resources
Arafura Rare Earths
MP Materials
Energy Fuels and others
Solactive Rare Earths Index
Link: https://shorturl.at/KPyWG
$LYC (-3,4 %)
$ILU (-5,68 %)
$ARU (+1,2 %)
$MP (-7,71 %)
$UUUU (-7,73 %) $
77

8Lun·
Arafura Rare Earth - a chance? A bet? Or is the risk too high?
Arafura Rare Earths (ASX: ARU) - Rare earths project of the future with great potential?
Arafura Rare Earths is an Australian resource developer focused on rare earths, particularly neodymium and praseodymium (NdPr), which are critical for high performance magnets in electric cars, wind turbines, robotics and defense technologies - exactly where the global energy mix is being transformed towards electric mobility and renewable energy.
Core project:
Nolans Project
The Nolans Project in Australia's Northern Territory is the centerpiece of Arafura Rare Earths.
Location & Scope
- Location: approx. 135 km north of Alice Springs
- Resource: around 56 million tons of ore with an average of approx. 2.6% rare earth oxides
- Main objective: Production of NdPr oxides - the most important raw material for high-performance magnets
The project is one of the most advanced rare earth developments outside China.
Integrated value chain
Arafura is planning fully integrated "mine-to-oxide" production - this means that not only mining, but also preparation and chemical processing will take place at the site. This means that the company would not just sell a concentrate, but produce marketable oxides directly. Although this approach increases investment costs, it creates significantly more added value and strategic importance.
Planned production
- Target production: approx. 4,400-4,500 tons of NdPr oxides per year
- Planned mine life: around 35-40 years
- Production start: after final financing and construction phase in the second half of this decade
In full operation, Nolans could cover around 4% of global NdPr demand. In view of the strong dominance of Chinese suppliers in the rare earths sector, this is of considerable geopolitical importance.
Financing and strategic partners
The development of such a project requires investments in the billions. Accordingly, financing was one of the key milestones.
Capital measures
Arafura has carried out extensive capital increases, including a large placement in the region of several hundred million Australian dollars. These measures led to a significant increase in the number of shares and thus to dilution effects for existing shareholders. In the short term, this had a negative impact on the share price, but in the long term it was a necessary step towards project implementation.
Strategic investments
An important signal was the entry of Gina Rinehart via its investment company Hancock Prospectingwhich significantly increased its stake. Such an investment is often interpreted in the market as a sign of confidence in the economic viability of the project.
State support
In addition, Arafura received support from the National Reconstruction Fund Corporationwhich made a substantial investment commitment. The aim is to promote critical mineral projects in Australia and reduce dependence on individual supplier countries.
Market environment: Why NdPr is so crucial
Neodymium and praseodymium are central components of permanent magnets, which are indispensable in the following areas:
- Electric vehicles
- wind turbines
- industrial automation
- defense technology
With the global expansion of renewable energies and electromobility, the demand for high-performance magnets is constantly increasing. At the same time, Western countries are seeking to diversify their supply chains for critical raw materials. This is precisely where Arafura is positioning itself as a potential strategic supplier outside China.
Opportunities
- Strategically extremely important raw material with structural growth in demand
- Project in a politically stable country
- Fully integrated production with higher added value
- Long-term mine life of several decades
- Institutional and government support
If the project is implemented as planned and NdPr prices remain at an attractive level, Arafura has significant upside potential.
Risks
- No operational production yet and therefore no cash flow
- High capital requirements and possible further dilution
- Construction and schedule risks for major projects
- Volatile prices for rare earths
- Competition from established suppliers, particularly from China
Arafura therefore remains a classic project developer with a corresponding opportunity/risk profile. The investment case stands and falls with the successful commissioning of Nolans.
How do you see the opportunities? I am invested and convinced 👍

55
7 Comentarios
•
22
•Valores en tendencia
Principales creadores de la semana
Datos LSX · Datos fundamentales y de cierre diario de FactSet