
Nebius Group NV
Price
Debate sobre NBIS
Puestos
238


Podcast Episode 173: "Buy High. Sell Low." Subscribe to the podcast so that Nvidia's stock will rise again.
00:00:00 Tax increases, tax office
00:05:50 Market environment
00:28:04 Anthropic IPO $ANT (-16,71 %)
00:47:20 Nebius $NBIS (-8,17 %)
01:37:40 Nvidia $NVDA (-3,09 %)
01:56:56 Good news
Spotify
https://open.spotify.com/episode/336jnuOGsPWNiYGWe3D6cM?si=upIfQ7dHQvOYFyuf2mjfZg
YouTube
https://openyoutu.be/Gxfu69izK3Y
Apple Podcast
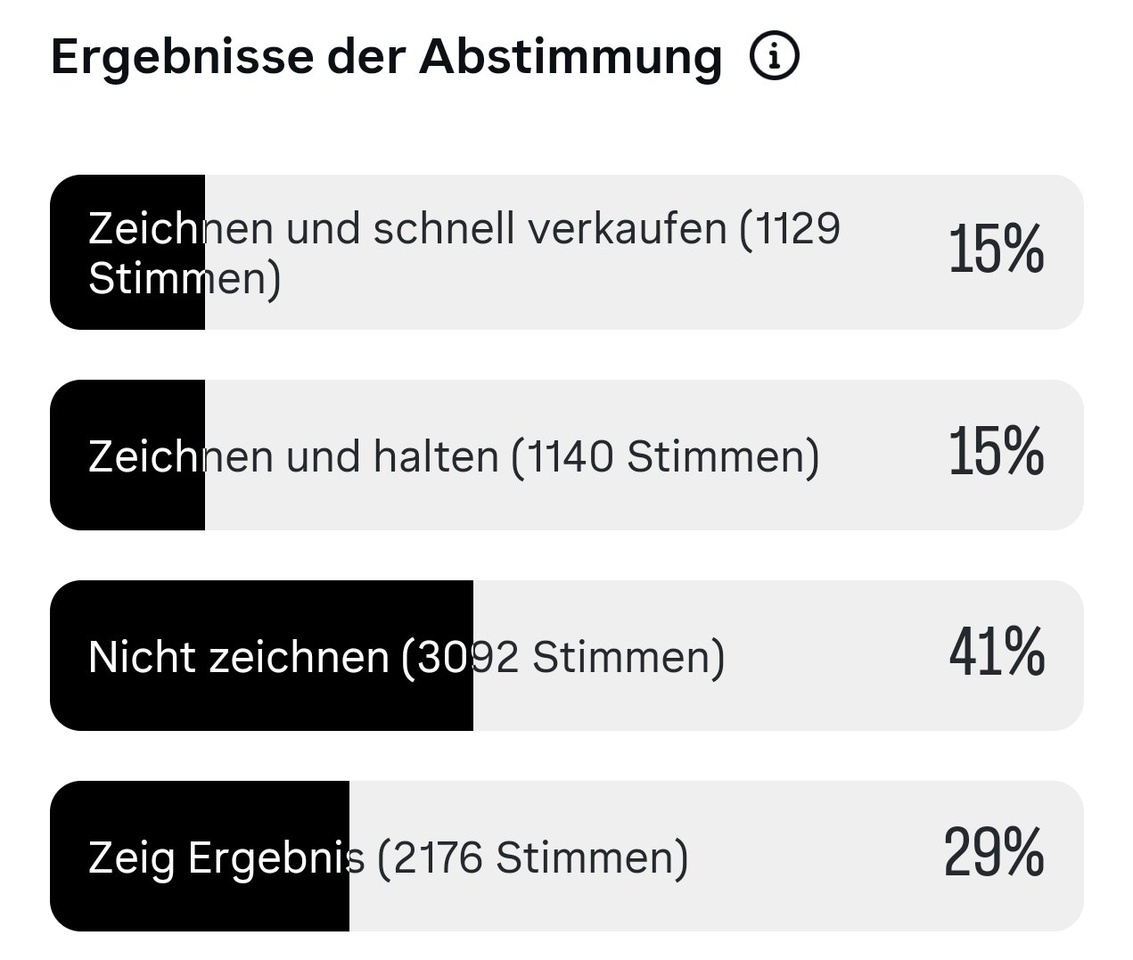
Poll: What will you do when Anthropic goes public?
I'm going to skip Anthropic. I already own SpaceX, a lot of AMD, Galaxy Digital, and Nebius from the AI sector.
You can subscribe until Wednesday, November 18, at 6:00 p.m. Please note that, as with SpaceX, you may only receive about 10–20% of the invested amount in shares.
With SpaceX, the stock rose 49% in the first three trading days. This time, the gain might be smaller because the Anthropic CEO has less star power than Elon Musk and doesn’t have rockets or Starlink. If you don’t plan to hold for the long term but are speculating on a quick profit during the IPO pop, it might be a good idea to sell when the price is up 25–30%.
According to surveys, 24% to 30% of my subscribers plan to subscribe.
Results from Instagram below.
$ANT (-16,71 %)
$AMD (-8,46 %)
$NBIS (-8,17 %)
$SPCX (-3,85 %)
$GLXY (-7,52 %)


Which tech stocks stand to benefit?
When the AI boom subsides. In my opinion, the biggest beneficiaries will be the hyperscalers such as $GOOGL (-2,91 %) , $AMZN (-3,91 %) , $MSFT (-1,68 %) . Because when the boom subsides and delays occur, the hyperscalers will return to positive cash flows thanks to lower Capex expenditures. And after the initial shock, their stocks will benefit again. At risk are stocks such as $CRWV (-6,07 %) , $NBIS (-8,17 %) , $IREN (-5,55 %) and, of course, chip suppliers, memory manufacturers, etc.


Today in the Wall Street Journal... Who is Colette Kress?
Here’s a recent report on Colette Kress, Nvidia’s new interim CEO. It’s clear that she has views that are completely different from Jensen Huang’s—especially when it comes to the controversial vendor financing. That’s exactly why I believe we’re in for a big surprise when the earnings are released next Tuesday.
Events surrounding Nvidia are unfolding rapidly these days. Following the abrupt departure of founder and CEO Jensen Huang, the chip giant is facing a historic turning point. While the stock market is eagerly awaiting Tuesday’s quarterly earnings, a recent report in the Wall Street Journal has brought to light just how fiercely things have recently come to a head behind the scenes due to the enormous financial risks.
The Internal Clash: Vision vs. Ironclad Financial Discipline
In recent years, Nvidia has operated not only as a chip manufacturer but, thanks to so-called vendor financing , it has also functioned as a sort of private central bank for the AI industry. To keep demand high and enable emerging cloud providers to purchase the extremely expensive hardware, guarantees and credit facilities totaling astronomical sums were granted.
But it was precisely at this point that internal resistance emerged. According to the Wall Street Journal , Colette Kress openly questioned the wisdom and the enormous default risks of these billion-dollar deals during a board meeting last August. She demanded strict criteria for return on investment (ROI).
Jensen Huang’s reaction was brutal: He reportedly called the experienced CFO a “deer in the headlights” (“deer in the headlights”) and accused her of being too nervous about the risks.
Actions Speak Louder Than Words: Kress Cuts Back on Billion-Dollar Deals
However, Kress proved she wouldn’t be intimidated not only through her words but, above all, through her decisions:
- During negotiations for a massive OpenAI data center project in Ohio, she prevailed against the original plans and without hesitation cut Nvidia’s financial guarantee in half, from 250 billion to 105 billion U.S. dollars.
- Some of the riskier, revenue-based financing structures were put on hold for the time being with her involvement.
Given supply and purchase commitments totaling over $530 billion across the entire group, this marks a fundamental shift: away from the unconditional expansion and hype-driven policies under Huang, toward rock-solid risk management.
What this means for next Tuesday
On Tuesday, Colette Kress will face her first major test as interim CEO. Given stalled data center approvals in the U.S., full chip inventories, and looming export restrictions on the crucial Asian business, the stage is set for a reality check.
Anyone expecting Kress to throw borrowed money around in her usual style on Tuesday and artificially fuel optimism is likely to be disappointed. As a rational CFO who has sharply criticized the risks of “vendor financing” internally, she has all the tools at her disposal to ground the forecasts on a conservative foundation.
The question is no longer whether Nvidia’s fundamentals are changing—they have already changed. The question is how candidly Kress will disclose this shift on Tuesday. Personally, I don’t think she’ll say, “Business as usual.” However, the biggest losers next week will likely be the “neoclouds,” which have relied—and continue to rely—on Nvidia’s deep pockets.
$NVDA (-3,09 %)
$CRWV (-6,07 %)
$NBIS (-8,17 %)
$IREN (-5,55 %)


Q3 NEBIUS 🪄
Double beat for $NBIS (-8,17 %) ✅
+571% YoY
$980.8M revenue
But:
~$325M non-recurring
Capex keeps rising
ARR target pushed to February
Demand is there.
Execution is the key.
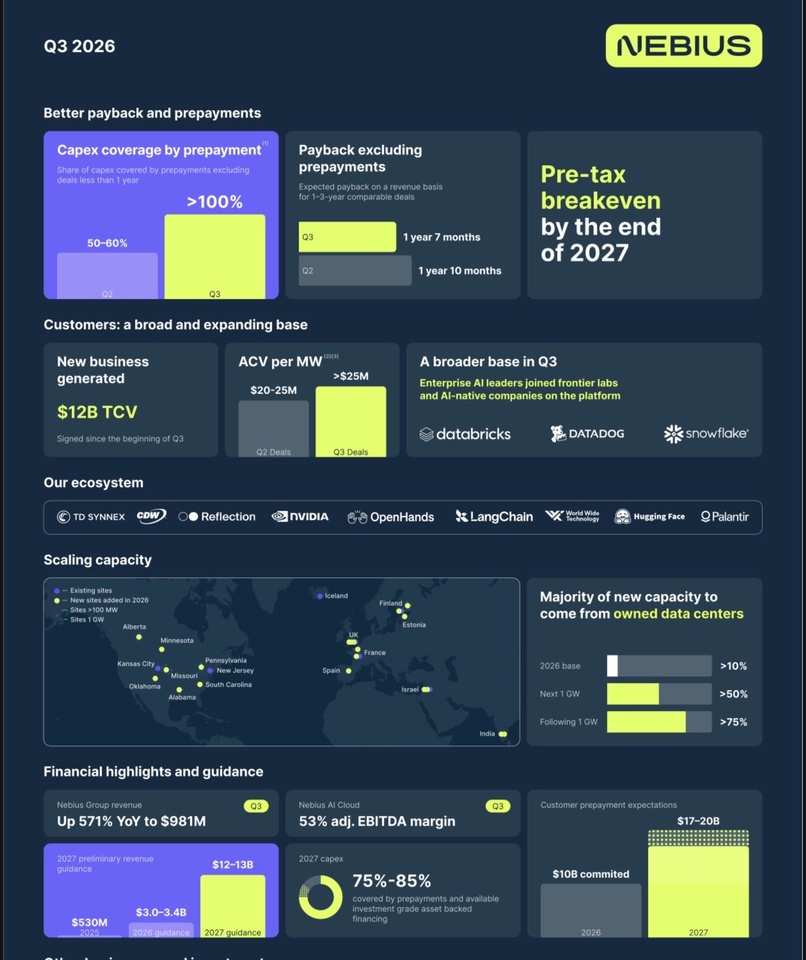

𝐍𝐞𝐛𝐢𝐮𝐬: 𝐐𝟑 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝐁𝐞𝐚𝐭𝐬 𝐄𝐬𝐭𝐢𝐦𝐚𝐭𝐞𝐬, 𝐒𝐮𝐫𝐠𝐞𝐬 𝟓𝟕𝟏% 𝐘𝐨𝐘, 𝐀𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐄𝐁𝐈𝐓𝐃𝐀 𝐑𝐞𝐚𝐜𝐡𝐞𝐬 $
⠀
📊 𝐑𝐞𝐬𝐮𝐥𝐭𝐬
• Revenue: $980.8M (Est. $907.17M) ✅, +571% YoY.
• Adjusted EBITDA: $465.8M (vs. -$5.2M YoY).
• Adjusted EBITDA Margin: 47.5%.
• GAAP Net Loss from Continuing Operations: $37.5M (vs. $119.6M loss YoY).
• Adjusted Net Income: $90.9M (vs. $100.4M loss YoY).
• Operating Income: $50.4M (vs. $130.2M loss YoY).
• Operating Cash Flow: -$273.0M.
• Capital Expenditures: $7.30B.
⠀
📌 𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
• Q3 revenue exceeded consensus by ~8.1%, increasing nearly 6.7x YoY.
• Adjusted EBITDA swung from a $5.2M loss to a $465.8M profit, representing a 47.5% margin.
• GAAP operating profitability turned positive at approximately $50M, compared with a $130M loss a year earlier.
• GAAP net loss narrowed 69% YoY to $37.5M.
• Quarterly capital expenditures surged to $7.3B, up 664% YoY, reflecting aggressive infrastructure expansion.
• Nine-month capital expenditures reached $15.43B.
• Operating cash flow remained negative at $273M despite strong adjusted EBITDA.
• Depreciation and amortization increased 258% YoY to $354.7M.
• Product development expenses increased 164% to $118.6M, while SG&A rose 165% to $237.4M.
• Nine-month revenue reached $1.96B, up 549% YoY.
• Nine-month adjusted EBITDA reached $831.5M, compared with a $79.9M loss a year earlier.
• Consolidated results include Nebius AI Cloud, Avride and TripleTen.
⠀
💬 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐔𝐩𝐝𝐚𝐭𝐞
• CEO Arkady Volozh published a separate quarterly shareholder letter alongside the earnings release.


CoreWeave: Demand Ten Times Higher Than Capacity & 100% Prepayments
$CRWV (-6,07 %) Key Takeaways from the Earnings Call:
– Mike Intrator (CEO): By the end of 2027, there will be 10 times more qualified demand than available capacity. 2027 is largely sold out. Capacity for 2028 has not even officially hit the market yet, but demand for it is already several times the supply.
– Prepayments: In 70% of this year’s deals, customers paid in advance, in some cases up to 100% of the contract value. Over the next three months, CoreWeave expects approximately $9 billion in prepayments and down payments.
– Price increases: In July, prices across all GPU types rose by about 25%, followed by a further 10% later in the quarter. They will continue to rise in the fourth quarter.
– Rental rates per megawatt:
Short-term contracts: over $40 million per MW per year
New four- to five-year contracts: $20–25 million per MW per year
– Older GPUs are becoming more expensive: Nvidia’s Ampere and Hopper chips $NVDA (-3,09 %) were rented out at rates 30–50% higher this quarter than in the previous quarter, now exceeding the original contract price.
– Expiring contracts: Over 130,000 GPUs will become available in 2027, with another 170,000 or so in 2028. At current prices, this could generate nearly $10 billion in additional annual revenue without new investments.
– Financing: Interest expense totaled $846 million, and the net loss was $709 million. By 2027, CoreWeave aims to raise less than $5 billion in new capital at the corporate level and, at current yields, does not plan to issue unsecured bonds.
$NBIS (-8,17 %)$IREN (-5,55 %)$ORCL (-3,11 %)$MSFT (-1,68 %)$GOOGL (-2,91 %)$AMD (-8,46 %)
Valores en tendencia
Principales creadores de la semana