
⠀
📊 𝐑𝐞𝐬𝐮𝐥𝐭𝐬
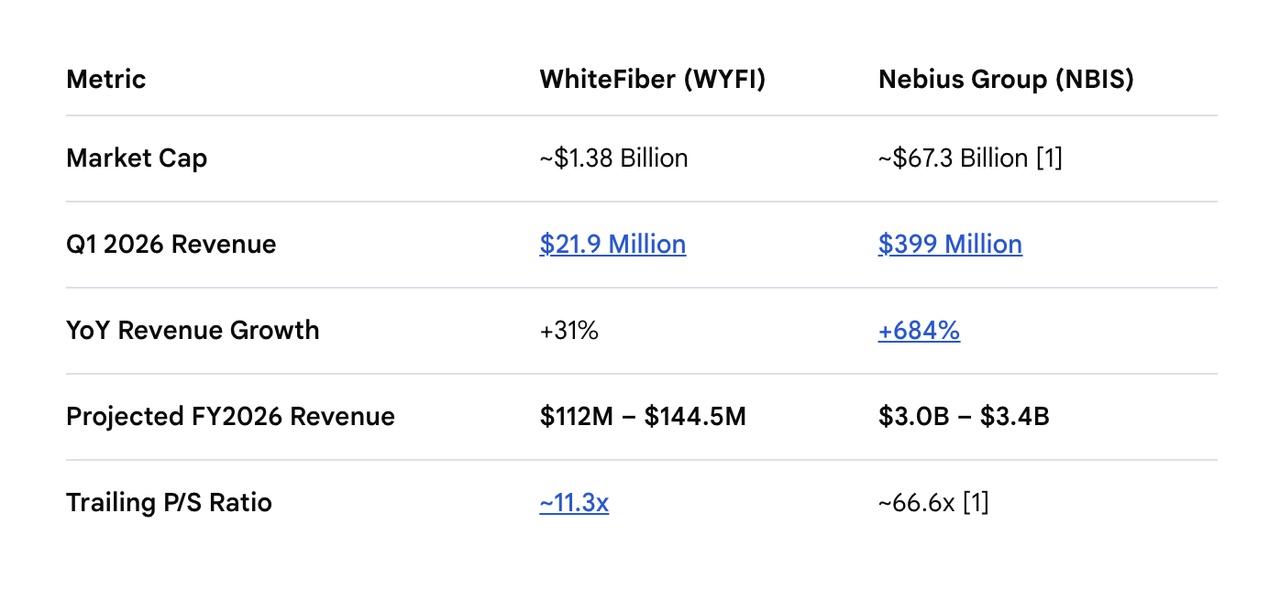
• Revenue: $24.0M (Est. $30.19M) ❌, +19% YoY.
• GAAP EPS: -$2.44 (Normalized Est. -$0.30, not directly comparable).
• Net Loss: $101.4M (vs. $15.8M loss YoY).
• Operating Loss: $12.4M (vs. $14.5M loss YoY).
• Adjusted EBITDA: Approximately breakeven (vs. $2.3M YoY).
• Cloud Services Revenue: $18.1M, +0.4% YoY.
• Colocation Revenue: $5.6M, +232% YoY.
• Gross Margin Excluding D&A: 56.9%.
• Cash & Restricted Cash: $147.6M.
⠀
🎯 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
• Cloud Services Annualized Revenue: ~$365M at full deployment, targeted for mid-2027.
• NC-2 & NC-3: Initial service readiness targeted for late 2027.
• NC-2 & NC-3: Potential expansion to ~200 MW within seven years, subject to power availability.
⠀
📌 𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
• Q3 revenue missed consensus by ~20.5%, reflecting delays in the NC-1 capacity ramp.
• NC-1's full 40 MW of contracted IT capacity is now operational and billing has commenced.
• Signed >$700M in new cloud services contracts across five customers since August, including its first capital-light managed services agreements.
• New contracts support a targeted ~$365M annualized cloud revenue run rate by mid-2027, subject to deployment and financing.
• Secured a $300M NC-1 credit facility, including $200M in initial term loans and $100M in delayed-draw capacity, with funding still subject to conditions.
• Acquired NC-2 and NC-3 for $60M, targeting at least 60 MW of initial gross utility capacity.
• NC-2 and NC-3 customer discussions include non-binding proposals from investment-grade counterparties.
• Remaining Performance Obligations totaled $729M, with an additional $421.5M in future lease payments excluded from RPO.
• Net loss included an $80.8M non-cash convertible note conversion expense.
• Completed a $310M convertible note offering and exchanged ~$198M of existing notes, extending debt maturities.
• Deferred revenue reached $306M, primarily reflecting customer prepayments.
• Launched WhiteFiber Continuum, connecting geographically separated data centers into logical GPU superclusters.
⠀
💬 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐂𝐨𝐦𝐦𝐞𝐧𝐭𝐚𝐫𝐲
“Our third-quarter results reflect the delayed NC-1 ramp, while much of our newly contracted cloud business is preparing to enter service.”