
Thanks for the introduction!
Inditex
Stock
Stock
ISIN: ES0148396007
Ticker: ITX
ES0148396007
ITX
Price
Discussion about ITX
Posts
151Wk·
And First Steps at Inditex
7Mon·
Inditex: Strong brands with young customers - solid business figures
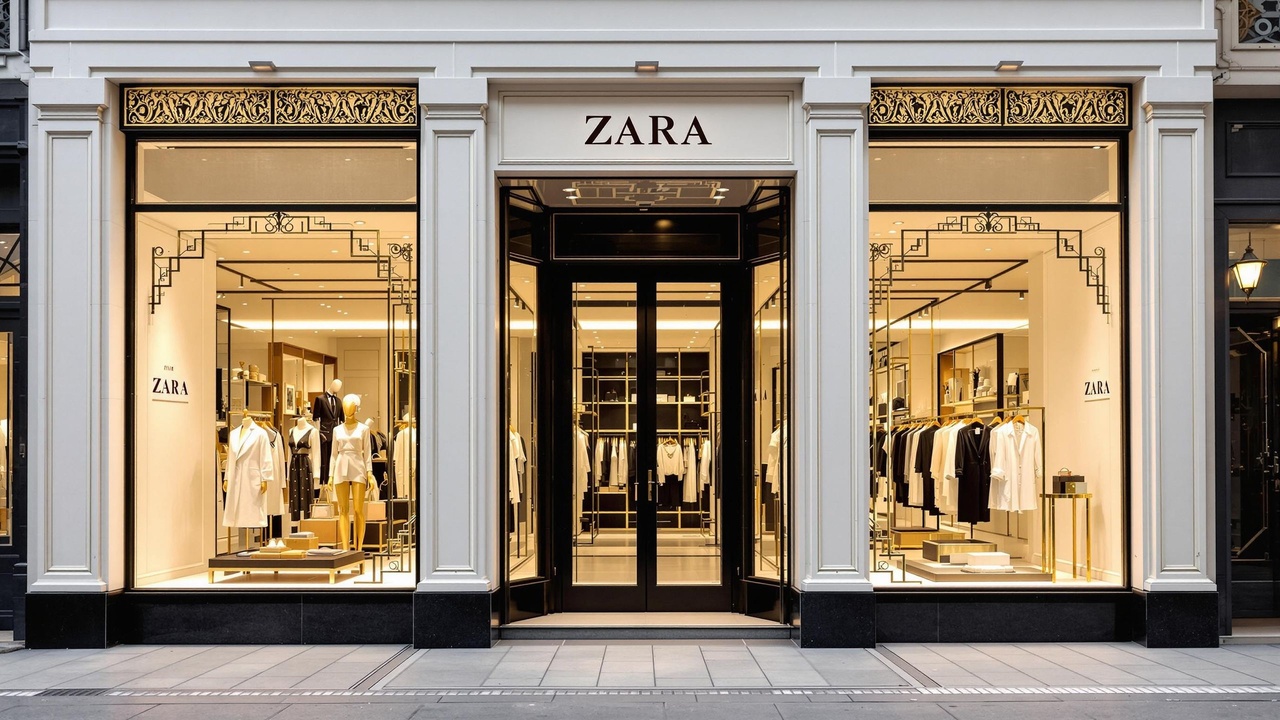
One point that I think Inditex $ITX (+2.74%) I think is often underestimated is the enormous strength of the brands with young consumers. Especially for people in their twenties - students or young professionals - fashion is important but must remain affordable. This is exactly where Inditex hits the nerve of the times. Brands such as Zara, Bershka and Stradivarius offer trendy clothing at relatively moderate prices and react extremely quickly to new fashion trends.
I particularly noticed this on a trip to Lisbon: In many shopping streets, Stradivarius, Zara, Massimo Dutti and Bershka are right next to each other - and all three stores were full. This shows how well the brand portfolio works. The brands don't really compete with each other, but cater to different tastes within the same target group. For me, this is exciting from an investor's point of view because Inditex has created an entire fashion ecosystem for young shoppers.
Financial year 2025: solid growth and high profitability
Inditex once again reported solid results for the 2025 financial year (February 1, 2025 to January 31, 2026). Sales increased by 3.2% to 39.9 billion euros. In constant currencies, growth was even 7%. Both bricks-and-mortar retail and online business developed positively.
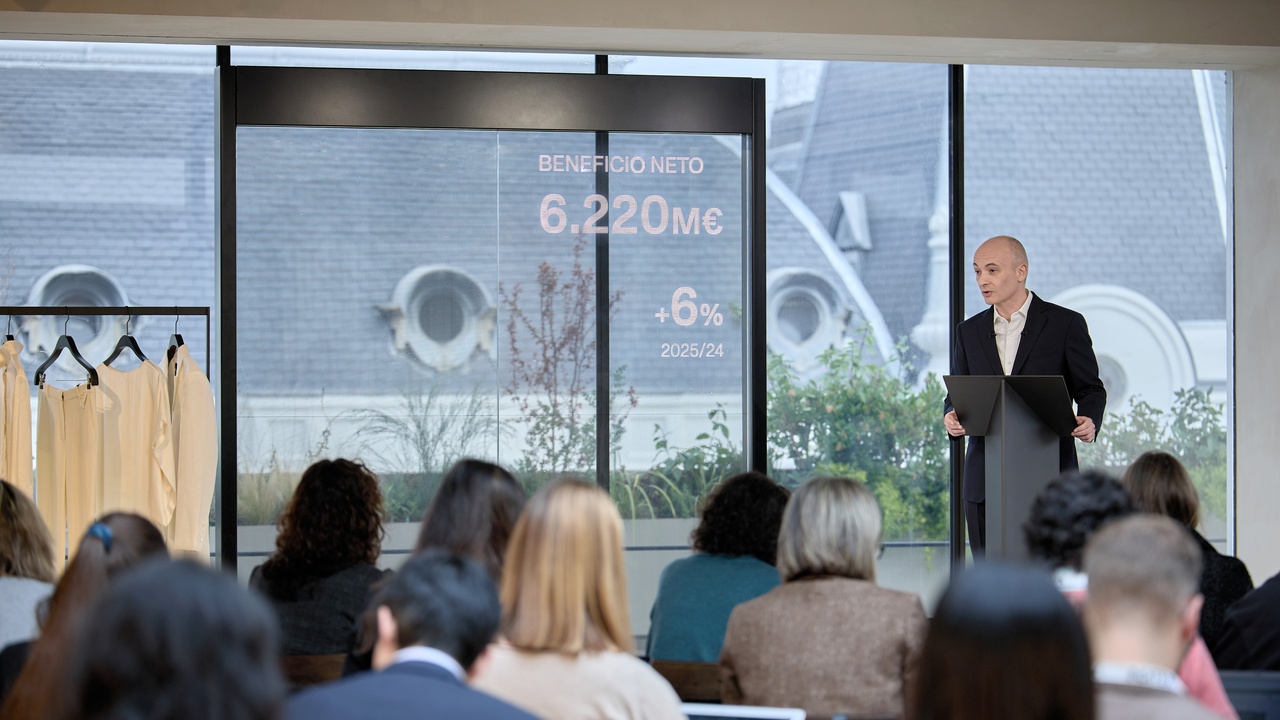
The Group also remained strong on the profit side. Gross profit increased to 23.2 billion euros, with a gross margin of 58.3%. EBITDA rose by 5% to 11.3 billion euros, while EBIT grew by 5.9% to 8.0 billion euros. At the bottom line, Inditex achieved a net profit of 6.2 billion euros, an increase of 6% compared to the previous year.
Another important point is the company's strong balance sheet. Inditex has a net cash position of around 11 billion euros, which gives the company great financial flexibility.
Shareholders also continue to benefit. A dividend totaling €1.75 per share is to be distributed for the 2025 financial year, consisting of a regular dividend of €1.20 and a bonus dividend of €0.55. The payout will be made in two equal tranches in May and November 2026.
Overall, it is clear that even if growth remains moderate, Inditex continues to impress with strong margins, high cash flows and a very robust business model.
1414
4 Comments
DerDanner@Therapeut
1Wk
•
22
•View all 2 further answers

2Mon·
Why Inditex is a Premier Compounder
$ITX (+2.74%)
World-Class Financial Strength: Carrying nearly €11 billion in net cash means Inditex essentially operates with zero balance-sheet risk. It self-funds its store expansions and tech integration completely without relying on debt.
Insane Profitability Engine: A gross margin sitting near 58–61% is almost unheard of for a mass-market apparel business. Their secret weapon is short lead times—they produce in smaller batches near their main markets (Spain, Portugal, Morocco, Turkey), enabling them to adapt to trends in weeks and rarely sell items at clearance discounts.
The "Cherry-Picker's" Dividend: With a stable dividend payout (including extraordinary payouts) yielding roughly 3%, you get paid while holding.
Continued 2026 Acceleration: In Q1 2026, Inditex kept the engine humming with revenues up 5.8% to €8.7B and constant currency sales accelerating into Q2 (+11.5%)
VALUATION:
MetricCurrent Value (2026)
Share Price
~€56.44
Trading near its 52-week highs (€40 - €58 range).
P/E Ratio
~27.5x - 28x
A historical premium. You are paying up for extreme quality.
Dividend Yield
~3.1%
Great passive income component
considering entering here if there is a small pullback to the 50€ area but if not will grab some anyways
55
2 Comments
2Mon
Thx for your analysis on Inditex. Even if it's around its ATH I have it in my trading portfolio.
••
7Mon·
Inditex: Strong brands with young customers - solid business figures
One point that I think Inditex $ITX (+2.74%) I think is often underestimated is the enormous strength of the brands with young consumers. Especially for people in their twenties - students or young professionals - fashion is important but must remain affordable. This is exactly where Inditex hits the nerve of the times. Brands such as Zara, Bershka and Stradivarius offer trendy clothing at relatively moderate prices and react extremely quickly to new fashion trends.
I particularly noticed this on a trip to Lisbon: In many shopping streets, Stradivarius, Zara, Massimo Dutti and Bershka are right next to each other - and all three stores were full. This shows how well the brand portfolio works. The brands don't really compete with each other, but cater to different tastes within the same target group. For me, this is exciting from an investor's point of view because Inditex has created an entire fashion ecosystem for young shoppers.
Financial year 2025: solid growth and high profitability
Inditex once again reported solid results for the 2025 financial year (February 1, 2025 to January 31, 2026). Sales increased by 3.2% to 39.9 billion euros. In constant currencies, growth was even 7%. Both bricks-and-mortar retail and online business developed positively.
The Group also remained strong on the profit side. Gross profit increased to 23.2 billion euros, with a gross margin of 58.3%. EBITDA rose by 5% to 11.3 billion euros, while EBIT grew by 5.9% to 8.0 billion euros. At the bottom line, Inditex achieved a net profit of 6.2 billion euros, an increase of 6% compared to the previous year.
Another important point is the company's strong balance sheet. Inditex has a net cash position of around 11 billion euros, which gives the company great financial flexibility.
Shareholders also continue to benefit. A dividend totaling €1.75 per share is to be distributed for the 2025 financial year, consisting of a regular dividend of €1.20 and a bonus dividend of €0.55. The payout will be made in two equal tranches in May and November 2026.
Overall, it is clear that even if growth remains moderate, Inditex continues to impress with strong margins, high cash flows and a very robust business model.
1212
1 Comment
2Mon
Certainly the most successful and international textile company from Spain. You go to any shopping center and hit one of this. From casual and cheap (Zara) to more high quality (Massimo). One of the big movers of IBEX35 index. Zara does not rent locations, they buy each corner and have huge investments in every big city they make business. Stark!
•
11
•
7Mon·
INDITEX FY 2025 RESULTS SUMMARY
📊 Key Financial Metrics
• 🟢 Revenue: €39.9B (+3.2% YoY | +7% constant FX)
• 🟢 EBITDA: €11.27B (+5%)
• 🟢 EBIT: €7.99B (+5.9%)
• 🟢 Net Profit: €6.22B (+6%)
• 🟢 Gross Margin: €23.22B (58.3%)
• 🟢 Dividend: €1.75/share (incl. €0.55 extraordinary)
🧱 Operational Performance
• 🟢 Sales growth remains strong despite FX headwinds.
• 🟢 Operating expenses grew +2.8%, below revenue growth.
• 🟢 Strong operating leverage driving profit expansion.
💰 Financial Strength
• 🟢 Net Cash: €10.96B
• 🟢 Cash generation remains very strong.
• 🟢 One of the strongest balance sheets in global retail.
🚀 Strategic Execution
• 🟢 Fully integrated store + online model continues to outperform.
• 🟢 Continued optimization of the store network.
• 🟢 Significant investment in technology and logistics.
🔮 2026 Outlook
• 🟢 Sales growth +9% (Feb 1 – Mar 8 at constant FX).
• 🟢 Retail space expected to grow ~5% in 2026.
• 🟢 €2.3B investment plan focused on store optimization and digital platforms.
Summary
Inditex continues to deliver a very strong operational performance, with record levels of sales, EBITDA and net profit. The company combines disciplined cost control, strong cash generation and a highly scalable omnichannel model. With €10.9B in net cash and continued investment in store optimization and digital platforms, Inditex remains one of the most profitable and resilient global retailers.
22
7Mon·
Pain in Spanish stocks
$IBE (-0.26%)
$ITX (+2.74%)
$VIS (-0.09%)
From BBC:
US President Donald Trump and German Chancellor Friedrich Merz's White House news conference has now finished.
- On Spain, he says is "going to cut off all trade" with the country, adding that he has told Treasury Secretary Scott Bessent to "cut off all dealings"
If you ask yourself why… Here is why:
“Spain's prime minister says he's clear. Pedro Sanchez took to social media, proclaiming "one can be against a hateful regime, as is the case with the Iranian regime… and at the same time be against an unjustified, dangerous military intervention outside of international law".
A number of US aircraft left Spain on Monday after Madrid said those bases could not be used for attacks on Iran.”
Time to buy more i gues….
www.bbc.comWhy Europe's leaders have struggled to speak as one on Iran
22
2 Comments
7Mon
If DT is furious about a person, than there is a high chance that this person is doing a good job :)
•
66
•
9Mon·
Comparison of three heavyweights
$$ABF (+1.74%) ;$ITX (+2.74%) ; $HM B (+1.82%)
1. inditex (Zara): The "beacon" of the sector
Inditex remains the undisputed favorite of investors in January 2026. While ABF struggles with stock levels, Inditex shares reached a new 10-year high of around EUR 57.48 on January 12, 2026.
Growth: In the first weeks of the new financial year (Nov. to Dec. 2025), sales rose by an impressive 10.6% on a currency-adjusted basis.
Margin strength: With a gross margin of almost 60%, Inditex is significantly more profitable than Primark (approx. 10% operating margin).
Logistics advantage: By producing close to the sales markets, Zara can implement trends more quickly and thus avoid the massive discount rounds that hit ABF in January.
2 H&M: Between the stools
The H&M share shows moderate weakness in January 2026, but is not under as much fire as ABF.
Analyst skepticism: Bernstein Research downgraded H&M to "Underperform" on January 6, 2026 (almost at the same time as ABF). The fear: H&M could be hit by the consumer slump in Central Europe in a similar way to Primark.
Support measures: An ongoing share buyback program (until 28 January 2026) has so far prevented a deeper fall in the share price.
Waiting for January 29: Investors are cautious as the company presents its annual report at the end of the month.
3. why ABF (Primark) performed worse
The main difference with Inditex and H&M in January 2026 lies in two factors:
Lack of online leverage: Primark is still almost entirely reliant on bricks-and-mortar retail. If footfall in Europe falls (as observed in Jan '26), ABF will be hit harder than its digitally better positioned competitors.
Conglomerate risk: In contrast to the pure fashion chains, ABF was additionally burdened by the weak US grocery business (edible oils/baking ingredients) - a problem that Zara and H&M do not have.
Source Gemini
33

9Mon·
Portfolio reconstruction 2026
I have now decided to restructure my portfolio in the coming days. It will then consist of these stocks.
Core:
1) the MSCI World $IWDA (+0.45%)
2) the MSCI EM IMI $EIMI (-0.13%)
3) the VanEck Morningstar $TDIV (+1.36%)
4) Bitcoin $BTC (-0.18%)
Satellites:
1) Microsoft $MSFT (-0.45%)
2) Amazon $AMZN (+0.14%)
3) Nvidia $NVDA (+1.51%)
4) MasterCard $MA (+0.16%)
5) Adobe $ADBE (+3.18%)
6) Ferrari $RACE (+1.29%)
7) Novo Nordisk $NOVO B (+2.17%)
8) Realty Income $O (+1.21%)
9) Wolters Kluwer $WKL (-0.32%)
10) Brown & Brown $BRO (+2.7%)
11) Inditex $ITX (+2.74%)
12) Uber $UBER (-1.78%)
13) Main Street Capital $MAIN (+0.44%)
14) Vici $VICI (+1.09%)
15) PayPal $PYPL (+0.86%)
In addition to my core of the 3 ETFs and Bitcoin, I think this mix of growth & dividend-focused stocks is really good. What do you guys think about this long term portfolio? Should be held for a long time, 20+ years... I don't think much of the short term. Of course, profits are taken from time to time, but nothing is sold completely and in the event of corrections we buy more! 🤑🔥🙏
I look forward to your suggestions / criticism.
Wishing you a Merry Christmas 🌲☺️
2828
5 Comments
•
1212
•9Mon·
Less is more, or what was that?
Hi everyone,
I would really appreciate your opinion on my portfolio.
Briefly about me:
I am 38 years old and unfortunately only started my Trade Republic portfolio about 2 years ago. I have been investing regularly since then. I can currently invest around €350 per month - I work in a gym 🥲, and unfortunately you don't earn very well there, you could almost call it a pittance.
In addition, I have my Bitcoin and Altcoin portfolio on Bitvavo... I can't share it here, too many errors in the coins and you can still change it somehow. I then deleted the connection again.
I played soccer until I was 32 (including 3rd league, mostly 4th league for many years) and was able to save up some capital during this time, which I later invested.
My long-term core consists of:
Dividend / cash flow portfolio
I also have a portfolio with a focus on cash flow, the aim is to hold around 15 stocks with a solid dividend yield and ideally dividend growth.
Currently included are:
$O (+1.21%) Realty Income
$RACE (+1.29%) Ferrari
$PEP (+0.21%) Pepsi
$MAIN (+0.44%) Main Street Capital
$NOVO B (+2.17%) Novo Nordisk
$ASML (-0.97%) ASML
$ITX (+2.74%) Inditex
$1211 (+0.63%) BYD
$ZTS (+0.34%) Zoetis
$BRO (+2.7%) Brown & Brown
$SBUX (+1.21%) Starbucks
$ITH (-0.2%) Ithaca Energy PLC
This brings my current total to 12 shares, so there is still room for one or two additions.
One of the stocks on my watchlist is Vonovia $VNA (+0.36%) with a dividend yield of just under 5%. However, the dividend growth doesn't look particularly good. As my wife will be starting work there soon, I've become more aware of the company for the first time ☺️
Other stocks on my watchlist:
Allianz
Vici
Linde
Microsoft
Waste Management
UnitedHealth Group
Mastercard
Visa
Texas Roadhouse
Nintendo
Enbridge
NextEra Energy
Wolters Kluwer (exciting sector, also corrected over 50% from ATH)
Amazon (for the yield/growth portfolio)
Maybe one or the other is missing $KO (-0.29%) or $MCD (+1.27%) but I had opted for $PEP (+0.21%) and $SBUX (+1.21%) and I don't want any more consumer stocks.
Pure growth portfolio
I also have a separate portfolio with a focus on share price growth:
$NVDA (+1.51%) Nvidia
$NKE (+1.39%) Nike
$MARA (+1.97%) Mara Holdings
$BITF (+0%) Bitfarms
$TTD (+3.12%) The Trade Desk
$CRCL (+5.22%) Circle Internet Group
$ADBE (+3.18%) Adobe
$COIN (+1.22%) Coinbase
$SMHN (-2.64%) Suess Microtec
$PYPL (+0.86%) PayPal
$HUT (+0.7%) Hat 8
$DRO (-0.96%) DroneShield
$LXS (-2.78%) Lanxess
$PLTR (-0.76%) Palantir
$WEED (+0%) Canopy
$UBI (-1.37%) Ubisoft
$MSTR (+5.4%) Strategy
I am aware that I have built up a lot of positions over the last two years. I am therefore also planning to sort out some of them and concentrate more on selected stocks.
I am grateful for any assessment, criticism, tips or suggestions.
Best regards
Chris
39Positions
8.53%
66
4 Comments
Private question 😀 Did you play in the B youth under Christian Ovelhey in Bochum by any chance? I played there and we also had a Chris in the team 😀 year fits yes
•
22
•
1Yr·
My portfolio update Q4 '25 IZF 20.2%
Following the rebalancing of the S&P Quality Aristocrats last Friday, the following stocks were removed from or added to my two ETF indices (50% weighting):
New additions:
$QDEV (+0.9%): $NOVN (+1.89%) , $REL (-0.06%) , $ITX (+2.74%) , $LSEG (+1.99%) , $DB1 (+0.55%) and more
$QUS5 (+0.58%): $BKNG (+0.79%) , $MRK (+2.54%) , $CRM (-0.28%) , $UNP (+0.06%) , $COR (+0.73%) , $CAH (+1.71%) and more
Kicked out of both indices and therefore according to S&P no longer Quality Aristocrats are among others: $BATS (+1.13%) , $7974 (+2%) , $HD (+1.5%) , $LOW (+0.68%) , $HLT (+3.43%)
In addition, the allocation of all individual stocks in the indices was reduced again to max. 5 % was limited.
Thanks to the recent rally of $$HY9H (-3.02%) my current top 10 weighting (ETFs+shares) is as follows:
3.48% Alphabet
3.04% SK Hynix
3.04% Broadcom
2.93% Meta
2.75% Microsoft
2.71% Apple
2.71% NVIDIA
2.55% Taiwan Semiconductor
2.13% Mastercard
2.08% Visa
New portfolio key figures:
P/E: 27.1 (<30) 🟢
Forward P/E: 21.1 (<25) 🟢
P/Β: 11.5 (<5) 🔴
EV/FCF: 28.7 (<25) 🟡
ROE: 42% (>15%) 🟢
ROIC: 19% (>15%) 🟡
EPS growth for the next 5 years: 15% (>7%) 🟢
Sales growth for the next 5 years: 9% (>5%) 🟡
My internal rate of return is currently 20.19%
1010
3 Comments
Thank you for the information on reallocation.
At what intervals is the $QDEV reallocated by Standard and Poor's?
Greetings
🥪
At what intervals is the $QDEV reallocated by Standard and Poor's?
Greetings
🥪
•
11
•
1Yr·
📊 September 2025 — Monthly Recap & Positioning
September is traditionally a tricky month for markets, so I went defensive at the end of August — rotating into names such as $PEP (+0.21%)
$UNH (+2.53%)
$CTAS (+1.99%) Pool, and adding quality European exposures like $ASML (-0.97%) and $ITX (+2.74%) . My wanted to protect capital through a seasonally weak month for tech and speculative stocks.
Despite widespread expectations for a pullback, the US equity market kept moving higher in September:
S&P 500: +3.6% in September
🔹 My performance (September 2025): +2.04% for the month — not bad given my defensive tilt. That brings my YTD gain to +60%,
Looking to October: repositioning into value & beaten-down opportunities.
October has started on a stronger note for me. Already with almost 4% profir. Companies like$ABSI
$CAN (-0.48%) and $BMNR (+5.91%) These are higher-risk, higher-reward trades that complement the defensive core I built in late August and some at end ir september. Like GIS, ABNB, Starbucks
𝗧𝗵𝗶𝘀 𝗶𝘀 𝘁𝗵𝗲 𝗽𝗲𝗿𝗳𝗲𝗰𝘁 𝘁𝗶𝗺𝗲 𝘁𝗼 𝗰𝗼𝗽𝘆 𝗺𝗲 𝗼𝗻 𝗲𝗧𝗼𝗿𝗼—𝗱𝗼𝗻’𝘁 𝗺𝗶𝘀𝘀 𝘁𝗵𝗶𝘀 𝗼𝗽𝗽𝗼𝗿𝘁𝘂𝗻𝗶𝘁𝘆 𝘁𝗼 𝗴𝗿𝗼𝘄 𝗮𝗹𝗼𝗻𝗴𝘀𝗶𝗱𝗲 𝗺𝘆 𝘀𝘁𝗿𝗮𝘁𝗲𝗴𝘆.
😎 𝗗𝗶𝘀𝗰𝗹𝗮𝗶𝗺𝗲𝗿: This is my personal opinion and is for informational purposes only. You should not interpret this information as financial or investment advice
22
Trending Securities
Top creators this week
Real-time data from LSX · Fundamentals & EOD data from FactSet