

The dividend is nice, and the stock has potential, so CAD and fingers crossed 🤞
- Markets
- Stocks
- Hacksaw AB
- Forum Discussion

Hacksaw AB
Stock
Stock
ISIN: SE0025138357
Ticker: HACK
SE0025138357
HACK
Price
Discussion about HACK
Posts
13
1Wk·
ASML cuts
I took some profits on ASML ahead of the earnings report. It’s still the second-largest position in my portfolio, but I figured it never hurts to take some profits.
Instead, I’m DCA-ing at $DTE (-1.05%) and $HACK (+0.16%) used part of my income to do so.
1717
3 Comments
Hey, I still regret taking those profits to this day 😅😅 My initial investment was about 500€ 🙈
•
99
•1Wk·
Hacksaw Took a Significant Hit
Last night, $HACK (+0.16%) suffered a significant setback and corrected by just under -30%. Revenue growth expectations for Q3 were not met. Is this a chance to buy more?
LG and a good start to the week
Johannes
66
8 Comments
I already posted this elsewhere today; I’ll be happy to copy it here for you:
Hacksaw released preliminary Q3 figures today.
Revenue is expected to be around 57.5–58.5 million EUR, up from 52.0 million EUR a year ago.
That represents growth of only +11 to +12%. Adjusted EBIT is expected to reach 48–49 million EUR, with the EBIT margin even coming in at around 83%.
Operationally, the company remains extremely profitable.
However, the statement that’s hitting the market is this: Revenue growth was below the historical growth rate because market conditions have weakened and game performance was weaker than in the most recently reported periods.
The stock is reacting brutally to exactly that.
The share price is currently hovering around 59–60 SEK at times, representing a decline of about 27% over the past 5 days.
The key point is:
Hacksaw is not valued like a typical value stock, but rather like a high-growth compounder. When the market has priced in 25–40% growth for years and suddenly only 11–12% materializes, the valuation multiple can shrink very quickly, even if the margin remains fantastic.
My verdict:
Business model 🟢
Profitability 🟢🟢
Balance sheet/operational quality remains strong
Growth momentum 🟠
Valuation needs to be reassessed following the growth slowdown
Short-term chart 🔴
I wouldn’t interpret this as “the company is broken.” But the story has taken a real hit today:
An 83% EBIT margin is sensational, but 11–12% revenue growth isn’t automatically enough to justify the previous valuation.
For me, the key date now is the full Q3 report on November 3, 2026. That’s when we’ll have to see whether this was just a weak quarter or whether Hacksaw is structurally shifting into a lower growth phase.
•
66
•1Mon·
PART 3: How I'm Trying to Improve Human Investment Decisions Using a Structured AI Research and Control System
Part 3: The Five Categories in Practice
What This Part Is About
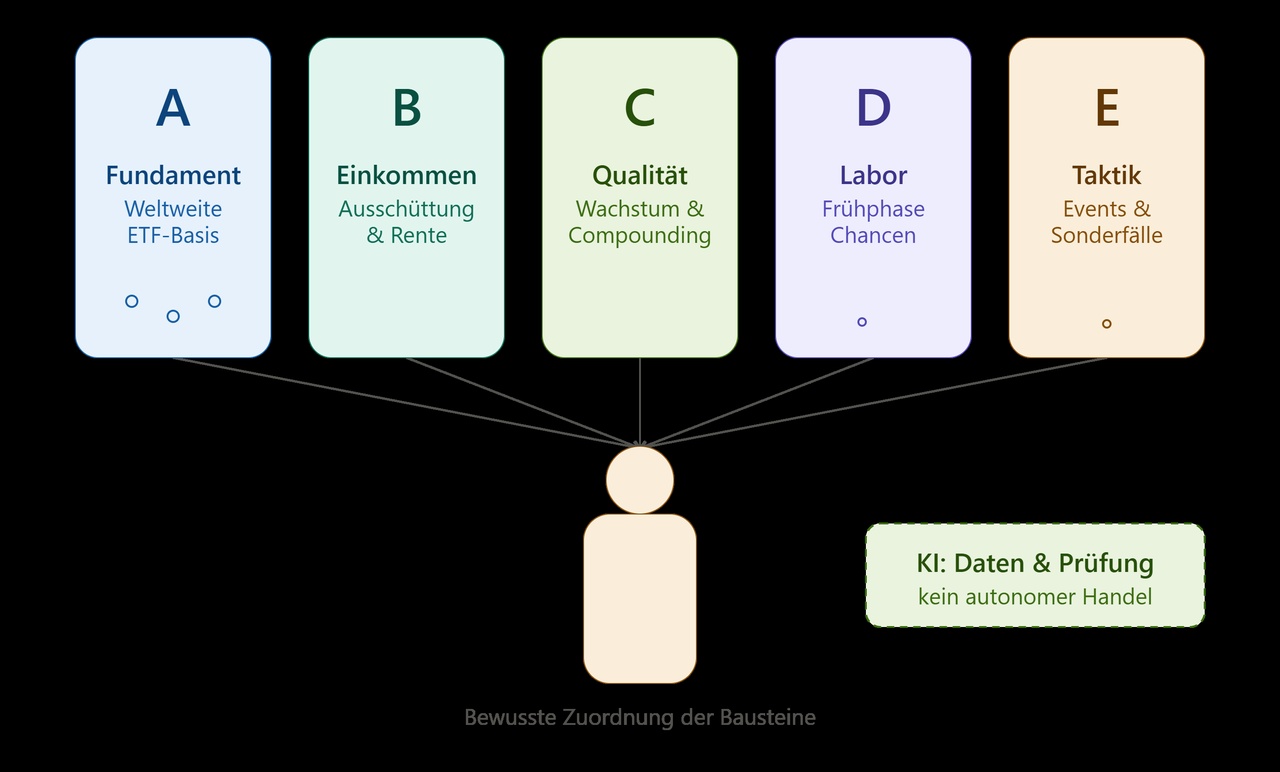
In Part 1, I described the origins of the 55555 system. Part 2 showed how an initial stock idea is transformed into a well-reasoned decision through research, cross-checking, and comparison. Now we’ll look at the practical side: What is the purpose of the five categories, A through E; which stocks are currently included in them; and why do they fit exactly where they are?
The categories are not a ranking from safe to risky. Each serves a different function.
A forms the broad foundation. B is intended to provide ongoing cash flow. C seeks quality growth. D allows for limited asymmetric opportunities. E is intended for tactical situations, events, and special cases. Therefore, what matters is not only whether a company is interesting, but what role it is meant to fulfill within the overall system.
The following chart shows the current confirmed portfolio following the addition of AeroVironment. It deliberately does not include share counts, portfolio values, absolute position sizes, purchase volumes, or absolute gains and losses. The goal is to make the system transparent without disclosing personal financial data.
Grab a cup of coffee or a snack, because the estimated reading time this time is 14 minutes :)
Category A: The Broadly Diversified Foundation
Category A consists of 5 ETFs.
This tier is not intended to identify the most exciting individual stocks, but rather to stabilize the portfolio, provide broad coverage of regions and companies, and reduce dependence on individual investment theses.
Therefore, there is no mechanical price limit for Category A.
The key factors are index quality, costs, diversification, liquidity, and whether the building blocks complement each other effectively.
Categories A and B are the long-term cash flow building blocks for future retirement income enhancement. For this reason, frequent buying and selling is expressly not intended here:
A replacement requires a clear deviation from the objective or a significantly better alternative that is convincing in terms of costs and risks.
Currently, Category A is fully allocated with five building blocks:
VanEck Developed Markets Dividend Leaders $TDIV (-0.42%)
- Dividend component for developed markets
Dividend and region (as of September 16, 2026): approximately 3.0 percent dividend yield, paid quarterly. Rough regional breakdown: Europe 56 percent, North America 16 percent, Asia-Pacific and other markets 28 percent.
Why include it in your portfolio: The ETF brings together established companies with a strong focus on dividends, thereby complementing the portfolio’s foundation with a clear emphasis on income.
Expectations: In the long term, it is expected to deliver robust distributions and broader diversification across developed markets.
Key risk: A focus on dividends may temporarily result in significant overweighting of certain sectors and value stocks; high dividends are no substitute for corporate quality.
L&G Global Quality Dividends $LDGL (-0.43%)
- global quality and dividend component
Dividend yield and region (as of September 16, 2026): Approximately 4.3 percent annualized based on the most recent monthly payment; the fund is still young and does not yet have a full 12-month history. Distributions are made monthly. Rough regional breakdown: North America 35 percent, Europe 29 percent, Asia-Pacific 34 percent, other markets 2 percent.
Why include it in your portfolio: This ETF combines international diversification with quality and distribution characteristics. It is intended to prevent the dividend portion of the portfolio from consisting solely of traditional high-dividend stocks.
Expectations: It is intended to provide exposure to global corporate quality while also delivering regular distributions.
Key risk: Factor strategies can lag behind the broader market for extended periods and, despite their global focus, may develop regional or sector-specific biases.
WisdomTree Europe SmallCap Dividend
$DFE (-0.1%)
- European small-cap stocks
Dividend and Region (as of September 16, 2026): Approximately 3.7 percent dividend yield, paid quarterly. The equity allocation is almost entirely in Europe; the largest countries are the United Kingdom, Sweden, and Norway.
Why include it in your portfolio: This component adds smaller European companies to the portfolio that have little weight in major global indices. At the same time, the dividend component is maintained.
Expectation: It is intended to tap into additional sources of returns beyond global megacaps over the long term.
Key risk: Small-cap stocks are more sensitive to economic conditions, financing costs, and lower liquidity; Europe may also experience prolonged periods of relative weakness.
Fidelity Emerging Markets Quality Income
$FYEQ (+0.09%)
- Emerging markets with a quality filter
Dividend and region (as of September 16, 2026): 2.6 percent dividend yield, paid quarterly. Rough regional breakdown: Asia 81 percent, Europe 3 percent, Middle East and Africa 8 percent, Latin America 3 percent, other markets 5 percent.
Why include it in your portfolio: The ETF incorporates emerging markets into the portfolio without relying exclusively on the largest index holdings. Quality and dividends are intended to mitigate some of the typical risks associated with emerging markets.
Expectations: It aims to combine growth from emerging markets with a more disciplined approach to quality and income.
Key risk: Currencies, politics, regulation, and geopolitical tensions can significantly impact corporate earnings and returns as measured in Europe.
iShares MSCI ACWI
$ISAC (-0.02%)
- Cornerstone of the portfolio and thus the broad global core
Dividend Policy and Regional Breakdown (as of September 16, 2026): Reinvesting dividends, so no ongoing cash distributions; returns are reinvested in the ETF. Rough regional breakdown: North America 66 percent, Europe 12 percent, Asia-Pacific 16 percent, Latin America, the Middle East, Africa, and other markets 6 percent.
Why it’s in the portfolio: It covers developed and emerging markets within a very broad global equity strategy. It is the simplest and most diversified component of the system.
Expectation: It is intended to drive long-term global wealth accumulation, regardless of which individual investments are currently the focus in the rest of the portfolio.
Key risk: Even a global index does not protect against general stock market losses and is often heavily influenced by large U.S. technology companies.
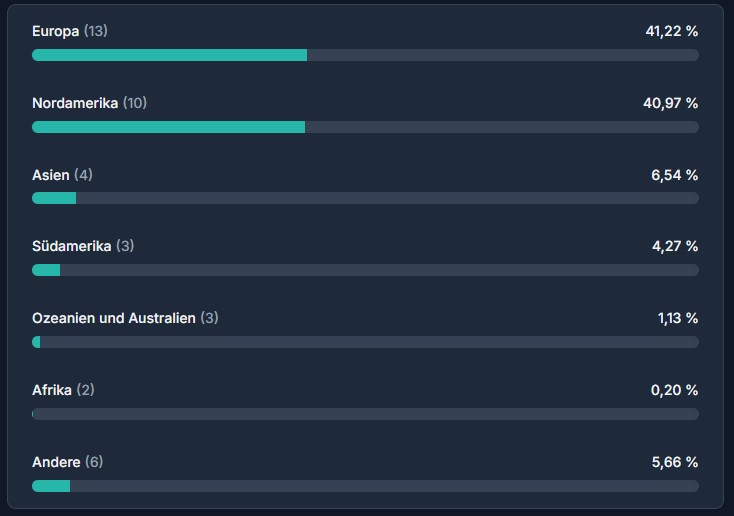
Overall portfolio regions:
Category B: Cash Cows and Regular Dividends
Category B is intended to generate reliable cash flow.
A high percentage alone is not sufficient for this. Before making a new purchase, we review dividend coverage, the balance sheet, debt, the business model, capital allocation, and concentration risks. For new Category B positions, a minimum yield of six percent generally applies. Mechanical price stops are not a priority here; we sell if the dividend or fundamental thesis breaks down or if a clearly better alternative emerges.
Like Category A, Category B is geared toward long-term holding and subsequent recurring income. Price movements alone therefore do not trigger a change in position; dividend coverage, balance sheet, business model, and sustainable cash generation remain the decisive factors.
Currently, this category has a dividend yield of approximately 9% excluding any special dividends!
Cibus Nordic Real Estate
$CIBUS (-1.17%)
- Monthly real estate cash flow
Dividend (as of September 16, 2026): approximately 7.1 percent annualized, paid monthly.
Why it’s in the portfolio: Cibus focuses heavily on food and other everyday necessities. The monthly distribution and largely indexed rents align with the cash flow objectives of this category.
Expectation: The position is intended to provide predictable distributions from a defensive real estate portfolio.
Key risk: Debt levels and refinancing needs remain high. Rising interest rates, weaker like-for-like revenue, or overly aggressive growth through acquisitions would weigh on the investment thesis.
Hercules Capital $HTGC (+0.1%)
- Specialized financier for growth companies
Dividend (as of September 16, 2026): Approximately 10.8 percent based on current regular and supplemental distributions, paid quarterly. Supplemental distributions are not guaranteed.
Why include it in your portfolio: Hercules primarily extends loans to technology- and life sciences-oriented companies. Many loans have variable interest rates, which means returns can initially benefit from higher interest rates.
Expectation: The goal is to achieve an above-average current distribution from a specialized loan portfolio.
Key risk: Loan defaults, a weak venture capital environment, falling interest rates, or a deterioration in distribution coverage could put pressure on cash flow.
Vår Energi $VAR (+0.13%)
- Energy cash flow
Dividend (as of September 16, 2026): approximately 10.0 percent annualized based on the most recent quarterly payment, paid quarterly. The amount remains dependent on the commodity cycle and free cash flow.
Why include it in your portfolio: Vår Energi adds a commodities-related cash flow component to the portfolio. Production, the project pipeline, and distributions offer a different source of returns than real estate or the lending business.
Outlook: The position is expected to benefit from efficient oil and gas production as well as a shareholder-friendly dividend policy.
Key risk: Oil and gas prices, project delays, cost overruns, and political intervention make the dividend more cyclical than that of a traditional defensive dividend stock.
Capital Southwest $CSWC (-0.37%)
- SME financing
Dividend (as of September 16, 2026): approximately 10.8 percent based on the most recently reported annual payments. The regular dividend is paid monthly; supplemental dividends may be paid quarterly.
Why include it in your portfolio: Capital Southwest is another BDC component, but with its own loan portfolio and a different corporate structure. This position complements Hercules and spreads the credit risk across a second manager.
Outlook: We expect recurring income from U.S. small and medium-sized businesses and disciplined distributions from net interest income.
Key Risk: The biggest risks are credit quality, recession, falling interest margins, dilution, and a distribution that grows faster than sustainably earned income.
Chesnara
$CSN (-0.86%)
- Insurance and run-off cash flow
Dividend (as of September 16, 2026): approximately 6.5 percent based on the most recent known 12-month payments, paid semiannually.
Why it’s in the portfolio: Chesnara manages life insurance portfolios and acquires additional portfolios. This results in a cash flow profile that differs significantly from real estate, energy, and BDCs.
Outlook: The position is expected to deliver stable long-term distributions from existing insurance portfolios and disciplined capital allocation.
Key risk: Capital requirements, market fluctuations, the quality of acquisitions, and weaker cash generation could limit dividends and growth.
Category C: Quality Growth and Long-Term Compounding
Category C is intended for companies that can grow revenue, earnings, and free cash flow over many years. Quality and growth are considered separately from the initial entry point. A company can reach the “Champions League” and still be too expensive or technically unfavorable at first.
For active C positions, a 20-percent trailing rule generally applies, whereby actual broker orders and theoretical benchmarks must remain clearly separate.
An open position does not create an obligation to buy.
Nu Holdings $NU (+0.06%)
- digital financial platform in Latin America
Why it’s in the portfolio: Nu combines strong customer growth, a scalable digital platform, and the ability to offer more financial products per customer. The stock also brings regional diversification to the C-segment.
Outlook: In the long term, Nu is expected to profitably monetize its large customer base in Brazil, Mexico, the U.S., and other markets.
Key risk: Credit quality, regulation, currencies, competition, and an overly high valuation could undermine the growth thesis.
Schneider Electric
$SU (-0.07%)
- Electrification, energy efficiency, and automation
Why it’s in the portfolio: Schneider is a high-quality company positioned to benefit from several structural growth themes: rising electricity demand, data centers, automation, grids, and more efficient energy management. The stock was added following a direct comparison with several industrial and energy infrastructure candidates.
Outlook: The position is expected to benefit in the long term from the expansion of electrical infrastructure and the integration of hardware, software, and services.
Key risk: Valuation, economic conditions, integration and execution risks, as well as a significant slowdown in data center or industrial investments, are the main concerns.
Hacksaw $HACK (+0.16%)
- Growth in digital gaming and platforms
Why include it in the portfolio: Hacksaw represents a scalable, content-driven business model in the regulated online gaming sector. New games and additional markets can contribute disproportionately to earnings with relatively little capital tied up.
Outlook: The goal is long-term growth through new content, distribution, and international expansion.
Key risk: Regulatory changes, dependence on platform partners, shifting gaming trends, and a high valuation could quickly lead to a repricing of growth.
Vincorion $V1NC (+1.5%)
- Specialized energy and defense systems
Why include it in the portfolio: Vincorion complements C with a smaller German specialist that has long-term demand for robust energy and system solutions for safety-critical applications.
Outlook: The position is expected to benefit from increased defense and infrastructure investments as well as improved operational execution.
Key risk: Order delays, project and margin risks, low market liquidity, and customer concentration make the stock more vulnerable than that of a large industrial conglomerate.
RELX
$REL (-0.34%)
- Data-driven information and analytics services
Why include it in your portfolio: RELX has recurring revenue, strong data assets, and deep integration into professional workflows. Its business model is less cyclical than that of traditional industrial companies.
Outlook: The position is expected to grow over the long term through pricing, data, software, and continuous product improvement.
Key risk: An overly high valuation, regulatory issues, technological disruptions, and new AI-based competitors could limit growth and margins.
For Category C, the following applies: A C-rated position may not be downgraded to D.
If the C thesis deteriorates permanently, the position is replaced or sold within the C category.
D is not a catch-all category for damaged quality or growth theses.
A D company, on the other hand, may be upgraded to C if it demonstrably reduces its uncertainties and, in a direct comparison, better aligns with the quality and growth objectives of Category C.
It must , however, like any other security, be at least 10% to 15% better in valuation than the existing holding.
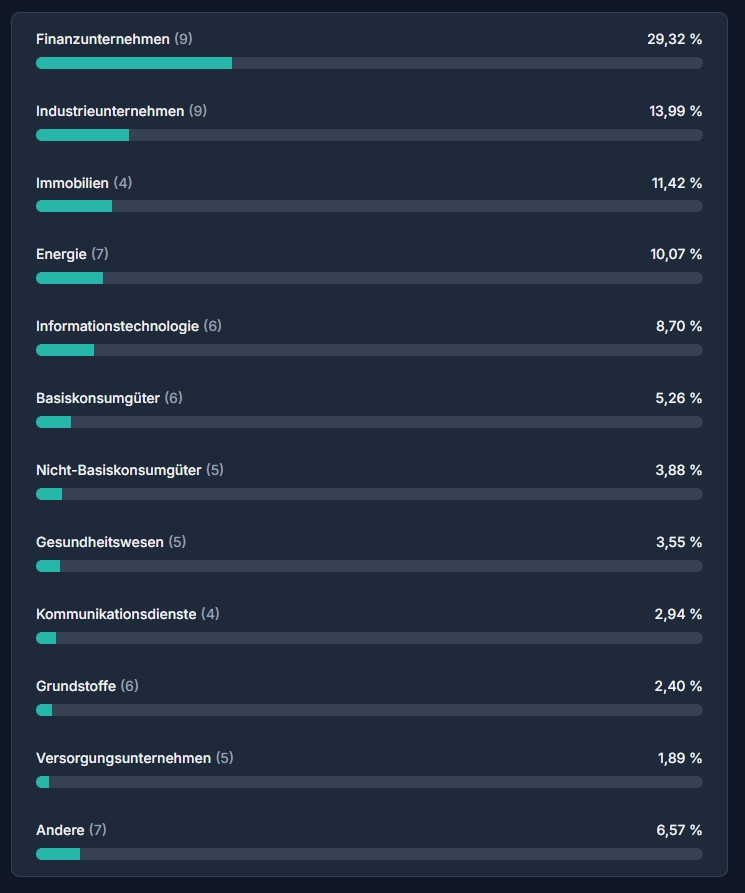
Sector Overview of the Portfolio:
Category D: Limited Asymmetric Opportunities
Category D deliberately accepts a higher degree of uncertainty. Here, we look for situations in which a successful milestone can significantly alter the company’s value, while the position size and exit strategy limit potential losses.
We evaluate the product and technology, financing, cash runway, dilution, customer or pipeline concentration, catalysts, and technical setup.
An open position does not create an obligation to buy.
NeoVolta $NEOV (+1.62%)
- small provider of energy storage systems
Why it’s in the portfolio: NeoVolta offers access to the growing market for residential and small-scale commercial energy storage. The investment case hinges on scaling, sales, and broader market acceptance.
Outlook: If growth is successful, the company could benefit from decentralized power supply, resilience, and increasing solar adoption.
Key risk: Financing, dilution, competition, the company’s small size, and its dependence on strong revenue growth make this a highly speculative position.
Kymera Therapeutics $KYMR
- Targeted Protein Degradation
Why include it in the portfolio: Kymera develops drugs designed to specifically degrade disease-relevant proteins. Successful clinical data could significantly boost the value of several programs and the entire technology platform.
Expectations: The position targets the asymmetric value of clinical progress and potential partnerships.
Key Risk: Clinical failures, side effects, binary data events, high capital requirements, and potential dilution are core risks rather than temporary side effects.
IQM Quantum Computers
$IQMX (-0.8%)
- European quantum computing technology
Why include it in the portfolio: IQM offers direct access to a strategically important future market and has operational systems, orders, and technology partnerships. At the same time, the market is still in its early stages and difficult to evaluate.
Outlook: The position is expected to benefit from growing demand for European quantum infrastructure and technological advances.
Key risk: Long development times, high financing costs, technological competition, and further capital requirements could significantly dilute the company’s value. The risk and stop-loss strategy will therefore be reviewed again.
AeroVironment
$AVAV (+0.05%)
- Drones, counter-UAS, and defense technology
Why it’s in the portfolio: AeroVironment was added following a renewed fundamental and technical review. The investment case combines a strong order backlog with growing demand for unmanned systems, defense solutions, and directed-energy applications.
Outlook: The position is expected to benefit from the transition of key programs to larger-scale production runs and from the structurally rising demand for drones and defense systems.
Key risk: Order timing, government budgets, project integration, valuation, and sharp price fluctuations could lead to significant setbacks despite strong demand.
As of today, the fifth spot in the D category is still open.
Currently, the main contenders are NeurAxis $NRXS , Praxis Precision Medicines, and Rocket Lab $RKLB (+1.02%) are being closely monitored.
NeurAxis has become significantly more attractive following technical improvements, but remains a speculative candidate due to losses, capital requirements, and potential dilution. The spot will only be awarded if quality, financing, catalysts, chart performance, and portfolio value collectively prove compelling.
Category E: Tactical Situations and Special Cases
This category is intended for swings, events, free rides, and clearly documented special cases. E is not a dumping ground for poor positions, nor is it a way to circumvent rules from categories B, C, or D. Before making a tactical purchase, the setup, trigger, risk, target, and exit strategy must be clearly defined. This category may remain empty if no compelling opportunity is available.
Desert Control $DSRT (-4.31%)
- Special Case and Grandfathering
Why it’s in the portfolio: Desert Control is developing technology to improve sandy and dry soils. The position dates back to an earlier phase of the portfolio and is not currently treated as a standard new purchase under the current D rules.
Expectation: The remaining position keeps open the possibility that pilot projects, partnerships, or commercial applications will validate the technology.
Key Risk: Early commercialization, financing, dilution, low predictability, and very high volatility make this investment unsuitable as a core position. It therefore remains explicitly a documented special case.
Teekay Tankers $TNK (-0.03%)
– Momentum Position
Why it’s in the portfolio: We have included Teekay Tankers as a tactical momentum/event position in Category E. The company is currently benefiting from high tanker rates, strong demand for oil transportation, and longer shipping routes due to geopolitical tensions. Added to this are a very solid balance sheet, high free cash flows, and a favorable valuation.
Expectations: Capitalizing on the momentum. For this reason, we do not treat Teekay as a long-term dividend or quality position, but rather as an E-position to be actively monitored with a clear exit strategy.
Key Risk: Despite these strengths, the business is highly cyclical: falling freight rates or an easing of the geopolitical situation could quickly bring earnings back to normal levels.
In addition, for the two open spots in the E portfolio, we are currently reviewing, among other things, selected “fallen angel” stocks, as well as potential rebound or event-driven setups.
Dorian LPG $LPG (-0.64%) and International Seaways $INSW (+0.4%) are examples of strong but highly cyclical momentum plays. DSV $DSV (+7.26%) would be more of a rebound or earnings event than an immediate C-buy.
Such ideas do not automatically become positions; the current chart and a predefined exit strategy are key factors.
Why the categories don’t have to be the same size
The 55555 system means five possible slots per category, not five identical positions and no rigid equal weighting.
A category may remain incomplete.
Capital is not automatically allocated to the next available slot.
First come rule violations and risk control, then vacant slots, the best candidates, and only then possible replacements or additional purchases.
Nor is a replacement made simply because a new name seems more modern or stronger in the short term. A candidate must demonstrably outperform the existing position and improve the overall portfolio by approximately ten to fifteen percent, or replace a clear rule violation. As a result, the category structure does not become an automated trading system, but rather a framework for disciplined decision-making.
The rulebook clearly states that no single sector may account for more than 30% of the portfolio!
This limit includes ETFs as well. So it can happen that a truly good stock can no longer be purchased—due to the sector cap—to avoid creating concentration risk.
What Has Changed Since the Start
The basic idea behind the five tasks has remained the same, but the practical implementation has become more precise. Category E is now active. Balance sheet, debt, and concentration are mandatory review criteria. Champions League, Reserve, Watchlist, and Top 3 Alternates distinguish quality from current buyability.
The Masterbook and Master Status ensure that new decisions, sales, and exceptions do not get lost in old chats and works.
It was particularly important to realize that a system does not improve simply by mechanically applying every rule.
A stop, a score, or an open slot is only part of the decision.
Data quality, company context, portfolio utility, and human judgment remain indispensable.
Preview of Part 4
The fourth and final part focuses on control and further development:
How Masterbook, Master Status, daily closing, lists, transaction history, dividend log, and catalyst calendar work together. I’ll also show how errors, conflicting data, and new information are handled and where the limits of an AI-powered system lie.
Part 3, too, describes exclusively my personal development and decision-making process. It is neither investment advice nor a solicitation to buy or sell securities.
I look forward to questions, suggestions, and constructive criticism. I find it particularly fascinating to see what roles other investors assign to the components of their portfolios and how they distinguish between long-term quality, ongoing cash flow, and limited speculative opportunities.
+ 2
4242
13 Comments
•
66
•
2Mon·
Mandatory Offer by Candle Lake for EVOLUTION AB
Kenneth Dart (who was already working part-time at $DKNG (+0%) , $FLTR (+0%) and $HACK (+0.16%) ) is offering 695 SEK per $EVO (-0.1%) share, but stated that there are no plans to delist the company.
At the same time, UBS raised its rating on Evolution, while AlphaValue/Baader Europe lowered its rating to “Sell.”

2Mon·
Hacksaw - Strong Numbers, but Stock Price Falls Sharply Anyway
Hacksaw $HACK (+0.16%) reported positive results today, yet its stock fell by 7%.
The performance compared to Q2 2025 is clearly positive:
- Revenue up 31% to €59.3 million
- EBIT up 31%, margin stable at 82%
- Net income up 43% to €45.7 million
- Cash flow from operating activities: +60% to €43.1 million
Why is the stock falling anyway?
EPS fell slightly short of expectations; €0.16 per share was expected, but the company reported €0.158. Given the company’s growth to date and its valuation, even minor shortfalls are enough to trigger a significant market reaction. And this is despite the fact that Hacksaw’s operating performance was actually even stronger; exchange rates are weighing on earnings. Strong results were repeated, but not stronger than in recent quarters. Stronger growth momentum had likely been priced in; here we see that “very good” can’t be good enough for the market. Additionally, the dividend payout—which is high for a growth stock—was viewed critically by some investors.
Is this a major setback for my investment?
No. Hacksaw remains on track operationally. Strong growth, impressive margins, robust cash flow, a growing portfolio, and continued expansion into new markets reaffirm my decision. Fundamentally, there’s no sign of a breakdown, and I view today’s pullback as an opportunity—so I’ve added a second tranche to my position. Even though it’s not yet clear whether the dividend policy will continue as is—which is normally an important factor for me—I see significant upside potential here that should be capitalized on.
2020
16 Comments
Markt: Sell the News
Opi: Bought a few
🤝🫶
Opi: Bought a few
🤝🫶
•
88
•4Mon·
My two cents on the matter
The metrics are truly elite (83% EBITDA margin, ~100% FCF conversion, debt-free, >100% ROIC), but the “deep value” was the February low—at SEK 82, you’re paying ~11x forward, which is moderate, not cheap. The remaining discount relative to software compounders is not a quality discount, but a regulatory discount: ~88% of revenue comes from gray/crypto markets, plus a stake-heavy top-10 concentration of 74%.
I’m out…I already found Evolution AB suspicious ^^
55
7 Comments
I’d love to see the prompt that spits that out. 🤷🏼♂️😅 But the answer is, well, meager and superficial, to say the least. So, in my opinion, it scores a 0.0. Gambling is probably the most regulated business in the world (chance AND risk rolled into one). But hey, you don’t have to dance at every party. To each their own.
•
77
•4Mon·
Off to catch the train, into the Olga, FOMO, whatever—I'm on Hacksaw now too 🙈
The presentation, including the figures, was really convincing—I'm considering $ALSTI (+0.65%) selling my position, which is still relatively small, and shifting it into a second tranche $HACK (+0.16%) . Time will tell...
Best regards, Johannes
99
1 CommentAs always, the rule is: DYOR.🤷🏼♂️ If you’ve done your research and CRV is a good fit for you, let’s go. I like it, and I’m definitely going to invest a four-figure sum as well.
•
55
•4Mon·
Actions speak louder than words
So today I jumped in with my first batch $HACK (+0.16%) . May the stock market gods be with us... 😂😇


4Mon·
"Growth engine with increasing dividend power."
To give you a good start to the trading week, there will be a second company presentation this evening.
Dynamic sales and profit growth meets an annually growing dividend - a rare combination of scaling and shareholder return.
Hello my dears,
Yesterday dear @Dividendenopi promised me a jar of homemade jam. That's why I went looking for another dividend stock.
The stock I found in Sweden surprised me.
And here I ask myself, is this the Juan's conclusion once again too euphoric.
Is there a fly in the ointment here that we have overlooked, or have investors simply been blind so far?
Many people often accuse Juan of being too young and optimistic in his valuations.
That's why I'm looking forward to your comments all the more.
I am urgently awaiting comments from.
@Dividendenopi , @Raketentoni , @Get_Rich_or_Die_Tryin , @Aktienhauptmeister
If no long hair is found here, I will consider liquidating my Mercedes Benz position and investing here. (no investment advice)
Disruptor in iGaming technology and game development
Hacksaw is active in the entire B2B iGaming value chain, from game development to distribution. Our clients are among the largest private and public iGaming operators in the industry.
Innovating the industry with our state-of-the-art RGS
Hacksaw's scalable and modular remote gaming server (RGS) platform, built on a modern codebase, enables rapid game development and distribution. The games developed by Hacksaw consist of digital slot machines, scratch cards and instant win games. Their momentum is driven by successful game launches and continued engagement from a growing player base.
Founded in 2018
Hacksaw was founded in 2018 and initially focused on developing the RGS platform. Since then, they have released a steady stream of games, such as digital slots, scratchcards and instant win games, built on the RGS and launched them in a growing number of jurisdictions. Furthermore, in 2023, they launched their RGS on a B2B basis, allowing third-party game studios to create games on their modern tech platform and distribute them across Hacksaw's wide distribution network.
Growth strategy
Hacksaw has historically grown with healthy profitability and is pursuing a strategy for continued profitable growth. They want to further strengthen their market position in the global iGaming market. The strategy consists of four main components:
- Product innovation
- Product innovation includes the introduction of new games and the ongoing development of the RGS platform to ensure a competitive, high-quality and differentiated product offering.
- Increasing commercialization
- Increased commercialization includes upselling to existing customers, acquiring new customers and commercial excellence as well as accelerating the roll-out of OpenRGS™ to external game developers.
- Increased global presence
- Leverage newly regulated markets and position for growth in markets where local licensing requirements are expected.
- Expanded scope
- Expansion into adjacent areas and further scalability of the business model.
Long-term financial targets and capital allocation policy
- Sales target>30% annual growth rate
- EBIT margin>80%
- Capital allocation policy>75%
of net profit to shareholders through dividends and/or share buy-backs
Hacksaw aims to return at least 75% of net profit to shareholders through dividends and/or share buybacks.
COMPANY PERFORMANCE
Hacksaw-Company-introduction-FY-2025-1.pdf
Hacksaw Gaming exceeds analysts' expectations in the first quarter
28,04,2026
(en.investing.com)
Hacksaw Gaming has reported 1st quarter significantly exceeded analysts' expectations. The turnover rose to € 57.6 millionwhich was 28 % YoY or 37% adjusted for currency effects and 5% above the consensus above consensus. Compared to the previous quarter, sales increased by a further 5 % increase.
The adjusted EBIT reached € 47.4 millionan increase of 27% YoY and 6% QoQand was 8 % above the analysts' estimate. The EBIT margin of 82.4 % also exceeded expectations.
In operational terms, Hacksaw published 27 new gamesexpanded the OpenRGS platform to 320 titles and increased the daily game rounds by 27 %. At the end of the quarter, the company had 176 million in net liquidity.
In terms of valuation, Hacksaw is currently valued at 7.7 times EV/EBITDA (2026) traded. The company confirms its long-term targets: >30% sales growth and >80% EBIT margin. In addition at least 75 % of the net profit flow back to shareholders via dividends or buybacks.
- NEWS
Hacksaw Gaming debütiert im Libanon mit BetArabia | Hacksaw Gaming
Friday, May 29, 2026
Hacksaw Gaming kündigt Partnerschaft mit Swiss Casinos an
- Dienstag, 12. Mai 2026
- Hacksaw begrüßt Aloha Gaming als neues Partnerstudio bei OpenRGS
- Hacksaw Gaming erweitert seine OpenRGS-Plattform weiter mit der Ergänzung von Aloha Gaming, einem Studio, das sich auf mutige, echte 3D-Slot-Erlebnisse mit innovativen Spielmechaniken spezialisiert hat.
Hacksaw Gaming kündigt Partnerschaft mit Mozzartbet in Rumänien an
MORE GREAT NEWS
Neueste Nachrichten | Hacksaw Gaming
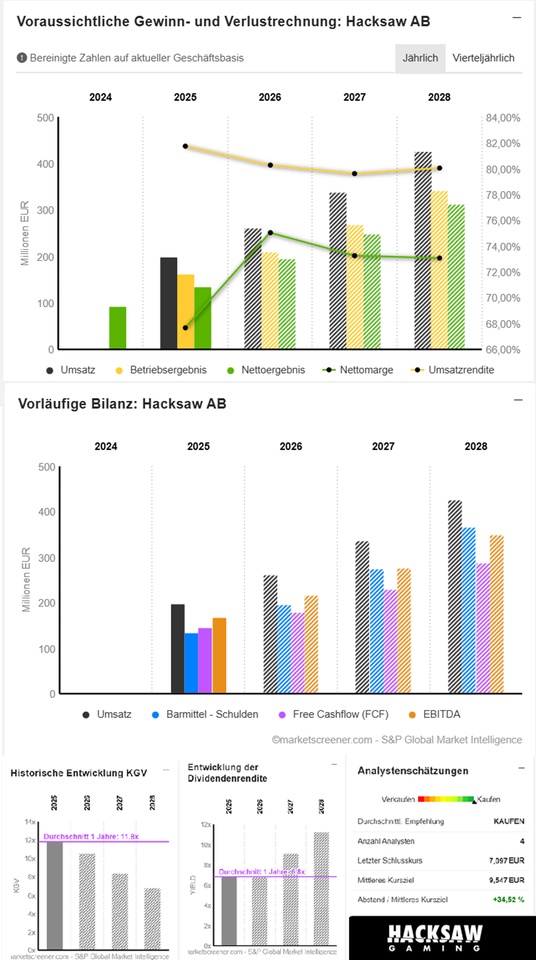
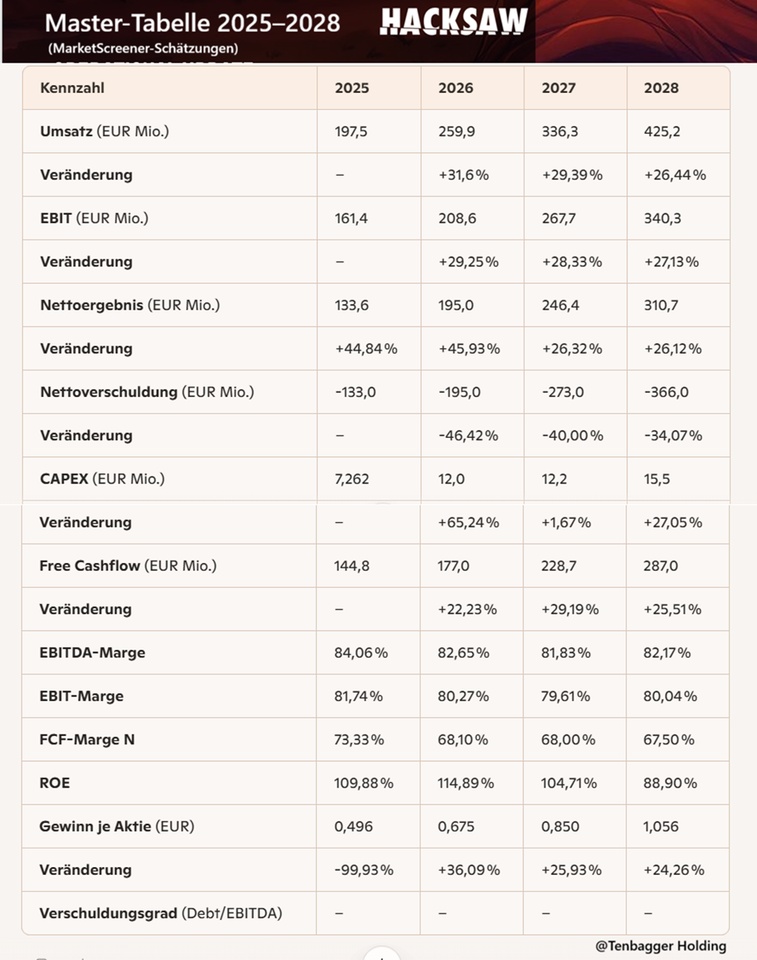
Juan's conclusion on the key financial figures
(Basis: MarketScreener data from your current tab )
In a nutshell: Hacksaw delivers an extremely scalable, highly profitable growth model - with margins that seem almost "unrealistically good" in the software/iGaming world. The 2025-2028 forecasts show strong growth, rising cash flows, falling debt and an ROE that plays in the Champions League.
🔹 Juan's look at the figures for 2025-2028
1) Growth & scaling
- Double-digit sales growth every year - +31,6 %, +29,4 %, +26,4 %.
- EBIT increases almost in step - a sign of real operational scaling.
- Net profit grows even faster than sales → Model becomes more efficient.
2) Profitability at top level
- EBITDA margin 82-84 %, EBIT margin ~80 % → This is software premium class.
- FCF margin remains >67 % → Cash machine.
- ROE remains extremely high (88-115 %) - return on capital is exceptional.
3) Cash flow & balance sheet
- Free cash flow increases from 144.8 → € 287 million.
- Net debt becomes more negative every year → Net cash position grows massively.
- CAPEX remains low → Model is capital poor.
4) Per share
- EPS grows solidly: 0,496 → 1,056 €.
- The extreme -99.93 % change in 2025 is a base effect by the distorted 2024 EPS (758).
🔹 Juan's overall assessment
Hacksaw is a prime example of a highly scalable, high-margin digital model. Growth + margins + cash flows + decreasing debt = Quality profile at a very high level. If the momentum holds, Hacksaw will remain a top-tier compounder in the iGaming B2B segment.
Market value 2,052
Number of shares (in thousands) 289,196
Date of publication 17,02,2026
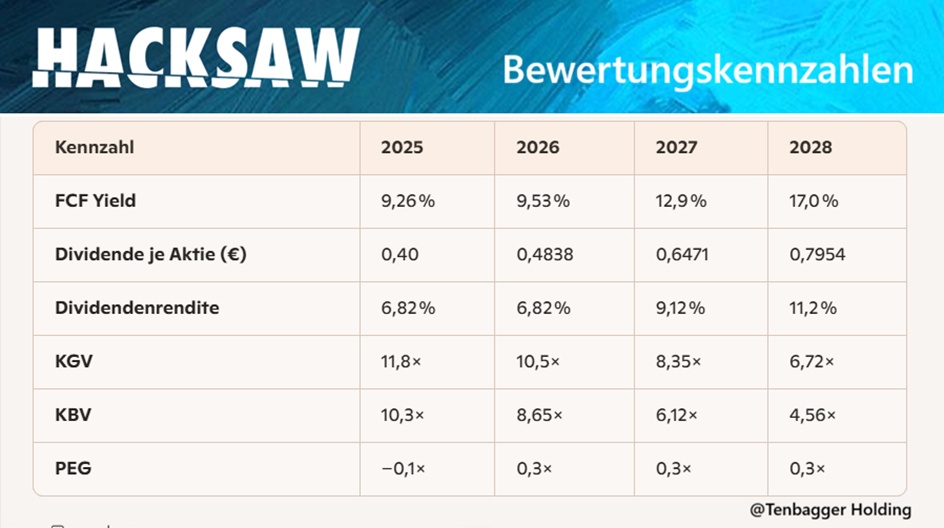
Juan's conclusion on the valuation ratios
(Basis: your current MarketScreener tab)
In a nutshell: Hacksaw looks like a quality stock that is simultaneously fast-growing and undervalued at the same time. The valuation metrics show a profile that typically only true compounders deliver.
🔹 Juan's view on the 2025-2028 valuation
1) FCF power meets attractive valuation
- A FCF yield of 9-17 % is exceptional for a fast-growing digital model.
- This means that the market is pricing growth growth far too conservatively too conservatively.
2) Dividend increases cleanly with
- Dividend per share grows every year → Shareholder return is steadily increasing.
- Dividend yield increases to 11 % → rare for a growth stock.
3) Multiples fall - even though the company is growing
- P/E ratio falls from 11.8× to 6.7× → Classic "multiple compression sweet spot".
- P/B ratio falls from 10.3× to 4.6× → Valuation becomes increasingly favorable relative to equity.
4) PEG shows clear undervaluation
- PEG by 0,3× → Market massively underestimates earnings growth.
- 2025 PEG is negative due to distorted EPS base effect.
🔹 Juan's overall assessment
Hacksaw combines growth, cash flow strength and falling multiples - a rare trio. The valuation ratios speak a clear language: The market is lagging operating reality. For Juan, this is a classic profile of an undervalued undervalued high-quality compounder.
🔶 Juan's conclusion (short & clear)
Hacksaw shows a valuation profile that rarely so clean clean: falling multiples, rising cash flows, growing dividends and an FCF yield that is expected to reach 17 % in 2028.
For Juan, this is a classic profile of a potential compounder with tenbagger DNA.
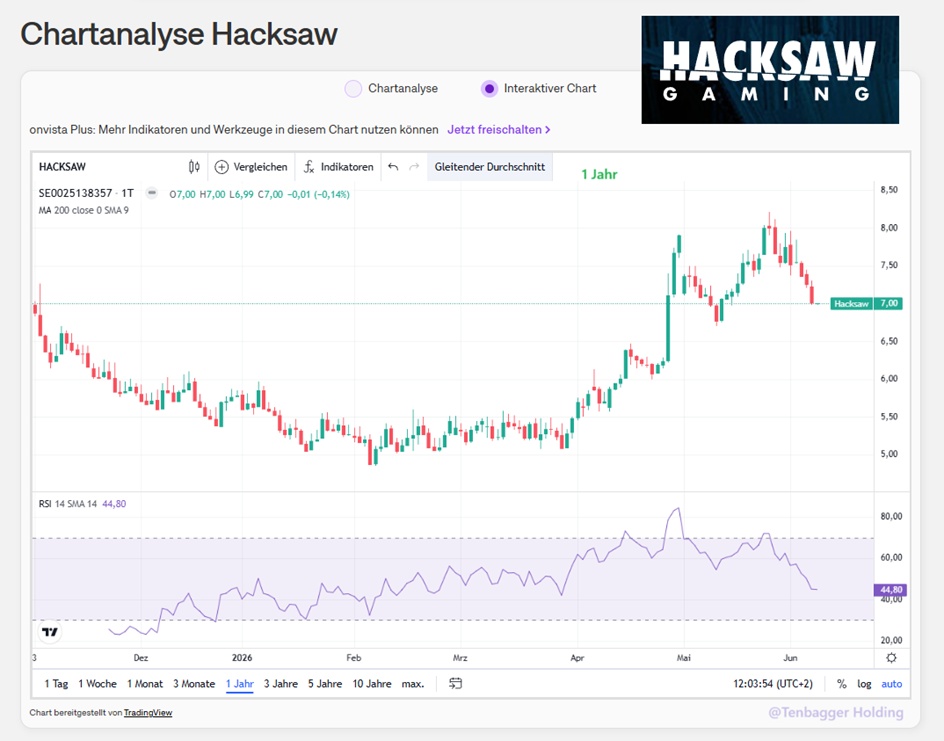
05.06.2026, 22:02:56 -
Tradegate BSX (EUR)
7.110 EUR
+ 4
1818
28 CommentsAs soon as my account transfer is complete, I'm in.👏🏻😉
•
44
•4Mon·
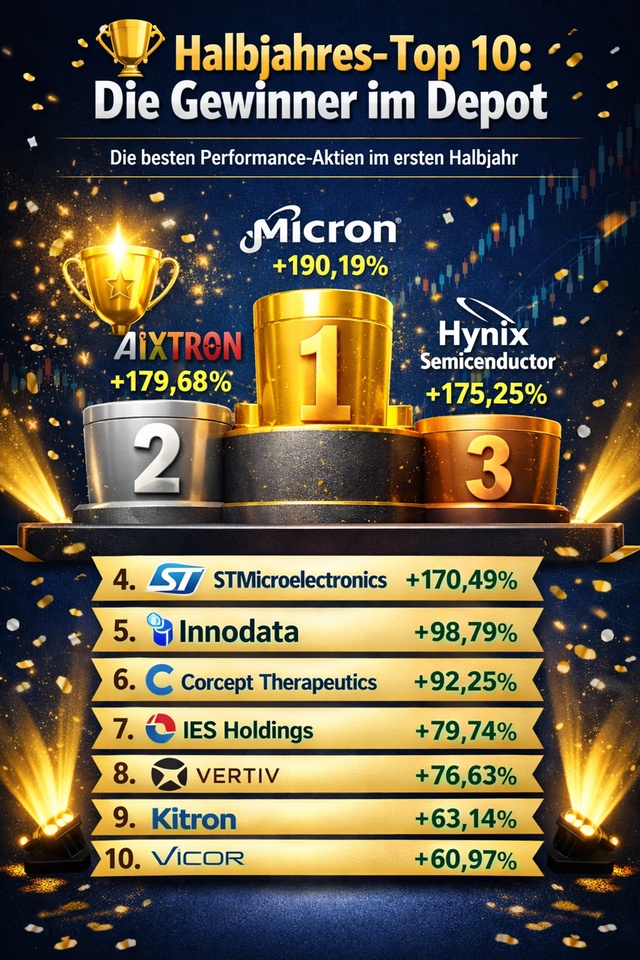
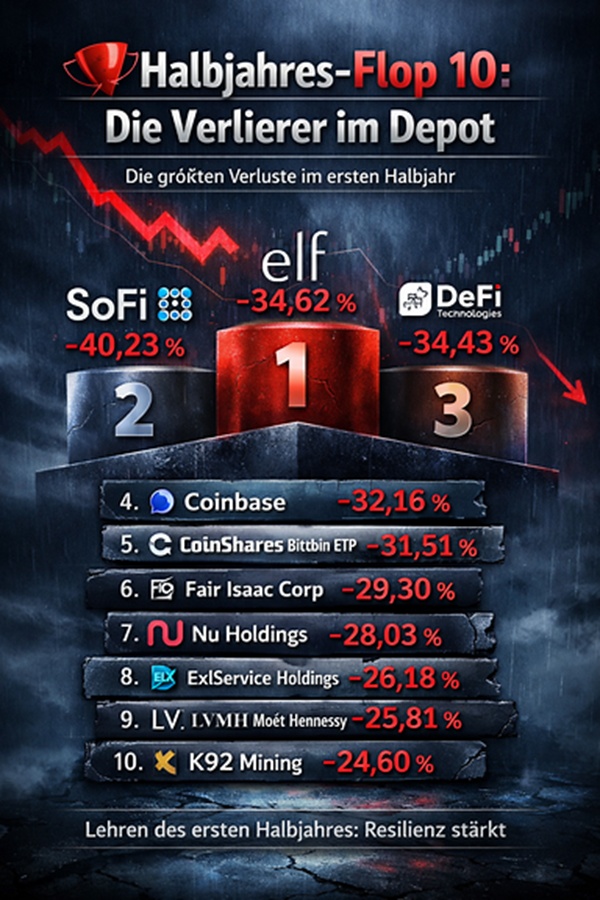
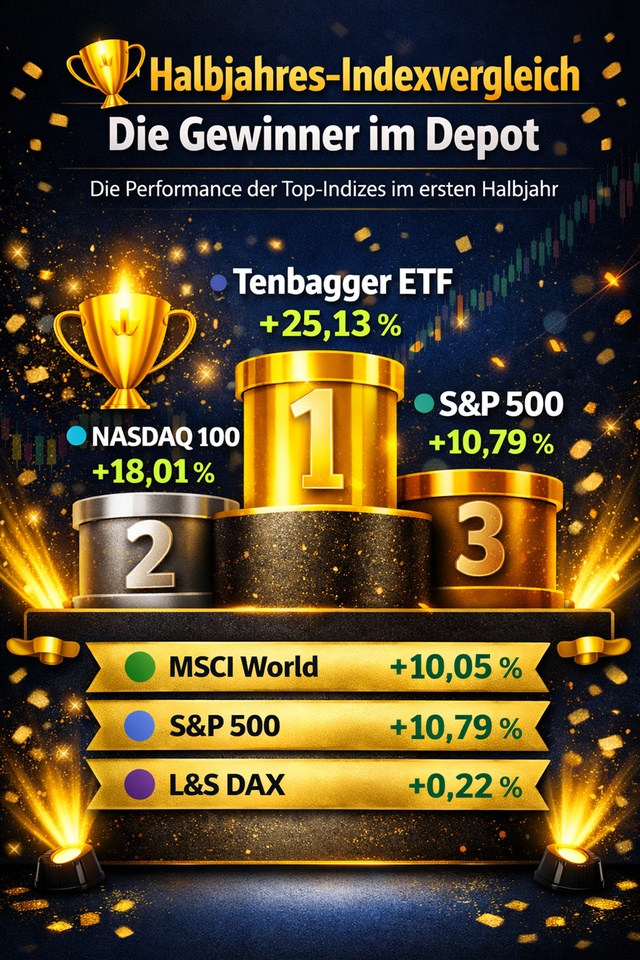
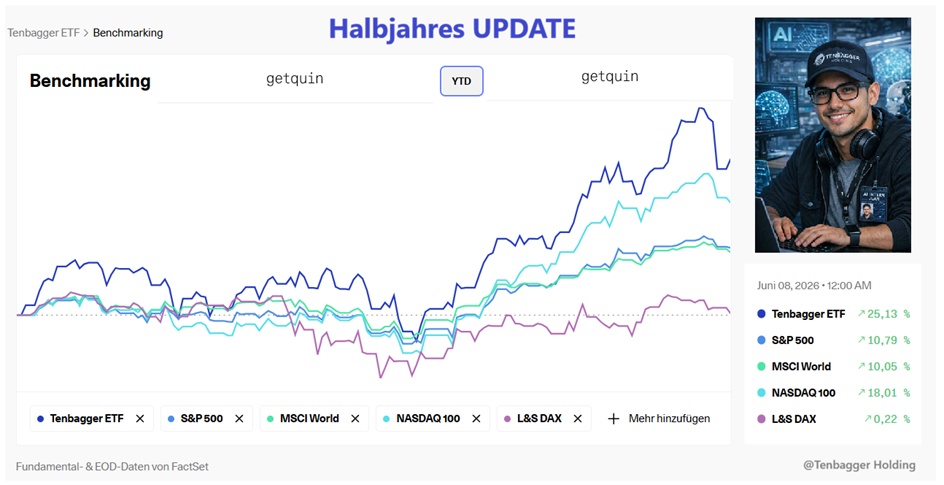
5 month UPDATE
Hello my dears,
The half-year is almost over, so I would like to give you an update.
If you like this type of update, please send me a 👍 to confirm.
There was a rebalancing today.
- Mercedes and Linde were sold -
- As soon as @Dividendenopi the check of $HACK (+0.16%) HACHSAW has been completed, the stock will flow into my portfolio.
The background would be:
- Dividend stocks are exchanged in order to achieve a better dividend yield with the expected share price performance.
I am satisfied with the half-year results.
As you can see from the chart on Friday:
- Is my portfolio significantly more volatile, whether up or down -.
So this is not a portfolio that should be suitable for everyone.
Dear all, how satisfied are you with your YTD results?
7373
36 CommentsI don't know. My semester isn't even over yet🤔
•
88
•Trending Securities
Top creators this week
Real-time data from LSX · Fundamentals & EOD data from FactSet