

Entry targets got hit for $NFLX (-0.51%) and $GRAB (-0.92%)
And so: 200K+ portfolio is here. 🥳
Posts
49Entry targets got hit for $NFLX (-0.51%) and $GRAB (-0.92%)
And so: 200K+ portfolio is here. 🥳
Just a heads-up: I don't own any shares. I $GRAB (-0.92%) already sold my shares two months ago.
But I think this information is important for current investors:
"Report: Grab Holdings is negotiating a majority stake in BNPL company Atome"

Here's the hot stuff from Grab Holdings
$GRAB (-0.92%) (NASDAQ: GRAB) Q2 2026 Earnings Release, fresh from Singapore:
🚀 Top-line Performance & Ecosystem Growth
Grab continues its rapid expansion in Southeast Asia in the second quarter of 2026 (ending June 2026), nearly surpassing the $1 billion revenue threshold:
Total revenue: Climbed by +22% YoY to $997 million (currency-adjusted +21%).
On-Demand GMV (Gross Merchandise Value): Rise by +21% YoY to $6.5 billion. Record number of users: Monthly active transaction users (MTUs) climbed to 54 million.
Segment Performance:
Deliveries: Revenue increased by +21% YoY to $531 million (driven by advertising & transactions).
Mobility: Revenue grew by +12% YoY to $331 million (GMV +18%).
Financial Services / Digibank: Revenue surged by +59% YoY to $134 million —driven by loan disbursements ($1.2 billion disbursed) and the consolidation of Superbank.
🔮 Massive jump in profitability & margins
The once-loss-making ride-hailing and delivery giant is transforming into a scaling cash machine:
Net Income: Soared dramatically to $235 million (up from just $20 million in the same quarter of the previous year), also boosted by one-time effects from the Superbank consolidation.
Adjusted EBITDA: Climbed by +54% YoY to 168 million USD (previous year: $109 million).
Margin expansion: The adjusted EBITDA margin improved from 13.3% to a robust 16.9% of revenue.
🤖 Full-Year Forecast Raised & $750 Million Buyback Capacity
Due to strong tailwinds, management is raising its full-year targets and returning significant capital to shareholders:
FY 2026 revenue forecast raised: Now at $4.10 to $4.15 billion (previously set lower).
FY 2026 Adjusted EBITDA raised: Raised to $720 million to $740 million.
Share buyback program: The Board has approved a new $750 million share repurchase program (bringing the total authorization to 1.75 billion USD).
⚡ 💡 Jack’s Takeaway
Grab impressively demonstrates that the super-app strategy is paying off in Southeast Asia! The 18th consecutive quarter of rising adjusted EBITDA underscores the company’s operational strength. While Mobility and Deliveries are reliably doubling in size, the Financial Services division (Digibank + Superbank) is emerging as a true profit accelerator. An upward revision of the full-year forecast plus a fresh $750 million buyback package—that’s what an all-around successful earnings report looks like!

Hello, community,
I could really use some help from the smart folks in the community.
I’d like to downsize my portfolio, but unfortunately, I’m really having a hard time choosing—and I’m wondering if I should sell a few shares of some tech stocks and use the cash to further increase my holdings in the ones I already own.
After much thought, these 6 candidates are on my shortlist:
$3350 (-8.6%) Metaplanet (it was pure FOMO), but also the smallest speculative position
What do you think of my selection, or which stocks would you have chosen instead?
I’d love to hear lots of opinions.
Best regards
Hello to Community✌️
At the end of the month, I would like to introduce you to another stock that I personally find extremely exciting. After that, that's it for the next few weeks. 👀
In my opinion, this stock is interesting for both short-term gamblers and long-term investors. The former 🫵 @Multibagger will primarily celebrate the momentum and the potentially rapid price movements. 📈
Others could discover an exciting growth story with long-term potential. 👀🤔
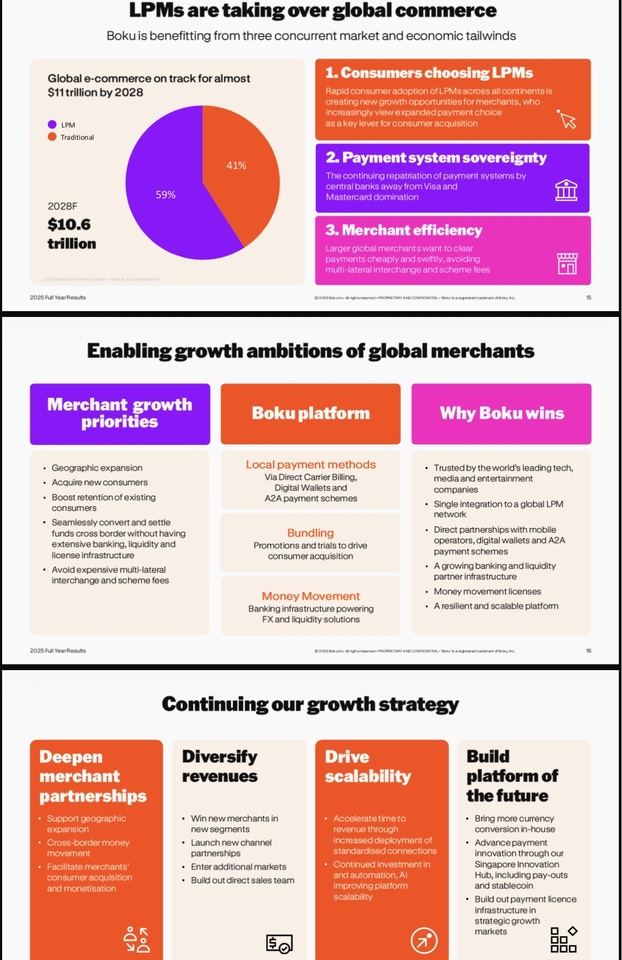
Today it's all about Boku $BOKU
BOKU INC. : The invisible tollbooth of the global tech giants:
Boku $BOKU is not a hyped, unprofitable FinTech dream that thrives on venture capital. It's a highly profitable, UK-based network powerhouse that's carving out the niche of Alternative Payment Methods (APMs) has occupied. While traditional credit card giants are reaching their limits in emerging markets and with Generation Z, Boku $BOKU acts as the invisible digital toll booth for the world's biggest companies. If someone is on Spotify, $SPOT (+6.14%) Netflix $NFLX (-0.51%) or the $GOOGL (-1.17%) Google Play Store via cell phone bill (direct carrier billing) or local eWallet (such as Pix, Mercado Pago $MELI (-1.56%) , Alipay $9988 (-1.09%) or GrabPay $GRAB (-0.92%) ), Boku mercilessly cuts off its fee in the background. Boku $BOKU benefits from the unstoppable global trend of digital consumption - regardless of which app is currently in vogue.
📱The business model: the 3-pillar transaction rocket 💳🌐📈
Boku $BOKU has transformed itself from a pure SMS payment service into a state-of-the-art, global identity and payment network (Boku Platform):
The insatiable eWallet & Account-to-Account (A2A) lever: Traditional business mobile operators (DCB) is solid, but the real hyper growth is coming from local wallets (Pix in Brazil, PromptPay in Thailand, Twint in Switzerland). Boku connects these fragmented local markets via a single API for the tech giants. This segment is growing rapidly and driving up transaction value (TPV) massively.
The fortress customer base (The "Whale" portfolio): Boku's client list reads like a who's-who of Silicon Valley: Apple $AAPL (-1.9%)
, Google $GOOGL (-1.17%)
, Meta $META (-0.36%)
, Microsoft $MSFT (-1.27%)
, Netflix $NFLX (-0.51%)
, Spotify $SPOT (+6.14%)
, Amazon $AMZN (+4.42%)
, Tencent $700 (+1.09%) . These giants won't just throw Boku out of their checkout infrastructure because setting up their own local connections in 60+ countries would be regulatory and technical suicide. High switching costs par excellence.
The recurring network effect premium (NRR 124%): Boku grows organically with the success of its customers. The more subscriptions $AMZN (+4.42%) Amazon Prime or Spotify $SPOT (+6.14%) sell in India or Southeast Asia, the more transaction volume automatically flows through Boku's servers - without Boku having to burn new marketing money.
📊The key figures (as of Q1 2026 / FY25 history)
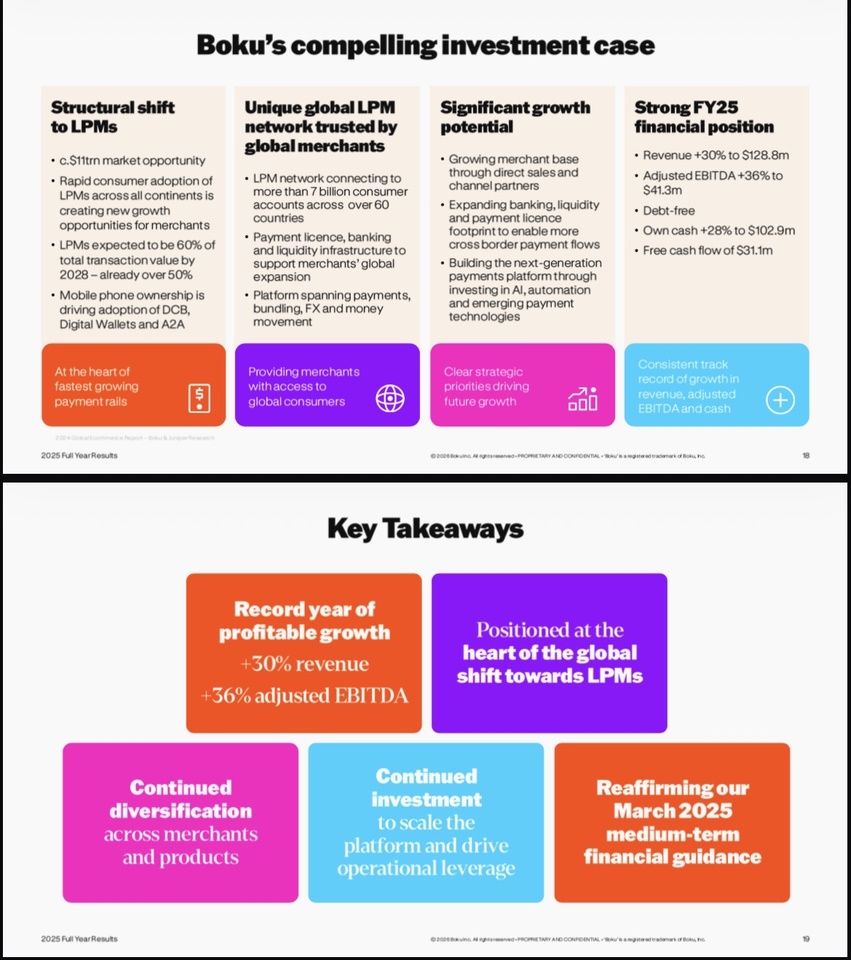
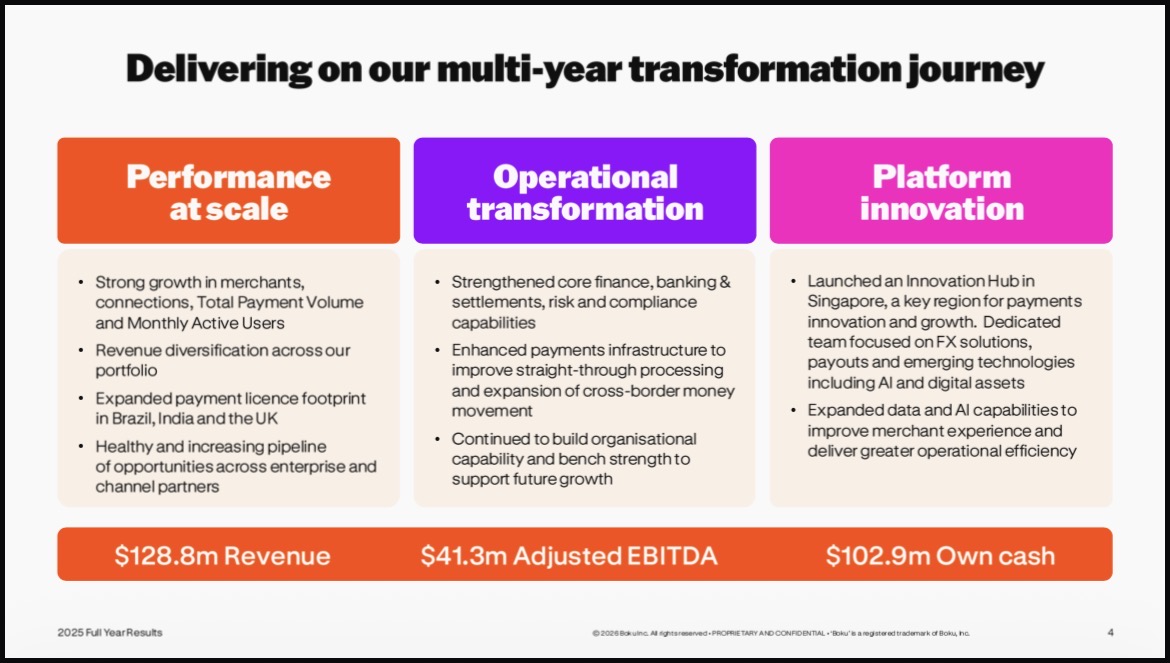
Market capitalization: Approx. GBP 540 million / ~EUR 635 million (Listed on the London Stock Exchange, AIM). A genuine, profitable small cap.
Sales momentum: Continuous growth of around +15% p.a. The shift from pure mobile billing to eWallets and A2A payments is taking off completely and is compensating for the maturity of the old DCB business.
EBITDA levers & margins: The adjusted EBITDA margin is scratching the 35% mark. As the platform infrastructure is in place, almost every additional dollar in transaction fees flows directly through to the bottom line (Gross margin of a proud ~68.5%).
Real FCF margin (SBC-adjusted): Strong ~24,0% of sales. Boku is a cash machine that easily digests its share compensation from operating cash flow without painfully diluting shareholders.
Balance sheet solidity (net cash): No long-term financial debt. Boku is sitting on a net cash position of around USD 50-60 million. This means zero refinancing risk in the current interest rate environment and maximum flexibility for smaller, strategic tech acquisitions.
🚀Why is the share exciting?
✅The demographic bet in e-commerce: In the growth regions (South East Asia, Latin America, Africa), billions of people don't have a credit card, but almost everyone has a smartphone and a local wallet. If you want to sell subscriptions there as a Western tech company, you have to use Boku.
✅The win-win shield against big tech: The often criticized cluster risk is not a one-way street. In markets such as Indonesia, Brazil and India, Boku is $BOKU for Apple $AAPL (-1.9%) and Google $GOOGL (-1.17%) not an annoying cost factor, but the exclusive revenue enabler. Without Boku's local infrastructure, the tech giants would have to do without millions of customers who are willing to pay and simply do not have a credit card. Apple $AAPL (-1.9%) and Google $GOOGL (-1.17%) are therefore structural partners 🤝not opponents - Boku brings them incremental revenue that they could not generate on their own.
✅Evolution of the moat & diversification: Management understood the historical "what if" scenario (the loss of a major customer) and proactively mitigated the risk. Through aggressive expansion into digital wallets and account-to-account (A2A) payments (which now account for 45% of revenue), Boku has fundamentally diversified. The moat today is of a technical, regulatory and geographical nature - not even a Silicon Valley giant can copy that in two quarters.
✅Operating leverage beats inflation: Boku's cost base consists primarily of IT infrastructure and developers. If the price of digital subscriptions rises worldwide due to inflation, Boku's transaction volume and thus its fee income automatically increases with it. A perfect inflation hedge.
✅Consolidation of the FinTech infrastructure: Boku $BOKU has spent years digging the regulatory foundation (licenses in dozens of countries). You don't rebuild this moat in two quarters. This also makes the company a permanent, highly attractive takeover target for larger payment groups.
⚠️Die Risks
❗️Brutal cluster risks (whale dependency): Apple $AAPL (-1.9%) , Google $GOOGL (-1.17%) and Amazon $AMZN (+4.42%) account for a lion's share of the volume. If one of these giants decides to slash fees or build its own global wallet infrastructure, the Boku story will be fundamentally shaken
❗️Commercial pressure on margins: Unit economics for eWallets are often thinner than for the old Direct Carrier Billing (DCB). Boku has to bolt on massive volumes to cushion the structural decline in margins per transaction
❗️Currency effects (FX risk): As Boku collects fees worldwide in local currencies (and accounts in GBP), severe currency turbulence in the emerging markets can visually spoil operating performance .
✍️Mein personal conclusion + Reaper verdict 💀
I personally find Boku Inc. extremely exciting. Boku $BOKU has an amazingly strong business in the background. For me, this is a highly profitable niche champion with a strong balance sheet and a business model that is much more robust than it appears at first glance.
What I particularly like is that without Boku $BOKU companies like Google $GOOGL (-1.17%) or Apple $AAPL (-1.9%) would miss out on millions of potential customers that they would not be able to reach via their traditional payment channels. Boku $BOKU opens up sales for them that would otherwise simply not exist. Why should the tech giants invest hundreds of millions of dollars to apply for their own regulatory licenses in dozens of emerging countries and connect local payment systems when they can simply use Boku's ready-made infrastructure instead? Boku $BOKU solves a complex problem that its customers could only solve themselves with considerable effort and is paid well for doing so. This also seems to me to limit the risk of major customers suddenly ending the collaboration. The benefit is simply too great and the alternative too costly.
BONUS MATERIAL:
💀Jack's Verdict:
"Let's not kid ourselves: Boku's operating business is sexy as a perfectly oiled money printing press. The NRR of 124% shows that the tech giants are becoming more and more dependent on Boku's API. But on the stock market, the music is also made by the price. A fwd P/E ratio of over 31x and a PEG of 1.7 for 15% growth? Once again, the market has looked a little too deeply into the hype bowl. The market is currently pricing in that the next 10 years will be flawless. If Apple coughs tomorrow and pushes down the fees by one basis point, the valuation will plummet. Therefore: stock on the watchlist, no emotional market purchases. We are laying down at 135 GBX on the lookout. If the impatient retail investors lose their nerve at the next macroeconomic dip and the stock corrects there, we will grab it. Before that, the capital stays in the holster."
Reaper rating: WATCH, TEND TO BUY 🔥
Reaper Score:
6,8/10
@Get_Rich_or_Die_Tryin
@Tenbagger2024
@Raketentoni
@schlimmschlimm
@Stocktective and of course all other ✌️
+ 4

I recently started this portfolio, being the reason it’s still quite small and not well balanced.
I would like to significantly expand my $PRAE (-0.81%) position, lowering the percentage of my portfolio that $MELI (-1.56%), $NU (-2.73%) and $GRAB (-0.92%) take up.
The primary reason for not investing in the US is because I believe that a large part of their stock market is overvalued, and that the people and politicians there will bring the country to its knees.
Long-term I see much more potential in Europe and Latin American.
Feel free to disagree.
Grab Holdings $GRAB (-0.92%) reported its first quarter 2026 results on May 5, 2026 and showed a robust financial performance that was in stark contrast to investor sentiment. Despite year-on-year revenue growth of 24% and a 46% increase in adjusted EBITDA, the stock fell 0.82% to USD 3.64 in after-hours trading, hovering near its 52-week low of USD 3.48.
The Southeast Asian super app operator proved resilient in its core businesses, with particular strength in the financial services segment, although seasonal pressures from Ramadan and the Chinese New Year impacted usual demand patterns.
Highlights of the quarterly performance
As the following overview of key financial metrics shows, Grab achieved significant growth in several dimensions in the first quarter.
The company reported revenue of USD 955 million, representing year-on-year growth of 24% (19% at constant exchange rates). Gross merchandise volume (GMV) in the on-demand segment reached USD 6.13 billion, an increase of 24% year-on-year and 21% on a constant currency basis. The number of monthly active users rose to 51.6 million, an increase of 16% compared to the same period last year.
Adjusted EBITDA reached USD 154 million, representing the 17th consecutive quarter of growth for this metric. The EBITDA margin improved to 16.2 % of sales, compared with 13.7 % in the prior-year quarter. Of particular note, adjusted free cash flow was positive at USD 98 million, compared to a negative USD 101 million in the first quarter of 2025. Adjusted free cash flow for the last twelve months reached USD 489 million.
The following chart illustrates the year-on-year development of Grab's primary financial ratios.
Analysis of segment performance
Grab's delivery business maintained its strong momentum, with the following key performance indicators demonstrating the health of the segment.
The Delivery Services segment generated revenue of USD 510 million, up 23% year-on-year, while GMV grew by 25% to USD 3.91 billion. Adjusted segment EBITDA improved by 40% to USD 88 million, representing 2.3% of GMV, compared to 2.0% in the previous year. The company noted that the number of daily active users in April 2026 exceeded the seasonal highs of December 2025, indicating continued user engagement beyond typical peak periods.
The mobility segment proved resilient despite regional fuel price increases, as illustrated in the following performance overview.
Revenue in the Mobility segment reached USD 337 million, up 19% year-on-year, with GMV increasing by 23% to USD 2.22 billion. The segment's adjusted EBITDA grew by 24% to USD 198 million and maintained a solid margin of 8.9% in relation to GMV. Operational data showed that weekly average daily transportation volume increased 32% in April 2026 compared to April 2025, while active driver partners' online hours increased 19% over the same period.
Financial services developed into Grab's fastest growing segment, as the following key figures show.
The segment's revenue increased by 43% year-on-year to USD 107 million, while the gross loan portfolio more than doubled, growing by 130% to USD 1.44 billion. Importantly, the segment's adjusted EBITDA loss decreased by 45% to USD -17 million. This corresponds to an improvement from -41.1 % of sales to -15.7 % and signals a clear path towards profitability.
Operational dynamics
Despite seasonal challenges, Grab's key operating figures showed sustained growth. The following chart shows the development of user engagement in the delivery segment.
The lending business in the financial services segment showed a particularly strong acceleration, as the trends in quarterly lending illustrate.
Loan originations reached USD 1.05 billion in the first quarter of 2026, an increase of 67% year-on-year, which corresponds to an annualized rate of USD 4.2 billion. Management emphasized that credit risk continues to be managed prudently as the business scales and pointed out that expected credit losses as a percentage of the gross loan portfolio had improved year-on-year.
The mobility business proved resilient to fuel price pressures in the region, with the following data demonstrating stable driver supply and sustained demand.
Strategic initiatives
At its GrabX event, the company unveiled several new product features designed to enhance the user experience and encourage long-term engagement. These included "Group Rides", which allows up to four passengers to share a ride and split the fare, "Travel Pay", which enables local QR code payments for tourists and travelers, and "Consumer Maps" (GrabMaps), which provides enhanced navigation and discovery features for restaurants, stores and other places of interest.
Management highlighted ongoing investments in artificial intelligence infrastructure, including the launch of 'Turbo' driving mode, which reportedly increased driver revenue by 23%. However, these AI investments contributed to increased regional corporate costs, which rose to USD 114 million from USD 86 million in the prior-year quarter.
Financial position & outlook
Grab had a strong balance sheet as of March 31, 2026 with net liquidity of USD 4.99 billion. This represents a slight decrease from the USD 5.37 billion reported at the end of 2025, but is significantly higher than the USD 5.86 billion reported a year earlier. The company's gross liquidity amounted to USD 6.93 billion, while loans and borrowings amounted to USD 1.95 billion.
The company confirmed its guidance for the full year 2026, forecasting revenue of between USD 4.04 billion and USD 4.10 billion, representing year-on-year growth of 20% to 22%. The forecast for adjusted EBITDA remained unchanged at USD 700 million to USD 720 million, which implies growth of 40% to 44%. Management is confident that the Financial Services segment will reach break-even in adjusted EBITDA in the second half of 2026.
The following slide outlines the company's unchanged outlook for the full year.

Hey, GQ crew ✌️
My first post since I got kicked out about 4 weeks ago—who would’ve thought that showing solidarity with one of the members (@Klein-Anleger ) would lead to a ban so quickly? But getquin’s generosity was so BIG (and, most importantly, “on a trial basis”) that they graciously let me back into the holy grail of the GQ community 😉
So guys, learn from my mistakes: The leniency here isn’t an “infinite money” glitch! Save your solidarity for later, keep your support for other members at zero, and most importantly 🚨: No sneaky advertising for alternative financial platforms like “Cisdord” 😉😂.
Sorry, that little dig after four weeks away was a must 🤝
But joking aside…
⏳The first three months of 2026 have passed. Time for a brief interim assessment of the current status of my portfolio rebuild.
Before I started rebuilding my portfolio, I naturally thought about what strategy I wanted to pursue in the coming months and years—especially with regard to stock selection and weighting.
To be honest, my original plan was to maintain a portfolio with a maximum of 20 stocks. As things progressed, however, I realized that it probably wouldn’t stay at 20—the number is more likely to rise to around 30 positions (+/-)—
♟️My Focus & Strategy:
To put it simply: The clear focus is on growth 🚀. Dividends play a rather secondary role here. Here, I’ll show you my shopping list—or rather, what my portfolio should look like in the future. The stocks I’ve already bought are marked with a green checkmark; those without a checkmark are ones I’m still waiting on ⏳
🤖TECH:
🏦💸FINANCE:
🏥🩻HEALTHCARE:
🏭🏗️INDUSTRY & OTHER:
————————————————————————
Here is my expanded watchlist:
IN THE TECH SECTOR:
RAMBUS $RMBS (-7.76%) , QNITY ELECTRONICS $Q (-4.65%) ,
INNODATA $INOD (-1.85%) , NETFLIX $NFLX (-0.51%) ,
VERTIV $VRT (-2.19%) , PALANTIR $PLTR (-4.98%) , VAT GROUP $VACN (-4.62%) , BROADCOM $AVGO (-3.9%) , AMADEUS IT $AMS (-1.23%) , DISCO CORP $6146 (-4.76%) , A10 NETWORKS $ATEN (-6.53%) , RORZE $6323 , CAMTEK $CAMT (-6.2%)
FINANCE:
APOLLO GLOBAL $APO (-1.77%) / BLACKSTONE $BX (-1.23%) , ALLIANZ $ALV (-0.06%) , FIRSTCASH $FCFS (-3.54%) , BLACKROCK $BLK (-2.55%) SKYWARD SPECIALTY INSURANCE $SKWD , VERISK ANALYTICS $VRSK (+3.52%) PRIMERICA $PRI (+0%) , ERIE INDEMNITY $ERIE (+6.73%) , MAREX GROUP $MRX , BGC GROUP $BGC (-1.23%)
HEALTHCARE:
MERIT MEDICAL SYSTEMS $MMSI (-6.01%) , REGENERON PHARM $REGN (+11.17%) , UFP TECHNOLOGIES $UFPT (-4.42%) , COLLEGIUM PHARM $COLL (-0.93%) , LIGAND PHARM $LGND (+1.77%) , HOYA CORP $7741 (-0.65%) , SHIONOGI $4507 (+0.03%) , IRADIMED $IRMD (-7.82%)
REST:
MISUMI GROUP $9962 (+3.26%) , KANEMATSU $8020 (-1.13%) , APPLIED INDUSTRIAL TECH $AIT (-2.37%) , BADGER METER $BMI (+1.63%) , CEMENT ROADSTONE HOLDING $CRH (-1.23%) , KADANT $KAI (-1.24%) , INTERTEK GROUP $ITRK (+0.07%) , IDEX CORP $IEX (-1.5%) , ORLA MINING $OLA , NEWMARKET CORP $NEU (-0.35%) , ROTORK $ROR (+0.84%) , POWER INTEGRATION $POWI (-10.12%) , LINDE $LIN (+2.62%) , GAZTRANSPORT & TECHNIGAZ $GTT (-2.88%)
This isn’t my final stock selection or watchlist yet. Of course, changes can always happen—for example, if the @Tenbagger2024 continues to introduce such hidden gems 🙏🏽🧐
————————————————————————
What should the sector/country allocation look like?
Let’s start with the “desired”
🌍country allocation:
🇺🇸🇨🇦USA ~60%
🇪🇺EUROPE ~20%
🇯🇵 JAPAN/ASIA ~15%
Remaining ~5%
Sector weightings should be as follows:
💻 TECHNOLOGY: ~30–35%
💸FINANCE: ~20–25%
🏥HEALTHCARE: ~10–15%
🏭INDUSTRY: ~10–15%
REMAINING: ~5–10%
So, what’s happened since the start of the year?
Of course, there were no sales 😬
There were a few purchases where I had a hand in the decision.
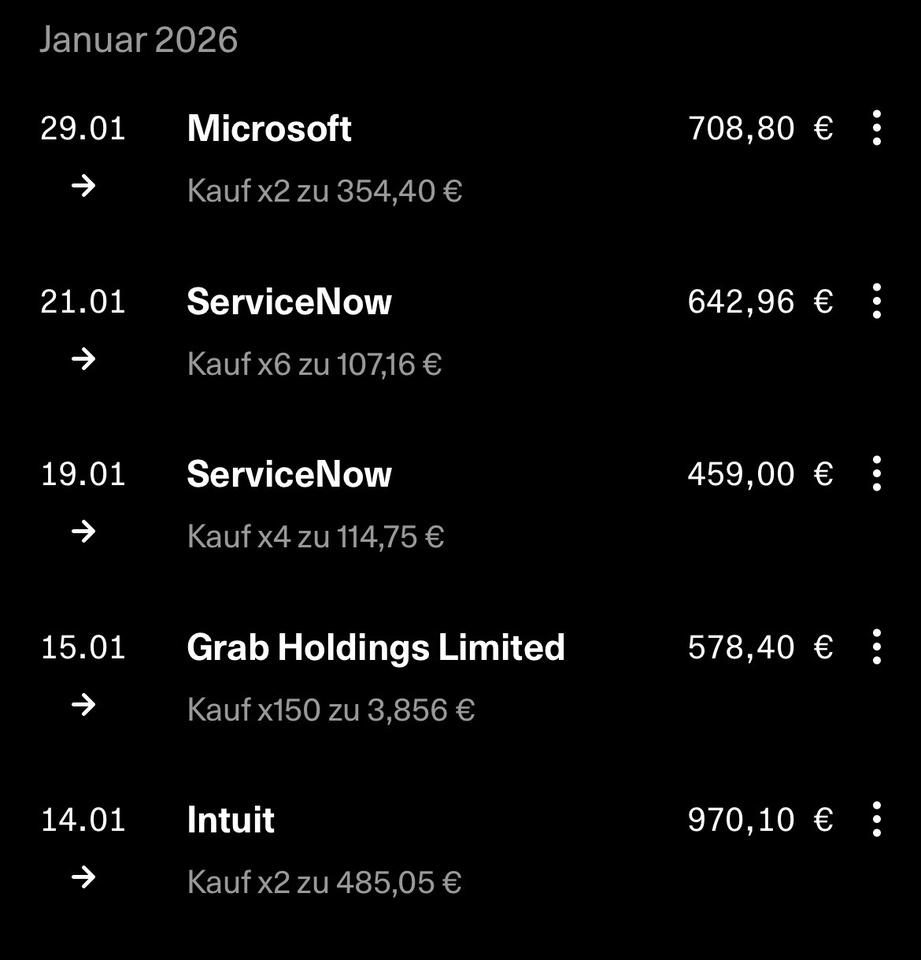
JANUARY PURCHASES
$INTU (+2.91%)
$GRAB (-0.92%)
$NOW (-3.64%)
$MSFT (-1.27%)
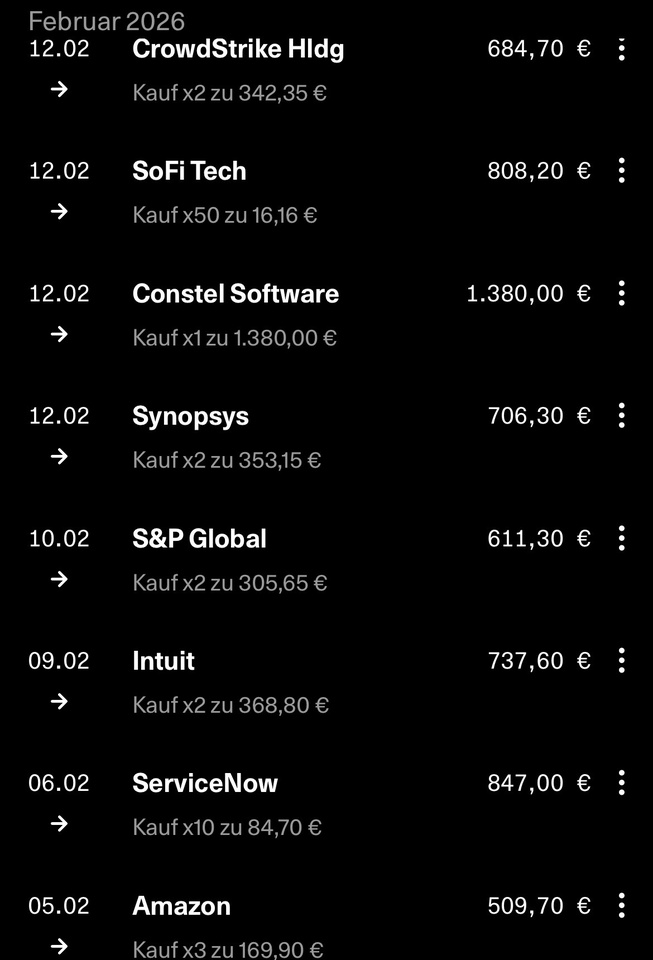
FEBRUARY PURCHASES
$NOW (-3.64%)
$INTU (+2.91%)
$SPGI (+1.03%)
$SNPS (-3.66%)
$CSU (-0.32%)
$SOFI (-2.84%)
$CRWD (-4.03%)
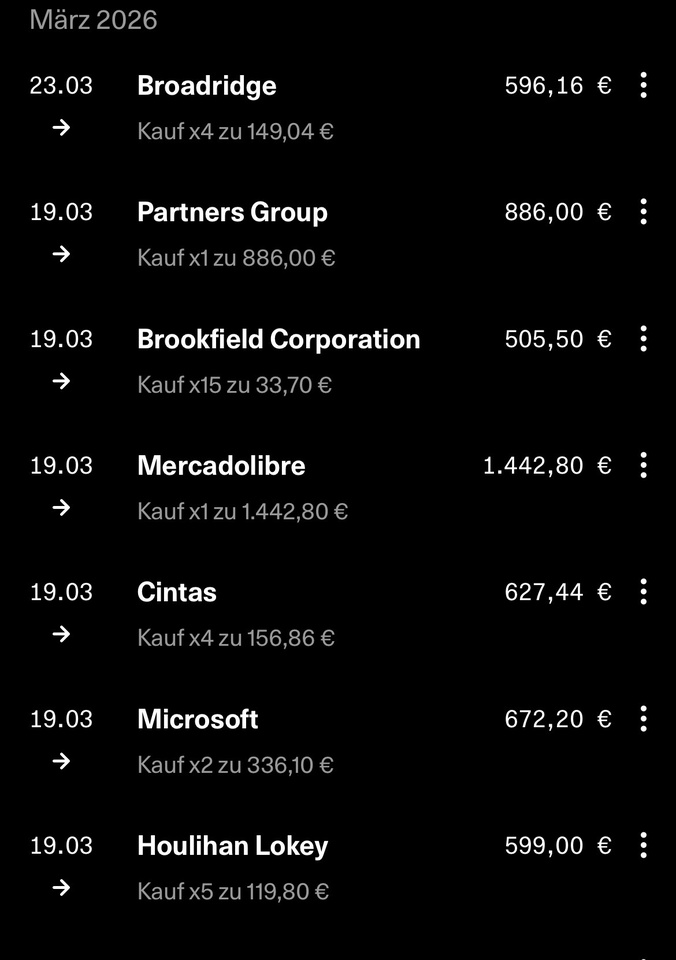
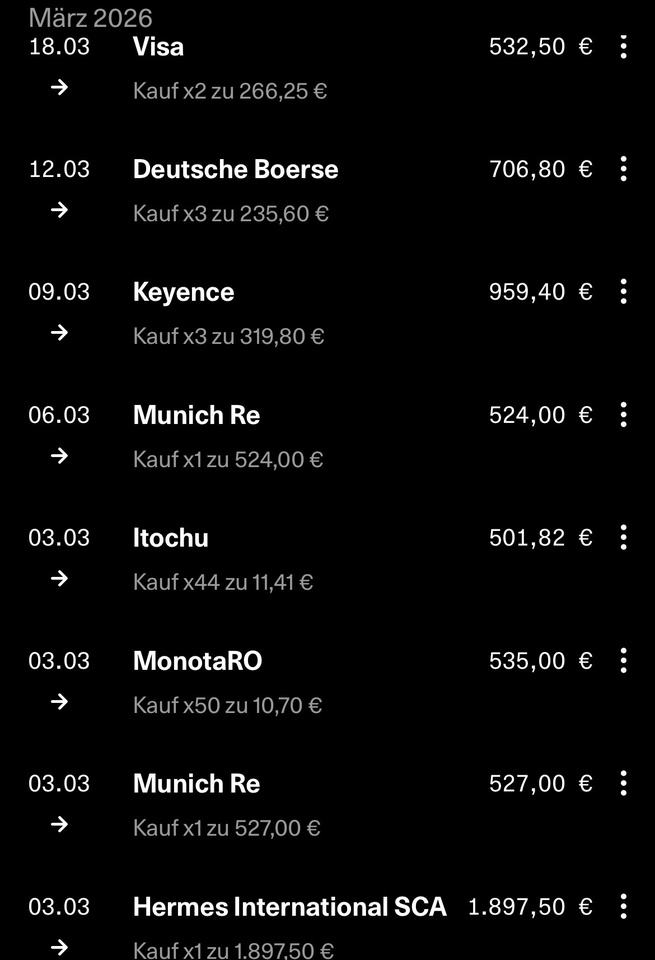
MARCH PURCHASES
$MUV2 (+1.82%)
$3064
$8001 (+2.67%)
$6861 (-3.95%)
$DB1 (+1.6%)
$V (+1.05%)
$HLI (-1.08%)
$MSFT (-1.27%)
$CTAS (+1.72%)
$MELI (-1.56%)
$BN (-0.58%)
$PGHN (-0.86%)
$BR (+0.56%)
Given the global political situation—especially because of that 🍊 in the White House, whose tweets cause more tsunamis 🌊than actual natural disasters—and the current drawdown in the S&P 500 (which is actually working out great for me right now and bringing me a lot of joy 🤩), I’m consequently in the red on some of my purchases so far 💦🫧.
But hey, we’re investing for the long term, after all, right? So, taking it easy, keeping it chill 🥱 I’ll most likely hold off on making any more purchases for the time being over the next few days or weeks, park my cash elsewhere or put it in a money market account, and wait to see where the market settles or wait for it to stabilize.
What do you guys have on your watchlist?
Are you sitting on the sidelines right now, or how are you handling the current situation?
@Get_Rich_or_Die_Tryin
@Tenbagger2024
@Max095 And, of course, all the other members
Okay, that’s enough for now 😂
That’s all from me for now ✌️
Your Stock Master

I'm currently traveling in Southeast Asia - and what strikes me again:
👉 The best investment ideas are often right in front of you in your everyday life.
I have consciously paid attention to which companies I constantly come across here - and collected some exciting names:
🛒 Everyday life & consumption
7-Eleven ($3382) (+1.66%)- felt like it was on every corner
Heineken (Tiger Beer) ($HEIA) (+1.98%)- THE beer here
Magnum - extremely present with ice cream
🏦 Financial sector
OCBC ($O39) (-0.95%) - one of the big banks in Singapore
🚛 Industry
Isuzu ($7202 (-1.01%)) - an incredible number of trucks on the roads
And then of course:
Grab ($GRAB) (-0.92%) - you can hardly get around here without the app
💡 What I find exciting:
Many of these companies have strong local market positions that are often not even on the radar from Europe.
It's precisely observations like this that always give me new investment ideas - far removed from the classic US tech stocks.
❓ Now I would be interested:
Which stocks have particularly caught your eye while traveling - and have you perhaps even invested in them?

Top creators this week


