
Last week's Neocloud crash has $CRWV (-1,58%), $NBIS (+0,56%) and $IREN (+2,72%) sent it into a tailspin. What’s behind this, and what has actually changed for the future?
It all starts with the price of oil
Since the attacks on Iran, the price of oil has risen from ~$80 in August to over $106 per barrel. This is having a major impact on U.S. inflation:
- Consumer Price Index (CPI): 3.7% in September, compared to an expected 3.6%. That’s nearly double the Fed’s 2% target
- Core inflation: 2.6%, also above expectations
- Producer prices (PPI): 6.3% year-over-year, more than three times the Fed’s target. Month-over-month: +1.3%, nearly double the expected increase and the sharpest rise since March 2022
The Fed raised interest rates on September 16 for the first time since 2023 raised interest ratesto 3.75–4.00%. The yield on 10-year U.S. Treasury bonds stood at over 5.2% at the end of September, the highest it has been since 2007. Added to this is a U.S. government that is sinking deeper and deeper into debt and must continually issue new bonds.
This is precisely where the problem with Neoclouds lies: The expansion of AI is largely financed by debt and competes for the same investors as the U.S. government. If a government bond yields over 5% with almost no risk, lenders will demand significantly more from a company that is still operating at a loss.
The trigger for the crash: CoreWeave’s bonds
On October 14, a chart went viral showing a CoreWeave bond worth $1.25 billion with a yield of just under 15% . It was issued in June at 9.625%. The credit default swap (CDS) is at a record high of 1,194.5 basis points; on October 6, it was still at 368.
According to standard calculations, this corresponds to a probability of default of over 60% within five years.
On the same day, Gartner added: By 2030, over 80% of Neocloud providers are expected to lose their independence. By then, AI data centers would generate at most $3.6 trillion in revenue, whereas $8.5 trillion would be needed.
Is this fear justified?
In CoreWeave’s case, partly yes. The higher market yield doesn’t affect the interest rate on existing bonds, but each new round of financing becomes more expensive, and CoreWeave’s growth depends on new loans. However, the 60% figure is a market price from a week of panic and not a forecast.
IREN and Nebius are in a different position
IREN has financed the Microsoft project $MSFT (+1,36%) at ~6% with $3.6 billion. Microsoft accepted Horizon 1 in August, and revenue has been generated since then. Horizon 2 through 4 are scheduled to follow in the fourth quarter; contractually, there is a buffer until early Q2 2027.
Information is currently circulating on X that Microsoft $IREN (+2,72%) is said to have provided incorrect network requirements, forcing the current Childress data centers to be have to be . Horizon 2 is reportedly delayed by ~45 days as a result; Horizon 1 will continue to operate and will continue to be paid for by Microsoft during the retrofit. Horizon 3 & 4 are not expected to be affected, as they will be completed directly with the correct network specifications. Thus, all four buildings are expected to generate revenue by the end of the year as planned. None of this has been officially confirmed.
In July, Nebius switched to a more capital-efficient model in which partners finance the data centers. In addition, advance payments from customers already amount to ~40–55% of the contract total, which alleviates a large portion of Neocloud’s financing risk. Added to this is the possibility of asset-backed financing, whereby the data centers themselves can be used as collateral for loans, thereby reducing interest rates. Nevertheless, the market treats the three companies—with their differing financing risks—as a single entity.
Demand points in the opposite direction
The GPU rental prices are rising: As of October 1, Nebius raised the price for B300 GPUs by 21% to $9.50 per hour—the second increase in three months.
The DESKB300 Rental Index, based on actual rental transactions at U.S. neoclouds, reached a record high in mid-October, driven in part by inference using open-source models. This does not bode well for concerns that GPUs are depreciating too quickly.
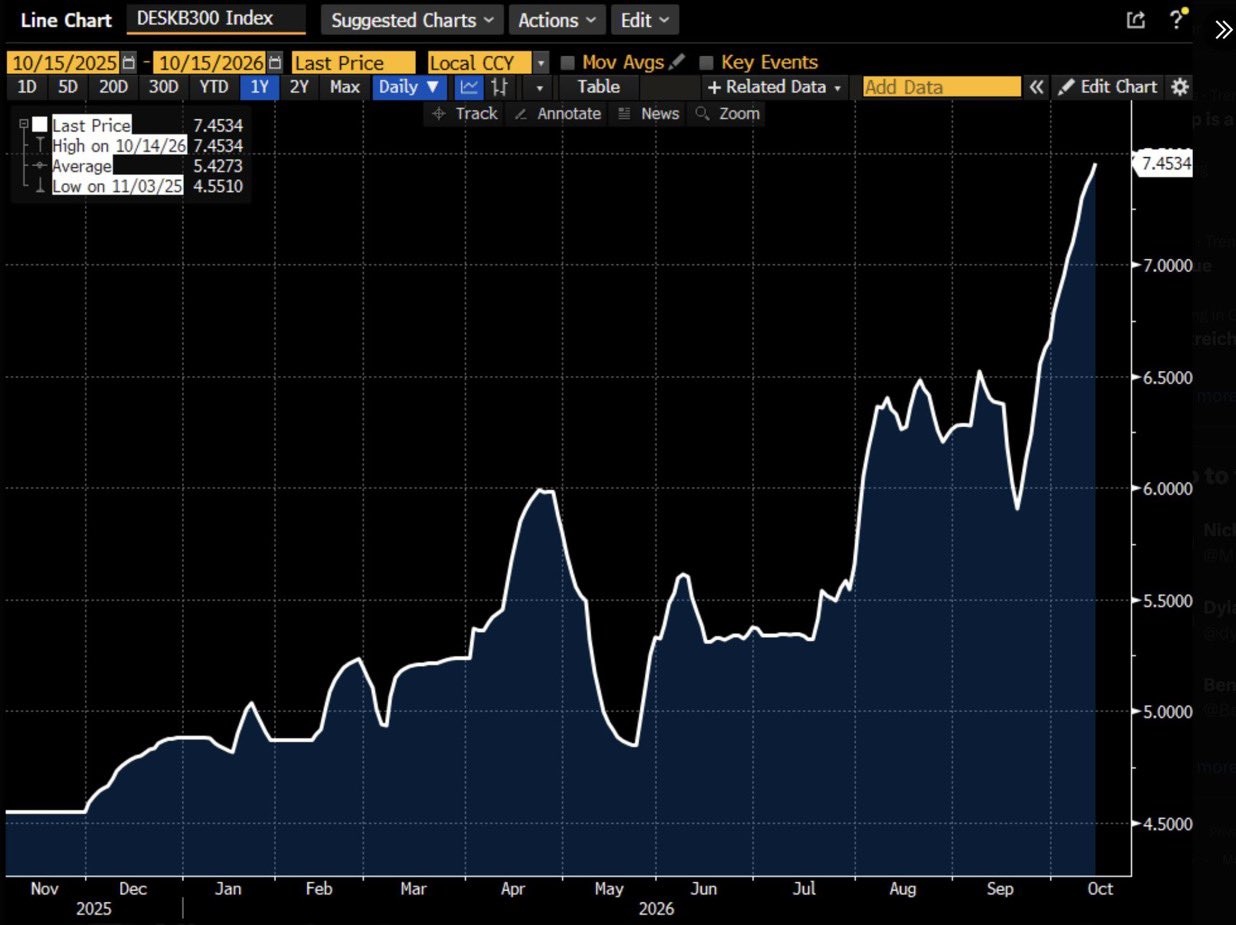
GPU rental prices could also be influenced by rising financing costs and thus increase—so overall, this is more of a neutral process.
Jensen Huang told Bloomberg in Berlin on October 16: “All of this is going to pass.” AI will transform every industry, he said, and we’re only at the beginning. According to Huang, CoreWeave’s cost of capital is actually falling. The bond market saw things differently this week.
Time is the real bottleneck
A data center isn’t built in a single quarter. Securing land and a power connection often takes years, and the construction itself is complex. Neocloud stocks are bets on where these companies will be in three to five years, but they’re traded as if they had to deliver every week.
Even with growing demand, not all of them will make it. Some will repeatedly dilute their shareholders, some will be acquired, and some will fail.
What matters is how management finances the expansion and whether it delivers on its promises.
Sharp sell-offs, months of stagnation, and rallies after which everyone suddenly turns bullish again are all part of this sector and should be clear to every investor. A five-year thesis is difficult to gauge based on year-to-date performance.
Overall, the market is pricing in a financing problem—one that is particularly acute for CoreWeave—and applying it to the entire sector. At the same time, demand for computing power shows no signs of weakness—quite the opposite.
High long-term interest rates are the main risk for all players
If government bond yields remain above 5% for the long term, every new round of financing will become more expensive, and that affects all three companies. CoreWeave, Nebius, and IREN are only at the beginning of their expansion and will need to raise many billions more for data centers and GPUs in the coming years. More expensive financing therefore puts direct pressure on future returns. Against this backdrop, the sell-off is understandable, even if demand itself remains intact.
Key events to watch include Nebius’s earnings report, expected on October 22; the Fed meeting in late October; and the acceptance of Horizon 2. Additionally, the course of the conflict (Iran & the U.S.) must be closely monitored, as it will significantly shape future developments.
Not investment advice
Sources:
https://www.bls.gov/news.release/cpi.nr0.htm
https://www.bls.gov/news.release/ppi.nr0.htm
https://www.sec.gov/Archives/edgar/data/0001878848/000187884826000052/iren-20260630.htm
$ORCL (+1,43%)$APLD (+7,26%)$CIFR (-0,47%)$GOOGL (+1,38%)$MSFT (+1,36%)$AVGO (+1,74%)$AMD (+2,16%)$INTC (+3,02%)$HUT (+1,29%)


