
So all the European and UK markets are up massively on the new $VUKE (-1,19%)
$VTI (+0,66%)
$VMID (-0,35%)
$VUSA (+0,69%)
$VGER (-0,92%) and expecting $GOOG (+1,26%)
$HTGC (-2,31%)
$AMZN (+5,26%)
$AAPL (+0,13%) to push up at US open. But is it just me, but does this not feel like a bull trap? I dont trust that this is the end of the issues with US/IRAN , and dont even feel like they stick to the ceasefire. I know its only known by those in power, but i might take this time to sell in to strength, and keep some cash on the side for if and when it comes down again?! Whats everyone elses thoughts on this?
Vanguard Morningstar Total Stock Market ETF
ETP
ETP
Ticker: VTI
VTI
Price
Discussione su VTI
Messaggi
76Mes·
2 week ceasefire, can you trust this!?
55
2 Commenti
TomTurboInvest@TomTurboInvest
6Mes
•
22
•Mostra la risposta

9Mes·
ETFs vs. Individual Stocks: What’s your "Core-Satellite" Ratio? 🛰️🌍
We all know the rule: Younger = More Stocks, Older = More Bonds. But there’s a second layer most people miss: How much of your stock portfolio should be in broad ETFs versus individual "conviction" picks?
-----------------------
NOTE: This is made for the broader investor group of people. Not most of us on Getquin, who spends more time watching stockgraphs and balance sheets than watching nature outside. ;)
-----------------------
The goal is to balance the safety of a global index with the alpha (market-beating potential) of picking winners. Here is a breakdown of how that ratio usually evolves:
1. The "Aggressive Builder" (Age 20–35)
Target Equity Split: 70% ETFs / 30% Individual Stocks
Strategy: You have the most valuable asset in the world—time.
Why: Use a broad ETF (like $VWCE (+0,58%) or $VTI (+0,66%) ) as your "Safety Net." The 30% individual stock portion is your "Satellite" where you can take bigger swings on growth or tech stocks. Even if a few of your stock picks go to zero, your 70% core keeps your retirement on track.
2. The "Wealth Optimizer" (Age 35–50)
Target Equity Split: 85% ETFs / 15% Individual Stocks
Strategy: Protect what you've built while still "playing the game."
Why: Life gets busy. Between career and family, most investors have less time for deep-dive research. Shifting more into ETFs ensures you don't underperform the market due to a lack of oversight, while the 15% allows you to keep a few high-conviction "blue chips" or dividend growers like $VICI (-1,67%) or $AAPL (+0,13%) .
3. The "Legacy Guardian" (Age 50+)
Target Equity Split: 95% ETFs / 5% Individual Stocks
Strategy: Simplicity and preservation.
Why: At this stage, a 50% drop in one "hot stock" can actually hurt your retirement timeline. Most veteran investors shift to 95% "boring" ETFs. The 5% in stocks is often just for fun or to stay connected to companies you truly love.
The "Golden Rule" of Diversification
If your individual stock picks aren't outperforming your broad market ETF over a 3-year period, you aren't "investing"—you're paying for an expensive hobby.
I'm currently: 65% Stocks, 35% ETFs at 21 years old.
Any thoughts?
55
3 Commenti
9Mes
Age is only a number. Experience is key for investing either in stocks or ETFs.
So for me the thesis is absolut bullshit.
Perhaps in 30 years you will understand my point of view.
So for me the thesis is absolut bullshit.
Perhaps in 30 years you will understand my point of view.
•
33
•
1Anno·
Build a portfolio
Build a portfolio with a STRONG FOUNDATION
ETFs are the easiest way to do this
$SPY (+0,66%) S&P 500
$QQQ (+1,37%) Invesco QQQ
$VTI (+0,66%) Vanguard Total Market
$DGRW WisdomTree Div Growth
$SCHD Schwab US Dividend Equity
33

1Anno·
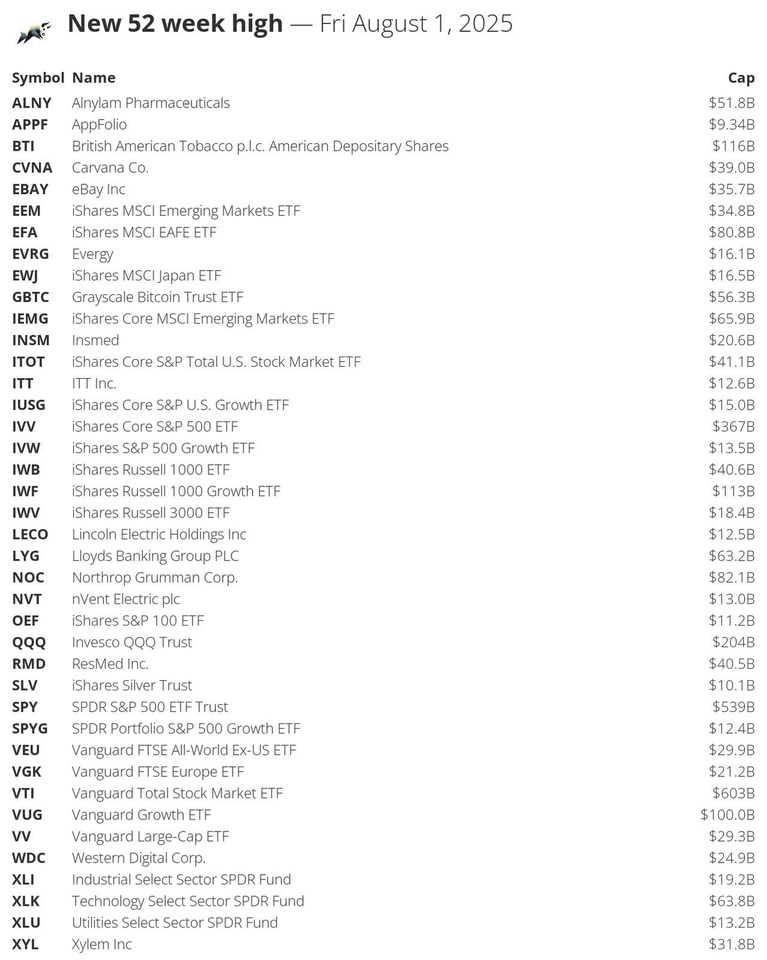
Market News
🔝 Stocks that made a new 52-week high today: $VTI (+0,66%)
$SPY (+0,66%)
$IVV (+0,67%)
$QQQ (+1,37%)
$BTI (-1,88%)
$IWF (+1,17%)
$VUG (+1,27%)
$NOC (-0,53%)
$EFA
$IEMG (+0,98%)
$XLK
$LYG
$GBTC
$ALNY (+0,87%)
$ITOT (+0,65%)
$IWB (+0,65%)
$RMD (+0,56%)
$CVNA (+0,02%)
$EBAY (+0,43%)
$EEM
$XYL (-0,24%)
$VEU (+0,06%)
$VV (+0,69%)
$WDC (+6,61%)
$VGK (-0,77%)
$INSM (-0,71%)
$XLI
$IWV (+0,64%)
$EWJ (+0,37%)
$EVRG (-1,35%)
$IUSG
$IVW
$XLU
$NVT
$ITT (+0,23%)
$LECO (-0,86%)
$SPYG
$OEF (+0,89%)
$SLV
$APPF (+0,08%)
#52weekHigh
33

2Anno·
UCITS or not UCITS, that is the question
I've been asking myself a huge doubt for weeks:
The perfect allocation I want would be 50% $VTI (+0,66%) and 50% $VXUS ... 2 ETFs, covering the large, mid and small-cap market, low purchase commissions, very low management costs (0.05% on average) and assets divided into only two securities.
The cons of this allocation are having American distribution ETFs that pay me dividends in $ taxed at 26% immediately (living in Italy).
Perhaps, the most suitable alternative for a European investor would be to purchase 4 ETFs which, applying the right %, more or less replicate the allocation of the two above, with higher but more efficient management costs for passive investments (45% $VUAG (+0,69%) , 34% $EXUS (-0,21%) , 15% $EIMI (+0,96%) , 6% $WSML (+0,22%) ).
Having the possibility to purchase both ETFs domiciled in Europe and USA, what would you do?
55
3 Commenti
2Anno
Just buy ETFs based in Europe. But watch out for the tax laws/agreements Italy has with other countries. AS For Germans it is best to buy ETFs in Ireland in most cases.
•
22
•
3Anno·
Now if i look to retire at 65 (im 46) holding $VTI (+0,66%)
$JEPQ
$BNDW
$VXUS as my long term holds and $ARCC (-1,45%) and $ZIM (-0,67%) for the see how it goes but if it stays in the red not to fussed stocks - anyone got suggestions on maybe what to change.
The two for fun ones (Zim and Arcc) Im not to fussed about and they are just loose change at the moment but maybe will drop more $$ in to them at a latter stage.
$BNDW
$VXUS
$VTI I make a point of putting around $400 in each month
3Anno·
$ARCC (-1,45%) Only got 6 at the moment but looking to up my positions, just wondering what everyone thinks of this stock for the long term and using the Dividend to put towards something like $VTI (+0,66%)