
$EL (-0,4 %)
$TEM (+4,63 %)
$VRTX (-0,6 %)
$AAPL (-0,78 %)
$PLTR (+0,49 %)
$ON (+0,76 %)
$ZAL (+0,58 %)
$BAYN (-1,12 %)
$DOCN (+2,2 %)
$SHOP (-0,12 %)
$RACE (+0,31 %)
$PFE (-0,39 %)
$PS (-0,12 %)
$DUOL
$SMCI (+1,59 %)
$CPNG (+0,6 %)
$BMW (+0,35 %)
$NOVO B (-0,81 %)
$UBER (+0,33 %)
$CVS (-0,61 %)
$DDOG (+1,42 %)
$MCD (-0,43 %)
$FSLY (+1,85 %)
$HUBS (+0 %)
$ELF (+0,01 %)
$QCOM (-0,05 %)
$ARM (+1,62 %)
$SNAP (+0,95 %)
$APP (+2,88 %)
$MELI (+0,37 %)
$FIG (+0,26 %)
$SHL (+1,57 %)
$DHL (+1,1 %)
$RHM (+0,69 %)
$LMND (+0,17 %)
$OSCR (-0,12 %)
$LYFT (+0,52 %)
$DBX (-0,33 %)
$ABNB (-0,1 %)
$NET (+1,25 %)
$TEAM (+0,12 %)
$LITE (+2,11 %)
$IREN (+2,24 %)
$OKLO
$MRNA (+0,5 %)
$UAA (+0,62 %)
Dropbox
Action
Action
Ticker: DBX
DBX
Price
Discussion sur DBX
Postes
101J·
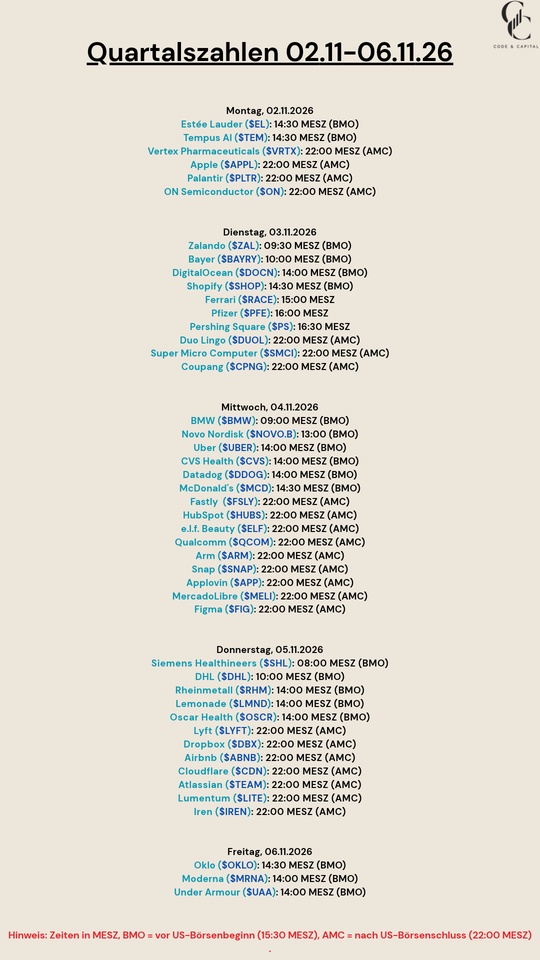
Quarterly Results Nov. 2–Nov. 6, 26
1212

1Année·
23andMe crashes | Dropbox under pressure from activist investor
The shares of DNA testing provider 23andMe $ME experienced a shocking 59% drop on Monday after the company filed for Chapter 11 bankruptcy protection under the US Bankruptcy Code. This drastic decision follows unsuccessful efforts to find a buyer and the resignation of CEO Anne Wojcicki. 23andMe now plans to sell its assets in a structured auction in hopes of securing the remaining value. The company's management had previously rejected a non-binding takeover offer from Wojcicki, who has been trying to take the company private since April. In recent months, the entire independent board of directors has also resigned, indicating deep-seated differences with Wojcicki. 23andMe's history is also marked by legal issues, including a data breach case in 2023, in which a €30 million settlement was reached with affected customers. Customers in California have been informed that they have the right to have their genetic data deleted from the company's systems, which has further shaken confidence in the brand.
In the USA, the cloud storage provider Dropbox is facing $DBX (-0,33 %) is facing increasing pressure from an activist investor who is questioning the founders' control over the company. According to a report in the Wall Street Journal, Half Moon Capital, a small hedge fund, is criticizing the company's slow revenue growth and payment model strategy. The company plans to reform its dual share structure, which gives CEO and co-founder Drew Houston an outsized voting majority. Half Moon holds approximately 40,000 Dropbox shares, which equates to a value of around 1.1 million euros. A majority vote would be required to pass the proposed amendment, which would require Houston's support as his Class B shares entitle him to approximately 77% of the votes. In a further move, Dropbox has already announced plans to reduce its global workforce by 20%, having already laid off 16% of employees in 2023. These measures show that the company is undergoing a restructuring process to ensure both stability and growth in the future.
Sources:
https://finance.yahoo.com/news/23andme-stock-plunges-following-bankruptcy-ceo-exit-203527004.html
https://finance.yahoo.com/news/dropbox-faces-pressure-activist-investor-204111280.html
22


2Année·
Do you think this is still a good ETF? A few years ago I bought Wisdom Cloud Computing ETF $WCLD (+0,3 %)
It is an ETF where I have the most losses but I personally think it still has a future.
The ETF consists of:
Samsara Inc-Cl A 1.86% $IOT (+0 %)
Gitlab Inc-Cl A 1.86% $GTLB (+0,08 %)
Box Inc - Class A 1.82% $BOX (-1,49 %)
Zoominfo Technologies Inc-A 1.80% $ZTNO
Zoom Video Communications-A 1.79% $ZM (+0,36 %)
Mongodb Inc 1.78% $MDB (+0,39 %)
Veeva Systems Inc-Class A 1.75% $VEEV (+0,2 %)
AvePoint Inc 1.71% $AVPT
Workday Inc 1.67% $WDAY (-1,06 %)
Dropbox Inc-Class A 1.66% $DBX (-0,33 %)
Remaining Portfolio 82.30%
I am curious about your opinion!
11
8 Commentaires
Mr. K@TechNav
2Année
•
22
•Voir toutes les 2 autres réponses


3Année·
Quarterly figures on 03.11.2022...
Feel free to leave a follow, because...⤵️
...at 5,000 followers there will be together with getquin, a small thank you for the community. But this post could already be created tomorrow. I look forward to it! On to today's quarterly numbers. In this post that I post every morning, I had announced what was happening today:
https://app.getquin.com/activity/ydggsOLkpb?lang=de&utm_source=sharing
$SBUX (-0,22 %)
Starbucks:
Beat analyst estimates of $0.73 in the fourth quarter with earnings per share of $0.81. Revenue of $8.4 billion beat expectations of $8.33 billion.
$PYPL (+0,03 %)
PayPal:
Beats analyst estimates of $0.96 in the third quarter with earnings per share of $1.08. Revenue of $6.85 billion beats expectations of $6.82 billion.
$DBX (-0,33 %)
Dropbox:
Beat analyst estimates of $0.38 in the third quarter with earnings per share of $0.43. Revenue of $591 million exceeded expectations of $586.15 million.
$DASH (+0,2 %)
DoorDash:
Missed analyst estimates of -$0.55 in the third quarter with earnings per share of -$0.77. Revenue of $1.7 billion exceeded expectations of $1.62 billion.
$GPRO (-2,56 %)
GoPro:
Beat analyst estimates of $0.17 in the third quarter with earnings per share of $0.19. Revenue of $305 million exceeded expectations of $298.85 million.
$MSI (-0,89 %)
Motorola Solutions:
Beats third-quarter analyst estimates of $2.88 with earnings per share of $3.00. Revenue of $2.37 billion beats expectations of $2.31 billion.
$HOT (+1,59 %)
Hochtief:
Reached sales of 7.18 billion euros in the third quarter, up from 5.32 billion a year earlier, and earned 115 million euros on the bottom line, up from 99.8 million a year earlier. Order intake on a comparable basis was 6.5 billion (prior year 7.5 billion).
$K
Kellogg Co:
Surpassed analysts' estimates of $0.97 in the third quarter with earnings per share of $1.01. Sales of $3.95 billion exceeded expectations of $3.77 billion.
$RCL (+0,78 %)
Royal Caribbean Cruises Ltd:
Beat analyst estimates of $0.19 in the third quarter with earnings per share of $0.26. Revenue of $3 billion exceeded expectations of $2.99 billion.
$UAA (+0,62 %)
Under Armour Inc:
Second-quarter earnings per share of $0.20 beat analyst estimates of $0.10. Revenue of $1.57 billion exceeded expectations of $1.42 billion.
$W (+0,75 %)
Wayfair Inc:
Missed analyst estimates of -$2.05 in the third quarter with earnings per share of -$2.11. Revenue of $2.8 billion below expectations of $2.82 billion.
$PTON (+0,65 %)
Peloton Interactive Inc:
Missed analyst estimates of -$0.64 with first-quarter earnings per share of -$1.20. Revenue of $616.5 million below expectations of $637.07 million.
$DDOG (+1,42 %)
Datadog Inc:
Third-quarter earnings per share of $0.23 beat analyst estimates of $0.16. Revenue of $437 million exceeded expectations of $415.07 million.
$MRNA (+0,5 %)
Moderna Inc:
Missed analyst estimates of $4.81 in the third quarter with earnings per share of $2.53. Revenue of $3.36 billion below expectations of $4.63 billion.
$CROX (-0,37 %)
Crocs Inc:
Missed analyst estimates of $2.62 in the third quarter with earnings per share of $2.50. Revenue of $985.1 million exceeded expectations of $942.52 million.
$IRM (-0,38 %)
Iron Mountain Inc:
Third-quarter earnings per share of $0.48 beat analyst estimates of $0.44. Sales of $1.29 billion below expectations of $1.31 billion.
$SBS (+6,38 %)
STRATEC:
Posts Q1-3 sales of €207.7 million (preliminary: €207.7 million), adjusted EBIT margin of 18.3% (preliminary: 18.3%), and net income (adjusted) of €29.5 million (PY: €40.6 million). Outlook confirmed.
$BOSS (+0,51 %)
HUGO BOSS:
Achieves Q3 sales of €933 million (PY: €755, analyst forecast: €903.4 million), EBIT of €92 million (PY: €85 million, forecast: €88.1 million) and net income of €58 million (PY: €53 million, forecast: €56.6 million). In the outlook for 2022, the company now expects sales of €3.5 to €3.6 billion (previous: €3.3 to €3.5 billion) and EBIT of €310 to €330 million (previous: €285 to €310 million).
$SGL (+1,55 %)
SGL CARBON:
Achieves Q1-3 sales of €853.9 million (previous year: €743.5 million), Ebitda (adjusted) of €136.1 million (previous year: €108.5 million) and net income after minorities of €70.6 million (previous year: €42.6 million). Forecast confirmed.
$PFV (+0,31 %)
Pfeiffer Vacuum:
Achieves Q1-3 order intake of €866.5 million (preliminary: €866.5 million), sales of €668.7 million (preliminary: €668.7 million), EBIT of €94 million (preliminary: €94 million) and net income of €66.6 million (PY: €52.1 million). October 17 forecast for revenue and Ebit margin confirmed.
$HNR1 (+0,17 %)
Hannover Re:
Achieves 3. Gross premiums written of €8.91 billion (PY: €7.15 billion, analyst forecast: €8.02 billion), combined ratio of 99.6% (PY: 101.5%, forecast: 99.6%), investment result of €400.3 million (PY: €491.1 million), an Ebit of €408.9 million (PY: €324.5 million, forecast: €399 million) and a net profit of €221.9 million (PY: €185.4 million, forecast: €311 million). In the outlook for 2022, the company sees net income in the lower range of €1.4 billion to €1.5 billion, profit target for 2022 remains achievable.
$UN01
Uniper:
Achieves 1st to 3rd. Quarter net result of -€40 billion (PY: -€4.8 billion), net loss includes €10 billion realized costs for replacement volumes; economic net debt at €10.91 billion (PY: €0.324 billion), net loss includes €31 billion expected losses and provisions; adjusted net loss of -€3.22 billion (preliminary: -€3.2 billion, prior year: +€0.487 billion), adjusted EBIT of -€4.75 billion (preliminary: -€4.8 billion, prior year: +€0.614 billion). Concrete earnings forecast currently impossible for the time being.
$O2D (-0,27 %)
Telefonica Germany:
Achieves Q3 sales of €2.085 billion (PY: €1.967 billion, analyst forecast: €2.030 billion), service sales of €1.47 billion (PY: €1.42 billion), adjusted OIBDA of €642 million (PY: €613 million, forecast: €640.5 million). In the outlook for 2022, sales and OIBDA are now expected to be in the "lower mid-single-digit percentage range" compared to the previous year (previously: in the "low mid-single-digit percentage range").
$BMW (+0,35 %)
BMW:
Reports Q3 sales of €37.18 billion (PY: €27.47 billion, analysts' forecast: €35.53 billion), EBIT of €3.68 billion (PY: €2.88 billion, forecast: €3.5 billion), EBT of €4.1 billion (PY: €3.42 billion) and net income of €3.18 billion (PY: €2.58 billion). Outlook confirmed.
$ZAL (+0,58 %)
Zalando:
Achieves Q3 revenues of €2.34 billion (PY: €2.28 billion), Ebit (adjusted) of €13.5 million (PY: €9.8 million) and net result of -€35.4 million (PY: -€8.4 million); number of active customers grows by 8% and exceeds 50 million for the first time. Outlook confirmed.
$COP (-0,18 %)
CompuGroup:
Posts Q1-3 revenue of €802 million (preliminary: €802 million), Ebitda of €166 million (preliminary: €166 million) and net income of €59.8 million (PY: 56.6 million). Outlook confirmed.
$RAA (+0,76 %)
RATIONAL:
Achieves Q3 sales of €274.2 million (PY: €207 million, analyst forecast: €270 million), Ebit of €70.3 million (PY: €49.7 million, forecast: €64.4 million), Ebit margin of 25.6% (PY: 24.0%) and net income of €53.8 million (PY: €37.8 million). Forecast confirmed.
$KCO (+1,56 %)
Klöckner & Co:
Achieves 3rd quarter sales of €2.37 billion (PY: €2.0 billion), Ebitda (adjusted) of €16 million (PY: €277 million) and net result of -€22 million (PY: +€185 million). Outlook confirmed.
#quartalszahlen
#boerse
#börse
#aktien
#paypal
#starbucks
#sandp500
#communityfeedback
#community


4Année·
𝑫𝒓𝒐𝒑𝒃𝒐𝒙
It's a lot of text, but only the most important.
Tried to leave out everything boring.
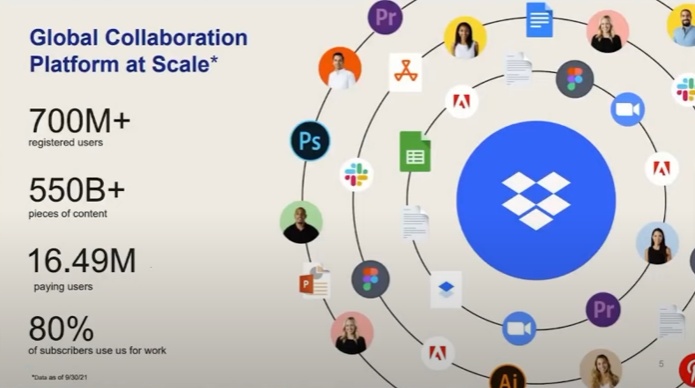
Dropbox was the first major cloud storage sharing provider for individuals, most should know the bumms. Have many collaborations across the market, see picture.
𝐊𝐨𝐧𝐤𝐮𝐫𝐫𝐞𝐧𝐳
Quite a few smaller players but all not so exciting, worry me immediately though: Google Drive and Microsoft OneDrive. Both companies have long-term goals in this area and attack exactly the business model of Dropbox, arebiten but at the same time with you.
Google Drive:
240 million users, documents can be edited and created directly over the web... so improvement over Dropbox.
Should also come for Linux (does anyone actually use it).
Google implies Drive as everything else on smartphones as an app, so for new customers it's already there and doesn't have to be downloaded first like Dropbox. Advantage Drive.
Companies that rely on this Google corporate program, "Google Apps for Work" get advantages that are worthwhile (30GB per employee, blah blah).
Microsoft One Drive:
Features like Google, comes with Office 365 or for companies for 4,20€ p.m. (ha, funny)
User numbers I didn't find but that it's included with the 365 package and that really everyone uses Lelek should be some.
In search of the numbers I slipped into so funny computer science forums that have all raved about the switch to One Drive, does not really speak for Dropbox.
So let's summarize: doesn't sound so cool for Dropbox for now, big companies with deep pockets have way too much buck.
𝐆𝐞𝐳𝐞𝐢𝐬𝐜𝐡𝐭𝐞 𝐙𝐚𝐡𝐥𝐞𝐧:
(Over 700 million users, nearly 17 million numbers of them).
13% increase in revenue to $550m, net profit was also quite fine, all minimally above analyst expectations.
Free cash flow from $491m in 2020 to $715m now.
In 2017 5% of users upgraded to premium, in 2020 it was 20%
We look at the chart and think whoops, not everyone was that happy with the numbers, although they weren't bad at all.
To save you a lot of unnecessary: the CEO sold shares 2 weeks before, there was too much red in the numbers (I'll get to that in a moment) but above all the shareholders also read my paragraph on the competition.
𝐈𝐧𝐡𝐚𝐥𝐭𝐥𝐢𝐜𝐡𝐞𝐫 𝐁𝐮𝐫𝐠𝐠𝐫𝐚𝐛𝐞𝐧?
I read some stuff but found it all a bit weak
Growth: nope, it's not a moat
Customer base remains: maybe, but from my informatics forums experience rather no.
𝐂𝐄𝐎: 𝐃𝐫𝐞𝐰 𝐇𝐨𝐮𝐬𝐭𝐨𝐧
Reminded me of Musk from the face,
Seems to know Mark that's why he helps out at Facebook, owns 25% of Dropbox. But has sold a mini-share, as well as all other insider purchases in the last half year.
𝐀𝐀𝐀𝐀𝐀𝐁𝐄𝐑:
There is a nice line in this pile of numbers that reads "Asset writedown". Dropbox noted during Corona that they could just do away with office buildings and send people home. (Additionally, they terminated a few by the way, gosh, my structure here is so awesome again).
So they were able to sublet offices, or had the idea to do so, and now comes the reason why studying business makes sense: They had to write off the differences between real and "fair" value of these buildings, big shit, whole idea in the ass like end result red, shareholders pissed.
And that's not exactly a small sum, 398 million USD (is only 155% of the 2020 net incomes 🤡).
If you take the shit out of it, the net income of the last two years was actually positive and would have increased significantly from 2020 to 2021.
Question that remains; that always remains: Is. That. Priced in?
No. A reasonable discount in the valuation is quite justified, but due to the risk of competition with Google, in a market comparison and before the prospect of rising interest rates, a price of 24 USD is already quite low. Therefore continue with ->
𝐁𝐞𝐰𝐞𝐫𝐭𝐮𝐧𝐠
Fun math fun with Moritz, episode 1:
If I assume 0.8 EPS for Dropbox based on past values (very conservative), and a growth rate of 16% per year (supposedly also conservative, but I think it's already decent for the competition) the intrinsic value of the stock according to the Graham formula is 32.40 USD.
Financial metric tells us EPS so 0.8 x (1+growth) x PE ratio (profit is not there only because of depreciation, without depreciation profit of approx. 280 Mio so PE ratio of 0.69 by current price). Price)
So = 0.8 x (1+ 0.16) x 34.39 = 31.91392 USD
Unbelievable but true, the result makes sense in terms of content, I don't believe it, probably I just made a mistake 2 times in the same place.
My fair price calculation (without including the much more expensive valued competition, I find comparison difficult here and with the only condition that the annual growth remains at 16%): 32 USD, exactly what we had 4 weeks ago. And that brings us to:
𝐂𝐡𝐚𝐫𝐭𝐭𝐞𝐜𝐡𝐧𝐢𝐤
We are currently running along the support at 23.73 USD, should this break we will go down to 21.70 and then possibly even below 18.
Next resistance is at about 26.25 USD if we get into a bullish movement, currently lurking. Neither buy nor should. Some son investor has bought something, but do not know the.
𝐙𝐮𝐬𝐚𝐭𝐳: 𝐈𝐧𝐟𝐥𝐚𝐭𝐢𝐨𝐧!
As we all have noticed expensive stocks are getting quite a bit of fear lately, I made it easy for myself now and always looked at the chart on Fridays, pretty much no movement on those days, so Dropbox is just smearing like that and not because of inflation. Yay✨
𝐅𝐚𝐳𝐢𝐭
Conservative potential of exactly 33%, but will continue to exist even if Google makes eye, only then we do not want to own the stock. Growth must remain, should it go down the drain, this speaks for even stronger competition and I am sure we will see the 15$.
Typical case of risk/potential, since my values in the calculations were conservative but TA grad does not necessarily point to buy, 33% is realistic. I'm in with a trade soon, but not long term, as the competition is pushing too hard.
[Update : https://www.tradingview.com/x/OmWtoh29/ ]
If you want to buy Dropbox because of this post be aware that you are trading random numbers from the internet, I don't recommend anything. The hook does not automatically verify everything I say, even if my comments are always at the top.
Sources
https://dropbox.gcs-web.com/financial-information/earnings-reports
https://www.youtube.com/watch?v=pEQ-AjEmmv c
https://www.fool.com/investing/how-to-invest/stocks/intrinsic-value/
https://www.onvista.de/aktien/DROPBOX-INC-Aktie-US26210C1045
https://www.macrotrends.net/stocks/charts/DBX/dropbox/pe-ratio
https://www.finanztrends.de/dropbox-aktie-uebertraf-die-geschaetzten-gewinne-um-571/
https://ycharts.com/companies/DBX/pe_ratio
https://www.itreseller.ch/Artikel/94982/Dropbox_mit_soliden_Quartalszahlen.html
https://www.gruender.de/software-tools/dropbox-alternativen/

2020
46 Commentaires
pffffff, who pays for Microsoft Office 365 is really quite lost. Use cloud services rather unconsciously, aka everything ends up in the Googlecloud. I heard that Apple has a limit when you have to pay, that's really cringe. 33% return is too little in my opinion with the risk, sry boss. But for all Teslajunkies: The CEO looks a bit like Elon Musk ordered on Wish, just look at it. Otherwise, his wife is quite pretty @SharkAce Your calculation is even really correct🤩I can hardly believe it and that, although you're no longer sober anyway (spiteful laughter unso) Hopefully it goes down another 10%🌚
•
22
•


Titres populaires
Meilleurs créateurs cette semaine
Données en temps réel par LSX · Données financières de FactSet