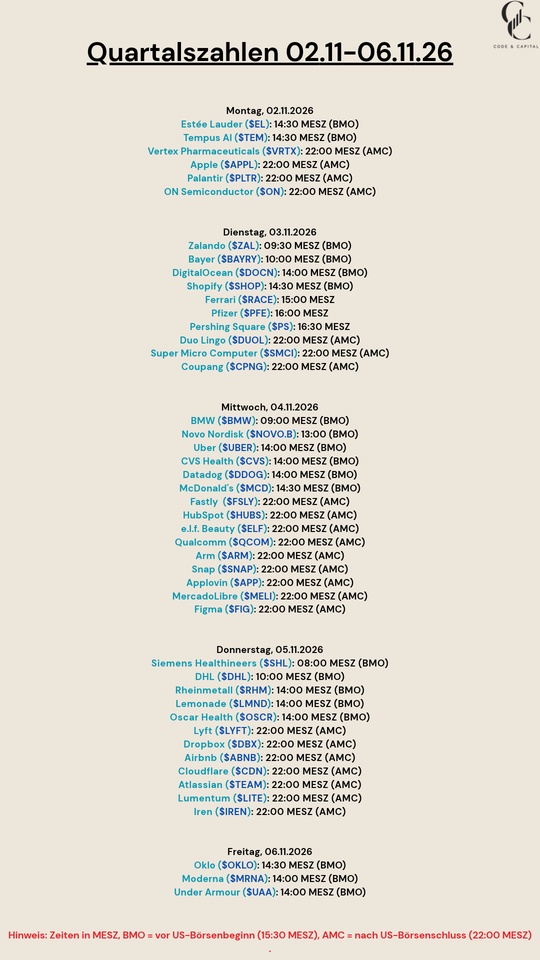

📊 𝐑𝐞𝐬𝐮𝐥𝐭𝐬
• GAAP EPS: $0.38 (Normalized Est. -$1.35, not directly comparable), vs. -$0.51 YoY.
• Revenue: $1.313B (Est. $890.22M) ✅, +29% YoY.
• Net Income: $162M (vs. -$200M YoY).
• U.S. Revenue: $780M.
• International Revenue: $533M.
• R&D Expenses: $583M, -27% YoY.
• Cost of Sales: $318M, +54% YoY.
• Cash & Investments: $8.0B.
⠀
🎯 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
• FY2026 Revenue Growth: +15%–25%, raised from up to +10%.
• FY2026 R&D Expenses: ~$2.7B, reduced from ~$2.9B.
• FY2026 SG&A Expenses: ~$1.0B, unchanged.
• FY2026 Capital Expenditures: ~$200M.
• FY2026 Year-End Cash & Investments: $8.1B–$8.3B, raised from $4.7B–$5.2B.
⠀
📌 𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
• Q3 revenue beat consensus by ~47.5%, driven primarily by stronger international COVID vaccine sales.
• Returned to GAAP profitability with $162M in net income, a $362M improvement YoY.
• Phase 3 intismeran + KEYTRUDA reduced melanoma recurrence or death risk by 42% versus KEYTRUDA alone.
• Distant metastasis or death risk declined 38% in the same Phase 3 trial.
• Received U.S. approval for mFLUSIVA influenza vaccine, its fifth approved product globally.
• Flu/COVID combination vaccine received approval in Canada following earlier EU authorization.
• Norovirus Phase 3 interim analysis failed to meet early-success criteria; no additional cohort planned this season.
• Reduced FY2026 R&D spending outlook by $200M amid continued cost discipline.
• Completed ~$3B convertible notes financing, generating ~$2.6B in net proceeds.
• Cash position increased to $8B, supported by debt financing despite a $950M litigation settlement payment and operating cash usage.
• Pivotal propionic acidemia trial data expected in 2026.
• Moderna Analyst Day scheduled for November 12.
⠀
💬 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐂𝐨𝐦𝐦𝐞𝐧𝐭𝐚𝐫𝐲
“We delivered 29% revenue growth in the third quarter, alongside the U.S. approval of mFLUSIVA, our fifth approved product globally, and positive Phase 3 results for intismeran in melanoma.”