
🛢️📈 Energy is up nearly 6% week-to-date through Thursday, the market's top-performing sector, with healthcare and financials also outperforming. BofA's Michael Hartnett warns rising debt and yields could still derail the rally.
SPDR State Street Health Care Select Sector SPDR ETF
ETP
ETP
Ticker: XLV
XLV
Price
Debate sobre XLV
Puestos
4
4Lun·
🐾 Zoetis (ZTS) - buying opportunity of the year or falling blade?
Hello everyone,
Today I would like to introduce you to a share that has completely disappeared from the radar of many investors - and that is precisely what makes it interesting: **$ZTS (+3,79 %) (NYSE: ZTS)**, the world's largest animal health company.
-----
What is Zoetis anyway?
For those who don't know the name: Zoetis was spun off from Pfizer in 2013 and is now the undisputed market leader for veterinary medicines worldwide. The portfolio includes vaccines, antiparasitics, dermatology products and diagnostics - both for pets (dogs, cats) and farm animals (cattle, pigs, poultry). Well-known products: **Simparica Trio** (tick protection), **Apoquel** and **Cytopoint** (allergy/dermatology), **Librela** (pain therapy for dogs).
-----
## Why is the price down?
The share price has more than halved in recent months - from ~172 USD to the current ~74 USD. This is not a small setback, this is a real price bloodbath. What has happened?
**Q1 2026 was a shock:**
- Sales +3% to USD 2.3 bn - but virtually zero organic growth
- Without a one-off effect of USD 100m in foreign business, organic sales would even have fallen by ~5%
- Adjusted EPS: USD 1.53 vs. expected USD 1.60 - missed expectations
- Adjusted operating margin: 33.5% - that is 6.4 percentage points less than in the previous year
- US pet business: **-11%** - the core of the problem
- CEO Kristin Peck lowered the annual targets: Sales now only USD 9.68-9.96 billion, EPS USD 6.85-7.00
In addition, there are legal disputes surrounding the painkiller **Librela** (safety concerns, plaintiffs accuse Zoetis of concealing risks) and competitive pressure from generics in key categories.
The market reacted brutally: **-21.5% in a single day on May 7, 2026**, -30% in the last month, -54% from 52-week high.
-----
## Why I still think this is a buying opportunity
And this is where it gets interesting. Because if you look at the fundamentals, the fall in the share price does not match the actual quality of the company.
**1. profit margin of 27.8%**
That shows: Zoetis is not a growth hype, but a genuine, highly profitable company. Even in a weak quarter.
**2. strong growth in international business**
While the US segment is weakening, the international business grew by **+17% to USD 1.1 billion** - driven by livestock products and antiparasitics. This shows that the business model is working and the problem is geographically limited.
**3rd EPS growth of ~13% expected**
Despite everything, analysts expect earnings per share of ~ USD 7.09 for 2026 - that is 13% more than in 2025. At a share price of USD 74, this results in a **CGV of around 10** - historically favorable for a quality stock in this class.
**4. RSI of 15 - extreme oversold territory**
Technically speaking, an RSI of 15 is exceptionally rare. This does not automatically mean a trend reversal, but it does signal that the selling pressure is approaching exhaustion. With solid fundamentals at the same time, this is a rare setup.
**5th analyst price target: USD 195**
The average price target of 22 analysts is USD 195 - compared to the current price of ~ USD 74. Even if the analysts are 50% too optimistic, there would still be considerable upside. Structurally, Zoetis is not an ailing company, but a market leader in a growth market (humanization of pets, increasing veterinary visits worldwide, growing middle class in emerging countries with farm animals).
**6th dividend remains**
Despite everything, the Board of Directors has confirmed a quarterly dividend of **0.53 USD per share** for Q3 2026. Management believes in the stability of the company.
-----
## The setup in short form
Current price: ~74 USD
52-week high: 172 USD
Price loss since high: -54%
RSI: ~15 (extremely oversold)
P/E ratio 2026e: ~10
Profit margin: 27.8%
EPS growth 2026e: +13%
Analyst price target Ø: USD 195
Dividend/quarter: USD 0.53
Dividend yield: ~2.6%
Dividend growth: increased 12 years in a row
## My assessment
Zoetis is not a turnaround case in the classic sense. The business model is intact, the moat (market leadership, customer loyalty among veterinarians, R&D pipeline) is in place. What is missing is short-term confidence - and that creates opportunities for patient investors.
If you are willing to bring a 12-18 month time horizon and bet on a normalization of the US pet business, you will get a global market leader at a fraction of its historical value.
-----
## ⚠️ An objection - which you should take seriously
I'll be honest: **This is not a risk-free bet.
The Q1 slump in the US pet business (-11%) is not a one-off effect - it reflects a structural shift. Pet owners are price sensitive, generics are eating into market share and competition in dermatology and parasitics is increasing. Added to this is the Librela lawsuit, the outcome of which is uncertain. Argus has just downgraded the share from "buy" to "hold" - these are not bullish signals from Wall Street.
The crucial question that Q2/Q3 must answer: Is the US pet business cyclically weak (i.e. recovery possible) - or is an era of high premium margins permanently breaking away? Until this is answered, there remains a certain risk that the share price will continue to move sideways despite the RSI 15 or test it again.
What do you think?
88
11 Comentarios
Marcel@Elrada
4Lun
•
77
•
1Año·
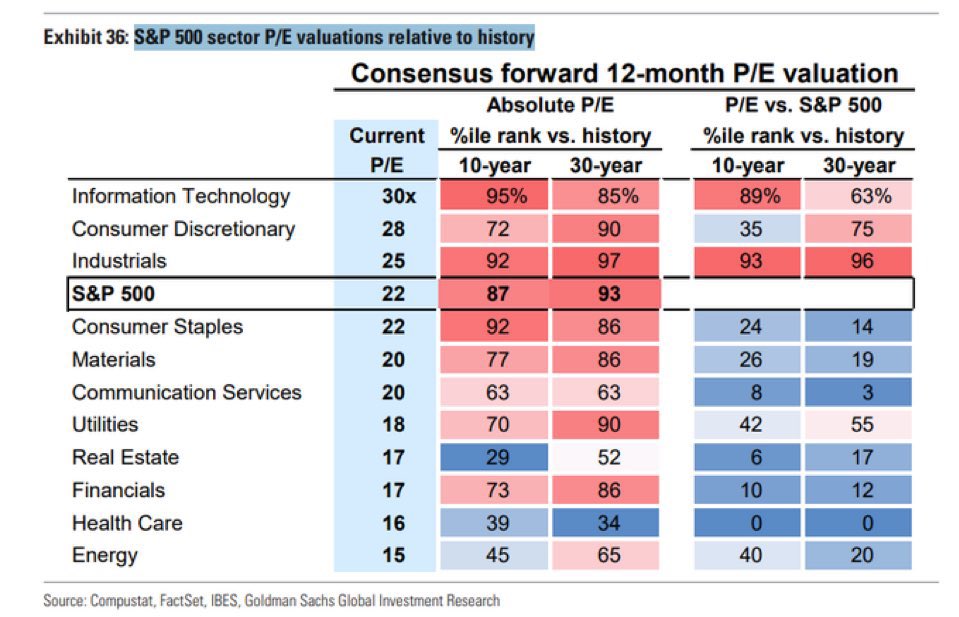
Valuation Healthcare sector - Goldman Sachs
$XDWH (+1,73 %)
$XLV (+1,53 %)
$CSPX (-1,01 %)
$VUSA (-1,02 %)
$UNH (+2,16 %)
$OSCR (-0,84 %)
According to Goldman Sachs, healthcare is the only sector in the S& P 500 that is cheaper than the 10- and 30-year averages.
This is an extremely attractive risk/reward ratio and the coming months will be exciting.
$ELV (+2,32 %)
$CNC (+2,03 %)
$DHR (-1,8 %)
$SRT (+4,57 %)
$LLY (+2,97 %)
$NOVO B (+1 %)
$NVO (+1,15 %)
$ISRG (+3,5 %)
$JNJ (+3,79 %)
$ABBV (+0,44 %)
$PFE (+1,88 %)
$SAN (+2,1 %)
$MRK (-1,26 %)
$BMY (+3,29 %)
$TMO (-2,87 %)
1Año·
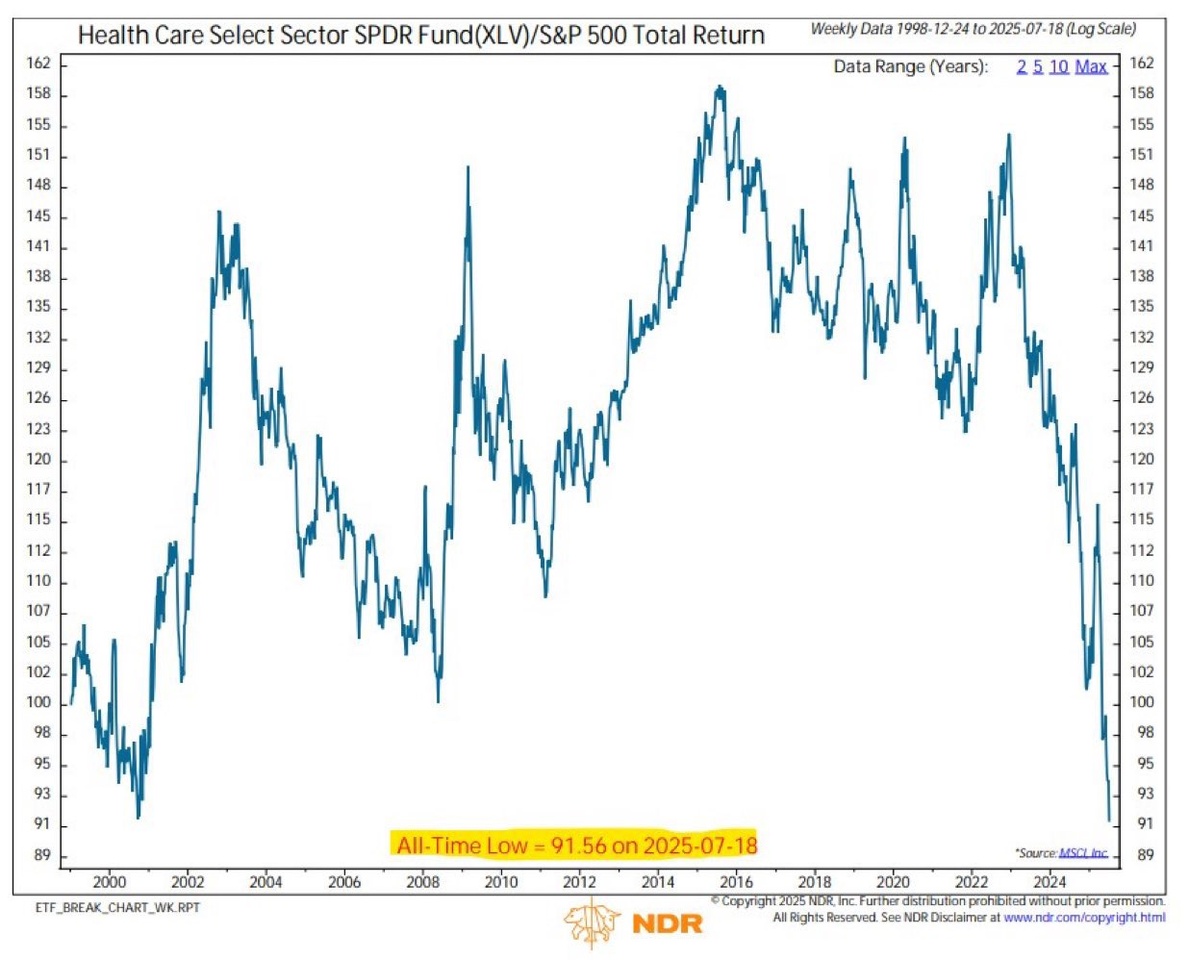
Weak US healthcare sector
$UNH (+2,16 %)
$OSCR (-0,84 %)
$XDWH (+1,73 %)
$ELV (+2,32 %)
$LLY (+2,97 %)
$XLV (+1,53 %)
The US healthcare sector is experiencing its biggest crash in the last 20 years.
If the strong weighting no. 1 $LLY (+2,97 %) (over 12%), one would have to go back even further/longer. (probably before the existence of the ETF).
I have positioned myself strongly here as I believe this is a great opportunity.
I also believe that a lot of capital will flow into the sector in the coming months. ✌️
Do you have a similar view? ✌️
99
6 Comentarios

I still have one US pharma share on my buy list.
But I'm wondering whether I should get in before August.
But I'm wondering whether I should get in before August.
•
22
•1Año·
Weak US healthcare sector
$UNH (+2,16 %)
$OSCR (-0,84 %)
$XDWH (+1,73 %)
$ELV (+2,32 %)
$LLY (+2,97 %)
$XLV (+1,53 %)
The US healthcare sector is experiencing its biggest crash in the last 20 years.
If the strong weighting no. 1 $LLY (+2,97 %) (over 12%), one would have to go back even further/longer. (probably before the existence of the ETF).
I have positioned myself strongly here as I believe this is a great opportunity.
I also believe that a lot of capital will flow into the sector in the coming months. ✌️
Do you have a similar view? ✌️
1616
17 ComentariosI think it will remain exciting for health insurers because I see a problem in keeping margins at the same level.
I see the medical device manufacturer sector as very exciting due to AI and robotics. Companies such as $SYK Stryker and $GMED etc. could be interesting here.
Humanoid care robots can already be seen in some nursing homes.
But the biotech sector is also being shaken up by AI.
Here I continue to bet on $CORT and $VRTX on the buy list is $EXEL
•
22
•