So from now on, I'll be keeping an eye on things too. KO had been sitting around for a while and was bought today.
To balance out the portfolio, I also $SIE (+2,7 %) and set up DCA on $SU (+2,44 %) . Not that it’s getting too speculative.
Puestos
18So from now on, I'll be keeping an eye on things too. KO had been sitting around for a while and was bought today.
To balance out the portfolio, I also $SIE (+2,7 %) and set up DCA on $SU (+2,44 %) . Not that it’s getting too speculative.


Unfortunately, the play money was lost due to $IINN and $BIOA (+2,17 %) is slowly running out. @Raketentoni But I'm not going to pass up these items for that price.

Part 3: The Five Categories in Practice
What This Part Is About
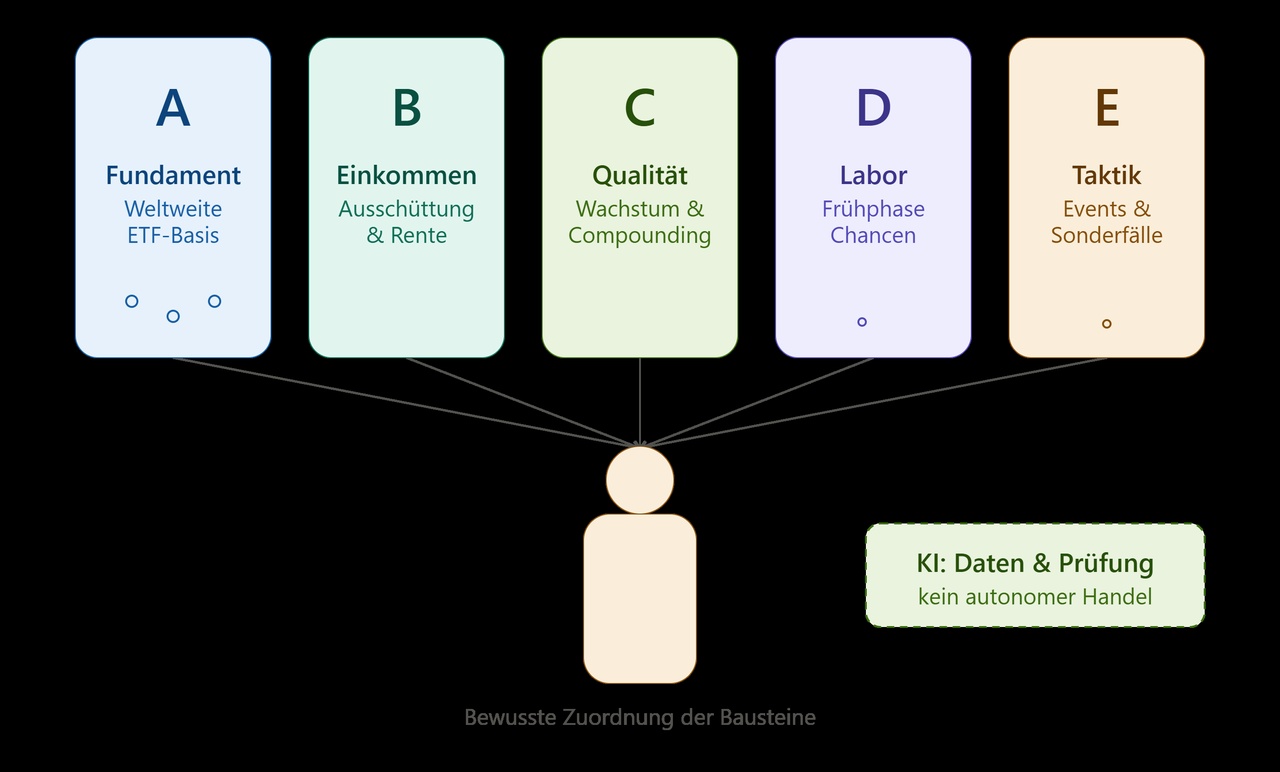
In Part 1, I described the origins of the 55555 system. Part 2 showed how an initial stock idea is transformed into a well-reasoned decision through research, cross-checking, and comparison. Now we’ll look at the practical side: What is the purpose of the five categories, A through E; which stocks are currently included in them; and why do they fit exactly where they are?
The categories are not a ranking from safe to risky. Each serves a different function.
A forms the broad foundation. B is intended to provide ongoing cash flow. C seeks quality growth. D allows for limited asymmetric opportunities. E is intended for tactical situations, events, and special cases. Therefore, what matters is not only whether a company is interesting, but what role it is meant to fulfill within the overall system.
The following chart shows the current confirmed portfolio following the addition of AeroVironment. It deliberately does not include share counts, portfolio values, absolute position sizes, purchase volumes, or absolute gains and losses. The goal is to make the system transparent without disclosing personal financial data.
Grab a cup of coffee or a snack, because the estimated reading time this time is 14 minutes :)
Category A: The Broadly Diversified Foundation
Category A consists of 5 ETFs.
This tier is not intended to identify the most exciting individual stocks, but rather to stabilize the portfolio, provide broad coverage of regions and companies, and reduce dependence on individual investment theses.
Therefore, there is no mechanical price limit for Category A.
The key factors are index quality, costs, diversification, liquidity, and whether the building blocks complement each other effectively.
Categories A and B are the long-term cash flow building blocks for future retirement income enhancement. For this reason, frequent buying and selling is expressly not intended here:
A replacement requires a clear deviation from the objective or a significantly better alternative that is convincing in terms of costs and risks.
Currently, Category A is fully allocated with five building blocks:
VanEck Developed Markets Dividend Leaders $TDIV (-0,15 %)
- Dividend component for developed markets
Dividend and region (as of September 16, 2026): approximately 3.0 percent dividend yield, paid quarterly. Rough regional breakdown: Europe 56 percent, North America 16 percent, Asia-Pacific and other markets 28 percent.
Why include it in your portfolio: The ETF brings together established companies with a strong focus on dividends, thereby complementing the portfolio’s foundation with a clear emphasis on income.
Expectations: In the long term, it is expected to deliver robust distributions and broader diversification across developed markets.
Key risk: A focus on dividends may temporarily result in significant overweighting of certain sectors and value stocks; high dividends are no substitute for corporate quality.
L&G Global Quality Dividends $LDGL (+0,5 %)
- global quality and dividend component
Dividend yield and region (as of September 16, 2026): Approximately 4.3 percent annualized based on the most recent monthly payment; the fund is still young and does not yet have a full 12-month history. Distributions are made monthly. Rough regional breakdown: North America 35 percent, Europe 29 percent, Asia-Pacific 34 percent, other markets 2 percent.
Why include it in your portfolio: This ETF combines international diversification with quality and distribution characteristics. It is intended to prevent the dividend portion of the portfolio from consisting solely of traditional high-dividend stocks.
Expectations: It is intended to provide exposure to global corporate quality while also delivering regular distributions.
Key risk: Factor strategies can lag behind the broader market for extended periods and, despite their global focus, may develop regional or sector-specific biases.
WisdomTree Europe SmallCap Dividend
$DFE (+0,99 %)
- European small-cap stocks
Dividend and Region (as of September 16, 2026): Approximately 3.7 percent dividend yield, paid quarterly. The equity allocation is almost entirely in Europe; the largest countries are the United Kingdom, Sweden, and Norway.
Why include it in your portfolio: This component adds smaller European companies to the portfolio that have little weight in major global indices. At the same time, the dividend component is maintained.
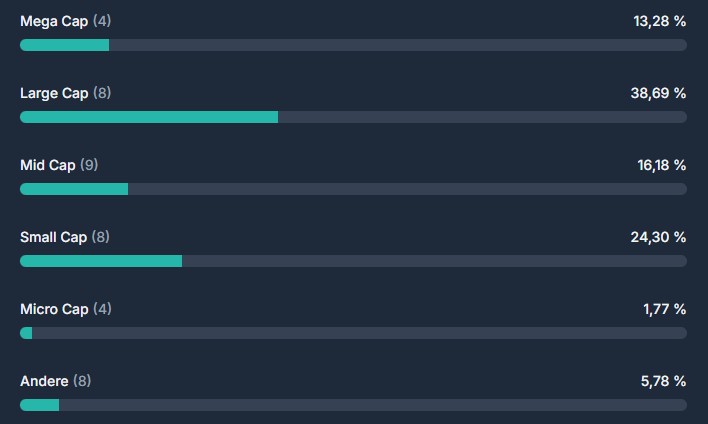
Expectation: It is intended to tap into additional sources of returns beyond global megacaps over the long term.
Key risk: Small-cap stocks are more sensitive to economic conditions, financing costs, and lower liquidity; Europe may also experience prolonged periods of relative weakness.
Fidelity Emerging Markets Quality Income
$FYEQ (+1,1 %)
- Emerging markets with a quality filter
Dividend and region (as of September 16, 2026): 2.6 percent dividend yield, paid quarterly. Rough regional breakdown: Asia 81 percent, Europe 3 percent, Middle East and Africa 8 percent, Latin America 3 percent, other markets 5 percent.
Why include it in your portfolio: The ETF incorporates emerging markets into the portfolio without relying exclusively on the largest index holdings. Quality and dividends are intended to mitigate some of the typical risks associated with emerging markets.
Expectations: It aims to combine growth from emerging markets with a more disciplined approach to quality and income.
Key risk: Currencies, politics, regulation, and geopolitical tensions can significantly impact corporate earnings and returns as measured in Europe.
iShares MSCI ACWI
$ISAC (+0,82 %)
- Cornerstone of the portfolio and thus the broad global core
Dividend Policy and Regional Breakdown (as of September 16, 2026): Reinvesting dividends, so no ongoing cash distributions; returns are reinvested in the ETF. Rough regional breakdown: North America 66 percent, Europe 12 percent, Asia-Pacific 16 percent, Latin America, the Middle East, Africa, and other markets 6 percent.
Why it’s in the portfolio: It covers developed and emerging markets within a very broad global equity strategy. It is the simplest and most diversified component of the system.
Expectation: It is intended to drive long-term global wealth accumulation, regardless of which individual investments are currently the focus in the rest of the portfolio.
Key risk: Even a global index does not protect against general stock market losses and is often heavily influenced by large U.S. technology companies.
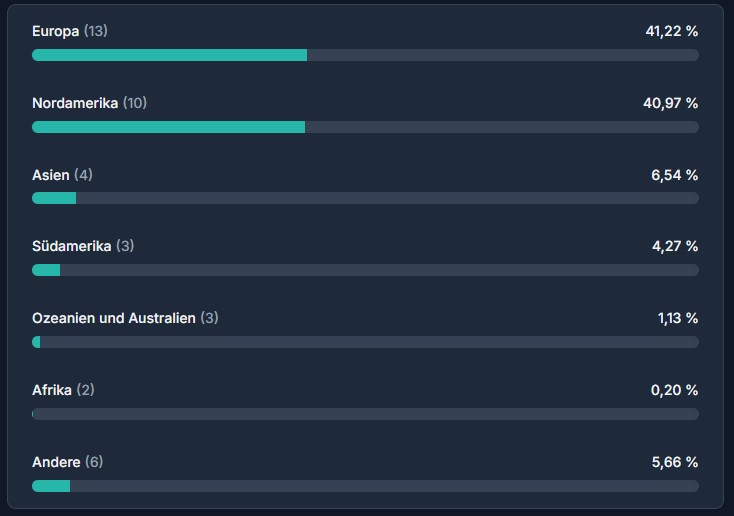
Overall portfolio regions:
Category B: Cash Cows and Regular Dividends
Category B is intended to generate reliable cash flow.
A high percentage alone is not sufficient for this. Before making a new purchase, we review dividend coverage, the balance sheet, debt, the business model, capital allocation, and concentration risks. For new Category B positions, a minimum yield of six percent generally applies. Mechanical price stops are not a priority here; we sell if the dividend or fundamental thesis breaks down or if a clearly better alternative emerges.
Like Category A, Category B is geared toward long-term holding and subsequent recurring income. Price movements alone therefore do not trigger a change in position; dividend coverage, balance sheet, business model, and sustainable cash generation remain the decisive factors.
Currently, this category has a dividend yield of approximately 9% excluding any special dividends!
Cibus Nordic Real Estate
$CIBUS (-2,19 %)
- Monthly real estate cash flow
Dividend (as of September 16, 2026): approximately 7.1 percent annualized, paid monthly.
Why it’s in the portfolio: Cibus focuses heavily on food and other everyday necessities. The monthly distribution and largely indexed rents align with the cash flow objectives of this category.
Expectation: The position is intended to provide predictable distributions from a defensive real estate portfolio.
Key risk: Debt levels and refinancing needs remain high. Rising interest rates, weaker like-for-like revenue, or overly aggressive growth through acquisitions would weigh on the investment thesis.
Hercules Capital $HTGC (+1,37 %)
- Specialized financier for growth companies
Dividend (as of September 16, 2026): Approximately 10.8 percent based on current regular and supplemental distributions, paid quarterly. Supplemental distributions are not guaranteed.
Why include it in your portfolio: Hercules primarily extends loans to technology- and life sciences-oriented companies. Many loans have variable interest rates, which means returns can initially benefit from higher interest rates.
Expectation: The goal is to achieve an above-average current distribution from a specialized loan portfolio.
Key risk: Loan defaults, a weak venture capital environment, falling interest rates, or a deterioration in distribution coverage could put pressure on cash flow.
Vår Energi $VAR (+0,06 %)
- Energy cash flow
Dividend (as of September 16, 2026): approximately 10.0 percent annualized based on the most recent quarterly payment, paid quarterly. The amount remains dependent on the commodity cycle and free cash flow.
Why include it in your portfolio: Vår Energi adds a commodities-related cash flow component to the portfolio. Production, the project pipeline, and distributions offer a different source of returns than real estate or the lending business.
Outlook: The position is expected to benefit from efficient oil and gas production as well as a shareholder-friendly dividend policy.
Key risk: Oil and gas prices, project delays, cost overruns, and political intervention make the dividend more cyclical than that of a traditional defensive dividend stock.
Capital Southwest $CSWC (-0,05 %)
- SME financing
Dividend (as of September 16, 2026): approximately 10.8 percent based on the most recently reported annual payments. The regular dividend is paid monthly; supplemental dividends may be paid quarterly.
Why include it in your portfolio: Capital Southwest is another BDC component, but with its own loan portfolio and a different corporate structure. This position complements Hercules and spreads the credit risk across a second manager.
Outlook: We expect recurring income from U.S. small and medium-sized businesses and disciplined distributions from net interest income.
Key Risk: The biggest risks are credit quality, recession, falling interest margins, dilution, and a distribution that grows faster than sustainably earned income.
Chesnara
$CSN (-1,6 %)
- Insurance and run-off cash flow
Dividend (as of September 16, 2026): approximately 6.5 percent based on the most recent known 12-month payments, paid semiannually.
Why it’s in the portfolio: Chesnara manages life insurance portfolios and acquires additional portfolios. This results in a cash flow profile that differs significantly from real estate, energy, and BDCs.
Outlook: The position is expected to deliver stable long-term distributions from existing insurance portfolios and disciplined capital allocation.
Key risk: Capital requirements, market fluctuations, the quality of acquisitions, and weaker cash generation could limit dividends and growth.
Category C: Quality Growth and Long-Term Compounding
Category C is intended for companies that can grow revenue, earnings, and free cash flow over many years. Quality and growth are considered separately from the initial entry point. A company can reach the “Champions League” and still be too expensive or technically unfavorable at first.
For active C positions, a 20-percent trailing rule generally applies, whereby actual broker orders and theoretical benchmarks must remain clearly separate.
An open position does not create an obligation to buy.
Nu Holdings $NU (+4,22 %)
- digital financial platform in Latin America
Why it’s in the portfolio: Nu combines strong customer growth, a scalable digital platform, and the ability to offer more financial products per customer. The stock also brings regional diversification to the C-segment.
Outlook: In the long term, Nu is expected to profitably monetize its large customer base in Brazil, Mexico, the U.S., and other markets.
Key risk: Credit quality, regulation, currencies, competition, and an overly high valuation could undermine the growth thesis.
Schneider Electric
$SU (+2,44 %)
- Electrification, energy efficiency, and automation
Why it’s in the portfolio: Schneider is a high-quality company positioned to benefit from several structural growth themes: rising electricity demand, data centers, automation, grids, and more efficient energy management. The stock was added following a direct comparison with several industrial and energy infrastructure candidates.
Outlook: The position is expected to benefit in the long term from the expansion of electrical infrastructure and the integration of hardware, software, and services.
Key risk: Valuation, economic conditions, integration and execution risks, as well as a significant slowdown in data center or industrial investments, are the main concerns.
Hacksaw $HACK (-0,24 %)
- Growth in digital gaming and platforms
Why include it in the portfolio: Hacksaw represents a scalable, content-driven business model in the regulated online gaming sector. New games and additional markets can contribute disproportionately to earnings with relatively little capital tied up.
Outlook: The goal is long-term growth through new content, distribution, and international expansion.
Key risk: Regulatory changes, dependence on platform partners, shifting gaming trends, and a high valuation could quickly lead to a repricing of growth.
Vincorion $V1NC (-0,91 %)
- Specialized energy and defense systems
Why include it in the portfolio: Vincorion complements C with a smaller German specialist that has long-term demand for robust energy and system solutions for safety-critical applications.
Outlook: The position is expected to benefit from increased defense and infrastructure investments as well as improved operational execution.
Key risk: Order delays, project and margin risks, low market liquidity, and customer concentration make the stock more vulnerable than that of a large industrial conglomerate.
RELX
$REL (+2,94 %)
- Data-driven information and analytics services
Why include it in your portfolio: RELX has recurring revenue, strong data assets, and deep integration into professional workflows. Its business model is less cyclical than that of traditional industrial companies.
Outlook: The position is expected to grow over the long term through pricing, data, software, and continuous product improvement.
Key risk: An overly high valuation, regulatory issues, technological disruptions, and new AI-based competitors could limit growth and margins.
For Category C, the following applies: A C-rated position may not be downgraded to D.
If the C thesis deteriorates permanently, the position is replaced or sold within the C category.
D is not a catch-all category for damaged quality or growth theses.
A D company, on the other hand, may be upgraded to C if it demonstrably reduces its uncertainties and, in a direct comparison, better aligns with the quality and growth objectives of Category C.
It must , however, like any other security, be at least 10% to 15% better in valuation than the existing holding.
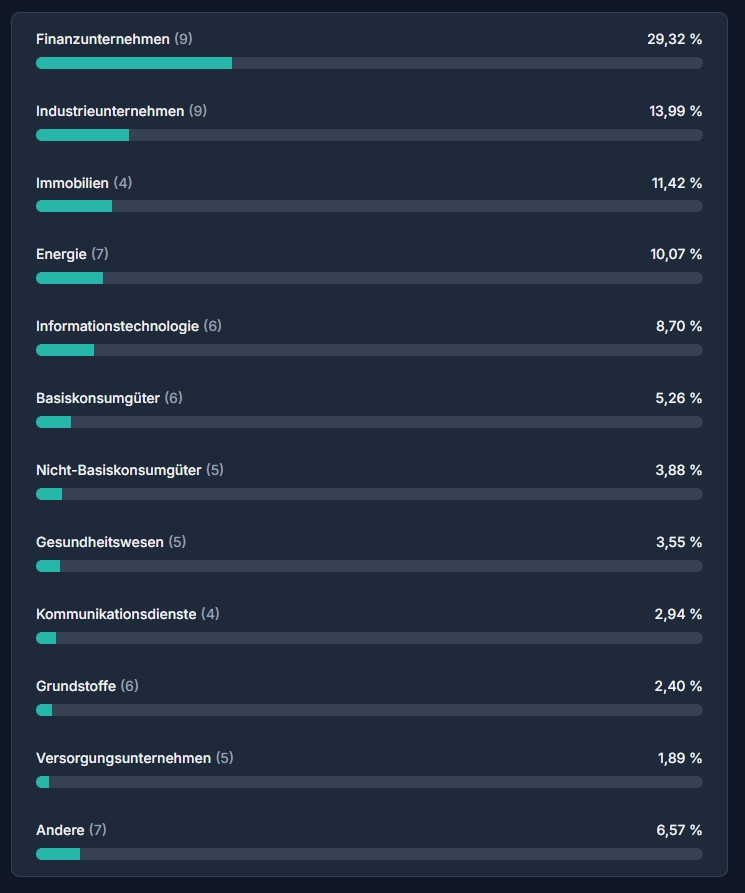
Sector Overview of the Portfolio:
Category D: Limited Asymmetric Opportunities
Category D deliberately accepts a higher degree of uncertainty. Here, we look for situations in which a successful milestone can significantly alter the company’s value, while the position size and exit strategy limit potential losses.
We evaluate the product and technology, financing, cash runway, dilution, customer or pipeline concentration, catalysts, and technical setup.
An open position does not create an obligation to buy.
NeoVolta $NEOV (+0 %)
- small provider of energy storage systems
Why it’s in the portfolio: NeoVolta offers access to the growing market for residential and small-scale commercial energy storage. The investment case hinges on scaling, sales, and broader market acceptance.
Outlook: If growth is successful, the company could benefit from decentralized power supply, resilience, and increasing solar adoption.
Key risk: Financing, dilution, competition, the company’s small size, and its dependence on strong revenue growth make this a highly speculative position.
Kymera Therapeutics $KYMR
- Targeted Protein Degradation
Why include it in the portfolio: Kymera develops drugs designed to specifically degrade disease-relevant proteins. Successful clinical data could significantly boost the value of several programs and the entire technology platform.
Expectations: The position targets the asymmetric value of clinical progress and potential partnerships.
Key Risk: Clinical failures, side effects, binary data events, high capital requirements, and potential dilution are core risks rather than temporary side effects.
IQM Quantum Computers
$IQMX (+2,54 %)
- European quantum computing technology
Why include it in the portfolio: IQM offers direct access to a strategically important future market and has operational systems, orders, and technology partnerships. At the same time, the market is still in its early stages and difficult to evaluate.
Outlook: The position is expected to benefit from growing demand for European quantum infrastructure and technological advances.
Key risk: Long development times, high financing costs, technological competition, and further capital requirements could significantly dilute the company’s value. The risk and stop-loss strategy will therefore be reviewed again.
AeroVironment
$AVAV (+0,06 %)
- Drones, counter-UAS, and defense technology
Why it’s in the portfolio: AeroVironment was added following a renewed fundamental and technical review. The investment case combines a strong order backlog with growing demand for unmanned systems, defense solutions, and directed-energy applications.
Outlook: The position is expected to benefit from the transition of key programs to larger-scale production runs and from the structurally rising demand for drones and defense systems.
Key risk: Order timing, government budgets, project integration, valuation, and sharp price fluctuations could lead to significant setbacks despite strong demand.
As of today, the fifth spot in the D category is still open.
Currently, the main contenders are NeurAxis $NRXS , Praxis Precision Medicines, and Rocket Lab $RKLB (-0,65 %) are being closely monitored.
NeurAxis has become significantly more attractive following technical improvements, but remains a speculative candidate due to losses, capital requirements, and potential dilution. The spot will only be awarded if quality, financing, catalysts, chart performance, and portfolio value collectively prove compelling.
Category E: Tactical Situations and Special Cases
This category is intended for swings, events, free rides, and clearly documented special cases. E is not a dumping ground for poor positions, nor is it a way to circumvent rules from categories B, C, or D. Before making a tactical purchase, the setup, trigger, risk, target, and exit strategy must be clearly defined. This category may remain empty if no compelling opportunity is available.
Desert Control $DSRT (+0 %)
- Special Case and Grandfathering
Why it’s in the portfolio: Desert Control is developing technology to improve sandy and dry soils. The position dates back to an earlier phase of the portfolio and is not currently treated as a standard new purchase under the current D rules.
Expectation: The remaining position keeps open the possibility that pilot projects, partnerships, or commercial applications will validate the technology.
Key Risk: Early commercialization, financing, dilution, low predictability, and very high volatility make this investment unsuitable as a core position. It therefore remains explicitly a documented special case.
Teekay Tankers $TNK (-0,11 %)
– Momentum Position
Why it’s in the portfolio: We have included Teekay Tankers as a tactical momentum/event position in Category E. The company is currently benefiting from high tanker rates, strong demand for oil transportation, and longer shipping routes due to geopolitical tensions. Added to this are a very solid balance sheet, high free cash flows, and a favorable valuation.
Expectations: Capitalizing on the momentum. For this reason, we do not treat Teekay as a long-term dividend or quality position, but rather as an E-position to be actively monitored with a clear exit strategy.
Key Risk: Despite these strengths, the business is highly cyclical: falling freight rates or an easing of the geopolitical situation could quickly bring earnings back to normal levels.
In addition, for the two open spots in the E portfolio, we are currently reviewing, among other things, selected “fallen angel” stocks, as well as potential rebound or event-driven setups.
Dorian LPG $LPG (-0,96 %) and International Seaways $INSW (-1,33 %) are examples of strong but highly cyclical momentum plays. DSV $DSV (+3,03 %) would be more of a rebound or earnings event than an immediate C-buy.
Such ideas do not automatically become positions; the current chart and a predefined exit strategy are key factors.
Why the categories don’t have to be the same size
The 55555 system means five possible slots per category, not five identical positions and no rigid equal weighting.
A category may remain incomplete.
Capital is not automatically allocated to the next available slot.
First come rule violations and risk control, then vacant slots, the best candidates, and only then possible replacements or additional purchases.
Nor is a replacement made simply because a new name seems more modern or stronger in the short term. A candidate must demonstrably outperform the existing position and improve the overall portfolio by approximately ten to fifteen percent, or replace a clear rule violation. As a result, the category structure does not become an automated trading system, but rather a framework for disciplined decision-making.
The rulebook clearly states that no single sector may account for more than 30% of the portfolio!
This limit includes ETFs as well. So it can happen that a truly good stock can no longer be purchased—due to the sector cap—to avoid creating concentration risk.
What Has Changed Since the Start
The basic idea behind the five tasks has remained the same, but the practical implementation has become more precise. Category E is now active. Balance sheet, debt, and concentration are mandatory review criteria. Champions League, Reserve, Watchlist, and Top 3 Alternates distinguish quality from current buyability.
The Masterbook and Master Status ensure that new decisions, sales, and exceptions do not get lost in old chats and works.
It was particularly important to realize that a system does not improve simply by mechanically applying every rule.
A stop, a score, or an open slot is only part of the decision.
Data quality, company context, portfolio utility, and human judgment remain indispensable.
Preview of Part 4
The fourth and final part focuses on control and further development:
How Masterbook, Master Status, daily closing, lists, transaction history, dividend log, and catalyst calendar work together. I’ll also show how errors, conflicting data, and new information are handled and where the limits of an AI-powered system lie.
Part 3, too, describes exclusively my personal development and decision-making process. It is neither investment advice nor a solicitation to buy or sell securities.
I look forward to questions, suggestions, and constructive criticism. I find it particularly fascinating to see what roles other investors assign to the components of their portfolios and how they distinguish between long-term quality, ongoing cash flow, and limited speculative opportunities.
+ 2

Norwegian Company Turns Desert Into Farmland.
Future food production will surpass the total of the past 500 years in just 3–4 decades. A Norwegian innovation is transforming deserts into farmland, which is currently thriving in parks in the U.S. and the Middle East and will soon be part of the UN World Food Programme.
— Nearly 2,000 soccer fields disappear every hour. Twelve million hectares of farmland are turning into desert at a rate of 210 kilometers per hour. That’s equivalent to the distance between Stavanger and Kristiansand, says Tor Mæhlum Karlsen, Chief Technology Officer at Desert Control.
He explains that the top layer of soil—the one we walk and stand on, the one where we grow grain—is getting thinner and thinner. It’s disappearing from below.
“Out of sight, out of mind,” says Karlsen.
But this can’t go on. The world’s population is growing, and we need more food. To produce more food, we need more water. Seventy percent of water consumption is accounted for by agriculture, and according to Desert Control, this share is rising.
The Garage Lab
The solution exists. It is liquid clay, known as LNC (Liquid Natural Clay), produced by the Norwegian company Desert Control. After a phase of developing and digitizing the product and the process, the technology is now ready for scaling.
The idea for LNC was conceived in the mid-2000s and developed in a garage in Stavanger by Kristian P. Olesen and his son Ole Morten Olesen, who still work for the company. In 2019, the two brought in an outside executive and raised the initial capital to build a prototype.
Since then, the company has been steadily moving closer to its goal.
The special clay produced by Desert Control works by being added to the topsoil, transforming desert sand into farmland. It can also be added to already cultivated land, reducing the need for irrigation.
This has now been tested on various soil types under different conditions.
“We’ve conducted many pilot projects. It seemed too good to be true, so we needed academic validation,” says Karlsen.
The pilot projects were successful. Both the clay mixture and the mobile units used to produce clay on-site, as well as the distribution of LNC over large areas, were thoroughly tested, and Desert Control is now ready to expand its business.
To succeed in this, more than just advanced laboratory work is required; high-tech solutions are also necessary.
“Alongside all the practical work being done, a lot is happening digitally. We’re collecting data from various sensors in the ground as well as from the production units that manufacture LNC,” he explains further.
The data is used to monitor the effects of the floating clay and to control LNC production at the local production units.
— “With Siemens systems, we can process the data we collect,” adds CTO Karlsen.
Scaling Up with Technology
The clay formula was developed in a laboratory in Sandnes. It is produced and shipped in one-metric-ton bags to the areas where the clay is added to the soil. There are mobile production units that mix dry clay with water before it is distributed.
This entire process has been tested time and time again. The warehouse, the production units, and the distribution of clay over large areas are now at the level required for scaling up. We and Desert Control are in the process of doing just that.
We provide data collection and automation solutions for the company that won the special award for Norway’s smartest industrial company in 2022.
— For Desert Control to become a data-driven organization, it is crucial that data and automation systems are closely integrated. That’s where we at Siemens come in, says Ståle Våga.
He is the account manager for Desert Control at Siemens and was involved in providing the technology that enables Desert Control to use IT-based tools and work processes, develop its own software, and benefit from Siemens’ extensive product and software portfolio.
In the future, it will be possible to use technology to control production anywhere in the world from the office in Norway.
“With a single keystroke, you can commission new equipment or send updates to multiple production units simultaneously,” says Våga.
The goal is to be able to control most of the process in this way, with just one operator on site. The operator does not need to have any special knowledge of machines, data, or programming, but must be able to operate the machine.
— The operator brings a tablet and receives instructions for the various steps via a user-friendly interface. The machine then carries out the tasks sent from the office in Norway, he explains further.
It’s been four years since the collaboration began, and Våga finds it exciting and meaningful to be part of something that has the potential to save the world.
— It’s always nice to come here. You can see that they’re making progress; everyone believes in the project, he says as he enters the courtyard between Desert Control’s offices in the FOMO office community in Sandnes and the lab.
Save the World
In the lab, four people are deeply focused. All around them are tubes and bottles filled with sand, soil, and green plants.
— It’s a far cry from the garage where it all began, says Karlsen, greeting Rosalia Garcia Teijeiro, the company’s head of research and development.
Teijeiro gives a tour of the lab and explains how the researchers here are currently studying how plants absorb nutrients with the help of LNC.
— With LNC, the nutrients stay in the soil longer, giving the roots more time to absorb them. That makes the plants stronger.
She is also in the process of setting up a lab in the U.S., where much of the work takes place. The company also has many clients and projects in the Middle East. They use LNC to keep parks, resorts, and golf courses green, but the real reward for their efforts is coming soon.
The product is being used in the Iraqi desert by the United Nations World Food Programme.
The UN organization is working to combat hunger and improve global food security, and there is no doubt that this is also Desert Control’s vision: to save the world. But it must be funded, and development is made possible by selling the product to those who can afford it and who, without LNC, would consume even greater amounts of water.
Freshwater is a limited resource, Karlsen reminds us, adding that the Earth has a finite amount of stable freshwater resources. To ensure they last, we cannot use more than is available.
But that’s exactly what we’re doing right now.
— How is that possible, you’re probably wondering? It’s because we’re living on credit!
This is a huge problem that Karlsen and his colleagues want to solve.
We’re pumping more groundwater than is being replenished. We’re doing this, among other things, to feed the growing global population.
— Over the next 30 to 40 years, we’ll have to grow more food than we have in the last 500 years.
Source:
https://www.siemens.com/de-de/company/insights/desert-control-software-defined-automation/

Anyone who exercised their subscription rights should see their new shares in their brokerage account today. $DSRT (+0 %)
A brief note on the semi-annual report:
Desert Control made significant operational progress in the first half of 2026. The company has completed 42 pilot projects at large agricultural operations and golf courses so far, compared to just seven in all of the previous year. In two trials with romaine lettuce, yield increases of more than 30 percent were achieved. In addition, a new, more efficient production facility was successfully commissioned.
Financially, however, Desert Control remains highly speculative. In the first half of the year, the company reported an EBITDA loss of 35.1 million NOK, while its cash balance stood at 18 million NOK at the end of June. A capital increase is intended to secure financing through the third quarter of 2027. For 2026, the company continues to expect revenue of around $2 million, with the majority of that revenue expected to be generated in the second half of the year through the conversion of pilot projects into commercial contracts.
The bottom line is that the technology appears to be working, and customer interest is growing significantly. The key question now, however, is whether the many successful tests will actually lead to larger, paid contracts and, eventually, a viable business model.

In a forum, I read about LNC's exclusive rights from Desert Control $DSRT (+0 %) that haven’t been discussed here yet. I decided to ask ChatGPT about it and received some interesting information that would also be of interest to us shareholders in light of the half-year financial report on August 19.
"Saudi Desert Control is quite interesting for Desert Control’s investment story because Saudi Arabia is precisely the market where LNC could theoretically be of great benefit.
First, the structure is important: Saudi Desert Control is based in Riyadh and is the exclusive licensed operator of Desert Control AS’s LNC technology in Saudi Arabia. So it’s not simply the Norwegian Desert Control AS itself, but rather a local operator that licenses the technology from Desert Control AS.
Why Saudi Arabia Is Particularly Exciting
The country actually has nearly the perfect profile for Liquid Natural Clay:
extremely sandy and arid soils,
very high irrigation needs,
large-scale agricultural and greening projects,
enormous government investments,
and, through the Saudi Green Initiative, the long-term goal of planting 10 billion trees and restoring 40 million hectares of degraded land.
If LNC actually reduces water consumption on a large scale there while simultaneously improving plant growth and yields, the addressable market is enormous.
And concrete progress is now being made
I find the collaboration between Saudi Desert Control and Estidamah, the Saudi National Research and Development Center for Sustainable Agriculture, particularly interesting. The state-run Saudi Press Agency confirms the agreement and explicitly mentions sustainable agriculture, combating desertification, and food security in connection with Vision 2030.
Saudi Desert Control itself also reports that it now serves farmers, project developers, municipalities, and Saudi mega-projects from its base in Riyadh. The company’s website already mentions initial results from the Estidamah collaboration as well as a pilot project as part of Green Riyadh.
For me, this is a crucial difference from mere “technological hope”: Efforts are now underway to integrate LNC directly into Saudi government and commercial structures.
What does this mean for your Desert Control shares?
There’s an important point to note here: Revenue generated by Saudi Desert Control does not automatically translate to the same revenue for Desert Control AS.
Desert Control has deliberately shifted its Middle East business to a licensing/royalty model. Local operators handle the operational implementation, while Desert Control stands to benefit from the use of its technology. This model is intended to reduce Desert Control’s capital requirements and operating costs while enabling greater scalability.
This could even be very attractive in the long term. Imagine, for example, that Saudi Desert Control eventually wins contracts worth €50 or 100 million. Desert Control would then not have to finance hundreds of employees and machines in Saudi Arabia itself, but could earn revenue from licensing and royalty payments.
The key issue, however, is scaling. I still see no evidence that Saudi Desert Control is already generating significant commercial revenue in the range of tens of millions. Pilot projects, research collaborations, and government contacts are promising—but for the stock, the real turning point would be a major commercial contract with a publicly disclosed contract value.
And that’s exactly why I find Saudi Arabia particularly interesting for your investment thesis: The potential is exceptionally large, but there’s still a significant gap between “working technology + successful trials” and “recurring revenue in the millions.”
By the way, here’s an interesting date to note: On Wednesday, August 19, 2026, at 4:00 p.m. CEST, Desert Control will release its Half-Year Business & Financial Update. I would pay particular attention to statements regarding Saudi Desert Control, Estidamah, Green Riyadh, commercial contracts, and royalty revenues."
Source: Chat GPT
$DSRT (+0 %) The sell-limit order has been executed

$DSRT (+0 %) Is it going well? Any news?


If that doesn't work, the only solution is nuclear fusion!