
- Share +14 % after trading
- The company is reportedly working with an advisor to explore a potential sale
- The payment services provider is evaluating strategic options in light of new M&A interest
Postos
5Yesterday was a rough one for the tech crowd. $ORCL (+1,09%) took a proper hit after The Information
(https://www.theinformation.com/briefings/oracles-ai-cloud-business-razor-thin-16-gross-profit-margin-new-data-show) shared some figures showing its shiny new AI business is running on margins of just 14% – and that’s before counting some potential losses on $NVDA (+1,48%) Blackwell chips.
That’s miles away from what everyone expected. The idea that “AI = easy profit” suddenly doesn’t look so bulletproof anymore.
$ORCL (+1,09%) stock dropped around 5%, and the whole cloud/AI sector followed it down. Nasdaq 100 slid roughly half a percent, but some individual names fell much harder – $SNOW (+2,74%)
$ZS (+2,95%)
$ZM (+3,35%)… and yeah, even $BILL (+0,49%) (which I’m holding myself 👀)
What’s behind the noise?
Turns out the costs of running massive AI infrastructure – chips, data centres, energy, staff – are chewing through profits faster than expected.
There’s also this slightly dodgy-sounding “circular funding” triangle going on between $ORCL (+1,09%) - OpenAI - $NVDA (+1,48%) basically money looping around the same players, propping up each other’s revenues.
Feels a bit like déjà vu from the early 2000s, doesn’t it?
About BILL
Funny thing is, $BILL (+0,49%) has also been in the news lately, but for something much healthier. They’ve teamed up with $ORCL (+1,09%)
NetSuite to improve B2B payments processing for US companies.
It’s a smart move, really. While $ORCL (+1,09%) AI margins look shaky, partnerships like this one show they’re still pushing to build value in the more “real-world” parts of the business stuff that actually saves companies time and money.
And for $BILL (+0,49%), it means tapping into $ORCL (+1,09%) huge client base and integrating deeper into enterprise systems proper long-term potential there.
My take. What do you think?
Yesterday’s dip felt more like a wake-up call than a meltdown.
AI’s not dead, but maybe it’s due for a reality check – not every company can print money just by slapping “AI” on the label.
Still holding my $BILL (+0,49%) position. It’s volatile, sure, but I reckon the fundamentals are sound and this partnership could age well once the market calms down a bit.
Was this just a short-term shakeout, or are we starting to see the first cracks in the AI hype cycle?
🔹 Revenue: $383.3M (Est. $376.5M) 🟢; UP +12% YoY
🔹 Adj EPS: $0.53 (Est. $0.41) 🟢; flat YoY
FY26 Guidance:
🔹 Revenue: $1.59–1.63B (Est. $1.63B) 🔴; UP +9–11% YoY
🔹 EPS (Non-GAAP): $2.00–2.20 (Est. $2.09) 🟡
Q1 Guidance:
🔹 Revenue: $385–395M (Est. $393.9M) 🟡; UP +7–10% YoY
🔹 EPS (Non-GAAP): $0.49–0.52 (Est. $0.53) 🔴
Q4 Segments:
🔹 Core Revenue: $345.9M; UP +15% YoY
🔹 Subscription Fees: $68.8M; UP +5% YoY
🔹 Transaction Fees: $277.1M; UP +18% YoY
🔹 Float Revenue: $37.4M
Operational Metrics
🔹 Businesses Served: 493,800; UP +13% YoY
🔹 Payment Volume: $86B; UP +13% YoY
🔹 Transactions Processed: 33M; UP +18% YoY
🔹 Network Members: 8.3M; UP +18% YoY
Profitability Metrics:
🔹 Gross Profit: $309.8M (80.8% margin) vs. $278.5M (81.0%) last year
🔹 Non-GAAP Gross Profit: $322.7M (84.2% margin) vs. $292.0M (85.0%) last year
🔹 Non-GAAP Operating Income: $56.4M; DOWN -6% YoY
🔹 Non-GAAP Net Income: $61.6M; flat YoY ($63.9M in Q4'24)
Capital Allocation
🔹 Repurchased ~2.2M shares for $100M in Q4 + July
🔹 New $300M Share Repurchase Program authorized
CEO Commentary
🔸 “Fiscal year 2025 was pivotal as we drove growth and profitability, launched essential new software and payment products, and expanded our market opportunity.” – René Lacerte, CEO
🔸 “Our scale advantage with ~500K SMBs and 9,000 accounting firms positions BILL to win intelligent financial operations.”
CFO Commentary
🔸 “We delivered a strong Q4 ahead of guidance while sharpening our focus on profitability.” – Rohini Jain, CFO
🔸 “Our new $300M repurchase reflects confidence in BILL as a compelling investment opportunity.”
🔹 EPS: $0.56 (Est. $0.46) 🟢
🔹 Revenue: $362.6M (Est. $360.14M) 🟢; UP +14% YoY
🔹 Subscriptions & Transactions: $319.6M (Est. $319.45M) 🟢
🔹 Free Cash Flow: $71.6M (Prev. $74.2M YoY) 🔴
Q3 Guidance:
🔹 Revenue: $352.5M-$357.5M (Est. $360.24M) 🔴
🔹 Core Revenue: $317.5M-$322.5M; UP +13-15% YoY
🔹 Non-GAAP EPS: $0.35-$0.38 (Est. $0.34) 🟢
FY25 Full-Year Guidance:
🔹 Revenue: $1.45B-$1.47B (Est. $1.46B) 🟡
🔹 Core Revenue: $1.30B-$1.31B; UP +16-17% YoY
🔹 Non-GAAP EPS: $1.87-$1.97 (Est. $1.78) 🟢
Business Metrics & Processing Volumes:
🔹 Total Payment Volume: $84B; UP +13% YoY
🔹 Total Transactions Processed: 30M; UP +17% YoY
🔹 Subscription Fees: $67.7M; UP +7% YoY
🔹 Transaction Fees: $251.9M; UP +19% YoY
🔹 Float Revenue (Interest on Funds Held): $42.9M
User & Business Growth:
🔹 Businesses Using BILL Solutions: 481,300
🔹 Convertible Senior Notes Offering: $1.4B due 2030
🔹 Share Repurchases: ~2.3M shares repurchased for ~$200M
🔹 New Board Members: Keri Gohman and Dan Wernikoff
CEO René Lacerte’s Commentary:
🔸 "We delivered strong financial results while executing on our vision to be the de facto intelligent financial operations platform for SMBs. We are leveraging our leadership position to empower businesses and expand the depth of our platform."
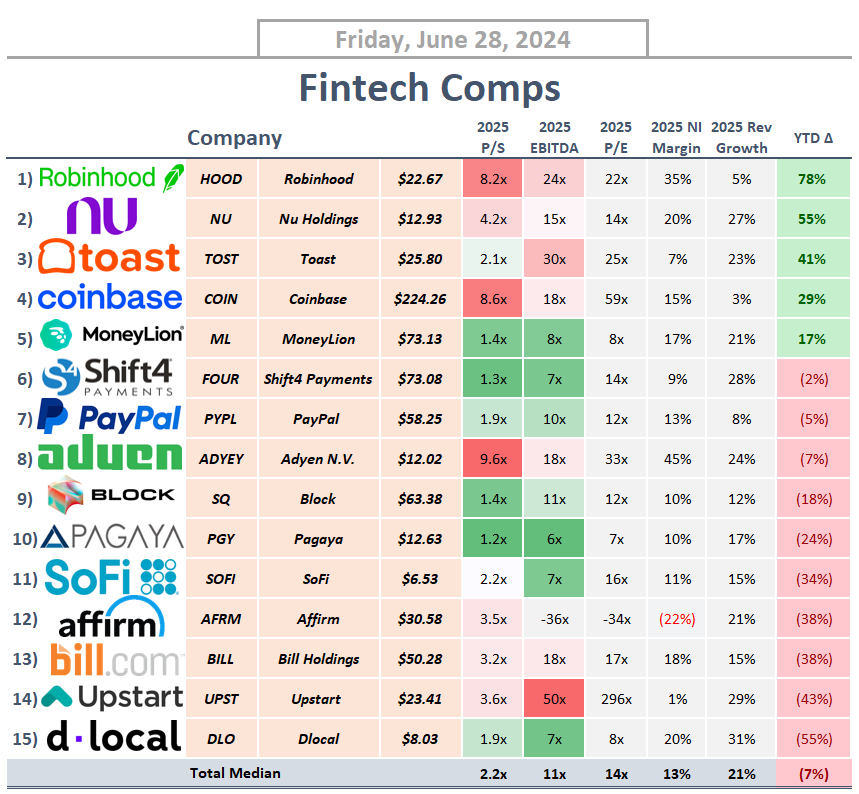
#fintech - I found a nice overview here
Neobanking is forecast to grow at a compound annual growth rate of around 55% to $2 trillion by 2030 - Let's take a look at where fintech stocks stand based on 2025 metrics
Who do you favor? ☺️
$NU (-0,39%)
$COIN (-2,3%)
$FOUR
$HOOD (-2,45%)
$DLO (+0,38%)
$TOST (+0,21%)
$PYPL (-0,18%)
$BILL (+0,49%)
$ADYEY (-1,07%)
$SQ (+0,4%)
$SOFI (-1,62%)
$PGY
$ML
$AFRM (-1,46%)
$UPST (-1,28%)
$SOFI (-1,62%) - Company presentation and personal opinion:

Principais criadores desta semana


