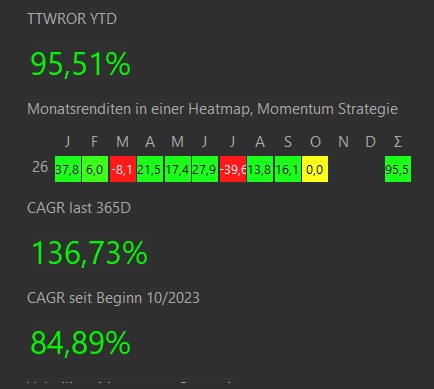
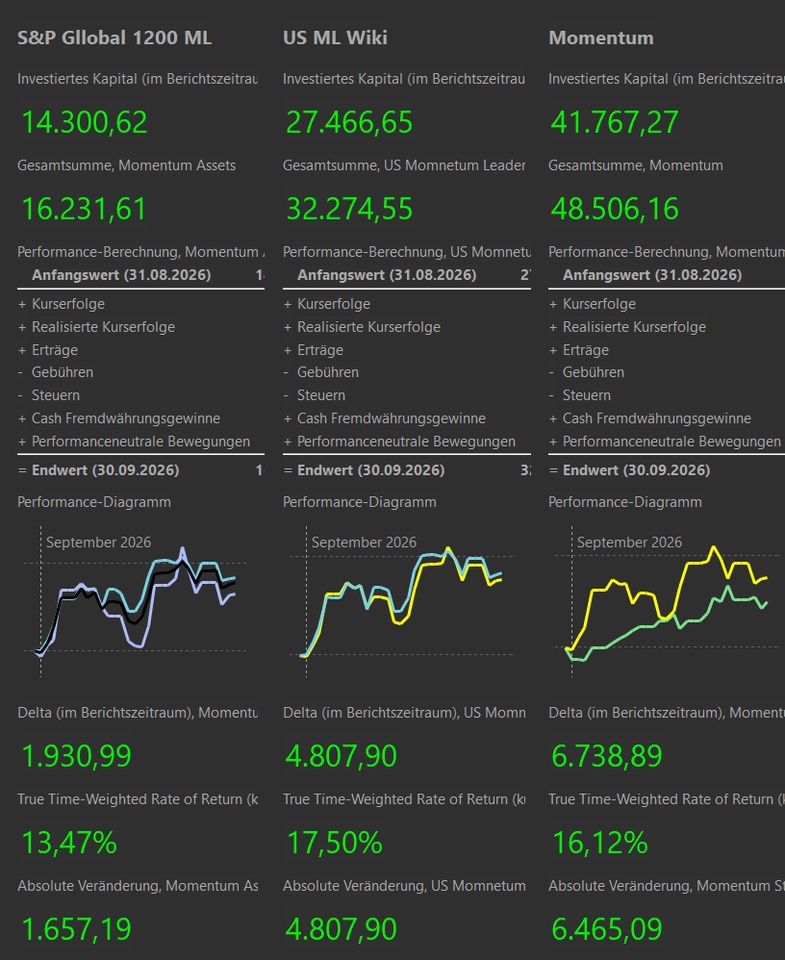
$19021982 (+4,59%)
Over the past few months, I’ve spent significantly more time than originally planned re-examining my momentum models from the ground up.
My starting point wasn’t Global Momentum Leaders at all, but rather my U.S. momentum model.
And in the process, I came to a realization that, while unpleasant, ultimately set the entire rest of the research process in motion:
A backtest is only as reliable as the data on which it is based.
The Starting Point: A Problem in the Historical U.S. Backtest
While re-examining the U.S. momentum model, it became apparent that the historical composition of the investment universe was not sufficiently represented at a specific point in time .
Simply put, this meant that the historical backtest sometimes included stocks that, at the respective point in time, would not actually have been part of the intended investment universe.
This is particularly problematic for a momentum strategy.
A few exceptional winners can have a massive impact on a backtest. If such stocks are retroactively included in the investment universe—even though they did not belong there at the time—this can result in returns that would not have been achievable under real-world conditions.
For me, therefore, it was clear:
I don’t want a model with impressive historical metrics if I can’t trust the underlying data.
The result was not simply to tweak the backtest a little.
It was rebuilt based on historically more accurate point-in-time holdings and the strategy was then retested.
This process resulted in US Momentum Leaders 2.0 . In addition to the cleaner historical data set, individual rules and parameters were also re-examined and optimized.
The launch of US Momentum Leaders 2.0 is scheduled for January 1, 2027. I will also publish a separate post on this topic before the transition, transparently explaining what has changed compared to the previous model and why.
And with that, Global Momentum Leaders also came under scrutiny.
The previous Global Momentum Leaders model was based on an assumption that seemed quite plausible at first:
If certain momentum rules and parameters work well within the U.S. stock market, they should, in principle, also be transferable to a global stock universe.
That was precisely the basis of the previous structure.
Proven elements of the U.S. model were largely applied to international stock markets to create a global momentum strategy.
However, following a much more in-depth restructuring and more extensive backtesting, I must revise this assumption.
A rule that works exceptionally well in a specific market is by no means a universal rule.
In my view, it is not enough to take a functioning U.S. momentum model and simply expand the investment universe to the entire world.
International stock markets differ too greatly for that.
The consequence of this:
Global Momentum Leaders will have its own model architecture.
What does the new Global Momentum Leaders look like?
The basic logic can be summarized relatively simply:
Search globally → compare regionally → form a pool of candidates → select based on momentum → take market regimes into account.
The investment universe continues to encompass major stock markets worldwide.
However, the selection methodology has undergone a significant change.
1. Regional comparisons instead of simply comparing everything against everything
Stocks are first evaluated within their respective regions . Only then do the strongest regional candidates compete against one another.
This is intended to prevent particularly volatile markets from dominating a global momentum ranking solely because of their higher volatility. The current model architecture distinguishes seven regions for this purpose: (the U.S., Canada, Japan, Europe, Asia, Australia, and Latin America)
2. A stable pool of candidates
Twice a year, a deliberately compact pool of candidates is formed from strong momentum stocks.
This is based on the 12-month momentum in euros.
At the end of the year, the pool is completely reconstituted; a partial renewal takes place at mid-year. This is intended, on the one hand, to maintain stability and, on the other hand, to allow a new strong trend to be included in the pool.
3. Extreme price swings are limited
Stocks with a return of more than +300% within twelve months are excluded even before the pool is formed.
In my analyses, this CAP300 filter has improved the risk profile without compromising the fundamental momentum-based nature of the strategy.
4. Monthly selection remains consistently momentum-based
From the candidate pool, a combined 6-/9-/12-month momentum scoredetermines which stocks are actually held.
5. It’s Not Just the Stock—the Home Market Matters, Too
Another significant change concerns the market filters.
A strong individual stock alone is not enough. The market environment of its home market is also taken into account.
The U.S., Europe, Japan, Australia, Canada, and various Asian markets are therefore not simply managed via a single global indicator. Instead, the model uses market- or country-specific trend filters.
This differentiation has proven particularly relevant in Asia. Hong Kong, Korea, Taiwan, and Singapore can be in very different market phases. In my analyses, a single “Asia” filter proved less convincing than a differentiated approach.
My goal is not to build a backtest champion
That is probably the most important point of the entire revision.
I have now tested numerous variants and parameters.
In the process, I also discarded ideas that I had originally expected would improve the model.
The crucial question was therefore not:
“Which combination of parameters produces the highest return in hindsight?”
But rather:
“Which rules can be logically justified and prove to be as robust as possible under different conditions?”
That’s why I don’t view the findings regarding the previous models as a failure.
The original hypotheses were plausible.
Then better data became available.
Then came more extensive testing.
And the results did not confirm certain assumptions.
So these assumptions are discarded, and the models are adjusted.
In my view, this is exactly how systematic model development should work.
And what role should Global Momentum Leaders play in the future?
This brings me to what is perhaps the most important insight for me from the entire research process.
Even with the new architecture, I do not view Global Momentum Leaders as a one-to-one replacement for US Momentum Leaders 2.0.
Both models serve different purposes.
US Momentum Leaders 2.0 is intended to form the core of my momentum approach.
Global Momentum Leaders, on the other hand, is the deliberate global complement.
The model is designed to capture additional strong trends when market leadership emerges outside the U.S.
If the U.S. remains the leader, U.S. stocks can also be part of the global model. If, on the other hand, market leadership shifts to Europe, Japan, Canada, or Asia, for example, the model should be able to systematically track this development.
That is why, for my personal investment goals, I find the combination of both approaches to be significantly more interesting than Global Momentum Leaders alone.
In my research to date, a breakdown of approximately the following has been particularly interesting:
80% US Momentum Leaders 2.0
20% Global Momentum Leaders
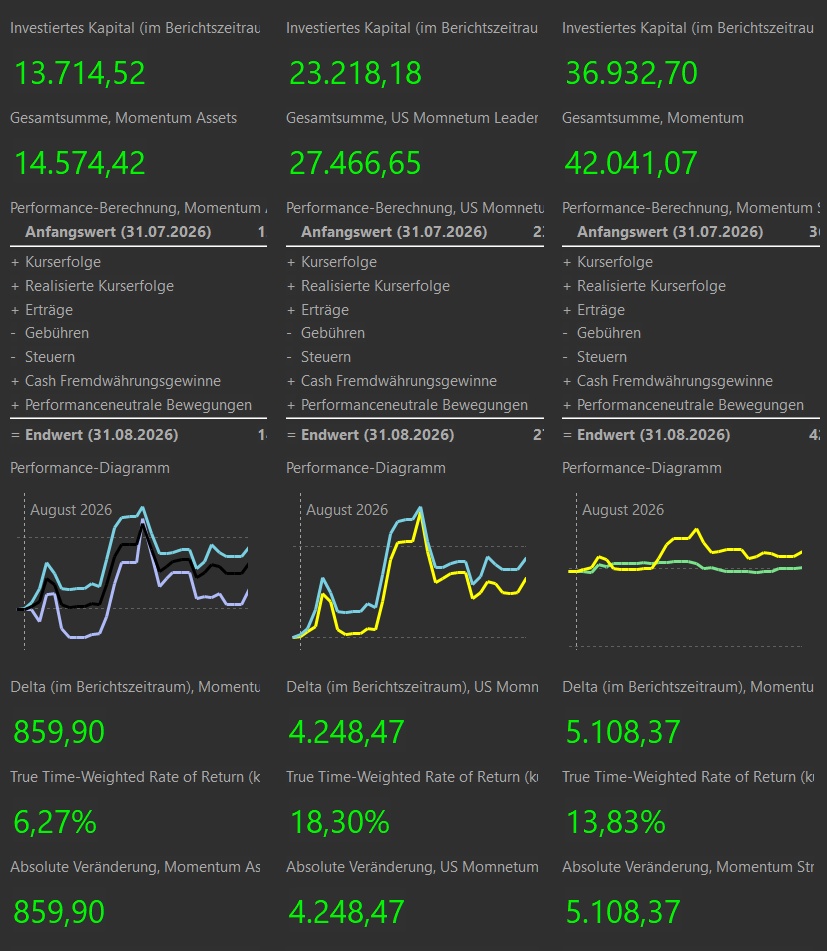
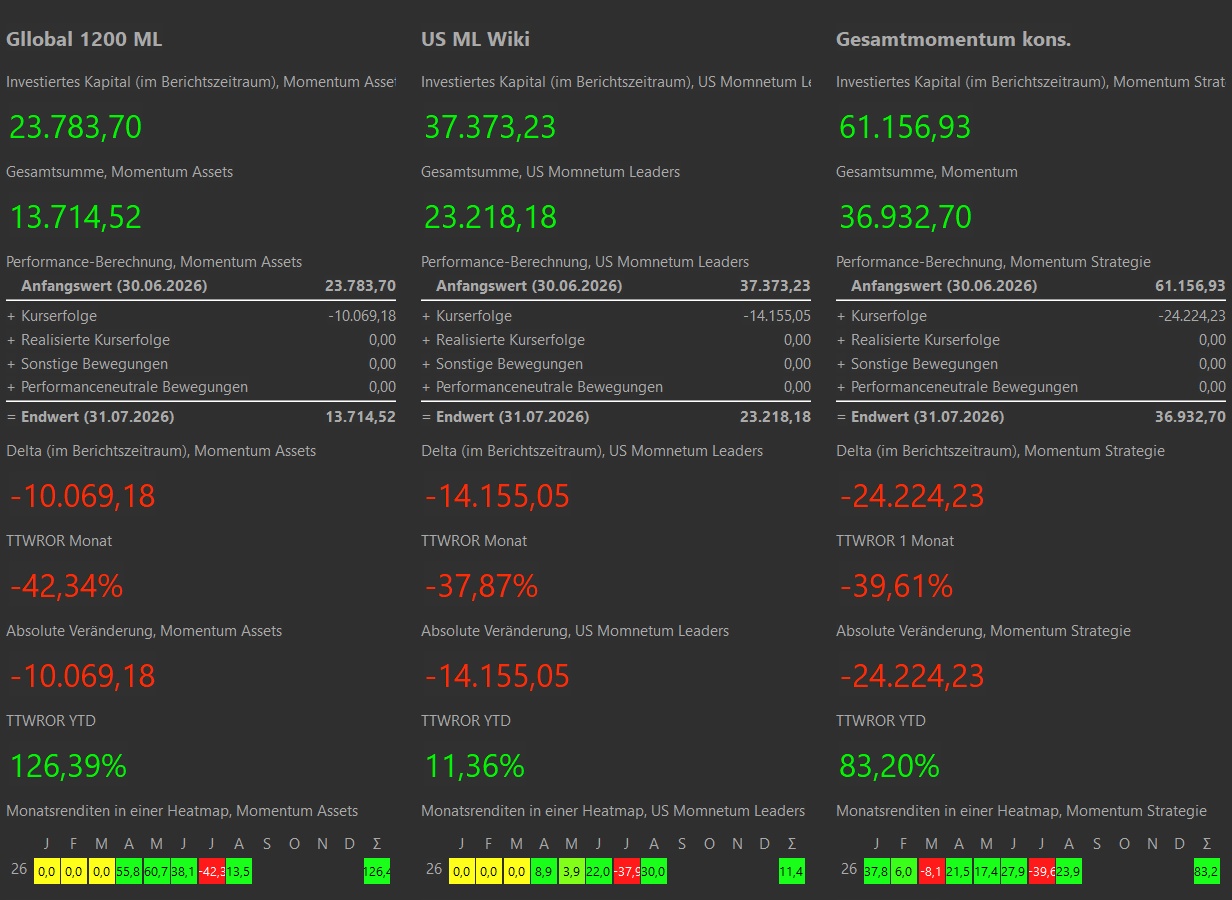
Although the inclusion of the global model historically cost a portion of the return compared to the pure U.S. Momentum model, it simultaneously significantly improved the risk profile of the overall strategy. This is precisely where I see the true purpose of the global component.
For my personal investment goals, I would therefore not prefer an exclusive Global Momentum Leaders portfolio.
The division of roles is now clear to me:
US Momentum Leaders 2.0 = Core of the momentum approach
Global Momentum Leaders = global complement / satellite
My Conclusion
Perhaps the most important insight from the past few months therefore has nothing to do with any specific lookback period, any market filter, or any single backtest.
It is this:
A good strategy does not consist of sticking to rules once they’ve been set. It consists of formulating hypotheses, testing them with the best possible data, and discarding them if the results contradict them.
For the U.S. model, this initially meant correcting the historical data set and revalidating the model using a cleaner point-in-time universe.
For Global Momentum Leaders, a second insight emerged:
The momentum philosophy can be applied globally. However, the rules and parameters of a U.S. model do not necessarily translate on a 1:1 basis.
Therefore, US Momentum Leaders 2.0 and Global Momentum Leaders will follow the same fundamental philosophy in the future, but will deliberately use different rules tailored to their respective investment universes .
And perhaps this is the most important insight for me regarding Global Momentum Leaders:
It is not intended to replace US Momentum Leaders 2.0. It is intended to add something that the U.S. model deliberately cannot achieve: systematically seeking out strong trends outside the U.S. as well, thereby giving my overall approach a second, global component.