There was a trade in my challenge area last week. It $AT100ASTA001 (+0,95%) left the portfolio with a net change of zero.
In exchange, $ASX (-6,4%) was added to the portfolio.
Messaggi
6There was a trade in my challenge area last week. It $AT100ASTA001 (+0,95%) left the portfolio with a net change of zero.
In exchange, $ASX (-6,4%) was added to the portfolio.
The last two posts were about HBM/Memory and Power & Cooling. Both topics show that the critical points in the AI stack are shifting step by step.
Today it's all about Advanced Packaging.
The reason for this lies in the architecture of modern AI systems: memory, compute and other components are are moving ever closer together physically. Without this integration, current performance and bandwidth requirements would hardly be achievable.
This is also changing the role of packaging. It used to be more of a downstream production step. Now it is becoming a key technological key technological point.
This is particularly evident in HBM (High Bandwidth Memory). The memory is located directly next to the GPU, data must be transferred extremely quickly, while at the same time the requirements for precision, heat dissipation and yield increase considerably.
That's why I look at companies like $ASX (-6,4%) (ASE Technology), $BESI (-6,52%) (BE Semiconductor) or even $TSM (-2,13%) (TSMC) are currently very close to this bottleneck.
I find one thing particularly interesting: the limiting factor is once again shifting a little further within the infrastructure. It is no longer just computing power that counts, but increasingly the ability to connect highly complex components efficiently at all.
Next, I'll take a look at energy/grid. Another bottleneck area that is currently becoming critical within the technology stack.


Hello my dears,
Following Juan's visit to ASE, the share continues to show good momentum.
I would like to praise Juan once again. And show you in the follow-up report why he chose this particular company. And why Juan recognized the potential here even before planning the trip to Taiwan.
Race for semiconductor packaging and testing capacity intensifies as ASE, Samsung and Amkor announce new moves
(this article quotes information from Bloomberg )
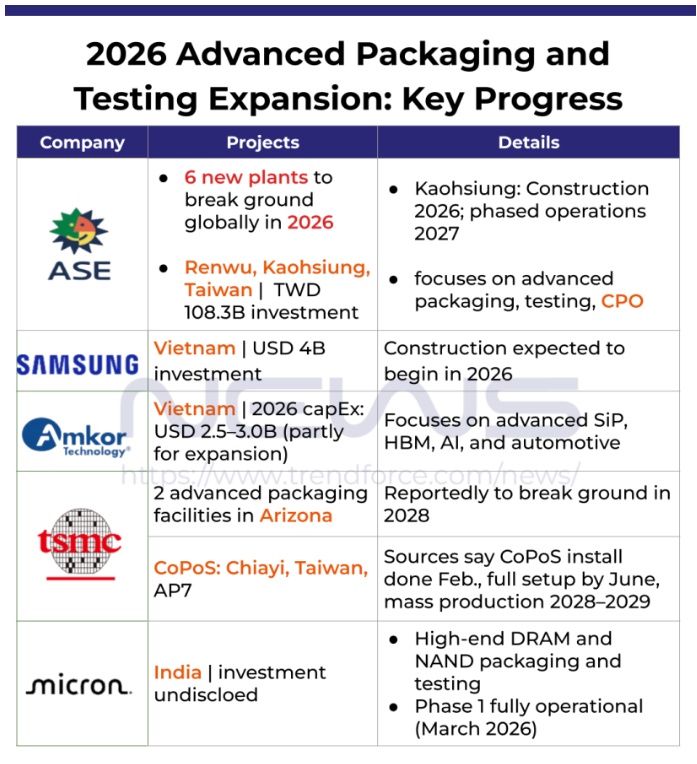
Since April 2026, the global semiconductor packaging and test sector has seen a wave of significant developments. ASE has launched its largest manufacturing construction program to date, with six new facilities scheduled to begin construction worldwide this year. Meanwhile, Samsung Electronics plans to invest US$4 billion in a new packaging and test facility in Vietnam, while Amkor is simultaneously accelerating its capacity expansion in the country.
ASE expands production worldwide
On April 10, 2026, ASE Technology Holding held a groundbreaking ceremony for a new facility at Renwu Industrial Park in Kaohsiung. With a total investment of over TWD 108.3 billion, the plant will focus on advanced semiconductor test services covering applications such as AI, HPC, 5G communications and automotive electronics. The first phase is scheduled to be completed by April 2027, followed by phase two in October of the same year. The facility is expected to achieve an annual production value of up to TWD 177.3 billion.
This project is just one part of ASE's wider global expansion. According to CEO Tien Wu, 2026 marks the company's most aggressive year in manufacturing construction, with six new plants coming online globally - a record high. In addition to the Kaohsiung site, expansion projects span the United States, Malaysia, Japan and Germany to address the growth in AI-driven semiconductor demand.
In terms of capital expenditure, ASE initially planned US$7 billion for 2026, but indicated a possible upward revision due to strong market demand, with details to be announced in the upcoming earnings call.
On the technology front, Wu pointed out that Co-Packaged Optics (CPO) is expected to enter mass production in 2026. To support the rapid expansion, ASE has also launched a new round of hiring, targeting 3,000 technical recruits in 2026 and another 1,000 in 2027 to strengthen R&D and capacity expansion.
Samsung and Amkor focus on Vietnam
According to Bloomberg on April 10, Samsung Electronics plans to invest USD 4 billion to build a semiconductor packaging and testing plant in Thai Nguyen province in northern Vietnam, with an initial phase of USD 2 billion. This would be Samsung's largest single investment in this segment since entering Vietnam in 2008. Vietnam's Ministry of Finance has confirmed ongoing talks with Samsung regarding investment cooperation in the semiconductor sector.
The new facility will be located near Samsung's existing smartphone manufacturing base and will leverage the region's established supply chain and infrastructure to meet the growing global demand for chip packaging and testing driven by data centers and AI devices.
Industry observers note that Samsung's move aligns with ongoing investments by TSMC and Intel in advanced packaging, solidifying its position in the overall semiconductor value chain. Vietnam, benefiting from competitive labor costs, strategic location and an established industry base, is increasingly becoming a major destination for the relocation of packaging and test capacity.
Meanwhile, Amkor is accelerating the expansion of its operations in Vietnam. Since 2021, the company has invested a total of USD 1.6 billion to build advanced packaging facilities at Yen Phong 2C Industrial Park in Bac Ninh province. This site represents Amkor's largest advanced packaging base in the world, focusing on system-in-package (SiP) and HBM storage integration, offering turnkey solutions from design to electrical testing.
According to Amkor's February 2026 financial report, the company plans capital expenditures of USD 2.5-3.0 billion for the year, with a focus on expanded packaging capacity expansion, including operations in Vietnam. Key end markets include HPC, AI, automotive electronics, IoT and mobile communications.
Vietnam has been positioned by Amkor as a "growth engine for the next decade", aiming to diversify risks in the supply chain. The sites in Vietnam have a modular production layout with 25% flexibility in reserved capacity, allowing for rapid reconfiguration of equipment in response to policy or market changes.
Competition in the semiconductor packaging and testing sector is increasing
Packaging and testing of semiconductors are the back-end processes of chip manufacturing and comprise two main phases: Packaging and Testing. Packaging includes processes such as dicing, chip termination, wire bonding or flip-chip, as well as forms that provide physical protection, electrical connections, thermal management and standardized interfaces for chips. Testing includes wafer probing (CP) and final testing (FT), where specialized equipment is used to identify defective or underperforming chips to ensure product quality and reliability before shipment.
As the effect of Moore's Law diminishes, advanced packaging has become a critical way to improve chip performance, while the value proposition of testing continues to increase in parallel with increasing chip complexity. Since the beginning of 2026, numerous companies worldwide have announced new or expanded packaging and test facilities.
Good morning my dears,
I need to find the perfect semiconductor for a project. And where would you find it if not in Taiwan? So dear Juan set off on his journey.
I had written him a cheat sheet:
My dears, and what can I tell you. Juan has done his homework well.
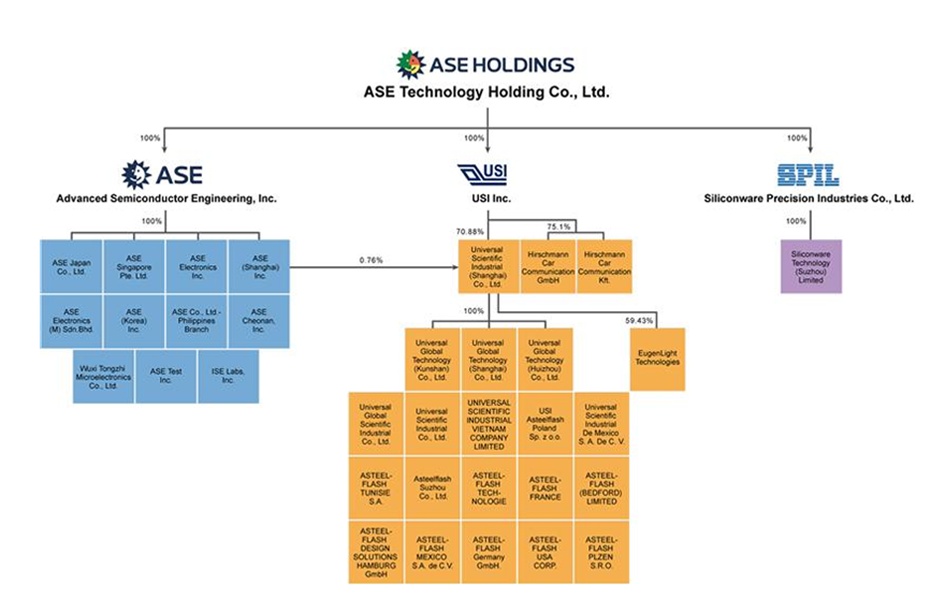
And so today we can present you with a company that is active in these important technologies through the back door, in the form of subsidiaries and holdings. And on top of that, there's even LIDAR.
And let's compare it with the companies in these sectors, which have been making one high after another for weeks. With a forward P/E ratio of 23 and a PEG of 0.50, our current company is perhaps even a small insider tip.
Of course, I would like to ask you for your opinion, how do you see the company?
And the company that Juan has found for us is ASE Technology Holding $ASX (-6,4%)
ASE Technology Holding Co Ltd is a Taiwan-based company that mainly invests in packaging services, testing services, electronic product assembly technology and manufacturing services. The investment business includes general investment projects. The packaging and testing business provides integrated circuit (IC) services, including packaging and module design, IC packaging, multi-chip packaging, micro and hybrid modules, memory packaging, front-end testing, wafer probe testing, finished product testing, substrate design and manufacturing. The electronics manufacturing service business mainly provides a series of professional services such as development and design, material procurement, production and manufacturing, logistics, maintenance and other after-sales services for domestic and foreign brand manufacturers in the fields of communications, consumer electronics, computers, memory industry, automotive electronics and other types of electronic products.
Number of employees: 105,955
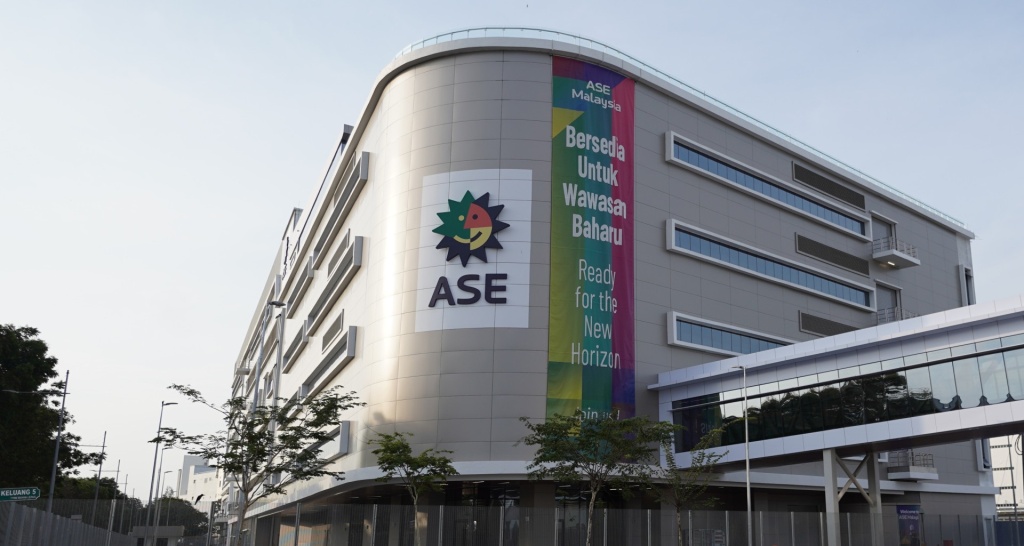
With over 95,000 employees worldwide, ASE operates manufacturing facilities in several countries, including Taiwan, China, South Korea, Japan, Singapore, Malaysia, Vietnam, Mexico, the United States, Poland, France, the United Kingdom, Germany, Tunisia and the Czech Republic.
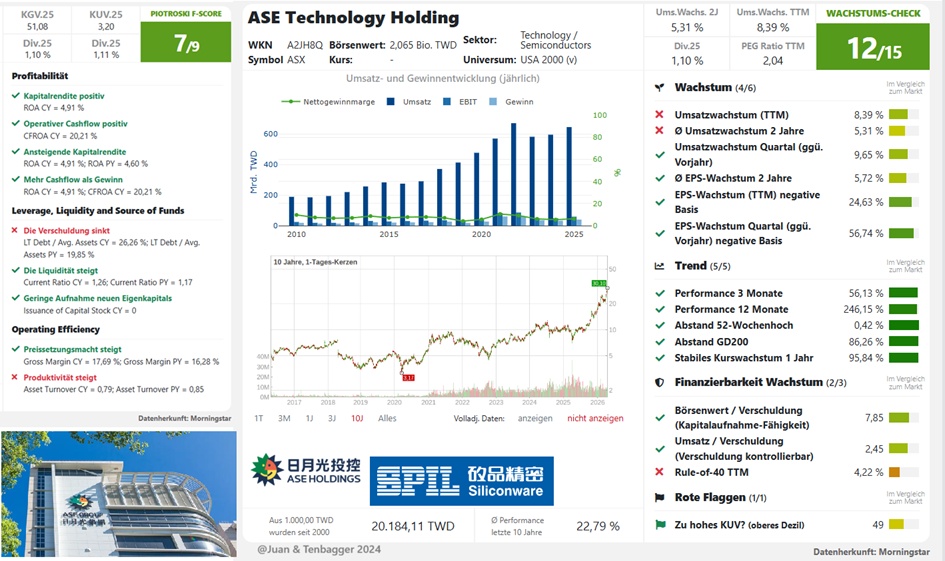
ASE Industrial published its figures for the quarter ended December 31, 2025 at the trimonthly financial conference on February 5, 2026.
Earnings per share of USD 0.22 were presented. In the previous year, earnings per share amounted to USD 0.130.
Revenue for the past quarter was reported at USD 5.73 billion - an increase of 14.24% compared to the same quarter of the previous year, when USD 5.02 billion was reported.
EPS for the year as a whole was put at USD 0.600. The previous year's figure was USD 0.470 per share.
Annual sales were put at USD 20.71 billion, compared to USD 18.54 billion in the previous year.
Editorial finanzen.net
USI subsidiary Universal Optoelectronics acquires controlling stake in Eugenlight Technologies, furthering the integration of the optical interconnect industry
January 16, 2026
USI (SSE: 601231), a subsidiary of ASE Technology Holding Co, Ltd (TWSE: 3711, NYSE: ASX), has announced that its subsidiary Universal Optoelectronics has acquired a controlling stake in EugenLight Technologies - a strategic move aimed at consolidating its position in the global optical interconnect ecosystem. By integrating EugenLight's expertise in high-speed optoelectronic components and silicon photonics - breakthrough technologies essential for AI data centers, LiDAR and photonic computing - USI, together with parent company ASE Holdings, aims to enhance its capabilities in rack system integration and advanced packaging.
ASE breaks ground on new high-tech facility in Kaohsiung, investing NT$17.8 billion to meet demand for AI chips
March 11, 2026
ASE starts construction of a new Renwu power plant to build a high-tech test cluster
April 10, 2026
ASE Technology Holdings recognized as one of Taiwan's top 10 sustainable companies for the third consecutive year and received 16 awards, demonstrating leadership in environmental, social and governance (ESG) practices
December 1, 2025
ASE introduces IDE 2.0 - AI-powered platform accelerates housing design accuracy and innovation
November 4, 2025
ASE and Analog Devices announce strategic collaboration
October 21, 2025
ASE und Analog Devices kündigen strategische Zusammenarbeit an | ASE-Holdings
SPIL hosts NVIDIA founder and CEO Jensen Huang at new fab site to accelerate semiconductor assembly and test services
January 16, 2025
Siliconware Precision Industries Co, Ltd ("SPIL"), a subsidiary of ASE Technology Holding Co, Ltd (TWSE: 3711, NYSE: ASX), welcomed Jensen Huang, founder and CEO of NVIDIA, to the opening ceremony of its Tan Ke Plant facility. The Chairman of SPIL, C.W. Tsai, met with NVIDIA Founder and CEO Jensen Huang and highlighted the close cooperation between the two companies as they work together to usher in the new era of AI chip innovation.
Sales breakdown by business unit:
2025 (TWD)
Packaging 314 billion
Electronic Manufacturing Service (EMS) 289 billion
Testing 72.46 billion
Others 16.38 bn
Adjustments and Eliminations -46.37 billion
Geographical distribution of sales:
2025 (TWD)
U.S. 366 bn
Taiwan 116 billion
Asia 97.82 billion
Europe 64.91 bn
Other 897 million
Brief summary of the key financial figures (2025-2028)
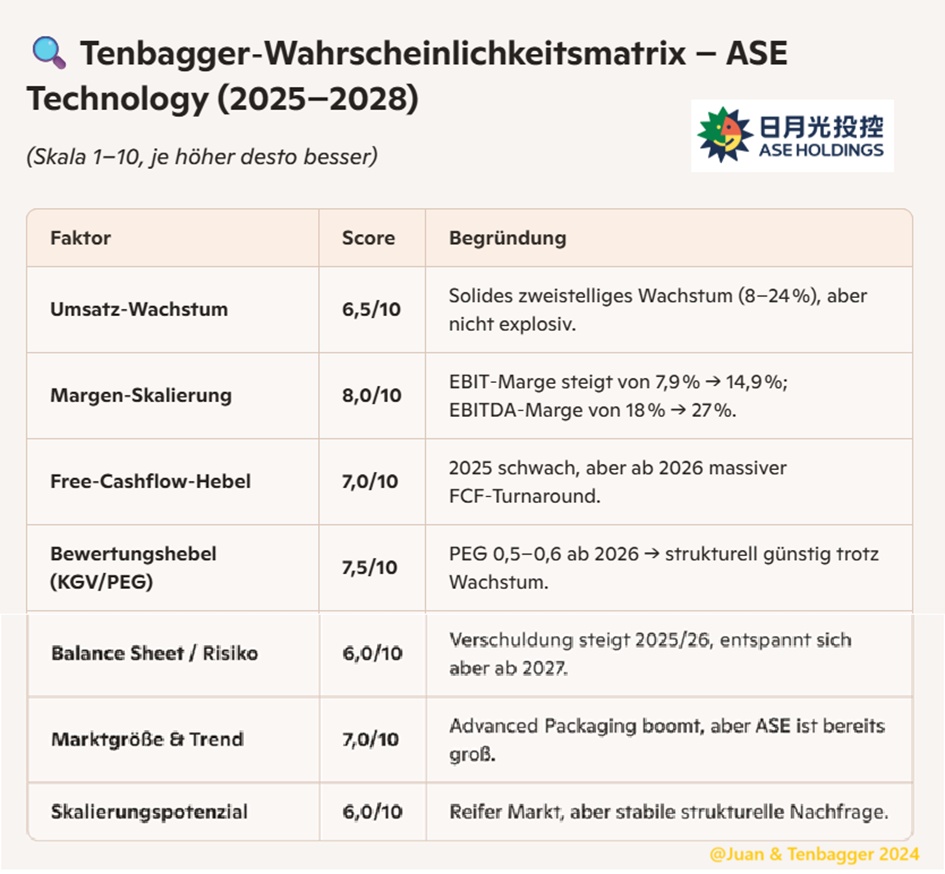
ASE shows from 2025 a significant operational recoveryacross all key performance indicators. Revenue, EBIT and net income grow double-digit growthwith 2026 in particular being a margin leap year year. Profitability improves significantly: EBITDA margin rises from 18% to over 27%, EBIT margin from 7.9% to almost 15%.
The free cash flow development is initially weak (negative in 2025 due to extremely high CAPEX), but turns strongly positive from 2026 onwards. Net debt rises sharply in 2025/26, but is reduced again from 2027 - at the same time, the leverage ratio falls to a very solid level by 2028.
All in all, ASE provides a picture of scaling growth, rising margins, decreasing risk and clearly improved return on investment (ROE of up to 25 %). For investors, this looks like a classic turnaround into structural growth.
(TWD in millions)
Market value 2,034,392
Number of shares (in thousands) 4,375,036
Date of publication 05,02,2026
Brief summary of the valuation ratios
In terms of valuation, ASE acts as a classic transitional value: expensive in the short term, fair in the medium term, cheap in the long term. The P/E ratio will remain high in 2025-2026 because earnings will only pick up with a delay. From 2027, the picture changes: earnings scale faster than the share price, causing the P/E ratio to fall significantly and the valuation to become more attractive.
The PEG curve is the strongest indicator: from 2026, it is stable in the 0.5-0.6 range - a level that normally indicates undervaluation with high growth growth. The dividend yield increases moderately, but remains more of a bonus than a core argument.
FCF yield turns positive from 2026 and improves strongly, further underpinning the valuation. Overall, ASE shows a profile that will turn into a structurally structurally favorable valuation valuation from 2027 onwards, while the operating performance increases significantly at the same time. For investors, this means Valuation and growth will start to move in the same direction from 2027 - a positive setup.
⭐ Overall score: 6.8 / 10
🎯 Realistic tenbagger probability: 10-15%
📌 Juan's conclusion
ASE is not a classic Tenbagger moonshotbut a solid compounderthat will enter a phase from 2027 in which:
This is a high-quality setupbut not explosive enough for a 10× story in 5-7 years.
A doubling to tripling is more likelynot a tenfold increase.
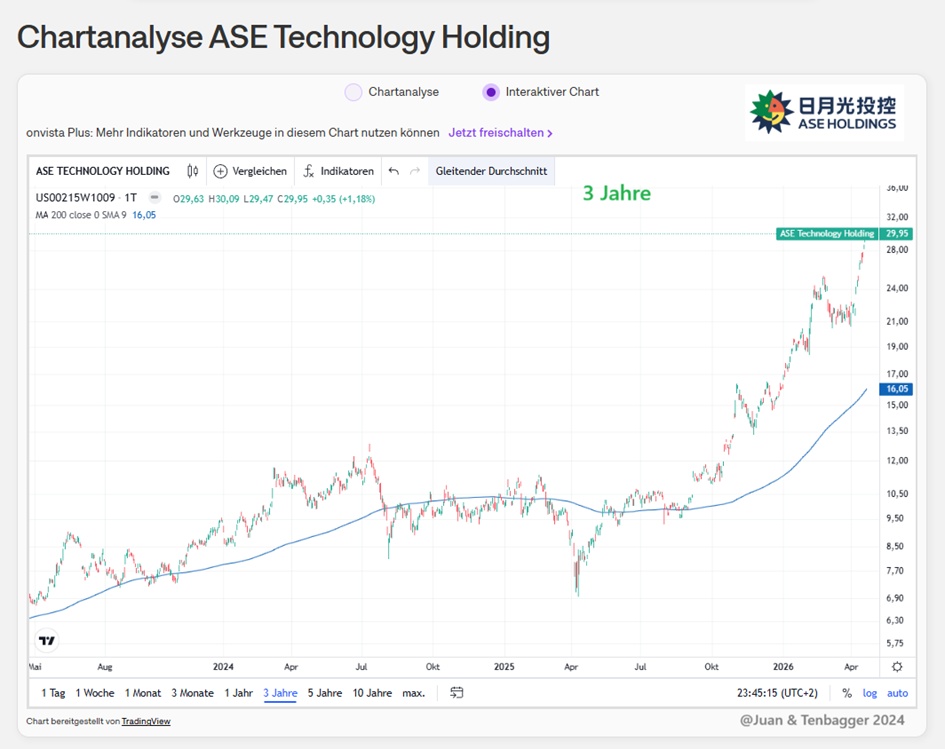
Performance
1 week +10.16 %
1 month +38.90
6 months +133.44 %
1 year +269.54 %
3 years +322.25 %
Ladies and gentlemen, the next correction should be coming. Figures will also be presented next week.
PRICE €25.50 (23.04.2026 at 07:52)
+ 5

Good morning my dears,
I need to find the perfect semiconductor for a project. And where would you find it if not in Taiwan? So dear Juan set off on his journey.
I had written him a cheat sheet:
My dears, and what can I tell you. Juan has done his homework well.
And so today we can present you with a company that is active in these important technologies through the back door, in the form of subsidiaries and holdings. And on top of that, there's even LIDAR.
And let's compare it with the companies in these sectors, which have been making one high after another for weeks. With a forward P/E ratio of 23 and a PEG of 0.50, our current company is perhaps even a small insider tip.
Of course, I would like to ask you for your opinion, how do you see the company?
And the company that Juan has found for us is ASE Technology Holding $ASX (-6,4%)
ASE Technology Holding Co Ltd is a Taiwan-based company that mainly invests in packaging services, testing services, electronic product assembly technology and manufacturing services. The investment business includes general investment projects. The packaging and testing business provides integrated circuit (IC) services, including packaging and module design, IC packaging, multi-chip packaging, micro and hybrid modules, memory packaging, front-end testing, wafer probe testing, finished product testing, substrate design and manufacturing. The electronics manufacturing service business mainly provides a series of professional services such as development and design, material procurement, production and manufacturing, logistics, maintenance and other after-sales services for domestic and foreign brand manufacturers in the fields of communications, consumer electronics, computers, memory industry, automotive electronics and other types of electronic products.
Number of employees: 105,955
With over 95,000 employees worldwide, ASE operates manufacturing facilities in several countries, including Taiwan, China, South Korea, Japan, Singapore, Malaysia, Vietnam, Mexico, the United States, Poland, France, the United Kingdom, Germany, Tunisia and the Czech Republic.
ASE Industrial published its figures for the quarter ended December 31, 2025 at the trimonthly financial conference on February 5, 2026.
Earnings per share of USD 0.22 were presented. In the previous year, earnings per share amounted to USD 0.130.
Revenue for the past quarter was reported at USD 5.73 billion - an increase of 14.24% compared to the same quarter of the previous year, when USD 5.02 billion was reported.
EPS for the year as a whole was put at USD 0.600. The previous year's figure was USD 0.470 per share.
Annual sales were put at USD 20.71 billion, compared to USD 18.54 billion in the previous year.
Editorial finanzen.net
USI subsidiary Universal Optoelectronics acquires controlling stake in Eugenlight Technologies, furthering the integration of the optical interconnect industry
January 16, 2026
USI (SSE: 601231), a subsidiary of ASE Technology Holding Co, Ltd (TWSE: 3711, NYSE: ASX), has announced that its subsidiary Universal Optoelectronics has acquired a controlling stake in EugenLight Technologies - a strategic move aimed at consolidating its position in the global optical interconnect ecosystem. By integrating EugenLight's expertise in high-speed optoelectronic components and silicon photonics - breakthrough technologies essential for AI data centers, LiDAR and photonic computing - USI, together with parent company ASE Holdings, aims to enhance its capabilities in rack system integration and advanced packaging.
ASE breaks ground on new high-tech facility in Kaohsiung, investing NT$17.8 billion to meet demand for AI chips
March 11, 2026
ASE starts construction of a new Renwu power plant to build a high-tech test cluster
April 10, 2026
ASE Technology Holdings recognized as one of Taiwan's top 10 sustainable companies for the third consecutive year and received 16 awards, demonstrating leadership in environmental, social and governance (ESG) practices
December 1, 2025
ASE introduces IDE 2.0 - AI-powered platform accelerates housing design accuracy and innovation
November 4, 2025
ASE and Analog Devices announce strategic collaboration
October 21, 2025
ASE und Analog Devices kündigen strategische Zusammenarbeit an | ASE-Holdings
SPIL hosts NVIDIA founder and CEO Jensen Huang at new fab site to accelerate semiconductor assembly and test services
January 16, 2025
Siliconware Precision Industries Co, Ltd ("SPIL"), a subsidiary of ASE Technology Holding Co, Ltd (TWSE: 3711, NYSE: ASX), welcomed Jensen Huang, founder and CEO of NVIDIA, to the opening ceremony of its Tan Ke Plant facility. The Chairman of SPIL, C.W. Tsai, met with NVIDIA Founder and CEO Jensen Huang and highlighted the close cooperation between the two companies as they work together to usher in the new era of AI chip innovation.
Sales breakdown by business unit:
2025 (TWD)
Packaging 314 billion
Electronic Manufacturing Service (EMS) 289 billion
Testing 72.46 billion
Others 16.38 bn
Adjustments and Eliminations -46.37 billion
Geographical distribution of sales:
2025 (TWD)
U.S. 366 bn
Taiwan 116 billion
Asia 97.82 billion
Europe 64.91 bn
Other 897 million
Brief summary of the key financial figures (2025-2028)
ASE shows from 2025 a significant operational recoveryacross all key performance indicators. Revenue, EBIT and net income grow double-digit growthwith 2026 in particular being a margin leap year year. Profitability improves significantly: EBITDA margin rises from 18% to over 27%, EBIT margin from 7.9% to almost 15%.
The free cash flow development is initially weak (negative in 2025 due to extremely high CAPEX), but turns strongly positive from 2026 onwards. Net debt rises sharply in 2025/26, but is reduced again from 2027 - at the same time, the leverage ratio falls to a very solid level by 2028.
All in all, ASE provides a picture of scaling growth, rising margins, decreasing risk and clearly improved return on investment (ROE of up to 25 %). For investors, this looks like a classic turnaround into structural growth.
(TWD in millions)
Market value 2,034,392
Number of shares (in thousands) 4,375,036
Date of publication 05,02,2026
Brief summary of the valuation ratios
In terms of valuation, ASE acts as a classic transitional value: expensive in the short term, fair in the medium term, cheap in the long term. The P/E ratio will remain high in 2025-2026 because earnings will only pick up with a delay. From 2027, the picture changes: earnings scale faster than the share price, causing the P/E ratio to fall significantly and the valuation to become more attractive.
The PEG curve is the strongest indicator: from 2026, it is stable in the 0.5-0.6 range - a level that normally indicates undervaluation with high growth growth. The dividend yield increases moderately, but remains more of a bonus than a core argument.
FCF yield turns positive from 2026 and improves strongly, further underpinning the valuation. Overall, ASE shows a profile that will turn into a structurally structurally favorable valuation valuation from 2027 onwards, while the operating performance increases significantly at the same time. For investors, this means Valuation and growth will start to move in the same direction from 2027 - a positive setup.
⭐ Overall score: 6.8 / 10
🎯 Realistic tenbagger probability: 10-15%
📌 Juan's conclusion
ASE is not a classic Tenbagger moonshotbut a solid compounderthat will enter a phase from 2027 in which:
This is a high-quality setupbut not explosive enough for a 10× story in 5-7 years.
A doubling to tripling is more likelynot a tenfold increase.
Performance
1 week +10.16 %
1 month +38.90
6 months +133.44 %
1 year +269.54 %
3 years +322.25 %
Ladies and gentlemen, the next correction should be coming. Figures will also be presented next week.
PRICE €25.50 (23.04.2026 at 07:52)
+ 5

Hello dear Getquin Community,
After $ORCL (-4,36%) Oracle caused quite a stir after the last quarterly figures and the market reacted extremely positively with a 40 percent increase in the share price, so much so that CEO Larry Ellison briefly became the richest person in the world overnight, I wanted to unravel the magic and find out exactly which division caused this tremor.
The answer is Cloud Infrastructure, or OCI for short. In this area, the demand for data centers for artificial intelligence has exploded, which has brought Oracle long-term orders worth 455 billion US dollars. However, it is not only Oracle that is benefiting, but also other hyperscalers, regional challengers and, above all, the so-called shovel manufacturers that provide the basic infrastructure.
I have taken the trouble to look for potential competitors and up-and-coming challengers so that you have a complete overview of this sector. I have divided the whole thing into the following segments: 🌍 Big players (hyperscalers), 💡 Hidden champions (selection by region), ⚒️ Shovel manufacturers (infrastructure suppliers) and, as always, my favorite.
If I have overlooked any important aspects or a classification was not entirely precise, I look forward to your comments and exciting additions. Together we can understand this topic even better and learn from each other.
Feel free to leave a 👍. I wish you every success with your investments 🚀
🌍 Big Player (Hyperscaler)
Amazon Web Services - $AMZN (-1,93%) (USA, Nasdaq) → World market leader with >30 % market share, huge data centers & own AI chips (Trainium, Inferentia)
Microsoft Azure - $MSFT (-1,82%) (USA, Nasdaq) → second largest provider, strong AI focus through OpenAI partnership
Google Cloud - $GOOGL (-2,33%) (USA, Nasdaq) → third largest provider, specialized in AI workloads & big data
Oracle Cloud Infrastructure (OCI) - $ORCL (-4,36%) (USA, NYSE) → Number 4 worldwide, currently fastest growth (+70-80 %), RPO USD 455 bn
Alibaba Cloud - $BABA (-2,12%) , $9988 (-2,02%) (China, NYSE/HKEX) → Market leader in Asia, complete cloud suite from IaaS to AI
Favorite: Oracle - $ORCL (-4,36%)
Oracle impresses with its cloud infrastructure OCI, which recently collected orders worth 455 billion US dollars. The moat lies in the close integration of the database business and cloud services as well as the multi-cloud partnerships with Microsoft and Google. The compounder property is the result of long-term contracts and economies of scale in data center construction.
Alternative favorite: Alibaba Cloud - $BABA (-2,12%) , $9988 (-2,02%)
Alibaba is number one in Asia and number four worldwide. The moat lies in the close integration with Alibaba's e-commerce and fintech ecosystem. The compounder property stems from the enormous growth in emerging markets and the increasing demand for cloud services in China. While the stock is valued significantly cheaper than Oracle, there are geopolitical and regulatory risks.
💡 Hidden champions (selection by region)
🇪🇺 Europe
OVHcloud - $OVH (-2,91%) PA (France) → largest European cloud provider, GDPR- and Gaia-X-focused
Scaleway - private (France, part of the Iliad Group) → Developer and AI cloud platform
T-Systems - part of $DTE (+0,98%) DE (Deutsche Telekom, Germany) → Hybrid & Sovereign Cloud for Public Sector
IONOS - $IOS (-2,05%) DE (Germany, Xetra)
Largest European web hosting and SME cloud provider. Burggraben: strong brand and high customer loyalty in the SME sector.
Aruba Cloud - private (Italy) → regionally strong in SMEs & hosting
Outscale - private (France, subsidiary of Dassault $DSY.PA) → Industrial Cloud & Simulation
Favorite: OVHcloud - $OVH (-2,91%)
Burggraben: strong position as a GDPR-compliant sovereign cloud with Gaia-X. Compounder: increasing trust from authorities and companies ensures growing recurring revenues.
🇨🇳 China
Baidu AI Cloud - part of $BIDU (-3,06%) , $9888 (-3,2%) (Nasdaq, China/USA) → AI workloads, autonomous driving, language models
JD Cloud - part of $JD (-1,74%) , $9618 (-1,23%) (Nasdaq, China/USA) → Cloud for e-commerce & retail
Kingsoft Cloud - $KC (-3,82%) , $3896 (-3,71%) (Nasdaq, China/USA) → Gaming, streaming and app cloud
China Telecom Cloud - part of $728 HK (HKEX) → Infrastructure cloud, state-supported
China Mobile Cloud - part of $941 HK (HKEX) → 5G edge cloud with telecom backbone
Favorite: Kingsoft Cloud - $KC (-3,82%) , $3896 (-3,71%)
Moat: Specializing in gaming, streaming and mobile apps with deep integrations into ecosystems. Compounder: benefits from China's growing online consumption and strong embedding in the Tencent environment.
🇯🇵 Japan
NTT Communications - part of $9432 (+0,51%) T (Tokyo) → Enterprise cloud with global network
NEC Cloud - $6701 (-0,65%) T (Tokyo) → Government & security solutions
Fujitsu Cloud K5 - $6702 (+1,55%) T (Tokyo) → Hybrid cloud for large companies
Rakuten Symphony Cloud - part of $4755 (+2,92%) T (Tokyo) → 5G & telecom cloud
IIJ Cloud - $3774 (-0,98%) T (Tokyo) → Cloud pioneer for enterprise IT
Favorite: NTT - $9432 (+0,51%)
Moat: global telecom backbone and huge enterprise customer base. Compounder: expansion of data centers in Asia and Europe with stable recurring revenues.
🇮🇳 India
Reliance Jio Cloud - part of $RELIANCE NS (NSE India) → Telecom Cloud, partnership with Azure
Tata Communications IZO - $TATACOMM NS (NSE India) → Hybrid cloud & global backbone
Infosys Cobalt - $INFY (NYSE/NSE India) → Cloud migration platform & consulting
HCLTech Cloud - $HCLTECH NS (NSE India) → AI-powered hybrid cloud
Wipro Cloud Studio - $WIPRO NS (NSE India) → MultiCloud service provider
Favorite: Tata Communications - $TATACOMM
Moat: global fiber optic network and deep networking in hybrid cloud. Compounder: growing international expansion and increasing demand for multi-cloud solutions.
🌏 Asia / Oceania
Naver Cloud - part of $035420 KQ (Korea KOSDAQ) → AI & gaming cloud
Samsung SDS Cloud - $018260 , $SMSN (-4,49%) KQ (Korea KOSDAQ) → Enterprise & IoT Cloud
KT Cloud - part of $030200 KQ (Korea KOSDAQ) → Telecom & Edge Cloud with 5G
Telstra Cloud - $TLS (-0,27%) AX (Australia) → Telecom Cloud, Asia-Pacific focus
Macquarie Telecom Cloud - $MAQ AX (Australia) → Public Sector & Compliance
Favorite: Naver Cloud - $035420
Moat: strong integration of AI and gaming in Korea. Compounder: rapid scaling due to growing demand for AI and ML applications.
🌍 Latin America
UOL Diveo (Compasso UOL) - private (Brazil) → Cloud + Managed Services
Tivit Cloud - private (Brazil) → MultiCloud for industry & banks
Locaweb Cloud - $LWSA3 SA (Brazil) → SME Hosting & Cloud
Claro Cloud - part of $AMX (+1,75%) (Mexico, NYSE/HKEX) → Telecom Cloud in Latin America
DesireCloud - private (Chile/Peru) → Local provider for companies
Favorite: Locaweb - $LWSA3
moat: Market leader for SME cloud and hosting in Brazil. Compounder: enormous scalability through the digitalization of small and medium-sized enterprises throughout Latin America.
🇨🇦 Canada
OVHcloud Canada - part of $OVH (-2,91%) PA (France) → Data centers for North America
SherWeb - private (Quebec) → Cloud and MSP services for SMEs
HostPapa - private (Canada) → SME cloud solutions
Canadian Web Hosting - private (Canada) → Cloud & hosting with a focus on data protection
Beanfield Cloud - private (Toronto) → Cloud combined with fiber optic infrastructure
Favorite: SherWeb - private
Moat: close ties to SMEs via managed services. Compounder: fast-growing cloud ecosystem for small businesses in North America, high customer loyalty.
⚒️ Blade manufacturers (infrastructure suppliers)
🖥️ Semiconductors & Chips
Nvidia - $NVDA (-1,52%) (USA, Nasdaq) → GPUs for AI training & cloud
AMD - $AMD (-5,46%) (USA, Nasdaq) → CPUs/GPUs for Data Center
Intel - $INTC (-5,89%) (USA, Nasdaq) → Server CPUs & AI accelerators (Gaudi)
TSMC - $TSM (-2,13%) (Taiwan, NYSE/TWSE) → largest chip manufacturer, produces for NVIDIA/AMD
Samsung Electronics - $SMSN (-4,49%) KQ (Korea) → Memory, foundry, GPUs/CPUs
Favorite: Nvidia - $NVDA (-1,52%)
Moat: near monopoly in high-end GPUs for AI. Compounder: Ecosystem and network effects through CUDA and developer community.
📦 Data center hardware & servers
Supermicro - $SMCI (-10,16%) (USA, Nasdaq) → GPU clusters & AI servers
Dell Technologies - $DELL (-4,44%) (USA, NYSE) → Enterprise Servers & Storage
Hewlett Packard Enterprise - $HPE (-5,68%) (USA, NYSE) → Hybrid Cloud & Edge
Inspur - private (China) → AI & Cloud Server
Lenovo - $LNVGY (+2,47%) (China/ADR) → HPC and AI servers
Favorite: Supermicro - $SMCI (-10,16%)
Moat: Specialization in GPU clusters and AI servers. Compounder: benefits from every expansion of the hyperscalers, extremely high scalability.
⚡ Memory & network chips
Micron - $MU (-5,27%) (USA, Nasdaq) → DRAM & HBM memory
SK Hynix - $HY9H (-7,21%) KQ (Korea) → Memory chips, HBM for NVIDIA
Broadcom - $AVGO (-4,04%) (USA, Nasdaq) → Network Chips & Switches
Marvell - $MRVL (-5,33%) (USA, Nasdaq) → Network & 5G chips
ASE Technology - $ASX (-6,4%) (Taiwan, NYSE) → Packaging for high-end chips
Favorite: Broadcom - $AVGO (-4,04%)
Moat: deep roots in network infrastructure of hyperscalers. Compounder: benefits from rising demand for switches and custom chips for the cloud.
🏭 Data centers / colocation
Equinix - $EQIX (-1,82%) (USA, Nasdaq) → largest colocation provider worldwide
Digital Realty - $DLR (+0,69%) (USA, NYSE) → Data centers worldwide, strong in Europe/USA
China Telecom DC - part of $728 HK (HKEX) → Data center infrastructure in China
NTT Data Centers - part of $9432 (+0,51%) T (Tokyo) → Data centers in Asia/Europe
NEXTDC - $NXT (+1,81%) AX (Australia) → Growing data centers in the APAC region
Favorite: Equinix - $EQIX (-1,82%)
Moat: global networking and extremely high switching costs for customers. Compounder: continuous expansion and cross-selling potential through platform structure.
🔋 Energy & cooling
Schneider Electric - $SU (-3,1%) PA (France, Euronext) → Power & Cooling for Data Center
ABB - $ABBN (-1,67%) (Switzerland, SIX/NYSE ADR) → Energy & Automation
Siemens Energy - $ENR (-0,89%) (Germany, Xetra) → Power Grids & Data Center Technology
Vertiv - $VRT (-3,68%) (USA, NYSE) → Cooling, Racks & UPSs
Eaton - $ETN (-3,4%) (Ireland/USA, NYSE) → Power Management
Favorite: Schneider Electric - $SU (-3,1%)
Burggraben: market-leading energy and cooling systems for data centers. Compounder: long-term growth due to increasing demand for efficient data centers.
🌐 Network & Connectivity
Cisco - $CSCO (-2,13%) (USA, Nasdaq) → Router & Network Hardware
Arista Networks - $ANET (-4,87%) (USA, NYSE) → High-speed switches for hyperscalers
Juniper Networks - Acquisition by $HPE (-5,68%) Hewlett Packard HP (USA, NYSE) → Routing & Network Security
Ciena - $CIEN (-6,31%) (USA, NYSE) → Fiber Optics & Optical Networks
Nokia - $NOK (-4,69%) (Finland, NYSE/Helsinki) → 5G & Core Networks
Favorite: Arista Networks - $ANET (-4,87%)
Moat: technological leadership in high-speed switches in hyperscaler data centers. Compounder: enormous growth opportunities due to exponential data traffic in AI workloads.
✨ Takeaway
The Oracle quake shows: Cloud & AI are the growth drivers of the coming years. While hyperscalers are in the spotlight, hidden champions are growing in their niches in the background and blade manufacturers are making money from every expansion of the infrastructure.
👉 Question for you: Do you prefer to focus on hyperscalers in your strategy? hyperscalersthe hidden champions or directly on the shovel manufacturers?
I look forward to your opinions!
Source: own analysis
Image - Image credit: Getty Images