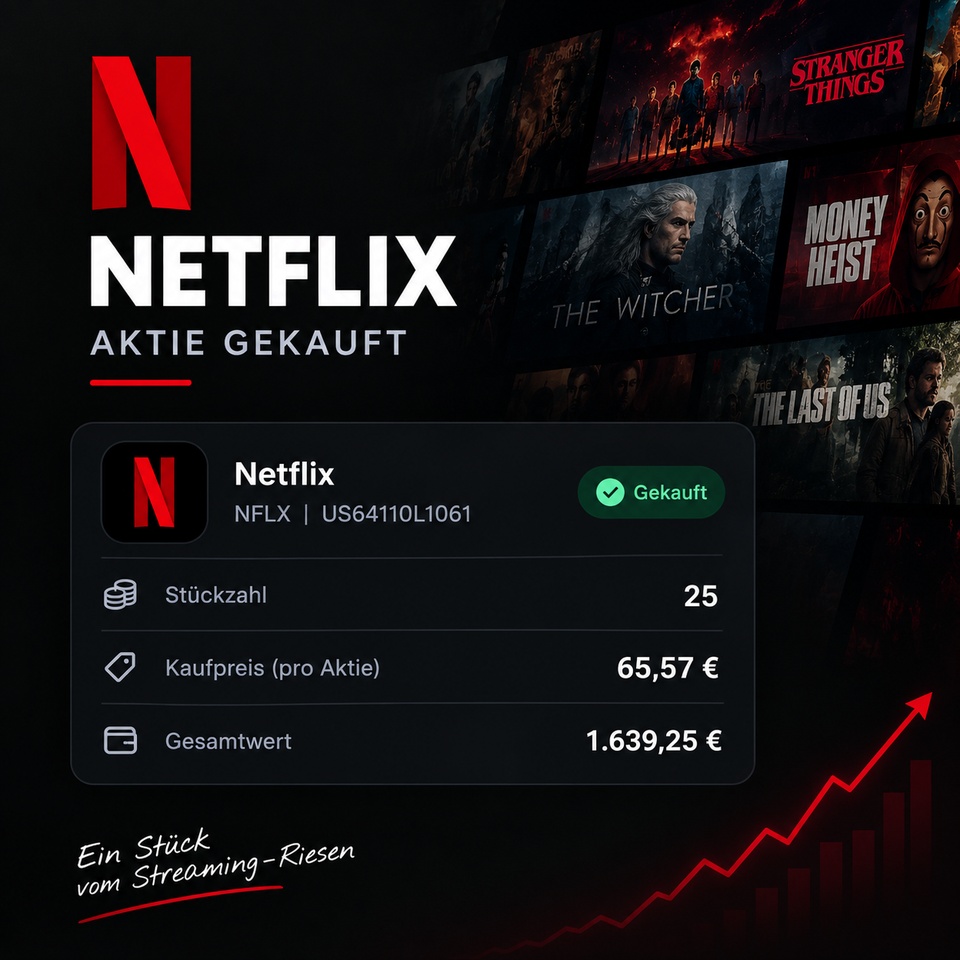
Entry targets got hit for $NFLX (-0,94 %) and $GRAB (+0,45 %)
And so: 200K+ portfolio is here. 🥳
Puestos
364Entry targets got hit for $NFLX (-0,94 %) and $GRAB (+0,45 %)
And so: 200K+ portfolio is here. 🥳
⠀
The key takeaway: More than 20 analyst firms have revised their estimates or lowered their price targets following Q3. Many remain bullish due to the valuation, but the key question now is whether Netflix can accelerate user engagement, ad revenue, and overall growth again by 2027.
⠀
Average price target: $86
Upside potential from the current price of $65.66: ~31%
⠀
Current analyst ratings:
• BMO: Outperform, $125 (unchanged) (+90%)
• Canaccord: Buy, $110 (down from $125) (+68%)
• UBS: Buy, $100 (down from $115) (+52%)
• TD Cowen: Buy, $100 (unchanged) (+52%)
• BofA: Buy, $90 (down from $105) (+37%)
• Evercore ISI: Outperform, $90 (down from $110) (+37%)
• Citi: Buy, $85 from $100 (+29%)
• KeyBanc: Overweight, $85 (unchanged) (+29%)
• JPMorgan: Overweight, $81 from $85 (+23%)
• Bernstein: Outperform, $80 from $95 (+22%)
• Oppenheimer: Outperform, $80 from $85 (+22%)
• Guggenheim: Buy, $78 from $80 (+19%)
• Piper Sandler: Overweight, $78 from $85 (+19%)
• Morgan Stanley: Overweight, $77 from $80 (+17%)
• Rosenblatt: Neutral, $71 from $75 (+8%)
• Barclays: Equal Weight, $65 from $70 (-1%)
• Pivotal Research: Hold, $65 from $70 (-1%)
• Needham: Downgraded to Hold from Buy
⠀
What analysts continue to view positively:
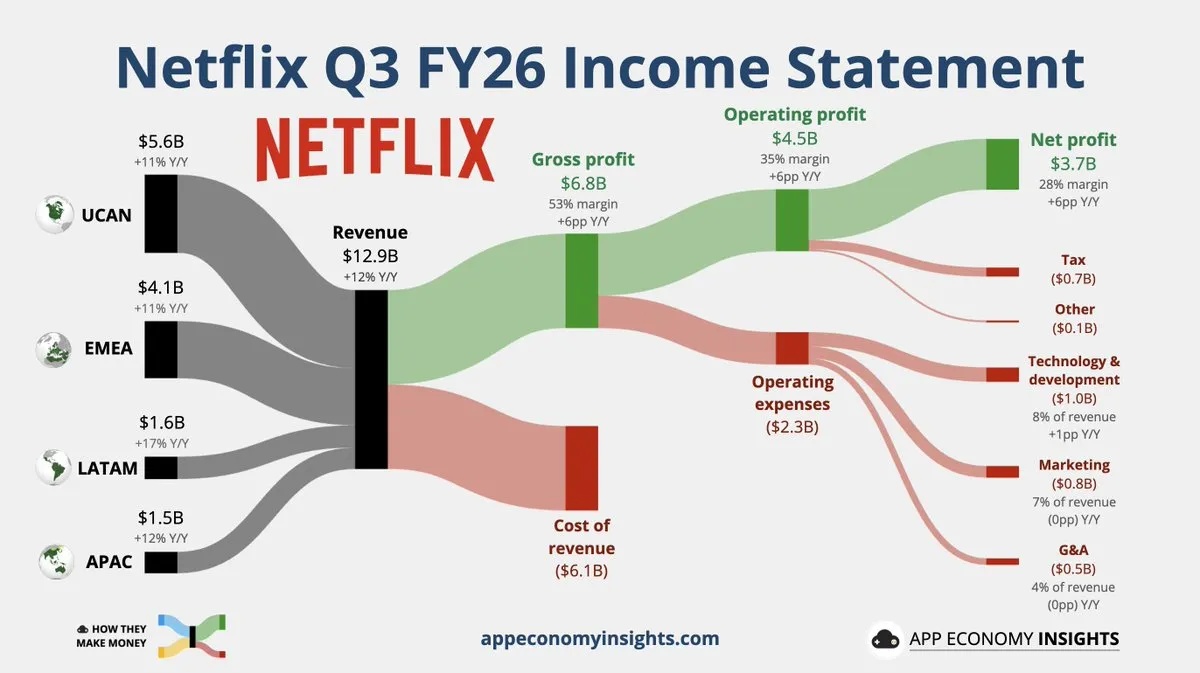
• Q3 revenue of $12.87 billion, approximately 12% year-over-year growth and in line with expectations
• Operating income of approximately $4.46 billion, above consensus
• UCAN revenue growth improved despite weaker engagement
• Customer retention remains robust; the churn rate improved year-over-year globally and in the U.S.
• The traditional subscription business performed better than previously expected
⠀
Why analysts are lowering their price targets:
• Revenue growth slowed to about 11% ex-FX, the lowest rate in nearly three years
• Q4 revenue guidance of $13.44 billion fell short of the consensus of ~$13.52 billion
• Q4 guidance for operating income of ~$3.50 billion fell short of the expected ~$3.73 billion
• The advertising revenue forecast for 2026 was lowered from around $3.0 billion to ~$2.7 billion
• Management itself acknowledges the need for improvement in U.S. content
• YouTube, TikTok, and other free platforms are intensifying competition for users’ attention
⠀
The biggest problem: Advertising was supposed to become one of Netflix’s next major growth drivers. Instead, product and integration delays are slowing monetization. Guggenheim lowered its 2027 advertising revenue forecast to $4.0 billion from $5.2 billion
⠀
The content reset: Netflix has replaced its Chief Content Officer, reshuffled leadership in film and TV, and cut about 6% of its workforce. Analysts increasingly view this as an admission that the U.S. content pipeline needs higher hit rates and more truly must-watch content.
⠀
The Bull Case: The subscription business is more stable than the stock price reaction suggests. Retention remains strong, price increases are working, the balance sheet is solid, and several analysts view the weakness in advertising revenue as a temporary setback rather than a structural problem.
⠀
Conclusion: For Netflix, it’s no longer about size, but about growth. Investors want to see better content reignite engagement and advertising finally become the second major growth engine. Until then, a more favorable valuation alone is unlikely to be enough for a sustainable revaluation.
Here's the latest report from Netflix $NFLX (-0,94 %)
(NASDAQ: NFLX) Q3 2026 Earnings Release, right after the U.S. stock market closed:
🚀 Solid top line—but growth is slowing
Netflix met revenue expectations point by point in the third quarter of 2026:
Revenue:
$12.87 billion → +11.8% YoY
(Expected: ~$12.87 billion)
Revenue momentum: Double-digit growth is on track, but remains well below previous peaks during the re-acceleration phase.
Ad Tier & Advertising Revenue: The advertising business is growing strongly and is on track to reach the annual target of approximately $3.0 billion , but still accounts for a comparatively small portion of total revenue.
The bottom line: Netflix is delivering consistently, but the momentum from the previous “password-sharing crackdown” is no longer a fresh driver of the stock price.
💰 Profit machine significantly beats expectations
On the bottom line, there was a strong beat for Q3:
EPS (diluted):
$0.87 → Beat!
(Expected: $0.82)
Operating Income:
$4.46 billion (+37% YoY)
Operating Margin: As strong as ever, driven by strict cost discipline and the recent job cuts in the product/tech division.
This shows that, from an operational standpoint, the streaming giant is extremely profitable and continues to push its margin higher.
⚠️ The catch & reason for the after-hours dip (~ -5%): Guidance & Outlook
Although Q3 was strong on the earnings front, the market is slightly punishing the stock in after-hours trading:
Revenue outlook (Q4 / outlook): The forecast for the coming quarter was slightly below Wall Street’s most optimistic whisper estimates.
Monetization vs. Content Costs: Investors are increasingly questioning how much organic user growth remains and how much of future growth will have to be squeezed purely from further price increases.
🧠 Ad-Supported Subscriptions & Live Content as the Next Phase
Netflix is trying to shift its focus entirely from pure subscriber numbers to engagement and ad revenue:
Programmatic & Pause Ads: Advertising partners are booking more heavily.
Live Events & Sports: The further development of live streams (WWE, NFL games) is the next planned lever to guarantee high reach for advertisers and minimize churn.
⚡💡 The Bottom Line
Netflix has finally evolved from a pure growth driver into a highly efficient cash machine.
$12.87 billion in revenue (+11.8% YoY).
$0.87 EPS (vs. $0.82 expected).
Operating income +37%.
Fundamentals: Strong margins & cash flow, but top-line growth is slowing.
Competitive Advantage: Undisputed No. 1 in the global streaming market.
Operating Leverage: Remains excellent.
Valuation/Guidance: The outlook is dampening short-term euphoria.
Rating for the earnings report: 🟡⚡ “SOLID BEAT ON MARGINS, BUT A SLIGHT DAMPENER ON GUIDANCE.”

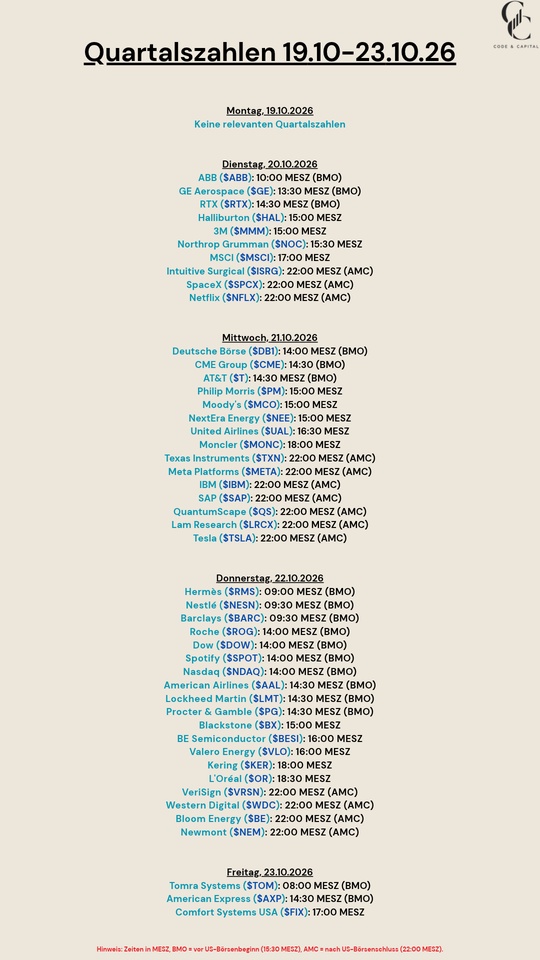
Monday, October 19, 2026
🇨🇳 4:00 a.m. | GDP (Q3), Industrial Production & Retail Sales
🇺🇸 4:00 p.m. | NAHB Housing Market Index
Tuesday, October 20, 2026
🇨🇳 3:00 a.m. | Central Bank Interest Rate Decision (LPR)
🇪🇺 11:00 a.m. | ZEW Economic Sentiment Index
🇺🇸 2:30 p.m. | Building Permits & Housing Starts
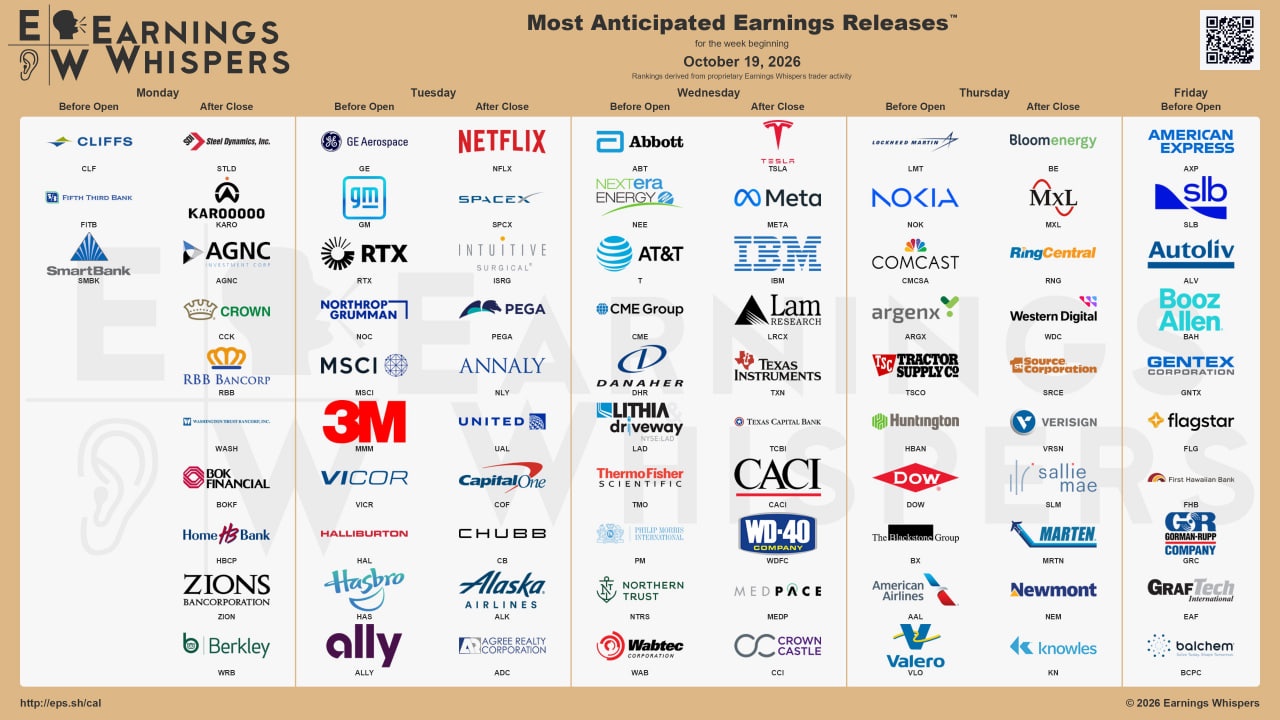
🍿 10:00 p.m. | Netflix & SpaceX (Q3 Earnings)
Wednesday, October 21, 2026
🇬🇧 8:00 a.m. | Consumer Prices / Inflation Rate (Sep)
🇺🇸 4:30 p.m. | EIA Crude Oil Inventory Report
🚘 10:00 p.m. | Tesla & IBM (Q3 Earnings)
Thursday, October 22, 2026
✈️ 2:30 p.m. | American Airlines (Q3 earnings)
🇺🇸 2:30 p.m. | Initial Jobless Claims
🇪🇺 4:00 p.m. | Eurozone Consumer Confidence (preliminary)
Friday, October 23, 2026
🇯🇵 1:30 a.m. | Core inflation / Consumer prices (Sep)
🇩🇪 9:30 a.m. | S&P Global Purchasing Managers’ Index (PMI) for Manufacturing & Services (Preliminary)
🇪🇺 10:00 a.m. | S&P Global Purchasing Managers’ Index (PMI) for the Eurozone (preliminary)
🇺🇸 3:45 p.m. | S&P Global Purchasing Managers’ Index (PMI) U.S. (Preliminary)
🇫🇷 After market close | Moody’s rating review for France
$NFLX (-0,94 %)
$AAL (-0,36 %)
$IBM (-0,41 %)
$TSLA (-1,74 %)
$AXP (+1,31 %)
$RTX (+1,32 %)
$BE (+1,12 %)
$LMT (+0,71 %)
$NOKIA (+1,29 %)
$ABT (-0,01 %)
$NEE (-1,04 %)
$CME (+0,58 %)
$T (-1,06 %)
$GM (+1,63 %)
$MSCI (+0,26 %)
$TMO (+1,31 %)$CMCSA (-0,96 %)
$ABBN (+2,15 %)
$GE
$RTX (+1,32 %)
$HAL (+0,63 %)
$MMM (+0,71 %)
$NOC (+0,53 %)
$MSCI (+0,26 %)
$ISRG (-0,41 %)
$SPCX (-3,43 %)
$NFLX (-0,94 %)
$DB1 (+0,3 %)
$CME (+0,58 %)
$T (-1,06 %)
$PM (+0,79 %)
$MCO (+0,47 %)
$NEE (-1,04 %)
$UAL (-1,28 %)
$MONC (+0,7 %)
$TXN (+0,28 %)
$META (-0,39 %)
$IBM (-0,41 %)
$SAP (-4 %)
$QS (-0,27 %)
$LRCX (+4,02 %)
$TSLA (-1,74 %)
$RMS (-1,62 %)
$NESN (-0,65 %)
$BARC (+1,32 %)
$ROP (-0,64 %)
$DOW (+0,99 %)
$SPOT (-3,11 %)
$NDAQ (+1,07 %)
$AAL (-0,36 %)
$LMT (+0,71 %)
$PG (+0,15 %)
$BX (-0,02 %)
$BESI (-1,51 %)
$VLO (+0,26 %)
$KER (-1,59 %)
$OR (-1,47 %)
$VRSN (+0,75 %)
$WDC (+3,97 %)
$BE (+1,12 %)
$NEM (+0,75 %)
$TOM (-1,28 %)
$AXP (+1,31 %)
$FIX (+3,71 %)
Out
$NOVO B (-1,98 %) -35% off the fry stand
In (additional purchases, no new purchases)
$MCD (+0,51 %) 15x
$NFLX (-0,94 %) 100x
I’m also planning a small savings plan project. I’ll share that later :)

That’s $NFLX (-0,94 %) is the result of them annoying us with ads and raising subscription prices.
Since I’ve bought in now, the price will of course drop soon, just like with $SYK (+1,09 %) 🤪 but that’s no problem, because you guys in the GQ community wanted even better prices—you’re welcome! 📥💸

I've started building a position in Netflix ($NFLX (-0,94 %) ) position at the current levels, but I plan to increase it to 80 shares.
I’m very bullish on the company, and fundamentally everything looks great—I think we’ll see new all-time highs in the coming years.