
A little more Europe can't hurt 😬
That's why I decided to $TSTL (+0,88 %) , but $NOVO B (+1,09 %) I kicked it out of my portfolio a few months ago 🤔
Puestos
4A little more Europe can't hurt 😬
That's why I decided to $TSTL (+0,88 %) , but $NOVO B (+1,09 %) I kicked it out of my portfolio a few months ago 🤔
Die Tristel plc $TSTL (+0,88 %) gab am Montag die kommerzielle Einführung von 3T Pro bekannt, einer kostenpflichtigen Premium-Version ihrer digitalen Compliance-Plattform. Damit führt das Unternehmen erstmals ein Abonnementmodell für die Software ein.
Der Hersteller von Produkten zur Infektionsprävention teilte in einer Pressemitteilung mit, dass 3T Pro einen strategischen Schritt zur Erschließung wiederkehrender digitaler Umsatzquellen darstellt, die das Kernproduktportfolio ergänzen sollen.
Bislang stand die 3T-Plattform Gesundheitsdienstleistern als kostenloses Tool zur Verfügung, um in Verbindung mit den Desinfektionsprodukten von Tristel Mitarbeiterschulungen zu verwalten und die Compliance nachzuverfolgen. Die Plattform wird von einem unternehmenseigenen Softwareteam entwickelt und gewartet.
Mit der Einführung formalisiert Tristel eine dreistufige Produktstruktur. Die Basisversion bleibt kostenlos und deckt die Kernfunktionen für Schulungen und Compliance ab. Eine mittlere Stufe kombiniert das Schulungsmanagement mit der Rückverfolgbarkeit von Geräten. Die Premium-Version 3T Pro bietet erweiterte Anpassungsmöglichkeiten, Workflows, Reporting-Funktionen sowie Kapazitäten zur Audit-Vorbereitung.
Das Unternehmen kündigte an, bestehenden Nutzern der Rückverfolgungsfunktionen Übergangsregelungen bei der Lizenzierung anzubieten. Kunden, die auf 3T Pro upgraden, erhalten Zugang zu den erweiterten Funktionalitäten zu den üblichen Geschäftsbedingungen.
Zu den Funktionen von 3T Pro gehören eine verbesserte Nachverfolgung von Geräten (Asset Tracking) und deren Lifecycle-Management, Dashboards, ein strukturiertes Audit-Reporting sowie eine Datenarchitektur, die für zukünftige Integrationen ausgelegt ist.
„Die Einführung von 3T Pro ist ein wichtiger Meilenstein für das Geschäft“, sagte Matt Fulford, Group Digital Director bei Tristel. „3T hat sich bei unserem Kundenstamm als zuverlässiges Compliance-Tool etabliert, und wir sind nun in der Lage, eine Premium-Version anzubieten, die der Reife der Plattform und den steigenden Anforderungen an Gesundheitsdienstleister gerecht wird.“
Das Unternehmen betonte, dass die Basisversion weiterhin kostenlos bleiben werde, um die Zugänglichkeit und Akzeptanz im gesamten Gesundheitssektor zu fördern.
Hier ist etwas, das Sie vielleicht interessieren könnte: - https://de.investing.com/news/company-news/tristel-fuhrt-kostenpflichtiges-premiumabonnement-fur-complianceplattform-3t-ein-93CH-3579999
Hello dear community,
Despite the sunshine 🌞 you still have to take care of your health somehow. In keeping with this, I would like to introduce you to a title from the health sector today.
Today it's all about Tristel $TSTL (+0,88 %)
1. the business model: the "razor blade" model of medicine
Tristel $TSTL (+0,88 %) has a worldwide monopoly on a patented disinfection chemistry based on chlorine dioxide (ClO_2). They clean medical instruments (such as ultrasound probes or endoscopes) that cannot be heat-sterilized.
Tristel $TSTL (+0,88 %) does not operate as a traditional cleaning manufacturer, but as an undisputed niche monopolist for high-level disinfection in hospitals. With its patented chlorine dioxide technology (ClO_2), the company controls clinical workflows in the reprocessing of endoscopes and ultrasound probes. Following the extremely profitable "razor and blades" model, regulatory requirements force hospitals to continuously repurchase the proprietary foams and wipes - before and after every single patient treatment.
The trick: They make their money not on the one-time hardware, but on the consumables (wipes, foams, rinses). Hospitals are hooked on the needle: every single examination generates recurring revenue. Once in the system, nobody changes.
FDA validation: The most recent accolade was the official US approval by the FDA for its core product Tristel ULT. This opens up the largest and most lucrative healthcare market in the world via the US sales giant Parker Laboratories.
2. the numbers: Financial muscleman
Margins from another world: With a gross margin of over 80% and a massive pre-tax profit expansion (+41% in the last six months), Tristel operates at the level of elite software companies - only with physical chemistry.
Cash flow & return on investment: They are brutally efficient at converting profits into cash (FCF margin of 21,4%) and achieve a physical ROIC of 25,8%. This is the absolute Champions League of capital efficiency.
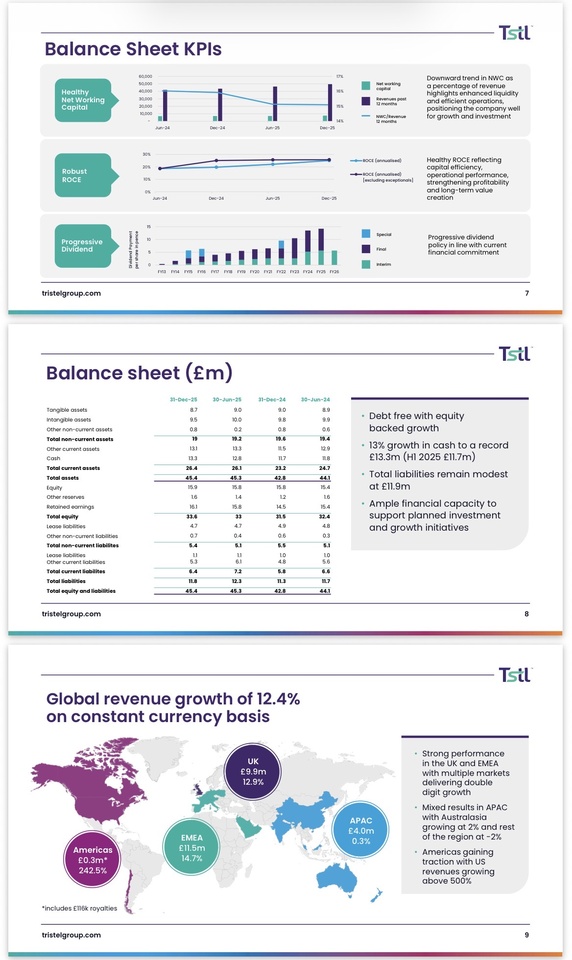
Balance sheet from Titan: Tristel $TSTL (+0,88 %) is completely debt-free and is sitting on a comfortable cash cushion of over GBP 11 million. The entire US growth is financed organically from cash flow - zero dilution risk for you.
3. 🚀 Why the share is exciting now
-Mispricing due to wrong label: The market often values Tristel $TSTL (+0,88 %) superficially like a classic, boring chemical or industrial producer and stares in shock at the visually high P/E ratio of ~25x. In reality, it is a medtech SaaS equivalent with a subscription character.
-The US catalyst: The market is underestimating the leverage of FDA approval. The cost of approval is historic, the operating leverage is now in full effect. Every new bottle of chemical that goes over the counter in the USA goes almost one-to-one into net profit.
-Regulatory tailwind: Health authorities around the world are tightening guidelines for the disinfection of medical devices. Hospitals are structurally forced to upgrade from cheap alcohol to Tristel's high-level process.
-Resistant to the economy: Hospitals must disinfect. Regardless of inflation, recession or geopolitical crises - the volume of examinations remains stable.
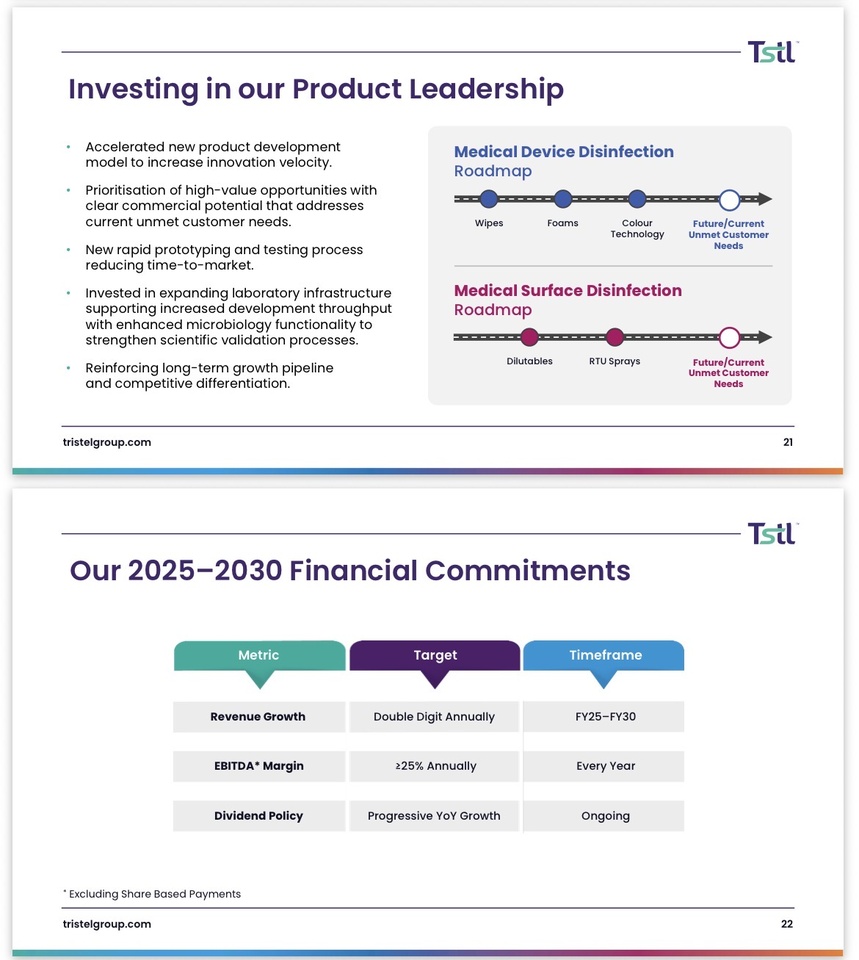
-Financial commitments 2025-2030: Management officially commits: Sustained double-digit sales growth per year and an EBITDA margin of ≥25% in every single year by FY30.
-Digital toll (3T platform & CLOì): Tristel $TSTL (+0,88 %) invests massively in digitalization. The wipe system is being expanded into a multi-tier SaaS platform that generates recurring software revenue and drives switching costs for clinics to infinity. An internal AI agent (CLOì) also speeds up internal regulatory processes.
4.⚠️ Valuation & risks
-Premium price: Quality has its price. With a forward P/E ratio of over 25x, the company is permanently expensive and does not forgive any operational disappointments in the US rollout.
-Bureaucracy brake: Success stands or falls on the speed of clinical adoption in the US. If American hospitals are slower to change over than expected, the growth story will be delayed.
-Chemical cluster risk: If there is ever any proven chemical damage to the extremely expensive ultrasound machines from the major manufacturers (GE, Philips, etc.), the story will falter. (So far unfounded, as the top manufacturers have officially released Tristel).
5.my personal conclusion + Reaper Bonus 💀
Tristel $TSTL (+0,88 %) is not a short-term hopeful bet for me like many overvalued hype stocks, but rather a rare quality stock with real substance. While other companies are still living on visions, Tristel is already delivering high margins, strong cash flows and an extremely robust business model and, in my view, the decisive factor: a profitable niche leader with a quasi-monopoly position, recurring revenues and enormous scaling potential.
BONUS MATERIAL 😂
Jack's conclusion:
Honestly? Tristel is exactly the band-aid you need if you're fed up with unprofitable hype shops that only live off shiny PowerPoint slides. Here you have a highly profitable, debt-free fortress with a gross margin of over 80% that earns its money in real life. Those who stare superficially at the supposedly high P/E ratio simply don't understand how rare real niche monopolies are.
The US expansion is no longer a hopeful bet, the engine is now clearly firing. If you fancy recurring sales, a cash fortress and software margins in a medical guise, then the situation is crystal clear: collect the shares, switch off the price ticker and put your feet up and relax.
Reaper rating: BUY ✅
Reaper Score: 7,5/10
@Get_Rich_or_Die_Tryin
@schlimmschlimm
@Tenbagger2024
@Multibagger
@Raketentoni and of course all other ✌️
+ 3

Small addendum: I opened a small new modest position on Friday at $TSTL (+0,88 %) will be gradually increased further 👀. Unfortunately, that was all I could do 🥲
Otherwise, I wish you a good start to the new week. May the yield be with you 📈🚀
That's it from me for now ✌️
Hello dear community,
Despite the sunshine 🌞 you still have to take care of your health somehow. In keeping with this, I would like to introduce you to a title from the health sector today.
Today it's all about Tristel $TSTL (+0,88 %)
1. the business model: the "razor blade" model of medicine
Tristel $TSTL (+0,88 %) has a worldwide monopoly on a patented disinfection chemistry based on chlorine dioxide (ClO_2). They clean medical instruments (such as ultrasound probes or endoscopes) that cannot be heat-sterilized.
Tristel $TSTL (+0,88 %) does not operate as a traditional cleaning manufacturer, but as an undisputed niche monopolist for high-level disinfection in hospitals. With its patented chlorine dioxide technology (ClO_2), the company controls clinical workflows in the reprocessing of endoscopes and ultrasound probes. Following the extremely profitable "razor and blades" model, regulatory requirements force hospitals to continuously repurchase the proprietary foams and wipes - before and after every single patient treatment.
The trick: They make their money not on the one-time hardware, but on the consumables (wipes, foams, rinses). Hospitals are hooked on the needle: every single examination generates recurring revenue. Once in the system, nobody changes.
FDA validation: The most recent accolade was the official US approval by the FDA for its core product Tristel ULT. This opens up the largest and most lucrative healthcare market in the world via the US sales giant Parker Laboratories.
2. the numbers: Financial muscleman
Margins from another world: With a gross margin of over 80% and a massive pre-tax profit expansion (+41% in the last six months), Tristel operates at the level of elite software companies - only with physical chemistry.
Cash flow & return on investment: They are brutally efficient at converting profits into cash (FCF margin of 21,4%) and achieve a physical ROIC of 25,8%. This is the absolute Champions League of capital efficiency.
Balance sheet from Titan: Tristel $TSTL (+0,88 %) is completely debt-free and is sitting on a comfortable cash cushion of over GBP 11 million. The entire US growth is financed organically from cash flow - zero dilution risk for you.
3. 🚀 Why the share is exciting now
-Mispricing due to wrong label: The market often values Tristel $TSTL (+0,88 %) superficially like a classic, boring chemical or industrial producer and stares in shock at the visually high P/E ratio of ~25x. In reality, it is a medtech SaaS equivalent with a subscription character.
-The US catalyst: The market is underestimating the leverage of FDA approval. The cost of approval is historic, the operating leverage is now in full effect. Every new bottle of chemical that goes over the counter in the USA goes almost one-to-one into net profit.
-Regulatory tailwind: Health authorities around the world are tightening guidelines for the disinfection of medical devices. Hospitals are structurally forced to upgrade from cheap alcohol to Tristel's high-level process.
-Resistant to the economy: Hospitals must disinfect. Regardless of inflation, recession or geopolitical crises - the volume of examinations remains stable.
-Financial commitments 2025-2030: Management officially commits: Sustained double-digit sales growth per year and an EBITDA margin of ≥25% in every single year by FY30.
-Digital toll (3T platform & CLOì): Tristel $TSTL (+0,88 %) invests massively in digitalization. The wipe system is being expanded into a multi-tier SaaS platform that generates recurring software revenue and drives switching costs for clinics to infinity. An internal AI agent (CLOì) also speeds up internal regulatory processes.
4.⚠️ Valuation & risks
-Premium price: Quality has its price. With a forward P/E ratio of over 25x, the company is permanently expensive and does not forgive any operational disappointments in the US rollout.
-Bureaucracy brake: Success stands or falls on the speed of clinical adoption in the US. If American hospitals are slower to change over than expected, the growth story will be delayed.
-Chemical cluster risk: If there is ever any proven chemical damage to the extremely expensive ultrasound machines from the major manufacturers (GE, Philips, etc.), the story will falter. (So far unfounded, as the top manufacturers have officially released Tristel).
5.my personal conclusion + Reaper Bonus 💀
Tristel $TSTL (+0,88 %) is not a short-term hopeful bet for me like many overvalued hype stocks, but rather a rare quality stock with real substance. While other companies are still living on visions, Tristel is already delivering high margins, strong cash flows and an extremely robust business model and, in my view, the decisive factor: a profitable niche leader with a quasi-monopoly position, recurring revenues and enormous scaling potential.
BONUS MATERIAL 😂
Jack's conclusion:
Honestly? Tristel is exactly the band-aid you need if you're fed up with unprofitable hype shops that only live off shiny PowerPoint slides. Here you have a highly profitable, debt-free fortress with a gross margin of over 80% that earns its money in real life. Those who stare superficially at the supposedly high P/E ratio simply don't understand how rare real niche monopolies are.
The US expansion is no longer a hopeful bet, the engine is now clearly firing. If you fancy recurring sales, a cash fortress and software margins in a medical guise, then the situation is crystal clear: collect the shares, switch off the price ticker and put your feet up and relax.
Reaper rating: BUY ✅
Reaper Score: 7,5/10
@Get_Rich_or_Die_Tryin
@schlimmschlimm
@Tenbagger2024
@Multibagger
@Raketentoni and of course all other ✌️
+ 3


