

Hi there, community! 🚀
As part of our latest search for undiscovered gems in the broader AI and energy ecosystem—because, as we all know, without massive energy storage systems (BESS), nothing will work in the extremely energy-hungry AI data centers of the future—we stumbled upon a pretty hot lead.
We first learned about the company through a recent press release on Investing, which covered a massive $200 million deal (a letter of intent). The link and more details are coming up later in the text.
And there was something else: We had promised our dear @Multibagger here in the group that we’d keep our eyes open for a speculative high-risk/high-reward candidate that really packs a punch and fits his type perfectly. Dear Multibagger, we really hope we’ve hit your sweet spot and that this stock delivers exactly the dose of thrills you’re looking for! 😉
While the solid cash cows on one side of our portfolio are quietly churning out their dividends, today I’ve brought something hot for the speculative side of things. A stock that hardly anyone has on their radar yet:
NeoVolta Inc. (NASDAQ: NEOV) $NEOV (+0%)
This isn’t a safe bet—it’s a full-blown gamble on the boom in battery storage systems and massive U.S. subsidies.
1. What the Company Does
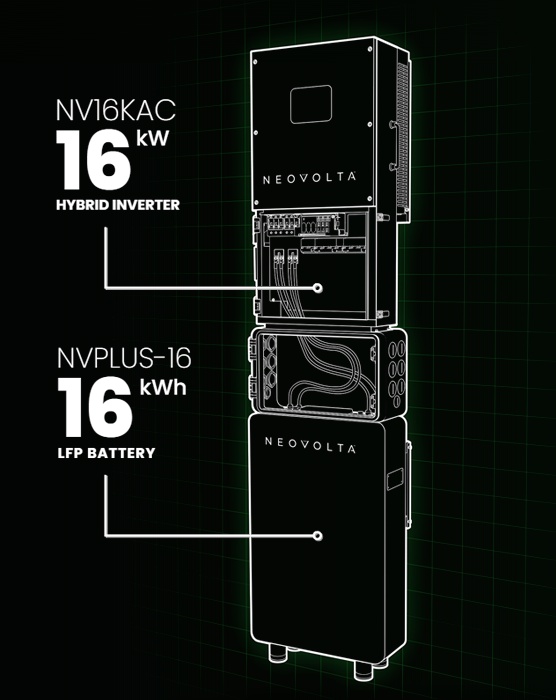
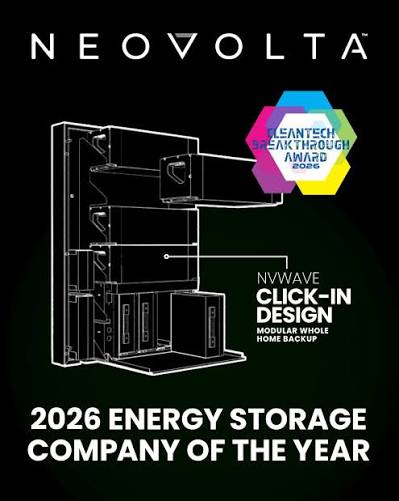
NeoVolta builds scalable battery energy storage systems (BESS) for residential and commercial use, and in the future, at the power-plant scale as well. The company is currently undergoing a massive transformation: it’s evolving from a provider of home storage solutions into a vertically integrated energy platform. At the very heart of this is a new factory in Pendergrass, Georgia, 80% of which is owned by the company.
2. Current Key Figures & Facts
- Market Capitalization: approx. $116.4 million (micro-cap!).
- Current share price: approx. $2.12.
- Revenue (Last 12 Months - LTM): $18.1 million.
- Net income (LTM): -11.5 million USD.
- Cash position: $11.5 million (more cash than debt on the balance sheet).
3. Core Quality Formula (Revenue Growth + Margin)
Our target score for solid investments is > 25.
- Revenue Growth: NeoVolta is experiencing explosive growth. In the first 9 months of the fiscal year, revenue rose by approximately 262% year-over-year to 13.3 million USD.
- Operating Margin: This is where the bloodbath begins. Operating profit (LTM) stands at -$9.4 million. With revenue of $18.1 million, this corresponds to an operating margin of approximately -51.9%.
- Score: The 25 threshold is formally exceeded by a wide margin, but only because of the absurd revenue leverage. Operationally, the company is burning through massive amounts of cash.
4. Cash Flow Quality Formula
- Operating Cash Flow (LTM): -9.1 million USD.
- Free Cash Flow (FCF) Yield: Stands at a dramatic -9.08%. The company is a pure cash burner that needs the funds to get the new factory up and running.
5. Dividend Filter (Income-Core)
A very quick check: 0%. NeoVolta doesn’t pay out a single cent; it’s a pure growth stock.
6. Exclusion Rule Check
Actually, our ironclad rule applies here without exception: Operating margin consistently < 5%, company with no clear path to immediate profitability.
Why are we looking at this stock anyway? Because this is a deliberately isolated gamble for the highly speculative portion of the portfolio, where the focus right now is solely on future orders and the company’s narrative.
7. Future and Industry Outlook
This is where the real potential lies: NeoVolta has received the coveted “FEOC compliance opinion” for its Georgia plant. This qualifies it as one of the few U.S. providers eligible for massive tax credits (IRS Sections 45X and 48E).
There is already a letter of intent for $200 million. If they scale production from 2 GWh to 8 GWh, we’re talking about a theoretical revenue capacity of around $400 million.
8. Competition
The market is a veritable shark tank. $NEOV (+0%) It faces direct competition from giant, well-capitalized players such as $TSLA (+4,51%) and $GNRC (+1,81%) , which have long-established, global distribution channels.
9. Analyst Forecasts
Analysts are going completely crazy: Needham recently initiated coverage of NeoVolta with a price target of $8.00, Lake Street is even calling for $11.00.
The analysts’ bullish scenario anticipates a jump in revenue from ~$14 million (FY26) to a staggering ~$657 million in FY28.
10. Chart Analysis of the Last Few Months
The chart is a shambles over a 1-year period: a plunge of a whopping -51.6%. The 52-week low was $1.36, and the high was $7.13.
However, the short-term trend over the past few weeks shows extreme price swings (high volatility with a negative beta of -0.57) due to positive news about the factory in Georgia.
11. Bargain Hunter List (Entry Zones)
The price is currently fluctuating between $2.12 and $2.30. There is no fundamental bargain threshold for this speculative trade.
Anyone entering this trade must operate with a strictly limited stake and must absolutely set a strict stop-loss at approximately 15–20% below the purchase price to avoid total losses in the event of bad news.
12. Long-Term Viability
Everything hinges on the factory’s “Site Acceptance Testing” by the end of August 2026 and the subsequent production ramp-up in the third quarter.
The company must convert the non-binding letters of intent into binding purchase agreements. If it fails to do so, it risks running out of money.
13. Potential Alternatives
Those who aren’t interested in micro-cap risk and dilution should turn to industry giants such as Tesla or Generac.
While these don’t offer the potential for a 300% price target in just a few months, they aren’t burning through cash at that rate in their operations.
14. Profit Margin Report
Currently unavailable. Although the gross margin climbed to approximately 36% in Q3 (adjusted), the bottom line for Q3 was a steep net loss of -3.0 million USD (EPS of -0.08 USD, which missed expectations by a wide margin).
According to analysts, profits are not expected to materialize until FY28 (with an estimated EPS of +$0.70 at that time).
15. RaketenToni’s Conclusion & Risk Disclosure
NeoVolta is an asymmetric bet on the expansion of U.S. infrastructure and the FEOC tax credits. The company raised an additional $25 million in May through a new share issuance (dilution!), giving it some breathing room in the short term.
Caution: This is not solid buy-and-hold investment for our Cibus faction!
$NEOV (+0%) It’s a bet for the bold among us.
If the deals get signed, this stock will skyrocket.
If the factory stumbles, the lights go out. Strict position sizing and stop-loss orders are mandatory!
Greetings from Denmark
Yours, Raketentoni
and, of course, everyone else :)


