Futu Holdings ADR
Price
Discussion sur FUTU
Postes
10
Update: +14% in one week - bottom found ???
A short update on my investment in $FUTU (-4,28 %) Holdings last week. 📈
I placed the order at € 116.00 and we are currently at € 132.00. That's a whopping increase of almost 14% in just a few days. Maybe I hit the local low?
Why am I so optimistic for 2026?
The fundamental data is extremely strong:
Profit machine: in the last quarterly report (March 2026), net profit rose by an impressive 80% year-on-year.
Japan hype: The expansion is bearing fruit. In Japan, customer assets have tripled within a year and the 2 million download mark has been broken. 🇯🇵
Technology lead: Futu is investing heavily in AI-supported analysis tools and the expansion of crypto trading.
This makes the "Moomoo" app an absolute standard tool, especially for the younger generation.
With a gross margin of over 88%, Futu is one of the most profitable brokers in the world. As long as the international growth (Malaysia, Canada, Australia) continues at this rate, I see significantly more potential for 2026.
Out of energy, into digital growth in China
Bye bye Valero Energy, the run was great, but I bagged the profits with 140% last week. The capital went straight into $META (-3,46 %) and $FUTU (-4,28 %) flowed directly into 🚀
For those who don't know the value: Futu Holdings is a leading online broker from the Tencent ecosystem that is currently undergoing massive global expansion. The app user numbers are growing impressively and I find the business model as an "all-in-one" financial platform for the younger generation extremely exciting.
Here's to a good hand! 🍀


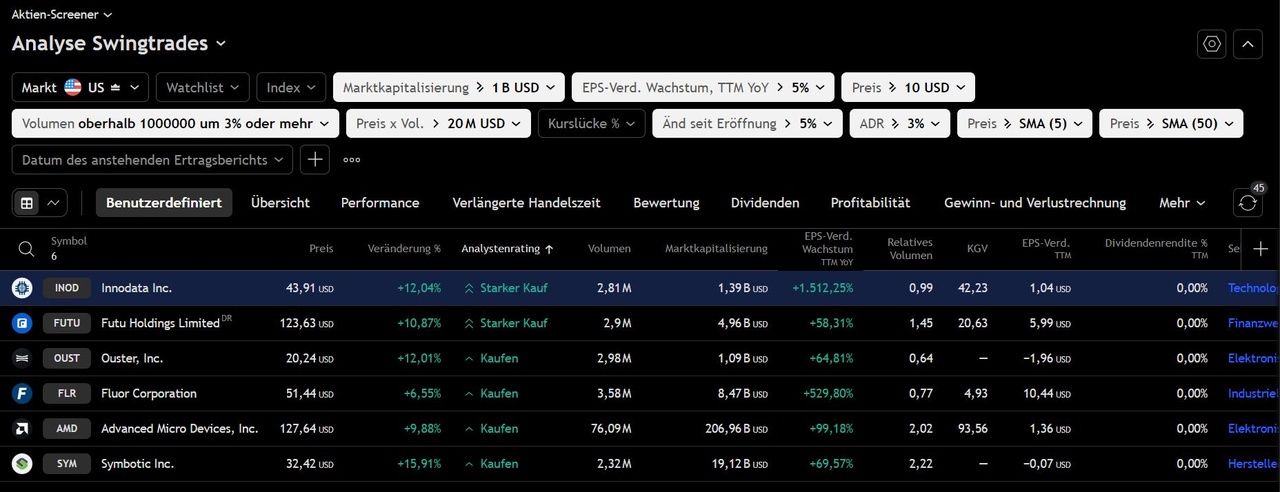
Trading today - Screener results
$INOD (-6,6 %)
https://www.tradingview.com/x/JRtOq7mU/
$FUTU (-4,28 %)
https://www.tradingview.com/x/FK6cnkiF/
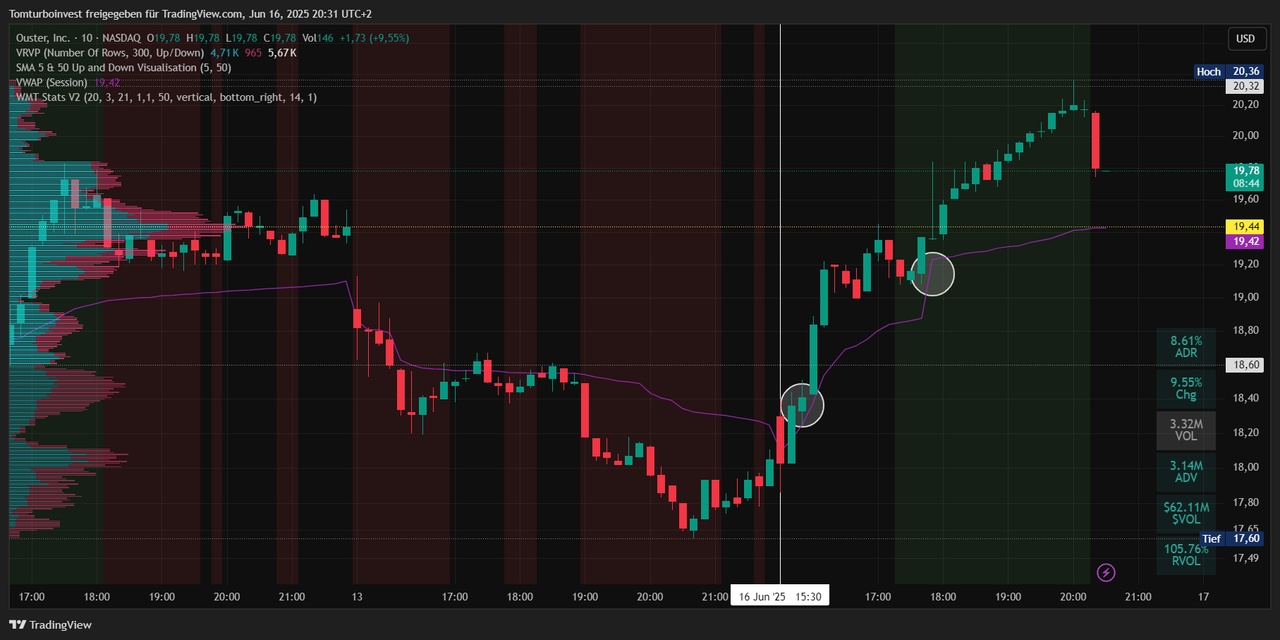
$OUST
https://www.tradingview.com/x/E2g8XCaV/
$FLR (-1,65 %)
https://www.tradingview.com/x/mz4FKsAX/
$AMD (-5,46 %)
https://www.tradingview.com/x/pW1E7zgH/
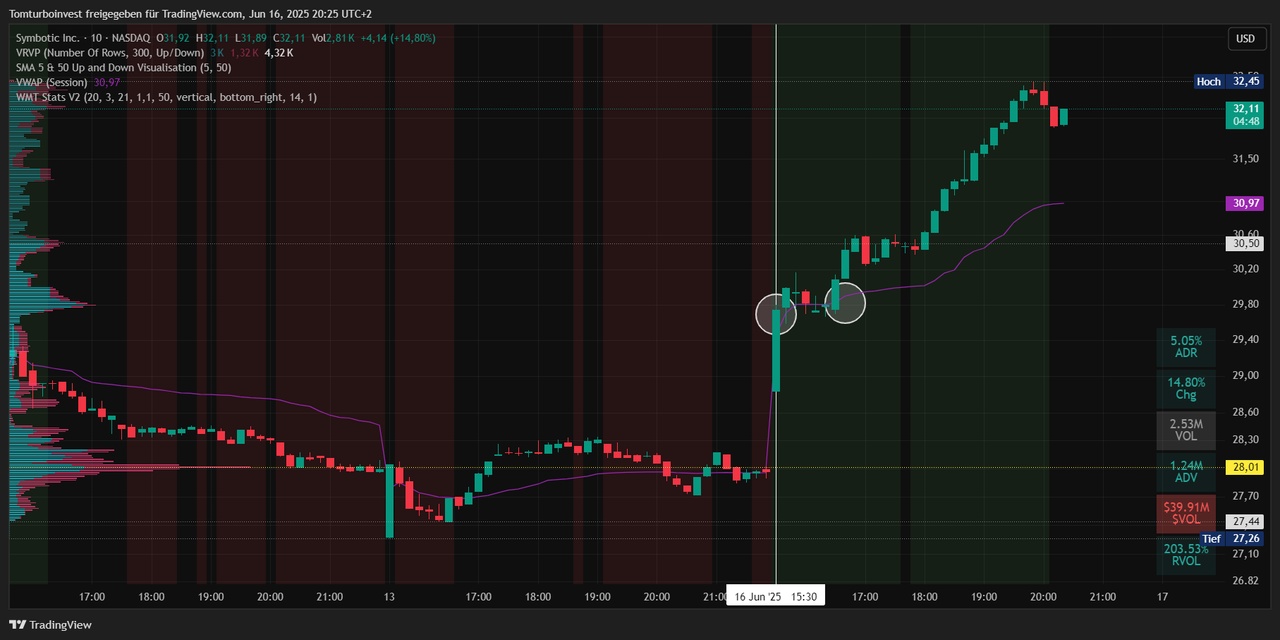
$SYM (-3,52 %)
https://www.tradingview.com/x/RkUvCPtq/
Entries and exits according to the VWAP of the session. As always for those interested in trading - otherwise keep scrolling 😅
Ex. $SYM (-3,52 %) I only enter when the price is at the VWAP (purple), either I catch the momentum at the start of trading, or I wait for the consolidation, which should be at least 30 minutes, and then enter if the structure is appropriate.
Example. $OUST

Futu Q3 2024 $FUTU (-4,28 %)
Financial performance
Futu Holdings Limited recorded solid growth in the quarter, with the following highlights:
Total revenue: an increase of 29.6% year-on-year to HK$3,436.1 million (US$442.3 million).
Net profit: An increase of 20.9% year-on-year to HK$1,319.2 million (US$169.8 million).
Adjusted non-GAAP net profit: An increase of 20.8% to HK$1,398.4 million (US$180.0 million).
Balance sheet summary
As of September 30, 2024, Futu Holdings reported:
Total assets: HK$143,462.0 million.
Total liabilities: HK$115,043.8 million.
Shareholders' equity: HK$28,418.2 million.
Details of the profit and loss account
Revenue from brokerage commissions and handling fees: HK$1,528.9 million, an increase of 51.5% compared to the third quarter of 2023
Interest income: HK$1,698.8 million, a year-on-year growth of 12.9%.
Total costs: HK$624.9 million, an increase of 42.9% compared to the third quarter of 2023
Key figures and profitability metrics
Gross margin: 81.8%, compared to 83.5% in the third quarter of 2023.
Operating margin: Increased to 50.4% from 49.8% in the previous year.
Net profit margin: Down to 38.4% from 41.2% in the same quarter of the previous year.
Segment information
Total trading volume: HK$1.90 trillion, an increase of 74.7% year-on-year.
Asset management (asset balance): HK$97.3 billion, an increase of 87.5% year-on-year.
Competitive position
Futu expanded its client base by 33.1% year-on-year.
Strong growth in established markets such as Hong Kong and Singapore; Malaysia is one of the main drivers for new paying customers.
Management forecasts and comments
Management expects growth in paying customers for the full year to exceed the forecast of 550,000, supported by momentum in established markets and momentum in new regions.
Risks and opportunities
Opportunities: Further expansion into international markets and introduction of new products such as US options and money market funds.
Risks: Unrealized foreign currency losses due to the appreciation of the renminbi.
Summary of results
Positive aspects:
1. significant increase in total revenue and net profit compared to the previous year.
2. strong growth in trading volume and assets under management.
3. expansion of the client base, particularly in international markets.
4. improvement in the operating margin.
5. announcement of a special dividend, signaling a strong liquidity position.
Negative aspects:
1. decline in net profit margin due to foreign currency losses.
2. increase in total costs, which negatively impacts the gross margin.
3. higher interest expenses due to securities lending and borrowing.
4. decline in the average commission rate.
rate.
5. weak performance of Japanese equities, which impairs customer acquisition.

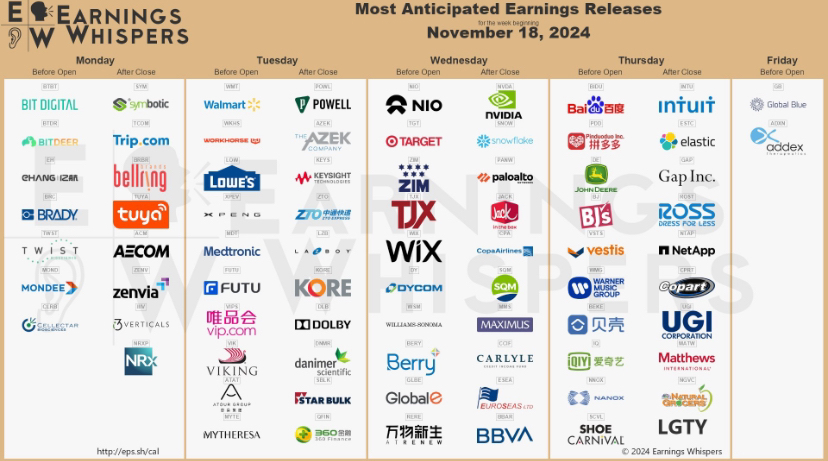
$FUTU (-4,28 %) Futu Holdings Limited reported earnings
Q3 FY2024 results ended September 30th 2024
- Revenue: $442.3M, +29.6% YoY
- Net income: $169.8M, +20.9% YoY
- EPS per ADS: $1.21 vs $1.01 in Q3 2023
- Total paying clients: 2.20M, +33.1% YoY
CEO Leaf Hua Li: "We acquired 154 thousand paying clients in the third quarter, up 138.0% year-over-year and flattish quarter-over-quarter. In the first nine months of the year, we acquired 487 thousand paying clients and we expect full year growth to comfortably exceed our guidance of 550 thousand, thanks to resilient growth in established markets and strong momentum in newer ones."
Revenue Breakdown:
- Brokerage commission: $196.8M, +51.5% YoY
- Interest income: $218.7M, +12.9% YoY
- Other income: $26.8M, +52.1% YoY
Other Metrics:
- Gross margin: 81.8% vs 83.5% in Q3 2023
- Operating margin: 50.4% vs 49.8% in Q3 2023
- Total client assets: $89.2B, +48.1% YoY
- Daily average client assets: $76.4B, +23.4% YoY
- Total trading volume: $244.6B, +74.7% YoY
Business highlights:
- Total registered clients reached 4.28M, +22.8% YoY
- Total users increased to 24.1M, +14.4% YoY
- Margin financing balance: $5.2B, +25.5% YoY
- Wealth management assets: $12.5B, +87.5% YoY
- IPO distribution and IR clients: 461, +17.9% YoY
- Strong growth in Hong Kong, Singapore and Malaysia markets
- Launched ETF-based robo-advisory service in Hong Kong and Singapore
Special Dividend:
- Declared special cash dividend of $2.00 per ADS
- Total dividend payment approximately $280M
- Record date: December 6, 2024
- Payment date: January 10, 2025
Forecast:
- Expected to exceed guidance of 550K new paying clients for full year
- Expanding product offerings in Malaysia with U.S. options trading and money market funds
- Continuing international market expansion

Futu Holdings- The fintech broker from China
Futu Holdings Limited is an innovative fintech company specializing in digital financial services. Founded in 2009 by Leaf Hua Li, a former Tencent employee, Futu has developed into a major player in online trading. Since its IPO on Nasdaq on March 8, 2019, the company offers a wide range of services, including trading and clearing services, asset management as well as market data and social interactions via its Futubull and moomoo platforms.
Core business and key products/services
Futu provides a comprehensive offering to its customers:
Trading services: enables trading of shares in various markets, including Hong Kong, the US and China.
Wealth management: Futu Money Plus gives customers access to over 100 investment funds.
Market data and analytics: Provides real-time market data and advanced analytical tools.
Social features: Users can interact in a community and share information and investment strategies.
Mission and vision
Futu's mission is to create a user-centric platform that revolutionizes investing through innovative technologies. The mission is to facilitate access to financial services and continuously optimize the user experience.
Historical development
Since its foundation in 2009, Futu has undergone impressive growth. The IPO in 2019 marked an important milestone and gave the company access to further resources for its expansion into international markets.
Important milestones:
2009: Foundation of Futu Holdings.
2019: IPO on the Nasdaq.
2020-2023: Expansion into markets such as the USA and Singapore and steady growth of the user base.
Strategic acquisitions and developments
Futu has established strategic partnerships with global asset managers to offer its clients a broader range of investment products, further strengthening the company's market position.
Business model & core competencies
Futu's business model is based on a powerful technological infrastructure that enables cost-effective and comprehensive services. The company's key strengths are
Technological innovation: Proprietary platforms for trading.
Ease of use: Intuitive operation and comprehensive support.
Customer centricity: High customer loyalty through personalized offers.
Competitive advantages
Lower trading fees compared to traditional brokers.
Strong technological platform that enables real-time data and analysis.
High customer loyalty, as over 80% of users are regularly active.
Future prospects & strategic initiatives
Futu plans to continue expanding into new markets and investing in innovative technologies to improve the quality of its services.
Growth initiatives:
Expansion of the offering in the areas of wealth management and social interactions.
International expansion, particularly in North America.
Futu is also investing more heavily in artificial intelligence and data analytics to develop personalized services and further improve the user experience.
Market position & competition
Futu is now one of the leading digital brokers in Asia and is actively expanding into North America.
Its main competitors in the USA include:
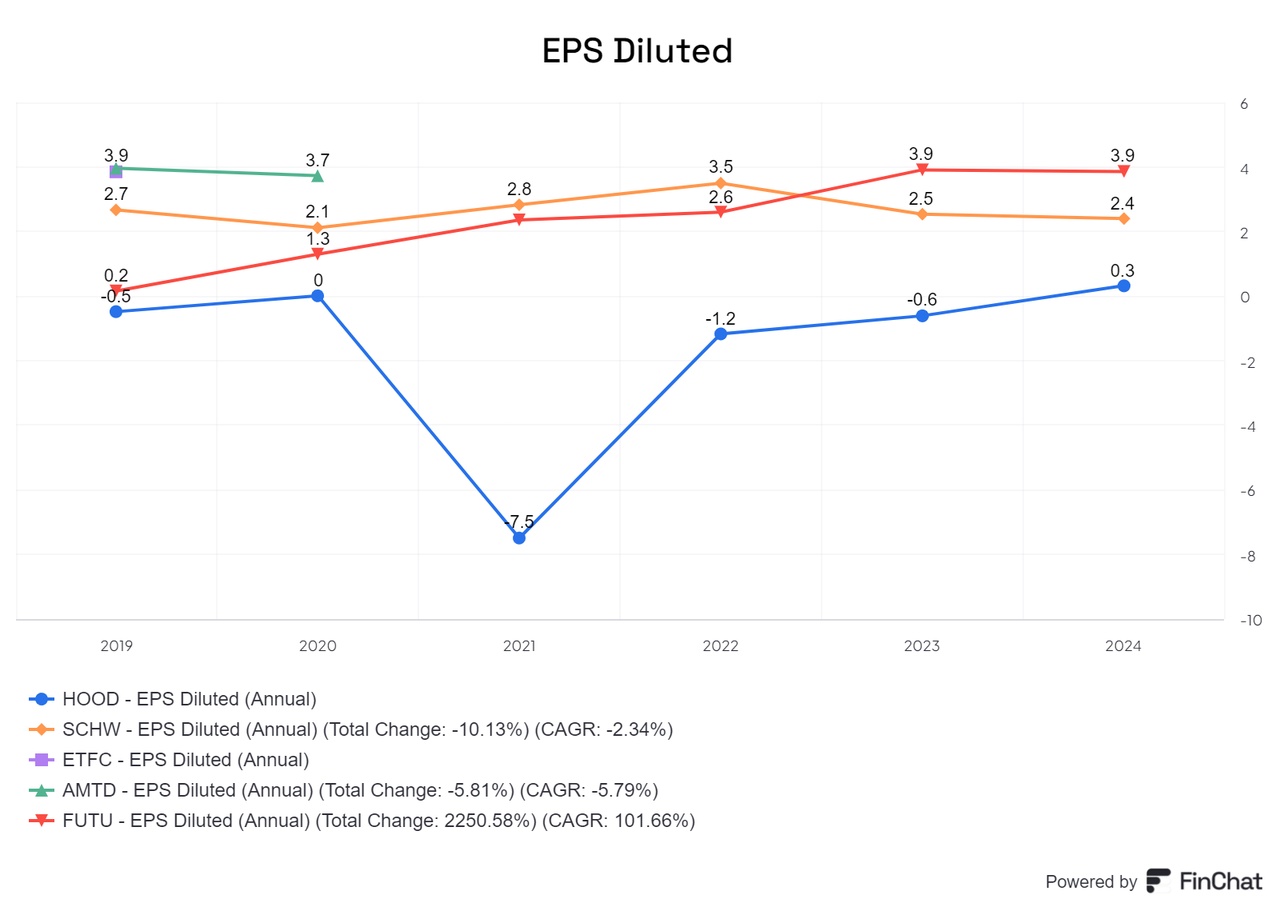
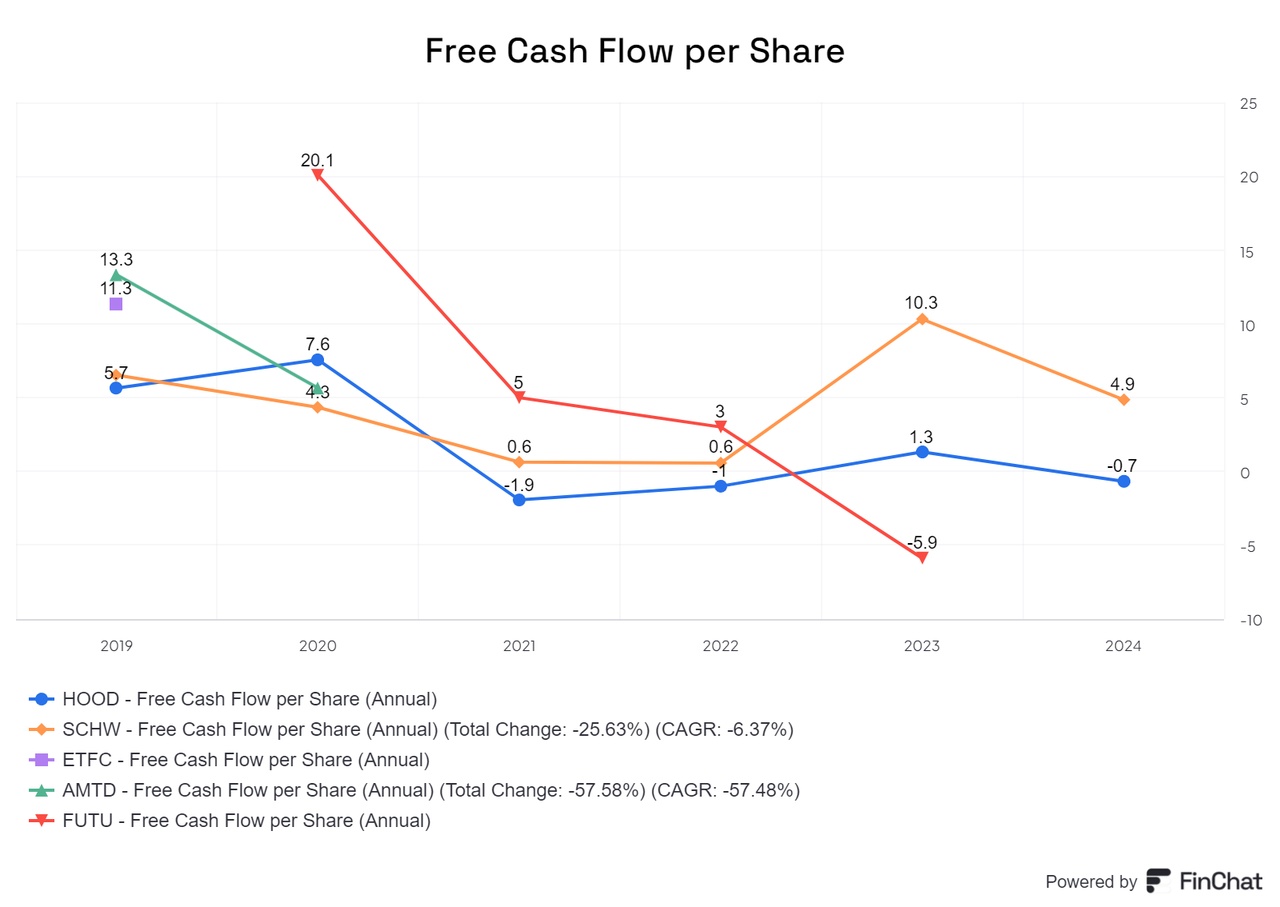
Robinhood
Charles Schwab
Total Addressable Market (TAM)
The global online retail market is estimated at around USD 9.5 billion, with an annual growth rate of 5.3% until 2030. Futu has the potential to gain a significant share of this market, particularly due to the growing demand for digital financial services.
Share performance
Since the IPO, the share has a TR of 533% in the last 3 years it was 67%, mainly due to the increase from last year with 57%
Share distribution
Investor
Date
% Owned
Market Value
Hua Li
2023-12-31
36.59986%
$2.6B
Tencent Holdings Limited
2023-12-31
22.42365%
$1.59B
Aspex Master Fund
2024-08-06
3.41907%
$242.81M
Aspex Management (HK) Limited
2024-08-06
3.41907%
$242.81M
Morgan Stanley, Investment Banking
2024-06-30
2.46291%
$174.91M
For the development (company figures), better view and more check out the free blog: https://topicswithhead.beehiiv.com/p/futu-holdings-der-fintech-broker-aus-china
Conclusion
Futu Holdings is well positioned to benefit from technological innovation and expansion into new markets. Especially in regions where the population is open to new brokers, Futu is positioning itself favorably to benefit from these developments. There is a lot of potential in Asia, as the markets are often still underdeveloped, especially in terms of shareholder culture. With the huge market in China, the company has access to an enormous population. It is also looking to position itself in Singapore and the USA, although Futu will probably only play a minor role in the USA. Futu can therefore be seen as an investment in Asia and the emerging markets.
The company is very innovative and is managed by the founders, who also hold a significant stake in the company. With the support of Tencent, one can positively emphasize that they are involved in interesting markets. On the other hand, there is the challenge that the voting rights of over 50% are held by 2 owners. Futu has a lot of cash, good metrics and is still not overpriced, but unfortunately the growth figures are currently falling sharply, but as long as these can be maintained or slightly increased, this should be sufficient for a reasonable valuation.
So what's the problem: the risk discount due to China, especially Hong Kong, is noticeable and I have to be honest and say that I would put this discount even higher to invest.
Actually, I don't have any individual stocks from China as I trust the dictatorship less than our own state. Therefore, Futu would have to get back to a point where the valuation is close to cash or well below book value. This was the case until the last increase, but I had not yet looked at the share in detail at that time. Therefore, the rule for me is: for an exceptional stock, I want at least a 15-20% additional China risk discount (normally 25%, which would mean the valuation at around 10 billion( before the rise), corresponding to 60 to 70 euros for the ADR share.
Then I would take another look at the figures and invest if the trend holds.


+ EV / Sales (5.71)
+ Gross margin TTM (93.81%)
+ Debt ratio (0.22)
+ EBIT margin LJ. (59,13%)
+ Equity ratio LY. (25,30%)
+ Profit growth (27.24%) ✌🏻
"Robinhood Inc: savior of small investors or master of the silent raid?"
An introduction to the neo broker and a look at some figures.
Company presentation
Robinhood Markets, Inc. is a financial services company based in Menlo Park, California, founded in 2013 by Vladimir Tenev and Baiju Bhatt. It has made a name for itself primarily through its innovative, commission-free trading platform that democratizes access to stocks, ETFs, options and cryptocurrencies.
Historical development
With the vision of democratizing financial trading and making it accessible to everyone, Robin Hood got off to a rapid start. Within the first year, the company had already gained almost one million users and processed transactions worth over one billion US dollars. Since then, Robin Hood has developed into one of the defining players in the field of neo-brokerage, which continues to grow and set new standards.
Business model
Robinhood operates as an online broker and relies on a diversified business model. The main sources of revenue include:
- Order flow payments: Robinhood receives compensation from market makers for routing trade orders.
- Interest income on client balances: The company earns additional revenue through interest on deposits or credit card usage
- Premium subscription (Robinhood Gold): For a monthly fee, customers gain access to enhanced features and exclusive benefits.
Core competencies
At the heart of Robin Hood's business strategy is the provision of a user-friendly platform for trading financial instruments. This includes:
- Commission-free trading: users can trade stocks, ETFs, options and cryptocurrencies without transaction costs.
- Intuitive user interfaces: Both the mobile app and the web platform are characterized by their ease of use, which appeals to young, technology-savvy target groups in particular.
Future prospects and strategic initiatives
Robinhood is pursuing ambitious plans to further expand its offering and compete with established brokers. These include the trading of index options and futures, which are now available and will be expanded, as well as the expansion and extension of international markets.
Current performance of the Robinhood share
Over the year, Robinhood's shares have gained an impressive 98%, an increase that can be attributed to key internal company decisions. While shareholders who joined the company a year ago can be pleased with this development, the situation looks much bleaker for those who have been invested for three years. Even if you used a good cash tap at the time of the IPO, the share is still down 55% since August 26, 2021.
Development of the figures and future challenges
(Image 4&7)
Robinhood has recently been able to increase both its turnover and gross profit, and the company has even reported a positive net profit since the fourth quarter of December. Projects within the company are also progressing rapidly and the once negative reputation seems to be gradually improving. On the surface, therefore, everything seems to be going in the right direction - the company has achieved a turnaround and appears to be living up to increased expectations. However, caution is required, particularly with regard to two key factors: interest rate dependency and customer behavior.
Point 1: Sustainability of customer acquisition
One crucial aspect that causes concern is the issue of sustainability. Many Robinhood users are characterized by a high willingness to take risks, which often leads to losses. Given that the average account balance is currently around USD 4,000, this is an alarming sign, as the customer base is young and instead of saving capital for the long term, it is often gambled away. Previous measures to stop this trend have had little success, and initiatives such as the 401k plan have so far found little favor. Robinhood therefore remains highly dependent on the disincentives that lead to speculative behavior. If it is assumed that sustainable revenue can only be achieved by eliminating 25% of options trading and 50% of crypto trading, the company would quickly lose $151.25 million in revenue and find itself in a precarious position. So the question remains: can the business model be sustainable in the long term if it fails to fundamentally change its customer strategy?
(Image 9)
Point 2: Dependence on interest rates
Another potential problem is the heavy reliance on interest income, which accounts for 47% of total revenue - and not just this quarter, but for some time now. Even if part of this interest is of an operational nature and does not come solely from deposits or investments, it must be questioned whether Robinhood's approach as a broker can be successful in the long term. The situation is much more sustainable for established competitors. Without the interest income, Robinhood would clearly be in the red, which is problematic for a company of this size and structure. If interest rates were to halve, this would equate to a loss of revenue of USD 120.5 million.
(Image 5)
Conclusion
$HOOD (-4,18 %) has undoubtedly made progress, repositioned itself strategically and improved its position. However, major challenges remain that cannot be solved overnight. The customer base consists mainly of risk-taking speculators rather than long-term investors. In addition, the company lacks the necessary size and stability to survive major challenges without slipping back into the red. Of course, my assumptions are extreme - there is no immediate reason why 50% of crypto sales should suddenly collapse - but they illustrate that Robinhood has not yet been a reliable investment and has still not proven that it can be one in the long term. The risk remains high and it will take some time and further positive developments to overcome the existing problems. For me, Robinhood therefore remains a candidate for the watchlist to keep an eye on. It should not be forgotten that more and more competition will enter the market and the comparison with other brokers who are already delivering reliable figures and whose growth story is far from over.
(rest of the pictures)
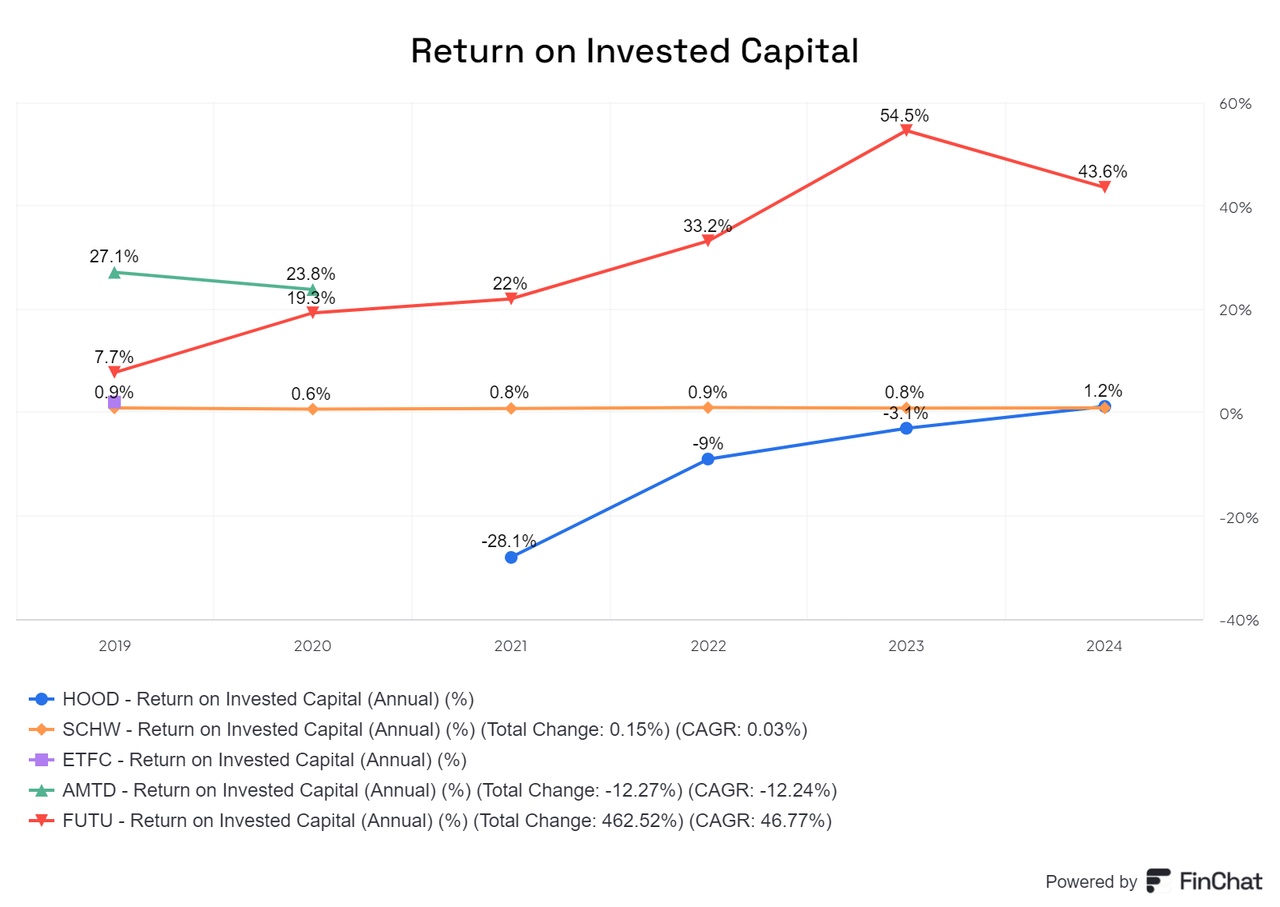
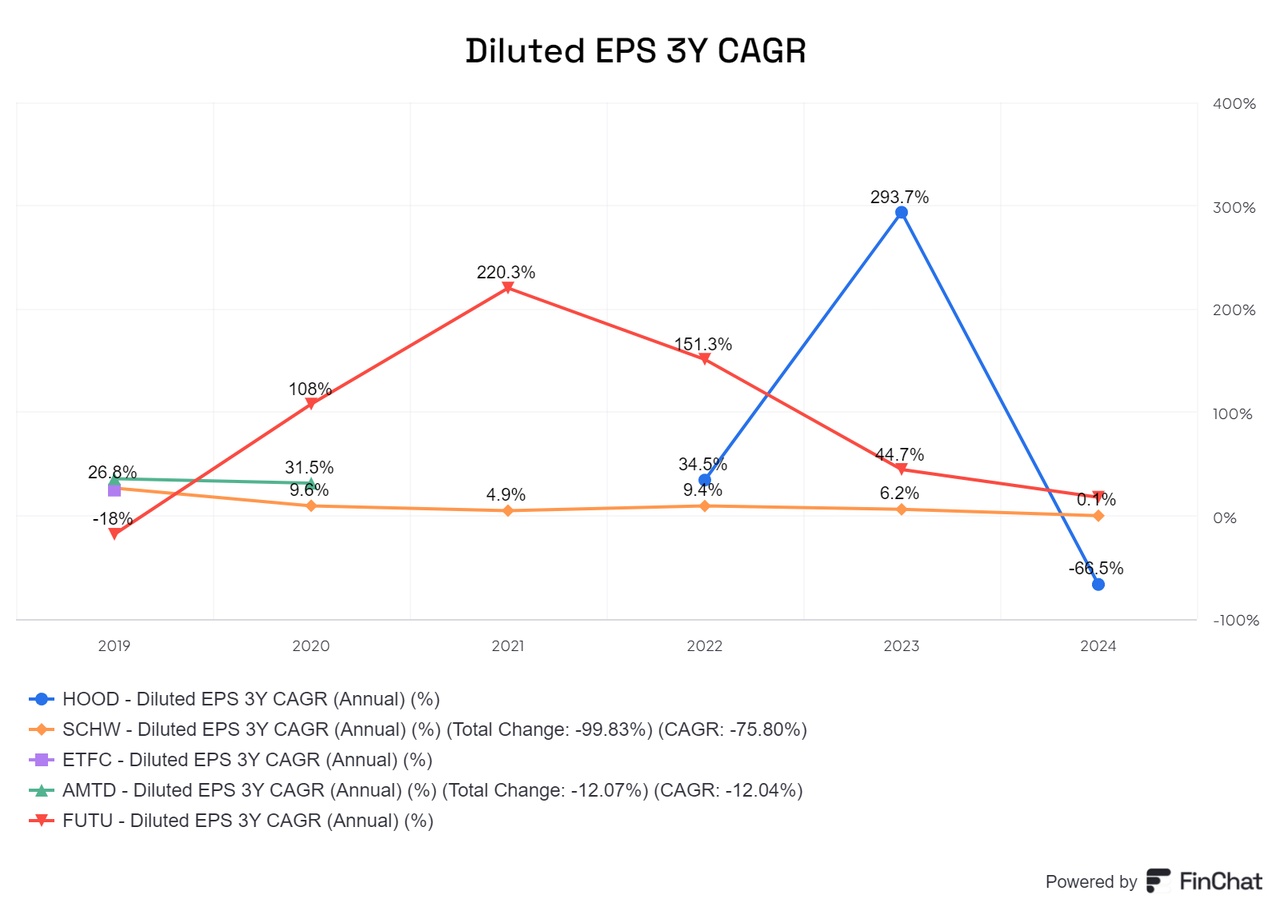
+ 5

All my posts broken down by single share, comparisons, theory and opinions.
Newsletter & Blog
https://topicswithhead.beehiiv.com/
Structure
- Individual shares:
$NVDA (-1,52 %)
: The brain behind the AI cycle https://getqu.in/R8kJvx/
$CRWD (-6,72 %)
: The falcon that can no longer fly? https://getqu.in/xAZJbb/
$D05 (+0,21 %)
: The best bank in the world? https://getqu.in/Mv6fLf/
$HOOD (-4,18 %)
: Savior of small investors or master of the silent raid?"
The venture play of the $XTP (-0,4 %)
. Participation in the self-proclaimed "European Charles Schwab". https://getqu.in/T5Fc49/
$ORI (+2,41 %)
The share for opis? https://getqu.in/HKAf7p/
$SNOW (-8,37 %)
Is the ❄️ melting away or growing into an iceberg https://getqu.in/FundGB/
$ASML (-1,11 %)
: The best technology company in Europe- The brains behind every smart chip https://getqu.in/JWXYkC/
$DDOG (-7,38 %)
The pit bull of data analysis https://getqu.in/YpHawB/
$AFX (-0,24 %)
: The share that catches the eye 🔍 https://getqu.in/oDGSmr/
🚜$DE (-1,84 %)
: From king of the field to prince of construction? https://getqu.in/27HkzI/
$CDR (-0,64 %)
: Of sorcerers and cyberpunks - the masters of the digital worlds 🏙️ https://getqu.in/dYjIcI/
🏎 $FWONK
: Pole position in the business of high-speed spectacle 🏁https://getqu.in/lY15B7/
💶$AMUN (+0,14 %)
: Europe's financial architect - Is he building the most solid fortunes? 🏗️ https://getqu.in/Erlpxb/
$IVSA
AB: A Swedish investment powerhouse with vision https://getqu.in/kI1lgD/
📊$MSCI (-1,21 %)
: More than just indices - the secret data king of the financial markets 👑 https://getqu.in/8IdYUC/
Man and machine $MUM (+0,43 %)
https://getqu.in/yk2ee7/
Genmab A/S $GMAB (-1,66 %)
https://getqu.in/eJDAxs/
Prosus NV- The Tencent Play $PRX (-0,3 %)
https://getqu.in/E8PMgz/
Futu Holdings- The Fintech Broker from China $FUTU (-4,28 %)
https://getqu.in/2CfdRy/
- Compare
⚡ Gas giants of the future: Who will lead the energy race? 🏁
✨ Who is the beauty king? A look at the stars of the cosmetics stocks ✨ https://getqu.in/C9QiOo/
🌐 Stock market battle: Deutsche Börse, ICE, Euronext, NASDAQ - who dominates trading? 📊 https://getqu.in/7mcYEJ/
⚙️ Giants of industry: Siemens, Schneider Electric, GE & ABB in a power comparison 💪https://getqu.in/iL6sJ3/
✈️ Aviation titans compared: Airbus, Boeing, Embraer - who will take off? 🚀https://getqu.in/Xfmo8G/
🍽️ Giants at the dinner table: Nestlé, Unilever & Co. - Who serves up the biggest success?
Haute Finance: LVMH,Richemont ,Kering and Hermès - The stock market défilé of the luxury giants https://getqu.in/HmleWd/
Celsius Holdings vs Monster Beverage. Who is the better buy for the future? https://getqu.in/mQIVSZ/
Number crunchers of the financial world: Moody's vs. S&P in a data duel https://getqu.in/s5l7qm/
💳 The card game of the giants: Visa, Amex, Mastercard - who will win the payment poker? 🃏https://getqu.in/Qb7UAo/
⛏️ Titans of the deep: Rio, Glencore, BHP, Vale - Who will dig up the biggest profit? 💎
Hardware of data: Arista, Cisco, Juniper and HPE in the infrastructure race https://getqu.in/dHfciF/
- Theory
Money today or tomorrow?
Annuity
Bond valuation
Stock valuation
Market efficiency
Portfolio theories
- Opinion
Why domestic ETF providers are worth considering
Diabetes injection. Miracle cure or economic injection? https://getqu.in/xc3C7R/

Titres populaires
Meilleurs créateurs cette semaine