
So far, the statement has had little impact on the stock price
DEUTZ
Stock
Stock
ISIN: DE0006305006
Ticker: DEZ
DE0006305006
DEZ
Price
Debate sobre DEZ
Puestos
5620H·
Deutz Responds to Short-Seller Report

www.deutz.comDEUTZ nimmt Stellung zu Shortseller-Bericht und weist zentrale Schlussfolgerungen als unbegründet zurück
44
2D·
Short Seller Report
$DEZ (-2,29 %) FRANKFURT (dpa-AFX Broker) - Following a negative report by a short seller, Deutz shares came under heavy pressure on Wednesday. Most recently, the stock had plummeted by
more than 15 percent. The engine manufacturer’s shares fell to their lowest level since November
2025.
The research firm Ningi Research published a critical article regarding the acquired defense company FFG. The article alleges that, in connection with the subsidiary FFG Industries GmbH, there is an unfavorable distribution of profits from the FFG deal for Deutz. Deutz had announced the acquisition of Flensburger Fahrzeugbau Gesellschaft mbH (FFG) in July and completed the transaction in early November. A company spokesperson initially declined to comment. “We’re looking into it right now,”
source: Goldesel.de
33
7 Comentarios
He-Man D.@He-Man
2D
••
Ver todas las 6 respuestas adicionales
1Semana·
DEUTZ Stock Forecast & Price Targets for 2026: A Bet on the Defense Sector or a Dilution Trap?
Summary
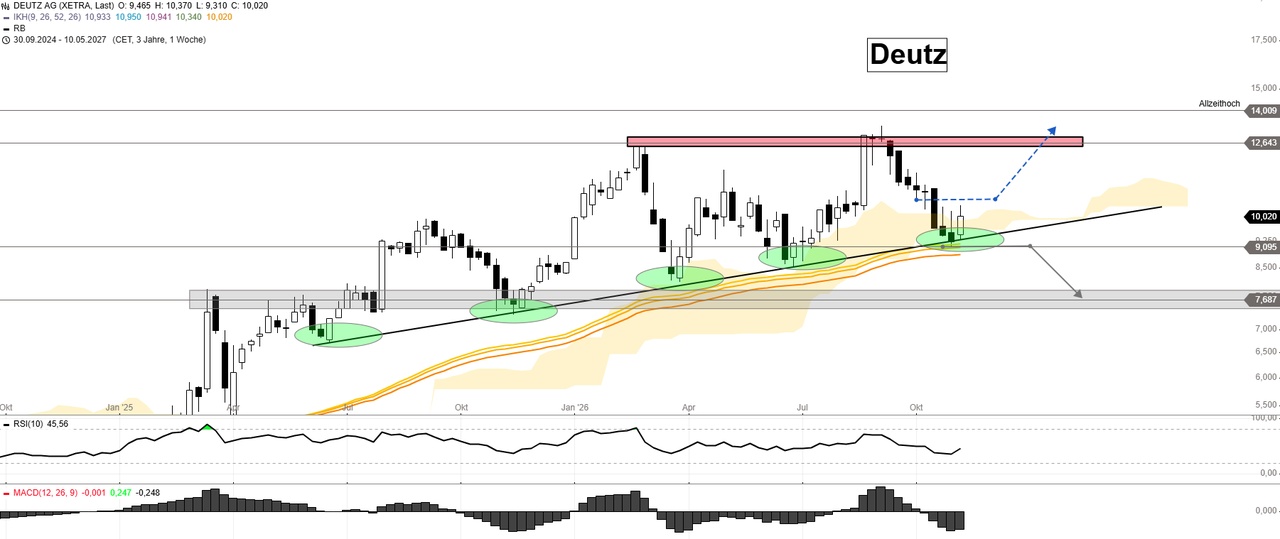
Deutz shares closed at EUR 10.02 (Xetra) on November 10, 2026, which is about 25% below their 52-week high of EUR 13.35 set in September. In the third quarter, revenue rose 12.3% to EUR 553.9 million, order intake jumped 34.2% to EUR 631.2 million, and adjusted EBIT reached EUR 38.5 million with a margin of 7.0%. Nevertheless, the stock fell following the November 5, 2026, earnings report, as two capital measures and the record-breaking acquisition of specialty vehicle manufacturer FFG are fundamentally transforming the company: Deutz is transforming from an engine manufacturer into a defense and energy conglomerate, but is paying for this with new shares and increased debt. The average price target from the five analyst firms covered is EUR 15.28, with the range extending from EUR 12.40 to EUR 18.00. From a technical analysis perspective, everything hinges on the trend line at EUR 9.09. The fair value according to Aktienfinder is EUR 12.57, which is about 25% above the current price.
Key Points
- Q3 2026: Revenue EUR 553.9 million (+12.3%), order intake EUR 631.2 million (+34.2%), adjusted EBIT EUR 38.5 million (margin 7.0%)
- 9M 2026: Revenue of EUR 1,669.2 million, adjusted EBIT of EUR 118.2 million (+36.0%), margin of 7.1% compared to 5.8% in the prior year
- 2026 Forecast: Revenue of EUR 2.3 to 2.5 billion, adjusted EBIT margin at the upper end of the 6.5 to 8.0% range
- Capital Measures: Cash capital increase on September 15, 2026 (15.26 million shares at EUR 11.70, approximately EUR 179 million) and a non-cash capital increase for FFG in early November 2026
- Valuation: Fair value according to Aktienfinder is EUR 12.57 (+25%), 52-week range is EUR 7.33 to EUR 13.35
What are the current key figures for the Deutz stock?
- Price (Xetra): 10.02 EUR (+1.6%), closing price as of Nov. 10, 2026
- 52-week high: 13.35 EUR (intraday), 52-week low: 7.33 EUR
- Average price target (5 firms): 15.28 EUR (+52%)
- Fair value (Aktienfinder): 12.57 EUR (+25%)
- Q3 Revenue: 553.9 million EUR (+12.3%), Q3 Order Intake: 631.2 million EUR (+34.2%)
- Q3 net income: just under 7 million EUR (−44%)
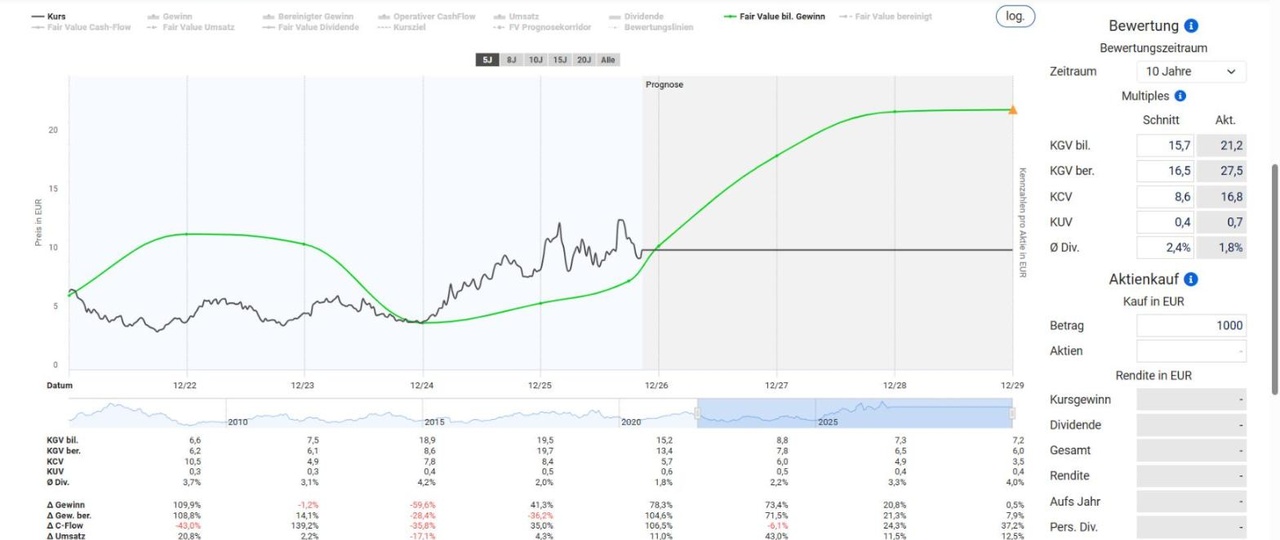
- P/E ratio (Aktienfinder, reported / adjusted): 21.2 / 27.5 (average 15.7 / 16.5)
- Dividend: 0.18 EUR for 2025 (yield approx. 1.8%)
- Next Earnings Release: 2026 Annual Results on March 30, 2027, according to the financial calendar
What news is currently driving the Deutz stock?
Three topics are primarily driving Deutz stock: the quarterly results from November 5, 2026, the subsequent analyst reports, and the capital measures related to the FFG acquisition. On September 15, 2026, Deutz issued 15,263,810 new shares at EUR 11.70 each through a cash capital increase, raising approximately EUR 179 million gross. Separately, in early November 2026, there was a capital increase in kind for the FFG acquisition: The owners of the Flensburg-based vehicle manufacturer will receive new Deutz shares and become anchor shareholders with a stake of up to 29.9%. The market reaction to the figures was mixed: On November 5, 2026, the stock jumped to EUR 10.18 but closed at EUR 9.50; on November 6, 2026, the closing price was EUR 9.25.
- November 9, 2026: Deutsche Bank initiates coverage with a “Buy” rating and a price target of EUR 14.50, viewing Deutz as a defensive stock that is undervalued as an engine manufacturer.
- November 6, 2026: Warburg Research (MPCM) lowered its target from 19.00 to 18.00 EUR (Buy); Berenberg reaffirmed its Buy rating with a target of 16.50 EUR.
- November 5, 2026: Q3 results show a 34% increase in order intake; net income for the period fell by 44% to just under EUR 7 million.
- November 5, 2026: DZ Bank maintains its “Buy” rating but lowers the fair value from 16.00 to 15.00 EUR.
- November 5, 2026: According to the Börsen-Zeitung, up to 300 additional jobs in the engine business are expected to be cut over the next two years.
- Early November 2026: FFG acquisition completed; purchase price approximately 1.6 billion EUR.
- September 24, 2026: Memorandum of understanding signed with Hypercraft regarding unmanned ground vehicles.
The catch: Although order intake rose by 34% in the quarter, the revenue forecast was not raised. The market is currently paying high premiums for defense-related speculation, as a look at my analysis Rheinmetall Aktie shows.
What does Deutz do, and how does the company make its money?
Deutz builds engines and powertrain systems, but has long since been generating revenue from services, power generation, and defense as well. In the first half of 2026, the Engines division generated the highest revenue at 642.4 million EUR, but posted an adjusted EBIT margin of only 3.8%. The Service division posted revenue of EUR 298.2 million and a 17.2% margin; Energy reported EUR 116.5 million in revenue with a 10.6% margin; and Defense & Other recorded EUR 52.1 million in revenue with a 10.0% margin. NewTech generated only EUR 6.1 million in revenue and posted a loss of EUR 13.5 million in adjusted EBIT. With FFG, Deutz is making the largest acquisition in the company’s history for approximately EUR 1.6 billion; FFG had revenue of around EUR 760 million in 2025. Anyone who wants to understand how a powertrain specialist makes money on military vehicles will find the RENK Aktie the closest comparison.
Fundamental Analysis: How is the Deutz stock valued following the FFG restructuring?
The Aktienfinder comparison shows a balance-sheet P/E ratio of 21.2 versus an average of 15.7; for the adjusted P/E ratio, the figures are 27.5 versus 16.5. The figures have not yet been adjusted for the full value of the FFG shares. According to the Aktienfinder chart, the fair value is EUR 12.57, which is about 25% above the current price of EUR 10.02.
- Margins: Adjusted EBIT rose by 36.0% to EUR 118.2 million over nine months, with the margin increasing from 5.8% to 7.1%.
- Debt: The net financial position as of June 30, 2026, was −520.5 million EUR, prior to the completion of the FFG transaction. According to management, approximately EUR 1 billion in secured debt and approximately EUR 600 million in shares are earmarked for financing. The debt level following completion has not yet been disclosed.
- Cash Flow: Free cash flow before acquisitions was negative at −29.7 million EUR in the first half of the year; for the full year, Deutz is projecting a high double-digit million amount.
- Segments: The Service and Energy segments (target: over 300 million EUR in revenue by 2026) are intended to reduce dependence on the cyclical engine business. My analysis of Siemens Energy Aktie.
- Outlook: For 2027, Deutz expects FFG to generate more than EUR 1 billion in additional revenue with an adjusted EBITDA margin of over 20%; in the medium term, it anticipates EUR 4 billion in revenue and a 10% margin by 2030.
Deutz Stock Price Targets and Forecast for 2026
Analysts see an average price target of around 15.28 EUR for Deutz stock, but from a technical analysis perspective, the trend line at 9.09 EUR is the first key level. Defense-related speculation is driving many stocks in the sector, as my analysis on Hensoldt Aktie , but at Deutz, dilution and debt are holding the stock back.
Key Price Levels
- 52-week high: 13.35 EUR (intraday), 52-week low: 7.33 EUR
- Current price: 10.02 EUR (Xetra close on Nov. 10, 2026)
- First resistance level: 12.64 EUR (recent highs)
- Second resistance level: All-time high according to the chart, just under 14 EUR
- Critical support level: 9.09 EUR (trend line; if broken sustainably, downside target 7.68 EUR)
Analyst price targets
- Average: 15.28 EUR (five firms, +52% from current price)
- Warburg Research (MPCM): Buy, 18.00 EUR (Nov. 6, 2026)
- Berenberg: Buy, 16.50 EUR (November 6, 2026)
- DZ Bank: Buy, fair value 15.00 EUR (November 5, 2026)
- Deutsche Bank: Buy, 14.50 EUR (November 9, 2026)
- Bernstein: Outperform, 12.40 EUR (October 15, 2026)
Chart Analysis
On the weekly chart, everything for the Deutz stock hinges on a single trend line. It connects the lows since spring 2025 and has been tested multiple times since then; the most recent touchpoint is right at the current price of 10.02 EUR. On November 6, 2026, the stock tested this exact zone with a daily low of 9.095 EUR and then turned back upward. Anything above 9.09 EUR is considered bullish.
The more likely scenario (blue arrow): After a brief consolidation, the price breaks out to the upside and heads toward the resistance level at 12.64 EUR. If it manages to break above this level, the all-time high of just under 14 EUR comes within reach.
The counter-scenario (gray arrow): If the price sustainably falls below the 9.09 EUR range, the trendline will be broken. In that case, a dip to at least 7.68 EUR must be anticipated, as that is where the next support zone from 2025 lies.
Indicators: The RSI stands at 45.56 in the neutral zone, while the MACD remains below the zero line. The indicators do not yet provide confirmation of an upward move; the trend line will be the deciding factor.
Conclusion: Deutz Stock—A Defense Bet or a Dilution Trap?
To me, the Deutz stock is a defense sector bet with dilution risk: The financial results point to a turnaround, but the number of shares and debt are holding it back. Above the trend line at 9.09 EUR, the outlook remains bullish; in that case, resistance at 12.64 EUR is the next target, followed by the all-time high of just under 14 EUR. If the price falls below 9.09 EUR and stays there, I expect a pullback to at least 7.68 EUR. This is my personal scenario and not a guarantee. Anyone looking for a comparison regarding powertrains and hydrogen will find it in my analysis of Nel ASA Aktie.
Opportunities
- Order intake rose by 34.2% to 631.2 million EUR in the third quarter.
- Adjusted EBIT rose by 36.0% over the first nine months, and the margin increased from 5.8% to 7.1%.
- FFG is expected to contribute more than 1 billion EUR in additional revenue in 2027 with an adjusted EBITDA margin of over 20%.
- The Service (17.2% margin) and Energy segments reduce dependence on the cyclical engine business.
- The average price target of 15.28 EUR is 52% above the current price; Deutsche Bank views Deutz as an undervalued defensive stock.
Risks
- With a purchase price of approximately EUR 1.6 billion, FFG is the largest acquisition in the company’s history; the integration may tie up costs and management attention.
- Net debt had already reached EUR 520.5 million by mid-2026, plus approximately EUR 1 billion in secured debt to finance the FFG acquisition.
- A cash capital increase and a capital increase in kind will dilute existing shareholders; FFG owners will hold up to 29.9%.
- The core Engines segment achieved a margin of only 3.8% in the first half of the year, and up to 300 additional jobs are being cut.
- Free cash flow before acquisitions was negative in the first half of the year, and net income for the period plummeted by 44% in the third quarter.
Sources
Deutz AG Investor Relations (company announcements, EQS ad hoc announcement regarding the capital increase on September 15, 2026); Reuters, AWP/cash.ch, and Rental Equipment Register (figures for the third quarter and the first nine months of 2026); dpa-AFX via finanzen.net, boerse.de, and wallstreet-online (analyst reports); Börsen-Zeitung (job cuts); Deutz press releases on the half-year results and the annual shareholders’ meeting; Aktienfinder (fair value and valuation); Stock3 (weekly chart); MarketScreener (financial calendar); Xetra price data.
This is not investment advice—all information is provided solely for financial education purposes.
What are your current thoughts on $DEZ (-2,29 %) ?
44
2 Comentarios
As if on cue—will that be enough for another 20–40% upside potential?
•
11
•
2Lun·
Annual Shareholders' Meeting Votes in Favor of the Acquisition of FFG
www.deutz.comAußerordentliche Hauptversammlung stimmt Milliarden-Transaktion nahezu einstimmig zu: DEUTZ wird durch Erwerb von FFG zu einem zentralen Akteur im Verteidigungsbereich
1515
3Lun·
Antitrust Authority Approves Merger with FFG
$DEZ (-2,29 %) Today, the Federal Cartel Office approved the merger with FFG. Now all that remains is for the shareholders to make their decision.
11

4Lun·
Deutz Plans Capital Transaction
What do you think?
Deutz Acquires FFG for 1.6 Billion Euros, Accelerates Defense Push
- Deutz expects the deal to help it achieve its 2030 goals one to two years earlier
- Following the closing, FFG’s owner families will hold up to 29.9% of Deutz
- The transaction is expected to close by 2027 at the latest
July 9 (Reuters) - German engine manufacturer Deutz $DEZ (-2,29 %) said on Thursday that it had agreed to acquire military vehicle manufacturer FFG Flensburger Fahrzeugbau Gesellschaft for 1.6 billion euros (1.83 billion dollars), deepening its push into the defense sector as European military spending rises.
The company said the transaction is expected to bring its 2030 strategic goals—4 billion euros in revenue and a 10% margin on earnings before interest and taxes—within reach ahead of schedule.
The following was also reported on TR:
Deutz plans to increase its share capital by up to 183,336,437.76 euros to finance the purchase of 100 percent of FFG.
- Up to 71,615,796 new shares will be issued at 2.56 euros per share, with up to 9,802,416 FFG shares contributed in kind.
- Shareholders’ subscription rights are to be fully waived; the sellers would retain up to approximately 29.9 percent of the shares.
- In addition, a cash component totaling 1,029,677,852 euros is planned for the remaining FFG shares; this amount decreases if the share component is higher.
- Vote at the extraordinary general meeting on August 24, 2026; recommendation: approve.
I’m wondering why the company is issuing new shares at such a massive discount?
I’d appreciate an explanation.
33
9 Comentarios
4Lun
2.56 euros is certainly the par value of all shares (it used to be 5.00 DM, I'm sure).
••

4Lun·
Deutz Acquires Defense Firm FFG and Strengthens Its Defense Division
$DEZ (-2,29 %) plans to acquire Flensburg-based FFG and pay approximately €1.6 billion for it. With this move, the engine manufacturer aims to expand its defense division. The acquisition of this profitable specialist is also expected to help the company reach its 2030 revenue targets—raising them from the current €2.3–2.5 billion to over €4 billion—well ahead of schedule.

www.spiegel.deDeutz will Rüstungsfirma FFG kaufen
88
5 Comentarios

If you know Deutz, you drive a Fendt 🚜
•
44
•
6Lun·
Infrastructure shares
Transportation
Utilities
Social affairs
Digital
Future needs until 2040
Private Markets Infrastructure
Modernization
Infrastructure programs
Link: https://shorturl.at/maYS2
$IFX (-8,42 %)
$NDA (-3,37 %)
$ENR (-6,67 %)
$SIE (-5,54 %)
$DEZ (-2,29 %)
$TKA (-6,48 %)
$CBK (-1,73 %)
$NKT (-5,77 %)
$DHL (-3,32 %)
$NEM (-1,9 %)
$BZU (-3,04 %)
$DBK (-3,95 %)
$SPIE (-2,4 %)
$ELI (-0,48 %)
$GBF (-3,97 %)
44

7Lun·
Every end is also a beginning
Review March 2026
📊 Performance & markets
Monthly performance: -3,99 %
The Robo-Advisor continues to stand at an overall performance of 35,58 %.
Hot factor favorite: Nvidia
King Midas Factor: Walmart
1 Swiss franc is quoted at 1.08 Euro
₿ Crypto & alternative investments
In the crypto area, savings plans are running as usual again.
There were no new purchases or sales in Timeless.
There was no news on NFTs and music rights.
🍷 Winery
No news at all.
📈 Individual shares, ETFs & savings plans
Sale of $TPE (-7,65 %) after purchases from $OTEX (+1,38 %) and $ELMRA
Top of the month: $quant
Flop of the month: $DEZ (-2,29 %)
🚀 Crowdcube & Startups
- No news at all.
🧠 Nao
- Savings plans continue.
🌴 Review March
You can find the first part here:
https://app.getquin.com/de/post/jkGlkRTWrT/offtopic-irland-urlaub
I deliberately used the last few days of my unpaid vacation:
I invited my wife to a 5-star brunch in Switzerland (170 francs per person), met up with friends and former work colleagues and had lots of good conversations. I also read two books and had my annual routine check-up at the hospital.
The car was also due for a service for around €400.
Financially interesting: despite all these expenses, compared to other months I only spent around 25 € more compared to other months but all savings plans were reduced to a minimum. This will remain the case in April.
It was an unusual feeling not to receive a salary at the end of the month and to have to bridge the gap with savings until the 25th. At the same time, it is a good simulation for early retirement.
And: Our Bitcoin-Oli is finally back, which made me happy. @innovaclustersolution
🎧 Interest rates, podcasts & real estate
There was no news at Vivid.
The podcast is in Season 3 Episode 1 is all about financial goals.
Real estate: We continue to save for the 2026 special repayment.
🔮 Outlook for April
The working day begins again on Maundy Thursday. Savings plans remain reduced for the time being. Easter will be spent in close company and the tax return is already waiting.
I wish you all happy holidays!
And you? How was your March?
If you want to find out more, feel free to follow me.
And if you don't like my investments: The block function works wonderfully 😄
app.getquin.comOfftopic Irland Urlaub
2121
10 Comentarios
Everything has an end, only the sausage has two 👍
•
22
•
Valores en tendencia
Principales creadores de la semana
Datos LSX · Datos fundamentales y de cierre diario de FactSet